
 Africa Sodium Reduction Ingredients Market | 2026-2036
Africa Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Sodium Reduction Ingredients Market Outlook
African mineral salt processors is broadening output of potassium-based substitutes to serve reformulating food manufacturers. Cargill Incorporated leverages its regional grain and oilseed supply chains to anchor ingredient distribution across West African processing hubs. Kerry Group competes through taste modulation systems designed for local bread and snack applications. DSM NV specializes in micronutrient-enhanced salt replacers that address both sodium reduction and fortification mandates.
Africa sodium reduction ingredients comprise functional compounds—primarily potassium chloride, yeast extracts, and amino acid derivatives—that replace or mask sodium chloride in processed foods, typically formulated to deliver equivalent salinity at 25-50% lower sodium content by mass. Salt substitutes dominate volume flows due to direct chloride replacement functionality and lower unit cost, while flavor enhancers capture expanding margin pools as manufacturers seek clean-label taste restoration without metallic off-notes. Bakery and snack applications lead demand structurally given high baseline sodium in bread, biscuits, and savory packaged goods across the continent.
South Africa's Department of Health enforces mandatory sodium reduction targets for bread, cereals, and processed meats under its 2016 regulations, compressing formulation timelines for domestic manufacturers. The country's national standards body, SABS, coordinates with EAC partner states on harmonized salt reduction guidelines that shape cross-border product registration and reformulation requirements. Nigeria's National Agency for Food and Drug Administration and Control and Kenya's Bureau of Standards apply parallel but non-identical maximum sodium thresholds, fragmenting compliance architecture. Stakeholders must monitor regulatory divergence between SADC and EAC frameworks while building flexible formulation platforms that accommodate multiple national threshold schedules without dedicated SKUs per market.
Market Dynamics
Front-of-pack labeling mandates and potassium chloride blend adoption on Lagos and Nairobi factory floors are compressing formulation timelines and concentrating supply chain investment in East and Southern Africa corridors.
Growth Catalysts
- South Africa's sodium reduction targets:Mandatory thresholds for bread, cereals, and processed meats under 2016 Department of Health regulations force domestic manufacturers into accelerated reformulation cycles.
- Yeast extract adoption:Umami-enhancing yeast derivatives gain traction in snack seasoning applications as manufacturers seek clean-label sodium masking without metallic potassium chloride off-notes.
- EAC harmonization momentum:Kenya Bureau of Standards coordination with SABS on cross-border salt reduction guidelines streamlines product registration for regional processors.
Market Restraints
- Potassium chloride price volatility:Dependence on imported potassium salts exposes formulators to currency fluctuation and shipping cost spikes from Middle Eastern and European suppliers.
- Taste modulation limitations:Metallic aftertaste in potassium-based substitutes persists above 30% sodium replacement levels, capping maximum feasible reduction in savory applications.
- Regulatory fragmentation:Divergent maximum sodium thresholds between SADC and EAC frameworks force manufacturers to maintain multiple formulation platforms or lowest-common-denominator recipes.
Strategic Opportunities
- Nigeria's processed meat sector:Suya spice blends and cured meat categories remain underpenetrated by sodium reduction technologies, offering first-mover positioning for localized taste modulation systems.
- Micronutrient convergence:Dual-function salt replacers combining sodium reduction with iodine or iron fortification align with WHO nutrition targets and national fortification mandates.
- Direct-to-mill distribution:Bypassing traditional ingredient traders to supply potassium chloride directly to industrial bakeries in Accra and Dar es Salaam compresses landed costs and secures volume commitments.
Industry Challenges
- Sensory science talent scarcity:Formulation chemists with expertise in salt taste receptor mapping and masking technology remain concentrated in South Africa, constraining R&D capacity in West and East African operations.
- Legacy equipment retrofit costs:Hygroscopic potassium chloride blends require moisture-controlled handling systems that demand capital expenditure beyond reach of mid-scale Nigerian and Kenyan processors.
- Multi-jurisdiction compliance timelines:Parallel NAFDAC and KEBS certification pathways for novel salt replacers extend product launch windows by 8-14 months versus single-market registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Sodium Reduction Ingredients Market |
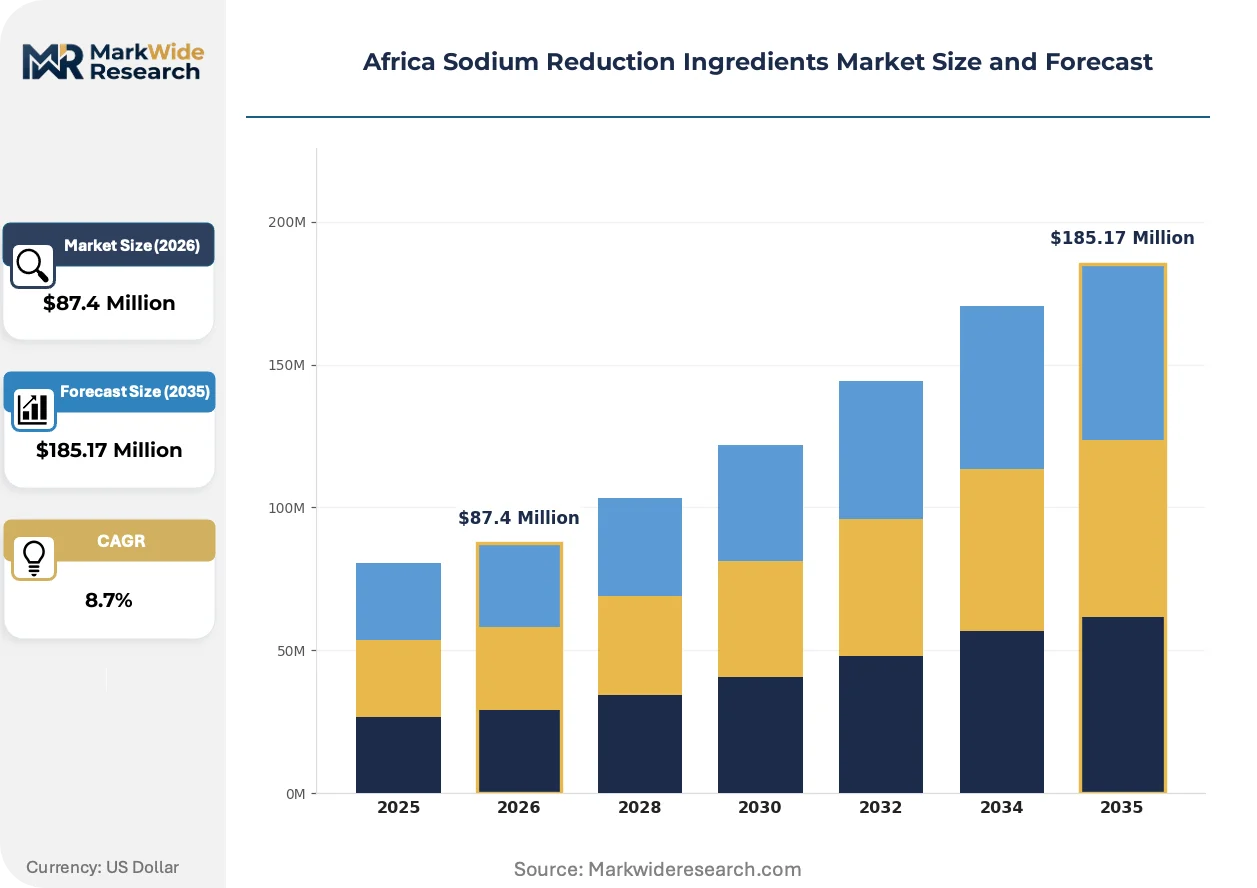
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Acidulants, Taste Modulators Application: Bakery, Dairy, Snacks, Beverage End User: Food Manufacturers, Packaging Companies, Restaurant Chains, Retailers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Kerry Group, Givaudan, Tate & Lyle, DSM NV, Innophos Holdings, Sensient Technologies Corporation, Jungbunzlauer Suisse AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Sodium Reduction Ingredients Market Strategic Shifts
Microencapsulation technologies and fermentation-derived flavor enhancers are displacing conventional mineral salt substitutes in premium formulation pipelines across the continent.
Layered potassium chloride crystals coated with hydrophobic lipids is rewriting moisture stability standards for sodium reduction ingredients. Nigerian biscuit manufacturers operating high-humidity production environments in Lagos port zones now specify encapsulated grades that eliminate caking and flow disruption. This technology is rewriting procurement specifications by enabling direct substitution in existing salt dosing equipment without pneumatic system upgrades.
Kenya's Bureau of Standards has advanced draft regulations mirroring South Africa's front-of-pack warning label system for high-sodium packaged foods. Industrial bakeries in Nairobi and Mombasa are pre-emptively reformulating bread and cracker portfolios to avoid mandatory black octagon labels. The biscuit and savory snack segment is responding fastest, with technical teams accelerating pilot trials of amino acid-based enhancers to maintain consumer acceptance at sub-400mg sodium per 100g thresholds.
Pan-African food manufacturers are consolidating ingredient procurement under centralized technical standards rather than country-specific sourcing. Regional category managers at multinational processors now mandate single pan-African formulations that satisfy the strictest national sodium ceiling rather than maintaining market-specific recipes. This pattern is most visible in the instant noodle and seasoning mix categories, where Ghana, Nigeria, and Kenya operations have unified around reduced-sodium base formulations despite divergent local taste preferences.
Africa Sodium Reduction Ingredients Market Segmentation
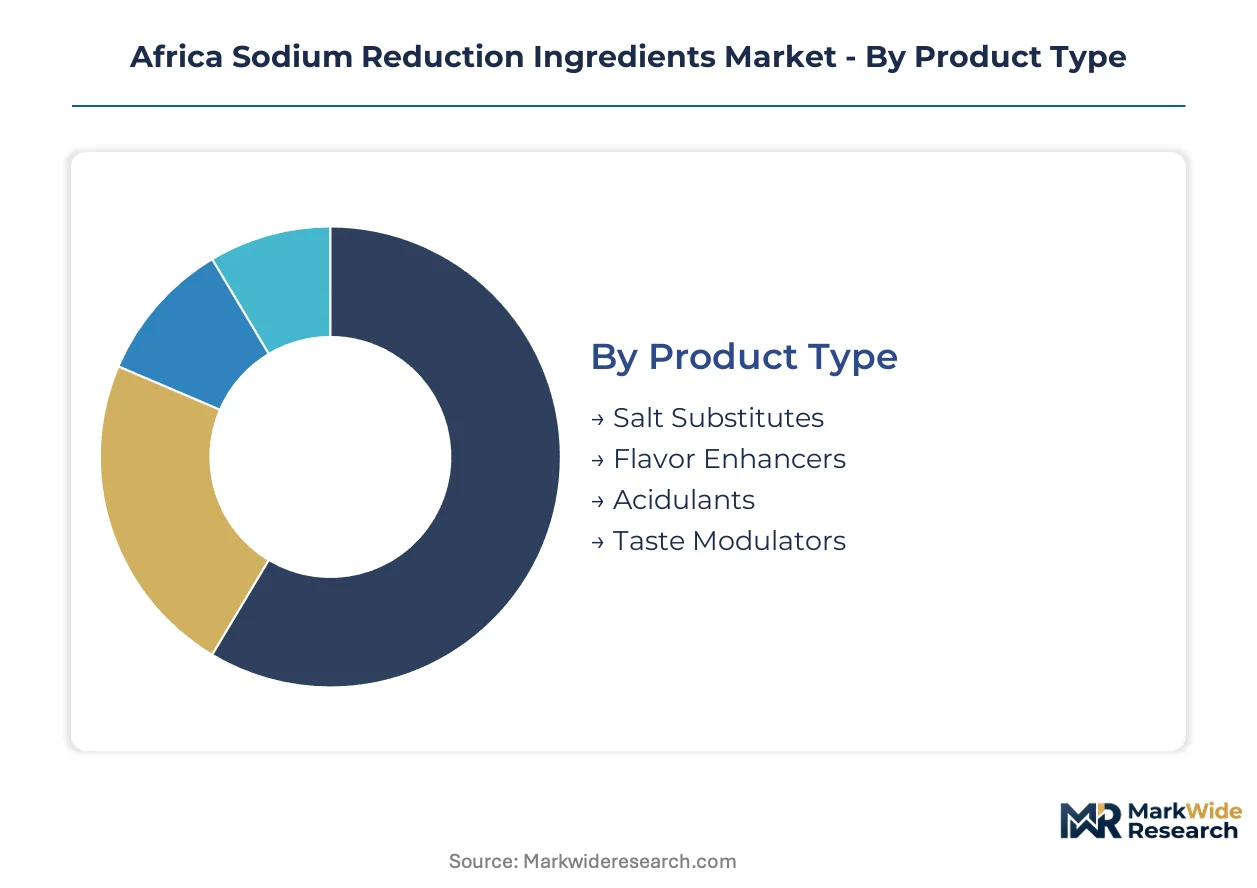
Sodium reduction ingredient procurement in Africa fragments across technical performance tiers, application heat-stability demands, and supply chain proximity to potassium chloride import corridors. Understanding these segment boundaries enables suppliers to align formulation investments with the continent's divergent regulatory timelines and manufacturing infrastructure gaps.
Product Type:
Potassium chloride supply concentrates in Middle Eastern and European export hubs, exposing African formulators to currency-driven cost tier volatility and shaping ingredient selection across humidity-stressed production environments.
- Salt Substitutes:Potassium chloride and potassium-based mineral salts deliver direct sodium replacement at 25-50% mass reduction. Lagos and Nairobi industrial bakeries specify encapsulated grades to combat caking in high-humidity port zones. Metallic aftertaste above 30% replacement thresholds limits savory application penetration.
- Flavor Enhancers:Yeast extracts and amino acid derivatives restore umami perception without sodium chloride. Kenyan snack manufacturers adopt these for clean-label positioning ahead of Bureau of Standards warning label mandates. Cost premiums versus mineral salts constrain mass-market deployment.
- Acidulants:Citric and lactic acid blends amplify salt perception through pH modulation. Nigerian suya spice processors utilize acidulant-salt synergies in cured meat applications.
- Taste Modulators:Bitter-blocking compounds mask potassium chloride off-notes in high-replacement formulations. South African sensory labs lead technical adoption for processed meat categories.
Today's leader: Salt Substitutes. Tomorrow's challenger: Flavor Enhancers.
Application:
Application demand stratifies around baseline sodium density, with heat-processing requirements and moisture sensitivity dictating ingredient compatibility across factory equipment generations.
- Bakery:Bread, biscuits, and crackers carry the highest structural sodium loads across African packaged food. Kenyan industrial bakeries drive reformulation urgency to preempt front-of-pack warning labels. Encapsulated potassium chloride grades enable direct substitution in legacy salt dosing equipment.
- Snacks:Savory seasoning applications favor yeast extract adoption for clean-label sodium masking without metallic off-notes. Nigerian and Ghanaian processors pilot amino acid-based enhancers for sub-400mg sodium per 100g thresholds.
- Dairy:Cheese and processed milk applications require heat-stable salt replacers compatible with UHT processing lines. South African dairy cooperatives lead technical specification development.
- Beverage:Isotonic and flavored water categories utilize mineral salt blends for electrolyte positioning alongside sodium reduction. East African bottlers show fastest uptake.
Bakery commands current volume. Snacks are climbing the fastest as warning label deadlines compress formulation timelines.
End User:
End-user procurement maturity diverges sharply between multinational processors with centralized technical standards and mid-scale domestic manufacturers reliant on distributor technical support.
- Food Manufacturers:Pan-African processors consolidate procurement under single technical standards satisfying strictest national sodium ceilings. Instant noodle and seasoning mix categories show unified reduced-sodium base formulations across Ghana, Nigeria, and Kenya operations.
- Packaging Companies:Flexible packaging converters integrate sodium reduction messaging into front-of-pack design services for compliant label positioning.
- Restaurant Chains:Quick-service operators in South Africa and Nigeria reformulate proprietary seasoning blends for menu sodium transparency.
- Retailers:Private-label packaged food programs in Kenyan and Nigerian supermarket chains specify sodium-reduced specifications for competitive differentiation.
Food Manufacturers set technical standards today. Restaurant Chains represent the emerging specification influence as consumer-facing sodium transparency demands intensify.
Distribution Channel:
Channel selection tracks order scale, technical service requirements, and geographic distance from potassium chloride import terminals in Lagos, Mombasa, and Durban.
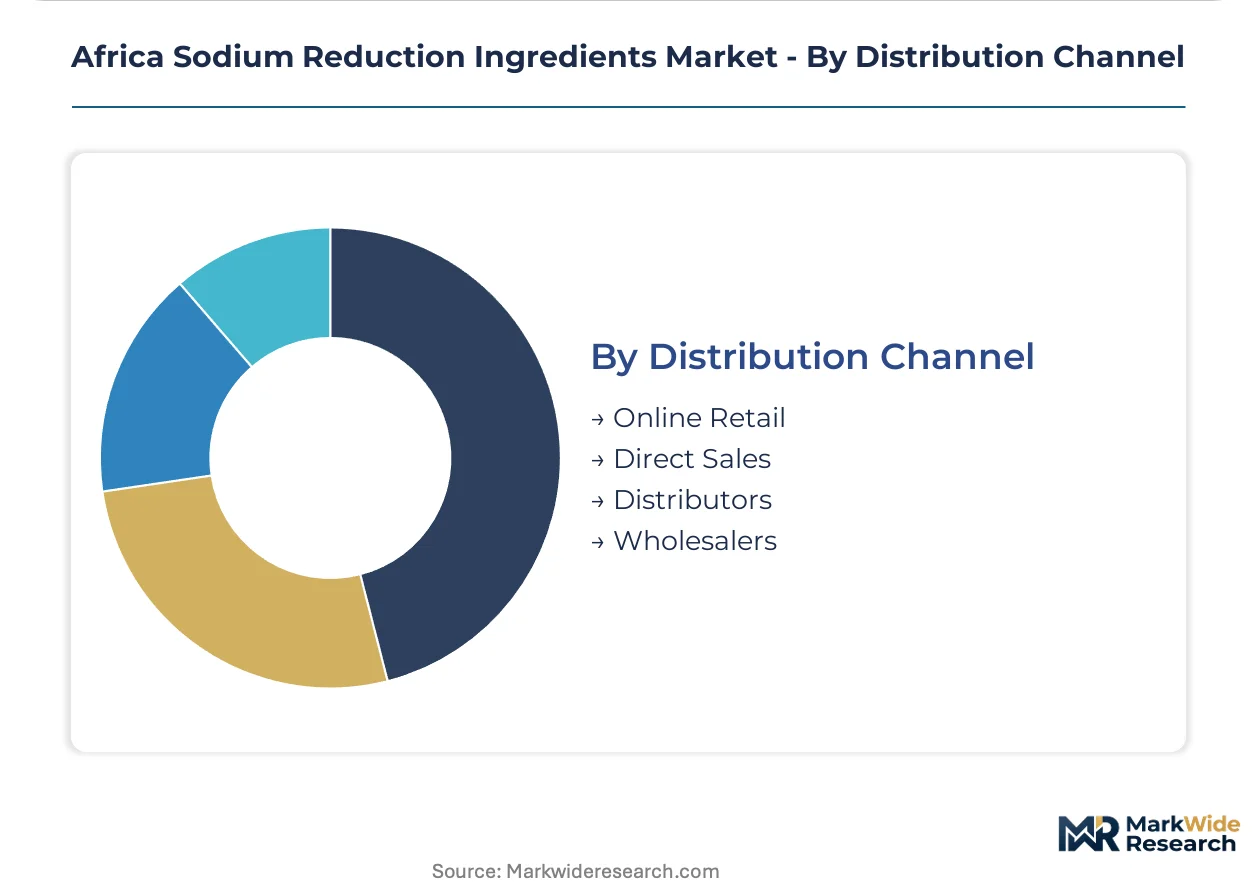
- Direct Sales:Cargill and Kerry Group deploy technical sales teams to anchor supply relationships with multinational processors in Johannesburg and Lagos. Direct channels capture premium formulation service margins.
- Distributors:Regional ingredient traders serve mid-scale Nigerian and Kenyan manufacturers lacking capital for moisture-controlled handling system upgrades. Distributor technical support fills sensory science talent gaps outside South Africa.
- Online Retail:E-procurement platforms gain traction among smaller Ghanaian and Tanzanian bakeries seeking spot potassium chloride purchases.
- Wholesalers:Traditional traders supply unpackaged salt substitutes to informal sector food processors in West African urban markets.
Direct Sales dominate value capture now. Distributors are gaining share fastest as mid-market processor technical demands outpace in-house formulation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating formulation capacity to jurisdictions with lighter compliance burdens or faster regulatory pathways. South Africa's strict sodium ceilings push some production toward neighboring SADC states with transitional enforcement timelines.
South Africa
Industrial bakeries in Johannesburg and Cape Town face compressed reformulation deadlines under Department of Health regulations. The country's national standards body coordinates with EAC partners on harmonized guidelines. Durban port terminals anchor potassium chloride import flows for regional redistribution.
Nigeria
Lagos factory floors are accelerating adoption of encapsulated potassium chloride blends for biscuit production. The National Agency for Food and Drug Administration and Control applies maximum sodium thresholds that diverge from EAC standards. Suya spice processors in Kano represent an underpenetrated segment for taste modulation systems.
Kenya
Nairobi industrial bakeries are pre-emptively reformulating to avoid pending Bureau of Standards warning label mandates. Draft regulations mirror South Africa's front-of-pack black octagon system. Mombasa port infrastructure supports direct-to-mill distribution models for regional manufacturers.
Ghana
Accra-based bakeries specify imported encapsulated salt substitutes for high-humidity production environments. The Food and Drugs Authority maintains parallel but non-identical sodium thresholds versus Nigerian and Kenyan regulators. Local procurement teams are consolidating under pan-African technical standards from multinational parent companies.
Tanzania
Dar es Salaam processing hubs are emerging as alternative formulation sites for brands seeking lower compliance costs than South Africa. The Tanzania Bureau of Standards participates in EAC harmonization discussions but maintains independent enforcement timelines. Smaller bakeries are experimenting with e-procurement platforms for spot potassium chloride purchases.
Africa Sodium Reduction Ingredients Market Competitive Environment
European specialists anchor one tier; North American integrated ingredient houses hold another. The vendor base splits between mineral salt processors with captive potassium chloride supply and flavor technology developers with sensory science capabilities. Three archetypes dominate: diversified agribusiness conglomerates with regional distribution networks, taste modulation specialists with proprietary masking compounds, and micronutrient-focused formulators serving dual-function fortification mandates. Capacity expansion and direct-to-manufacturer distribution partnerships constitute the primary competitive moves.
Within the diversified agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify players leveraging existing grain and oilseed supply chains to anchor ingredient distribution. Kerry Group and Givaudan occupy positions as taste technology specialists with formulation service capabilities. DSM NV represents the micronutrient convergence archetype, anchoring supply relationships where sodium reduction and fortification mandates overlap.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kerry Group |
| Givaudan |
| Tate & Lyle |
| DSM NV |
| Innophos Holdings |
| Sensient Technologies Corporation |
| Jungbunzlauer Suisse AG |
| Others |
Value Chain & Pricing Dynamics
Potassium chloride import costs from Middle Eastern and European suppliers cascade through three distinct pricing tiers as currency fluctuations and shipping spikes compress margins for African formulators. Lagos and Nairobi industrial bakeries absorb landed cost volatility through volume commitments, while mid-scale processors in Accra and Dar es Salaam face spot market exposure.
Pricing Analysis
Distributor margin layers separate premium encapsulated grades from standard mineral salts and economy bulk potassium chloride. Price differentiation hinges on moisture-stability certification and direct-to-mill volume scale, with premium tiers capturing formulation service bundling. Pricing pressure intensifies as Nigerian biscuit manufacturers consolidate procurement under pan-African technical standards. Mid-scale Kenyan processors exhibit highest price sensitivity due to legacy equipment retrofit burdens.
Supply Chain Analysis
Domestic-content mandates remain absent across SADC and EAC jurisdictions, leaving sourcing decisions tethered to import corridor efficiency. Supply concentrates in Germany, Israel, and Jordan for potassium chloride feedstock, with Kenyan and Nigerian formulators dependent on Mombasa and Lagos port terminals. Currency volatility and Red Sea shipping disruptions constitute primary supply chain risk. Distribution runs through Cargill and Kerry Group direct sales for multinationals, regional distributors for mid-market processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation technology premiums and yeast extract adoption are expanding margin pools for suppliers who capture formulation service relationships. Cost compression in standard mineral salt tiers is accelerating procurement consolidation.
For Market Incumbents: Extend sensory science capabilities into West and East African operations to counter talent concentration in South Africa. Deepen direct-to-mill distribution partnerships with industrial bakeries in Accra and Dar es Salaam to lock volume commitments ahead of regulatory harmonization. Anchor supply relationships through micronutrient-enhanced salt replacers that satisfy dual-function fortification mandates. For New Entrants and Emerging Players: Microencapsulation technology for high-humidity production environments offers first-mover positioning in Lagos port zone biscuit manufacturing. Target Nigeria's suya spice and cured meat segments where taste modulation systems remain underpenetrated. Lead with technical sales teams that fill sensory science gaps outside South Africa. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity constrains R&D capacity in West and East African operations. Long-term viability favors taste modulation specialists with proprietary masking compounds and regional distribution networks. Watch Kenya Bureau of Standards warning label implementation as inflection indicator for reformulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Mill Distribution Partnerships | Cargill's regional grain supply chains anchor potassium chloride delivery to Lagos and Nairobi industrial bakeries. |
| Microencapsulation Capacity Expansion | Encapsulated grades enable Nigerian biscuit manufacturers to bypass pneumatic system upgrades in high-humidity zones. |
| Sensory Science Talent Acquisition | Kerry Group's taste modulation systems address metallic off-note limitations above 30% sodium replacement thresholds. |
| Dual-Function Fortification Development | DSM NV's micronutrient-enhanced salt replacers align with WHO nutrition targets and national fortification mandates. |
| Pan-African Formulation Standardization | Regional category managers at multinational processors consolidate procurement under single technical standards. |
Study Parameters
Bottom-up bakery and snack manufacturer modeling reconciled against top-down potassium chloride import tracking forms the analytical core of this study. Primary interviews with formulation chemists, procurement leads at industrial bakeries, regulatory affairs officers at national standards bodies, and distribution channel partners were validated against secondary sources including SABS and KEBS regulatory filings, customs import records, and industry association sodium reduction guidelines.
Historical trendline analysis of reformulation cycles under South Africa's 2016 Department of Health regulations informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type tiers, application heat-stability requirements, end-user procurement maturity, and distribution channel proximity to import terminals. CAGRs were derived from volume trajectory analysis incorporating regulatory deadline compression effects and yeast extract adoption curves.
The model holds under stable currency and shipping cost assumptions; deviation in potassium chloride price volatility or EAC-SADC regulatory divergence would shift manufacturer formulation timelines. Forecasts reflect documented assumptions regarding harmonization momentum and encapsulation technology penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Germany Gelatin Market
Ingredients
Ben Oil Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Calendula Oil Market
Ingredients
Dry Molasses Products Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Native Starch Market
Ingredients
Food Botanicals Market
Ingredients
Egg Membrane Powder Market
Ingredients
Vegetable Fats Market
Ingredients
North America Feed Yeast Market
Ingredients
Synephrine Market
Ingredients
Egg White Powder Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market