
 Rice Protein Market | 2026-2036
Rice Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Protein Market Analysis
Subscription-based formulation services is restructuring how rice protein gets sold to nutraceutical brands, shifting transactions from bulk commodity orders to ongoing R&D partnerships. Axiom Foods, Inc. leverages its vertically integrated supply chain from rice milling to protein extraction. Kerry Group plc anchors its position through flavor-masking technology that solves rice protein's traditional taste limitations. BENEO competes by dominating the European regulatory pathway for novel food approvals.
Rice protein comprises amino acid chains extracted from brown or white rice through enzymatic hydrolysis, typically yielding protein content ranging from 50% to 85% depending on processing intensity, and serves primarily as a hypoallergenic alternative to dairy and soy proteins in food and supplement formulations. Concentrate and isolate grades command the bulk of current volume, though hydrolysate variants capture expanding margin pools in sports nutrition where faster absorption rates justify premium positioning. The supplements application segment leads absolute demand while beverages represents the fastest-growing insertion point as brands reformulate ready-to-drink products.
FDA labeling requirements and EFSA novel food frameworks jointly determine which rice protein products gain shelf access in North America and Europe, with organic certification standards adding a third compliance layer for premium positioning. The EU Green Deal's protein diversification targets accelerate research funding for domestic pulse and cereal protein production, indirectly boosting rice protein's competitive standing against imported soy. Stakeholders must monitor evolving amino acid fortification standards as regulators scrutinize plant protein nutritional equivalence claims.
Market Dynamics
Enzymatic hydrolysis advances are compressing extraction costs while FDA labeling clarity requirements force manufacturers to substantiate amino acid completeness claims with analytical data.
Growth Catalysts
- EFSA Novel Food Framework:Accelerated approval pathways in Germany enable functional food brands to secure shelf placement with validated health claims.
- Sports Nutrition Formulation:Recovery product lines embed rice protein at commercial scale as athletes reject dairy and soy allergens.
- Enzymatic Hydrolysis:Process intensification yields protein concentrates above 80% purity, opening pharmaceutical-grade applications.
Market Restraints
- Input Cost Volatility:Brown rice prices fluctuate with monsoon patterns across Indian and Thai growing regions.
- Flavor-Masking Burden:Rice protein's inherent chalkiness demands costly taste-modification additives that erode margin.
- Soy Protein Substitution:Established soy isolate supply chains in Brazil and Argentina undercut rice protein on bulk pricing.
Strategic Opportunities
- Ready-to-Drink Beverages:Beverage brands in the United States reformulate protein-fortified drinks with rice-derived alternatives.
- EU Green Deal Protein Diversification:Research funding mandates create procurement preferences for domestic cereal proteins over imported soy.
- Subscription R&D Partnerships:Nutraceutical brands abandon spot commodity purchases for ongoing formulation development contracts.
Industry Challenges
- Organic Certification Timelines:USDA and EU organic equivalency audits delay product launches by 8-14 months.
- Amino Acid Fortification Standards:Regulators scrutinize lysine and leucine supplementation claims, requiring expensive third-party validation.
- Flavor Chemistry Talent Scarcity:Protein manufacturers compete for food scientists capable of masking rice protein's sensory profile.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Protein Market |
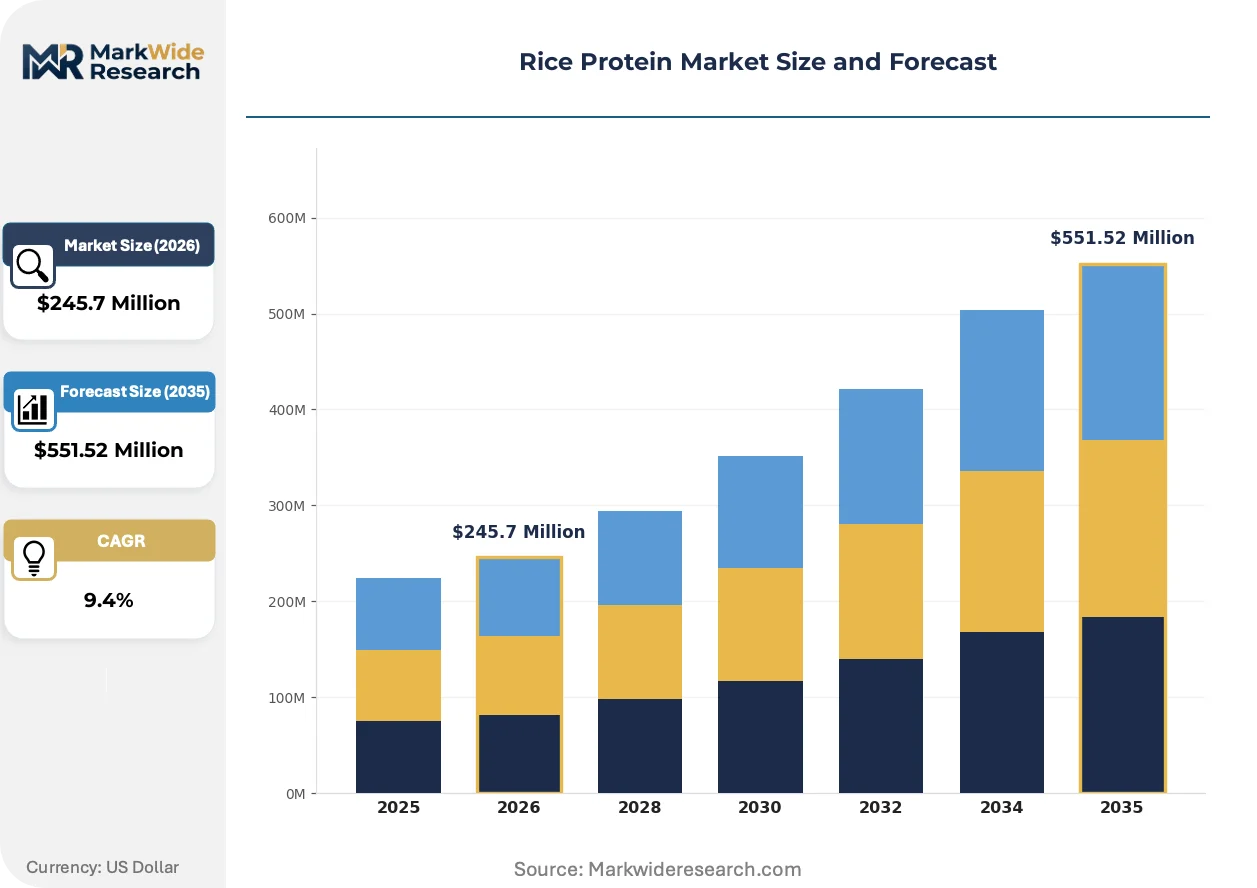
| Market Size in 2026 | $245.7 Million |
| Market Size in 2035 | $551.52 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Textured Application: Beverages, Bakery, Snacks, Supplements End User: Food & Beverage Industry, Nutraceuticals, Sports Nutrition, Private Label Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Distributors |
| Companies Covered | Axiom Foods, Inc., RiceBran Technologies, Kerry Group plc, Shafi Gluco Chem Pvt. Ltd., BENEO, Golden Grain Group Limited, AIDP Inc., Bioway Organic Group Limited, The Green Labs LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Protein Market Emerging Trajectories
Bioprocessing breakthroughs and regulatory clarity mandates are restructuring how rice protein manufacturers compete on purity claims and speed-to-market.
Hydrolysate-grade rice protein is overtaking standard concentrates in sports nutrition formulations. Premium sports brands specify enzymatically pre-digested proteins for faster amino acid absorption post-workout. This shift is compressing margins on legacy concentrate grades while rewarding processors with advanced hydrolysis capabilities.
EFSA's updated guidance on plant protein nutritional equivalence requires substantiated amino acid scoring data on all novel food approvals. German functional food manufacturers now submit complete PDCAAS profiles with every novel food dossier. Sports nutrition lines targeting EU distribution are reformulating with explicit lysine fortification to meet these documentation standards.
Direct-to-brand formulation partnerships are displacing traditional bulk commodity distribution. Nutraceutical companies in California and Bavaria now embed supplier R&D teams inside their product development workflows. This channel shift concentrates procurement decisions among vertically integrated processors with captive analytical laboratories.
Rice Protein Market Segmentation
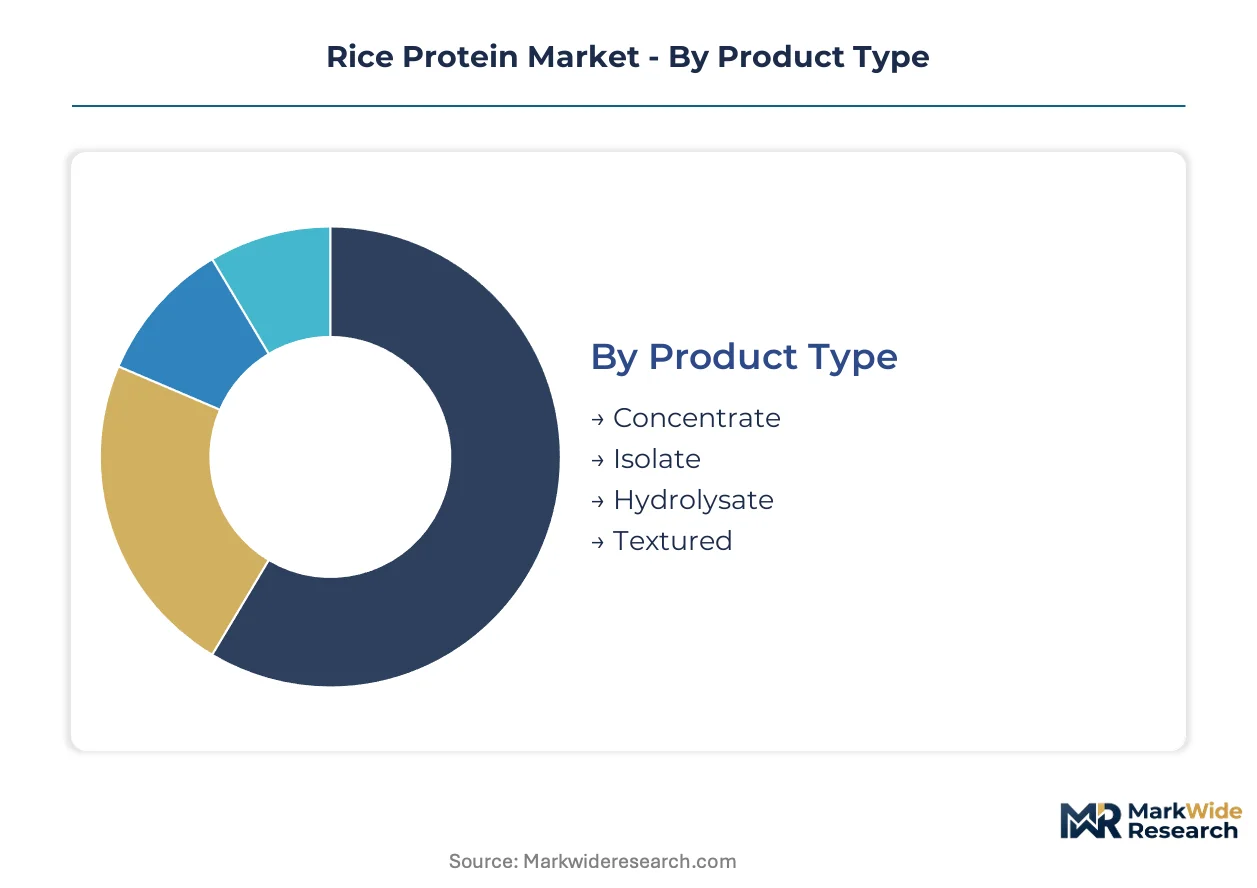
Product formulation upgrades and shifting consumer preferences toward hypoallergenic proteins drive how manufacturers prioritize segment investments. Each segmentation dimension reveals distinct margin structures and competitive intensity patterns across the value chain.
Product Type:
Enzymatic processing intensity determines protein purity tiers and unlocks application-specific pricing power.
- Concentrate:Protein content ranges from 50% to 70% with retained fiber and carbohydrate fractions. Food & Beverage Industry procurement in Germany favors concentrate grades for cost-sensitive bakery applications where EFSA novel food approvals mandate documented amino acid profiles.
- Isolate:Purity exceeds 80% through additional filtration and washing steps. Sports Nutrition brands in California specify isolate grades for premium recovery formulations where lysine fortification meets FDA labeling substantiation requirements.
- Hydrolysate:Pre-digested protein fragments enable rapid amino acid absorption. Nutraceutical brands embed hydrolysate in pharmaceutical-grade applications where enzymatic hydrolysis advances compress production costs.
- Textured:Extruded protein structures mimic meat-like mouthfeel. Plant-based meat manufacturers in Netherlands integrate textured rice protein for EU Green Deal-aligned protein diversification targets.
Concentrate sits at the top of the volume ranking, with Hydrolysate climbing the fastest.
Application:
End-use maturity and reformulation cycles segment demand by technical barrier and speed of adoption.
- Supplements:Powder and capsule formats dominate current procurement volumes. Sports Nutrition lines in Germany embed rice protein at commercial scale as athletes reject dairy and soy allergens, with EFSA-approved health claims accelerating retail placement.
- Beverages:Ready-to-drink protein fortification demands solubility and flavor-masking breakthroughs. United States beverage brands reformulate with rice-derived alternatives where Kerry Group's taste-modification technology resolves traditional chalkiness limitations.
- Bakery:Protein enrichment in bread and pastry applications requires moisture retention management. Private Label manufacturers in France leverage concentrate grades for functional food aisle expansion under EU organic certification timelines.
- Snacks:Extruded and puffed formats utilize textured protein for crunch and satiety claims. Nutraceutical brands in Bavaria specify isolate grades for high-protein snack bars where amino acid completeness documentation satisfies regulator scrutiny.
Supplements commands absolute demand, while Beverages expands most quickly as formulation barriers fall.
End User:
Customer type determines procurement sophistication, from spot commodity purchasing to embedded R&D partnerships.
- Sports Nutrition:Recovery product lines specify hydrolysate grades for post-workout absorption speed. German functional food manufacturers submit complete PDCAAS profiles with every novel food dossier under EFSA's updated equivalence guidance.
- Food & Beverage Industry:Mass-market reformulation drives concentrate volume at price-sensitive specifications. Brown rice price volatility across Indian and Thai growing regions directly impacts input cost structures for bakery and snack applications.
- Nutraceuticals:Subscription-based formulation services restructure procurement from bulk orders to ongoing partnerships. California brands embed supplier R&D teams inside product development workflows, concentrating decisions among vertically integrated processors.
- Private Label:Retailer-controlled brands demand flexible minimum order quantities and rapid certification turnaround. Organic certification equivalency audits between USDA and EU standards delay launches by 8-14 months for premium positioning.
Sports Nutrition leads margin capture, with Nutraceuticals gaining share fastest through partnership model displacement.
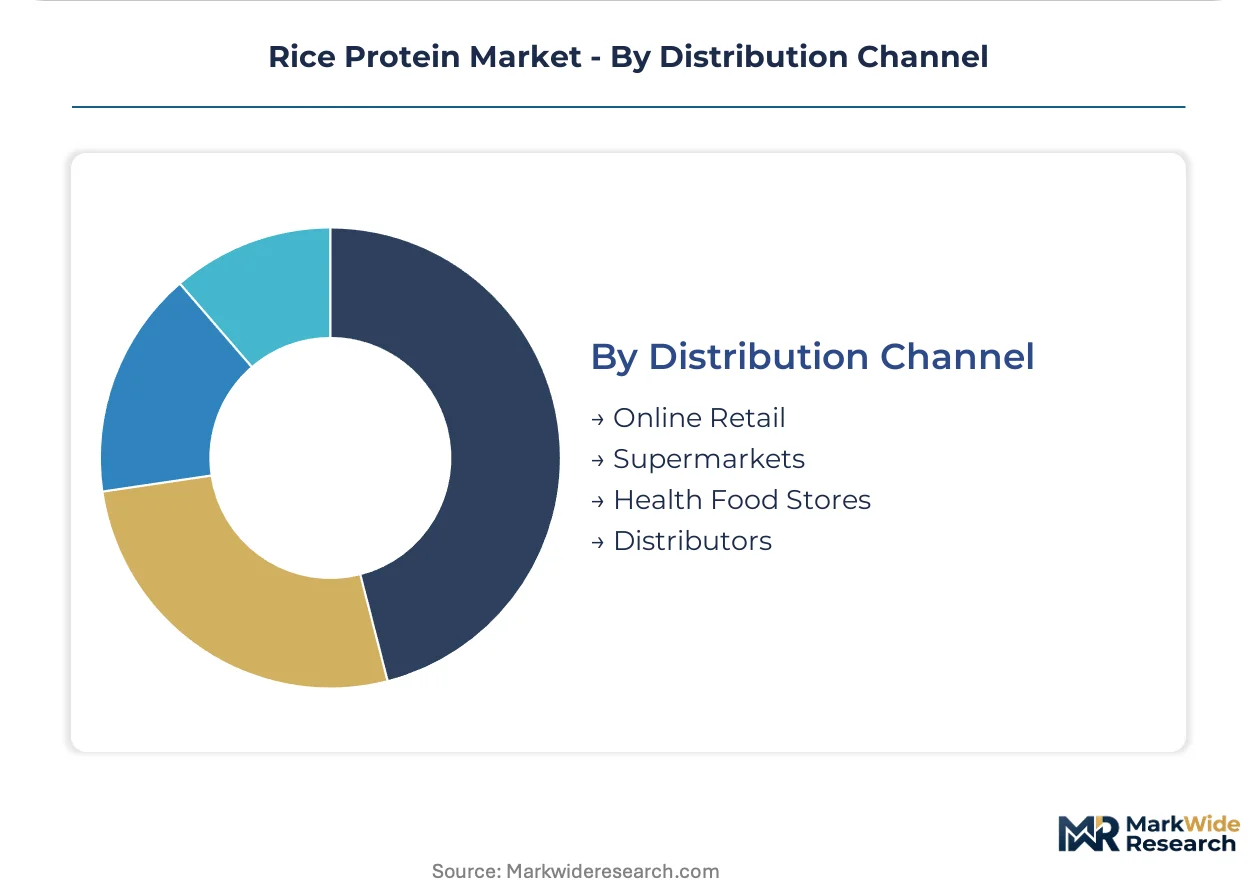
Distribution Channel:
Channel selection reflects customer education requirements and regulatory documentation burdens.
- Distributors:Bulk commodity flows through specialized ingredient distributors serving mid-scale manufacturers. Technical support and analytical laboratory access differentiate distributor relationships for hydrolysate procurement.
- Online Retail:Direct-to-consumer protein powders bypass traditional retail slotting fees. Subscription models in United States markets embed formulation development into recurring revenue structures.
- Health Food Stores:Specialty retail demands organic certification and clean-label positioning. German functional food aisles prioritize EFSA-validated health claims for shelf placement decisions.
- Supermarkets:Mass retail penetration requires flavor-masking technology investment and competitive unit economics. Soy protein substitution pressure from Brazilian and Argentine supply chains challenges rice protein pricing in bulk segments.
Distributors anchor current volume flows, with Online Retail climbing fastest as subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher functional food shelf placement velocity than the United States, where beverage reformulation cycles lag by roughly eighteen months. Brazil and India concentrate raw material supply, while Thailand and China dominate intermediate processing capacity.
Germany
EFSA novel food approvals accelerate retail placement in functional food aisles as manufacturers submit complete PDCAAS profiles with every dossier. The EU Green Deal's protein diversification targets channel research funding toward domestic cereal protein production. Bavaria-based nutraceutical brands embed supplier R&D teams inside product development workflows, shifting procurement from bulk orders to ongoing partnerships.
United States
Beverage brands reformulate ready-to-drink protein products where flavor-masking technology resolves traditional chalkiness limitations. FDA labeling clarity requirements force manufacturers to substantiate amino acid completeness claims with analytical data. California sports nutrition lines specify hydrolysate grades for post-workout absorption speed, anchoring West Coast demand concentration.
Brazil
Established soy isolate supply chains undercut rice protein on bulk pricing, pressuring margin structures for imported alternatives. The national agricultural regulator enforces equivalency standards for novel protein ingredients entering food formulations. São Paulo clusters concentrate private label manufacturing for Latin American export markets.
India
Brown rice prices fluctuate with monsoon patterns across growing regions, transmitting volatility directly into input cost structures. FSSAI standards govern protein content claims and amino acid fortification documentation for domestic nutraceutical sales. Punjab and Haryana rice milling belts supply raw material to emerging extraction facilities in Gujarat.
Thailand
Enzymatic hydrolysis advances compress extraction costs while maintaining protein concentrates above 80% purity. The country's national food and drug administration aligns with ASEAN harmonized standards for novel ingredient approvals. Bangkok-centered processing clusters export intermediate concentrates to European and North American finished goods manufacturers.
Rice Protein Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with concentrate grades flowing through bulk distributors while hydrolysate procurement concentrates among vertically integrated processors. The vendor base organizes around three archetypes: rice millers with captive extraction capacity, flavor technology specialists solving sensory limitations, and regulatory pathway navigators securing novel food approvals. Consolidation pressure intensifies as subscription-based formulation services displace spot commodity transactions. Capacity expansion and backward integration into rice milling represent the dominant competitive moves.
Within the vertically integrated tier, Axiom Foods, Inc. exemplifies processors controlling supply from rice milling through protein extraction. Kerry Group plc anchors the flavor-technology vector, occupying a position where taste-modification capabilities determine beverage application viability. BENEO sits within the regulatory-specialist archetype, representing European market access strategies built around EFSA novel food dossier expertise.
| Leading Market Players |
|---|
| Axiom Foods, Inc. |
| RiceBran Technologies |
| Kerry Group plc |
| Shafi Gluco Chem Pvt. Ltd. |
| BENEO |
| Golden Grain Group Limited |
| AIDP Inc. |
| Bioway Organic Group Limited |
| The Green Labs LLC |
| Others |
Supply Flow & Price Mechanics
Hydrolysate-grade premiums diverge sharply from concentrate commoditization, compressing margins on legacy grades while rewarding enzymatic processing investments. This bifurcation manifests in procurement patterns: sports nutrition brands in California pay absorption-speed premiums while German bakery buyers prioritize EFSA-compliant documentation over purity tiers.
Pricing Analysis
Capacity additions in Thailand are reshaping price floors for concentrate grades as enzymatic hydrolysis advances compress extraction costs. Three-tier pricing structure across hydrolysate, isolate, and concentrate levels anchors the market, with certification grade and volume scale driving differentiation. Cost compression in standard concentrates is intensifying because Brazilian soy isolate supply chains undercut rice protein on bulk commodity orders. Private label manufacturers exhibit highest price sensitivity, while nutraceutical brands pursuing subscription R&D partnerships show least.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Thai brown rice growing regions where monsoon patterns transmit volatility directly into input cost structures. Raw material dependencies center on milled brown rice, specialized enzyme inputs for hydrolysis, and organic certification audit capacity. Commodity price volatility constitutes the dominant structural risk, with brown rice futures fluctuating across Punjab and Haryana belts. Distribution runs through specialized ingredient distributors serving mid-scale manufacturers, though direct-to-brand formulation partnerships are displacing traditional bulk flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by sports nutrition demand-shift toward hydrolysate specifications with documented PDCAAS profiles.
For Market Incumbents: Extend flavor-masking technology investments to defend beverage application viability against emerging taste-modification specialists. Backward integration into rice milling secures input cost control as brown rice price volatility intensifies across Indian growing regions. Capacity expansion in Thailand leverages enzymatic hydrolysis advances to capture pharmaceutical-grade margin pools. For New Entrants and Emerging Players: Direct-to-brand subscription channels offer the lowest barrier entry point for nutraceutical procurement relationships displacing spot commodity transactions. Target ready-to-drink beverage reformulation in United States markets where Kerry Group's taste technology has not yet saturated channel access. White-space exists in textured protein for EU Green Deal-aligned plant-based meat applications. For Investors and Strategic Acquirers: Consolidation pressure builds where subscription-based formulation services concentrate procurement decisions among vertically integrated processors with captive analytical laboratories. Long-term viability favors acquirers of enzymatic hydrolysis capability over commodity concentrate processors. Signal to monitor: FSSAI amino acid fortification standard revisions altering documentation burdens for Indian export-oriented facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Thai processing clusters capture pharmaceutical-grade margin pools above 80% purity. |
| Backward Integration into Rice Milling | Axiom Foods' captive supply from milling through extraction insulates input cost volatility. |
| Flavor-Masking Technology Investment | Kerry Group's taste modification resolves chalkiness limitations blocking beverage adoption. |
| EFSA Novel Food Dossier Expertise | BENEO's regulatory pathway navigation accelerates German functional food shelf placement. |
| Subscription R&D Partnership Model | California nutraceutical brands embed supplier teams inside product development workflows. |
Methodological Framework
Multiple input streams — executive interviews with rice protein processors, procurement leads at sports nutrition brands, regulatory affairs specialists navigating EFSA novel food frameworks, and flavor technology R&D directors — were reconciled against secondary validation. Trade data from Indian and Thai customs authorities, FSSAI protein content standard filings, EFSA novel food approval registers, and SEC disclosures from listed ingredient suppliers anchored quantitative baselines. Bottom-up segment sizing and top-down macro reconciliation triangulated volume and value estimates.
Segmentation dimensions modeled across the analysis window include product type tier, application end-use, customer procurement sophistication, and regional regulatory cluster. CAGRs were derived from trend extrapolation of enzymatic processing adoption rates, EFSA approval velocity, and sports nutrition formulation shifts. Forecast inputs incorporated brown rice price volatility indices and FDA labeling clarity enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for enzymatic hydrolysis cost compression would alter the outlook. Forecasts reflect assumptions about EFSA novel food approval timelines and organic certification equivalency audit durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
South America Pea Protein Market
Plant Based Food
Vegan Food Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Vegan Meals Market
Plant Based Food
Tempeh Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Veggie Burger Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Vegan Spaghetti Market