
 India Olive Oil Market | 2026-2036
India Olive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
India Olive Oil Market Insights
Pomace oil is consolidating its role as the cost-efficient substitute for premium extra virgin grades in mass-market Indian kitchens. Oleev leverages its integrated crushing and refining infrastructure to control input costs across the value chain. Bertolli sustains brand recognition among urban retail consumers through sustained Mediterranean-origin positioning. Deoleo competes aggressively on imported Spanish and Italian stock availability, anchoring its distribution through modern trade channels in Delhi-NCR and Mumbai.
Olive oil comprises lipids extracted from Olea europaea fruit, with extra virgin grades requiring cold-press extraction below 27 degrees Celsius and free acidity below 0.8 percent for commercial grading in India. The product serves primarily as a cooking medium and cosmetic base, with food industry procurement expanding for bakery and packaged snack applications. Extra virgin olive oil commands the premium tier in retail pricing, while refined and blended variants capture volume growth through affordability-driven household penetration. Food industry buyers increasingly specify bulk container procurement, diverging from the bottle-centric patterns that still dominate supermarket shelves.
FSSAI mandates nutritional labeling and import clearance protocols that directly shape product entry timelines for Spanish and Italian suppliers. BIS certification requirements for edible oils, combined with DGFT's import tariff structures on crude versus refined olive oil, influence domestic blending economics and local crushing investment decisions. Stakeholders must monitor how evolving PLI scheme incentives for food processing infrastructure could alter the cost structure of domestic bottling operations relative to direct import models.
Market Dynamics
FSSAI's tightening import clearance protocols and nutritional labeling mandates are compressing entry timelines for Mediterranean suppliers while domestic bottlers exploit PLI scheme incentives to capture margin from integrated crushing operations.
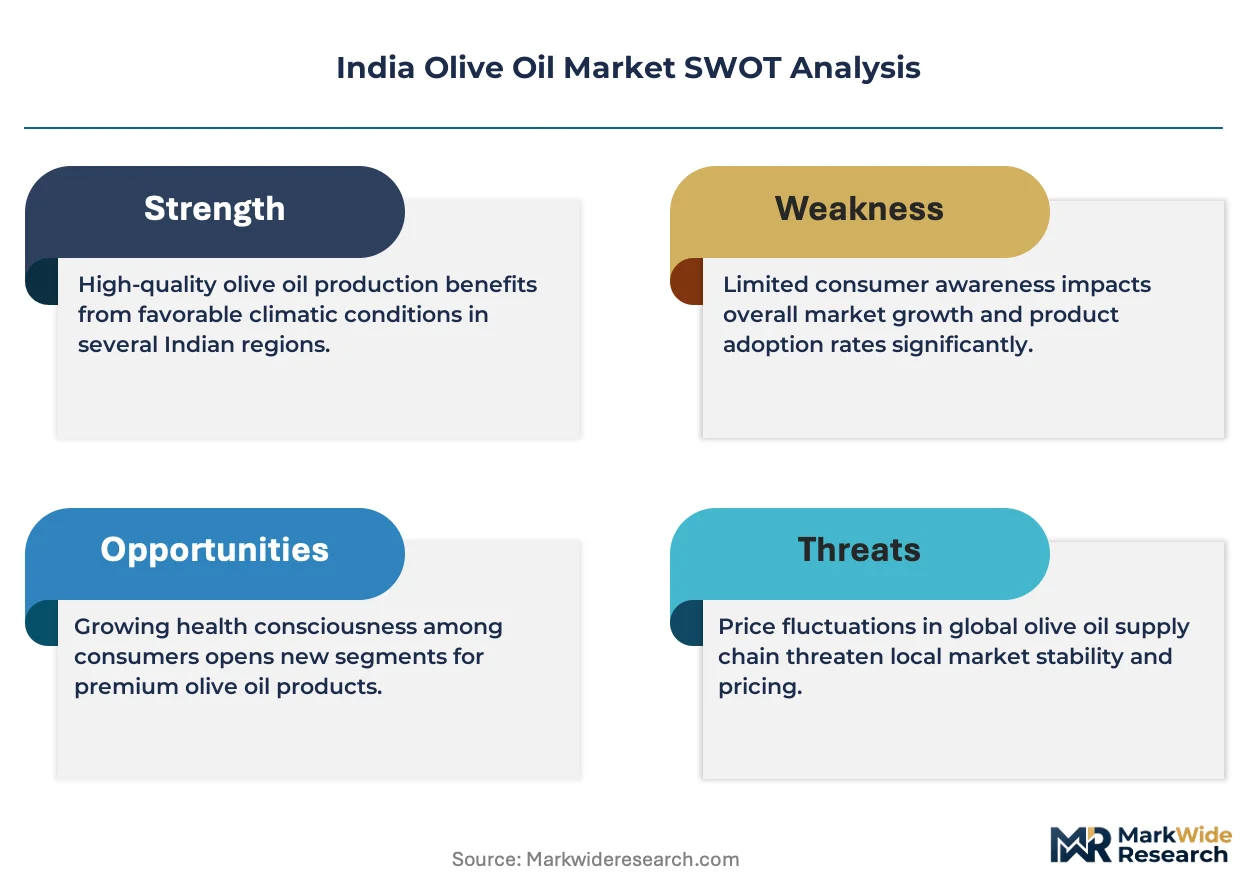
Growth Catalysts
- PLI scheme incentives:Food processing infrastructure subsidies are lowering capital barriers for domestic crushing and refining investments in Maharashtra and Karnataka.
- Urban health-conscious clusters:Mumbai and Bangalore households are substituting mustard and sunflower oils with extra virgin grades for daily cooking applications.
- Modern retail penetration:Supermarket and hypermarket expansion in Delhi-NCR is creating dedicated shelf space for imported Spanish and Italian stock.
Market Restraints
- DGFT tariff asymmetry:Higher duties on refined versus crude olive oil imports are distorting domestic blending economics and favoring direct-to-bottle models.
- Input cost volatility:Euro-rupee exchange rate fluctuations and Mediterranean harvest variability are compressing margins for importers locked into annual procurement contracts.
- Mustard oil substitution threat:Traditional edible oils retain price-performance advantages in mass-market segments and rural distribution networks.
Strategic Opportunities
- Bulk container procurement:Food industry buyers specifying tanker-load purchases for bakery and packaged snack applications are bypassing bottle-centric retail markups.
- BIS certification pathways:Streamlined domestic grading standards are enabling local bottlers to position refined variants against imported extra virgin premiums.
- Karnataka underpenetration:Bangalore's health-conscious consumer base remains underserved relative to Mumbai despite comparable disposable income profiles.
Industry Challenges
- Cold-chain integrity gaps:Temperature-controlled logistics for extra virgin grades degrade during last-mile distribution to tier-two cities.
- FSSAI compliance timelines:Import clearance documentation and nutritional label verification are extending product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Olive Oil Market |
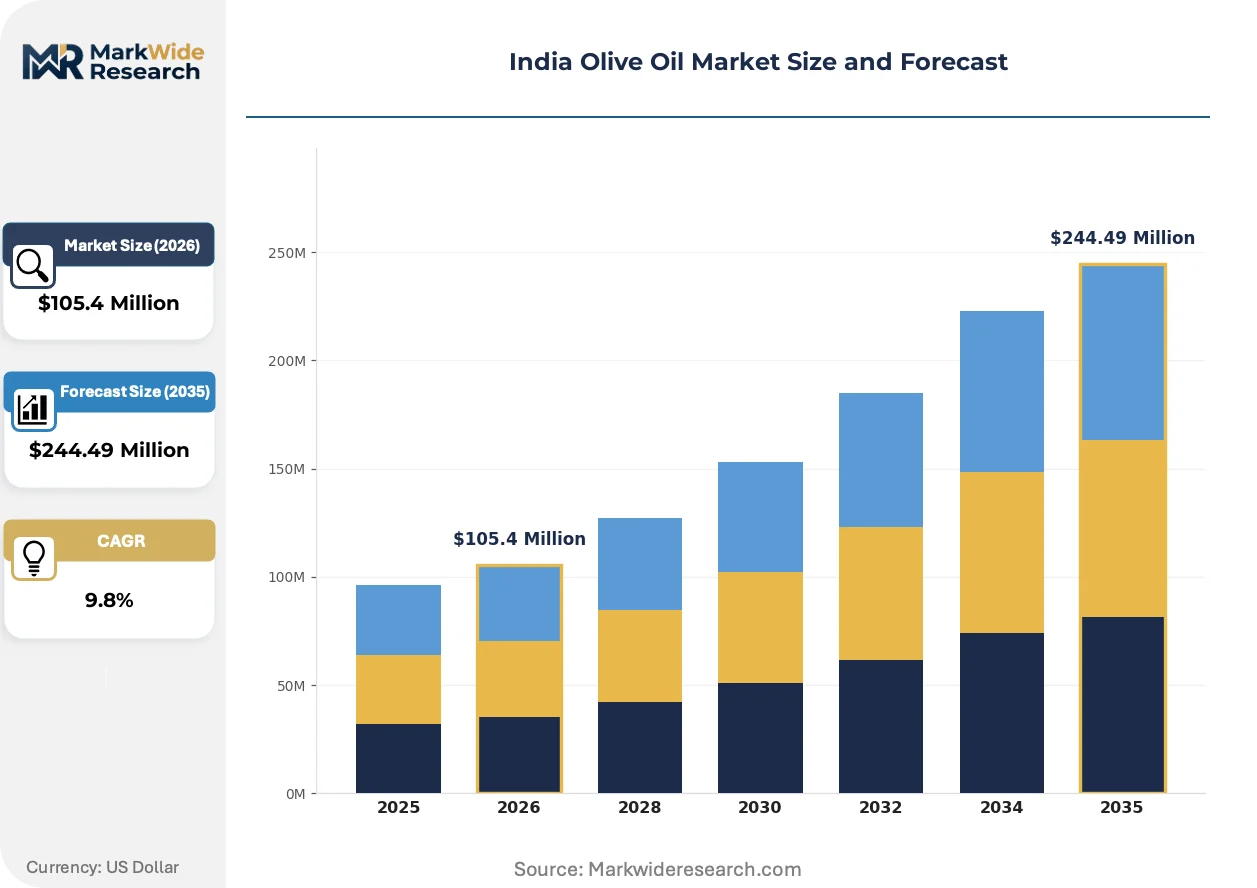
| Market Size in 2026 | $105.4 Million |
| Market Size in 2035 | $244.49 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extra Virgin, Pure, Refined, Blended End User: Food Industry, Retail Consumers, Restaurants, Exporters Packaging Type: Bottles, Cans, Pouches, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Oleev, Bertolli, Deoleo, Jovial Foods, Shakti Apifoods, Borges International Group, Figaro Olive Oil, Monini, Rafael Salgado, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Olive Oil Market Trends and Innovations
Cold-press extraction protocols, regulatory digitization, and procurement model evolution are compressing traditional supply hierarchies while creating new entry points for domestic value capture.
Mechanical cold-press systems operating below 27 degrees Celsius are modularizing quality control across small-scale crushing installations. Domestic bottlers in Maharashtra are adopting these units to bypass Mediterranean bulk import dependencies. The technology is modularizing input sourcing by enabling region-specific olive cultivation trials in Karnataka and Himachal Pradesh.
FSSAI's digitized import clearance portal is compressing documentation verification cycles for Spanish and Italian suppliers. The framework mandates real-time nutritional labeling uploads before customs release. Delhi-NCR distributors are responding by pre-positioning bonded warehouse inventory to buffer regulatory delays.
Food manufacturers are consolidating annual olive oil procurement into direct bulk contracts with crushing cooperatives, bypassing layered import-agent-distributor structures. Bakery and packaged snack producers in Mumbai are leading this consolidation. The shift is most visible in Maharashtra where industrial buyers command tanker-load minimums that exclude traditional retail packagers.
India Olive Oil Market Segmentation
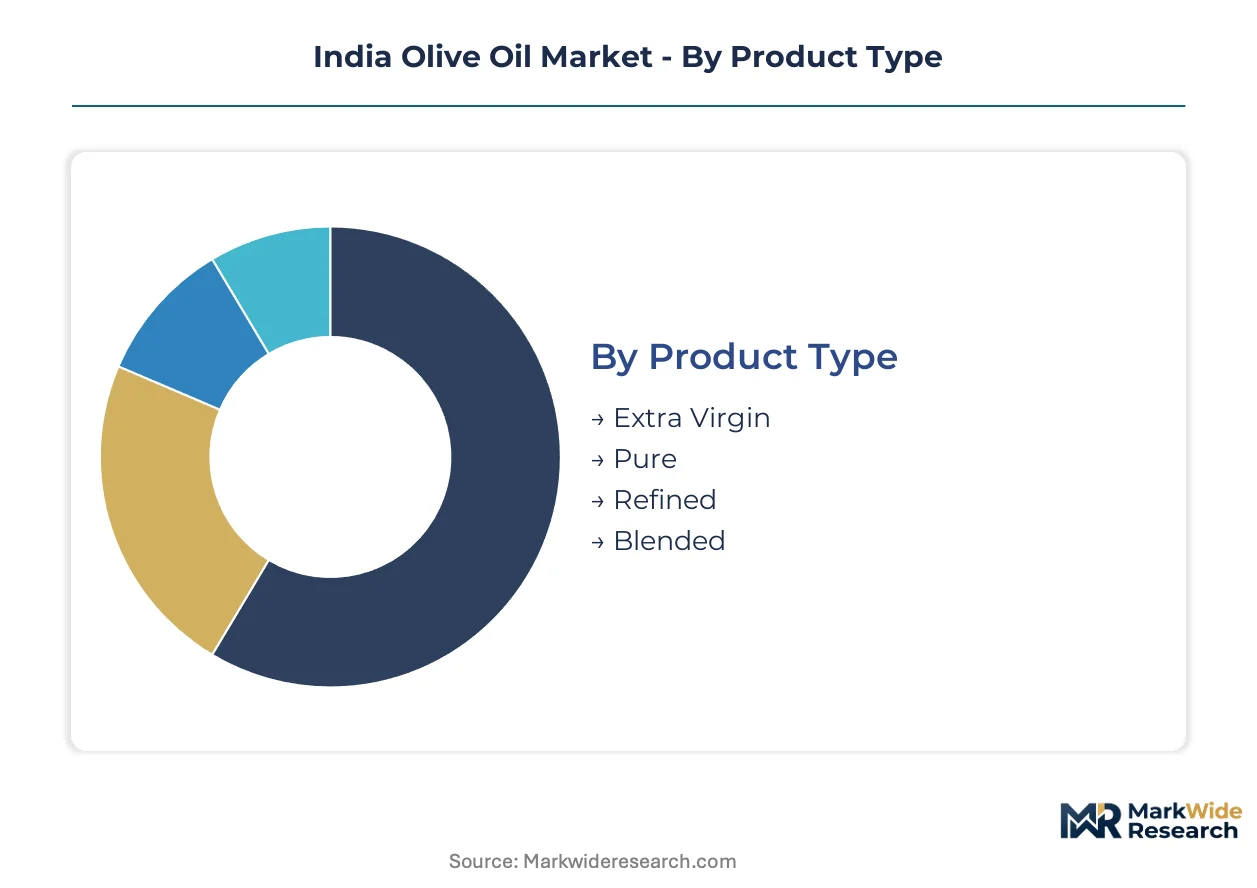
Olive oil purchasing in India splits across quality grades, end-use applications, and channel formats that reflect divergent consumer sophistication levels. Understanding these fault lines exposes where substitution economics favor refined variants over extra virgin premiums, and where bulk procurement is displacing bottle-centric retail.
Product Type:
Upgrade cycles from traditional edible oils drive differential adoption across quality tiers, with cold-press specifications separating premium positioning from mass-market penetration.
- Extra Virgin:Cold-press extraction below 27 degrees Celsius preserves polyphenol content and maintains free acidity under 0.8 percent per FSSAI grading. Mumbai and Bangalore households are substituting this grade for daily tadka and shallow frying despite price premiums over mustard oil.
- Refined:Chemical neutralization and deodorization strip flavor compounds but extend smoke points for high-heat Indian cooking applications. Karnataka bottlers are capturing margin from domestic refining infrastructure subsidized under PLI scheme incentives.
- Pure:Blends of refined and virgin grades balance cost efficiency with modest flavor retention for mid-tier retail shelves.
- Blended:Formulations incorporating palm or rice bran oils dilute olive content to hit price points competitive with sunflower and groundnut variants in mass-market distribution.
Refined olive oil sits at the top of the volume ranking, with extra virgin climbing the fastest among urban health-conscious clusters.
End User:
Procurement scale and specification stringency separate industrial buyers from fragmented household demand, creating divergent margin structures across the value chain.
- Food Industry:Bakery and packaged snack manufacturers in Maharashtra specify tanker-load procurement with bulk density and acidity certifications. Direct contracts with Spanish cooperatives are bypassing traditional import-agent markups.
- Retail Consumers:Urban households in Delhi-NCR purchase 500ml to 1 liter formats through modern trade channels, with purchase decisions driven by Mediterranean-origin labeling and FSSAI nutritional disclosures.
- Restaurants:Fine-dining establishments in Bangalore specify extra virgin for finishing applications, while casual chains absorb refined grades for frying volumes.
- Exporters:Reprocessing facilities in Gujarat repackage imported bulk stock for Middle Eastern and Southeast Asian markets, leveraging India's tariff preferences under regional trade frameworks.
Food industry procurement dominates absolute volume, with retail consumer segments gaining share fastest through modern retail penetration.
Packaging Type:
Container economics and shelf-life requirements shape channel accessibility, with format selection directly constraining addressable market reach.
- Bottles:Dark glass or PET formats dominate supermarket shelves, with UV protection preserving extra virgin quality during Delhi-NCR summer storage conditions.
- Cans:Metal packaging extends shelf stability for premium variants distributed through specialty stores with slower inventory turns.
- Pouches:Flexible formats reduce unit economics for rural market trials, though FSSAI labeling mandates complicate nutritional disclosure compliance on limited surface area.
- Bulk Containers:Stainless steel tankers and intermediate bulk containers serve food industry procurement with 10,000 liter minimums that exclude retail packagers from industrial supply contracts.
Bottles retain volume leadership in retail channels, with bulk containers expanding most quickly as food manufacturers consolidate direct procurement.
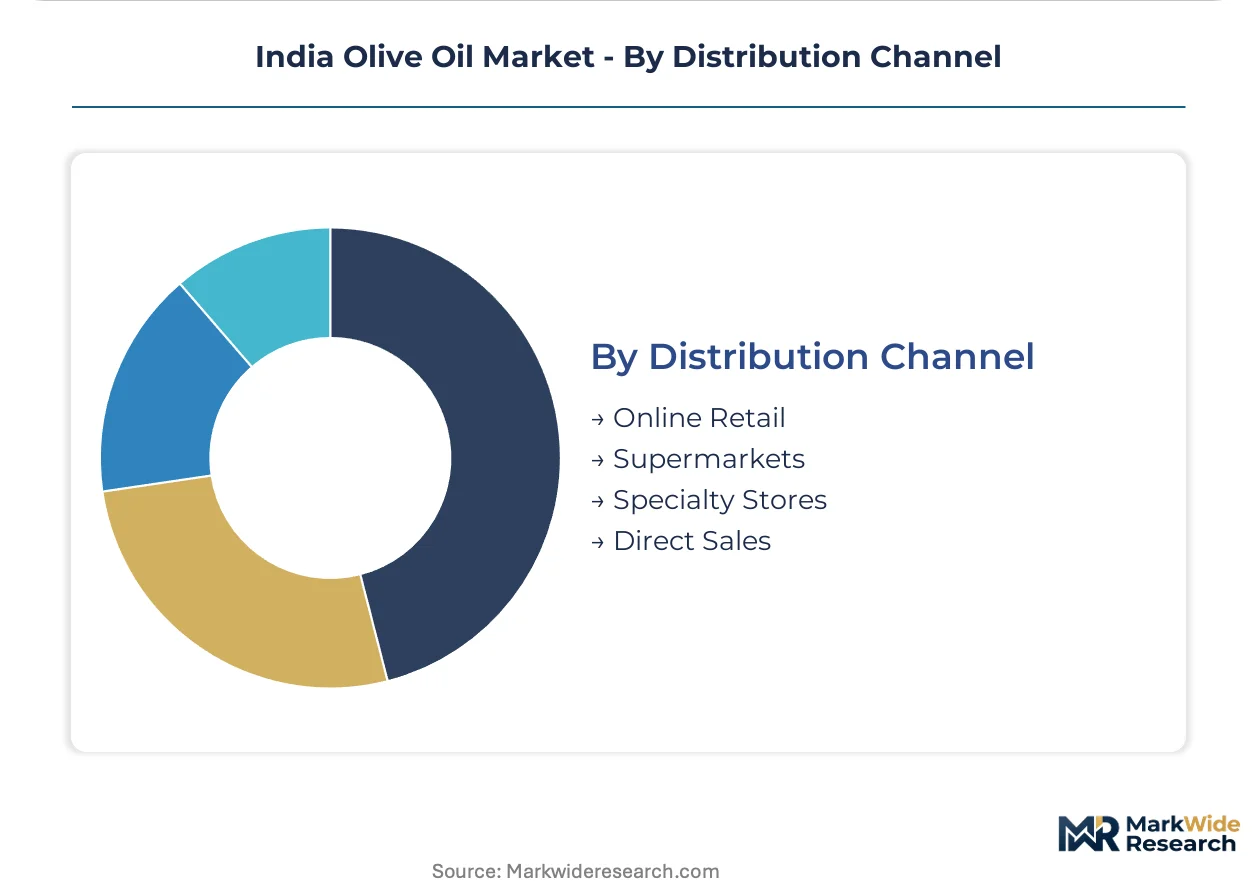
Distribution Channel:
Channel selection determines margin capture versus consumer education investment, with digital platforms eroding traditional specialty store positioning.
- Supermarkets:Hypermarket chains in Mumbai dedicate end-cap displays to imported Spanish and Italian stock, with in-store sampling converting mustard oil households.
- Online Retail:Quick-commerce platforms in Bangalore are compressing delivery timelines for premium grades, though temperature-controlled last-mile logistics remain inconsistent.
- Specialty Stores:Gourmet retailers in Delhi-NCR curate small-batch Mediterranean imports with harvest-date transparency, targeting gift-purchase occasions.
- Direct Sales:Corporate wellness programs and institutional catering contracts bypass retail markups through annual volume commitments.
Supermarkets anchor current volume distribution, with online retail channels showing steepest expansion trajectory among urban millennials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors olive oil consumption through Mumbai's modern retail density and integrated crushing infrastructure. Karnataka and Delhi-NCR follow as secondary demand clusters. Regional variation reflects disposable income gradients, health-conscious urbanization, and FSSAI regulatory enforcement intensity.
Maharashtra
Mumbai households substitute extra virgin grades for traditional tadka applications, driving premium-tier volume. PLI scheme subsidies incentivize domestic crushing investments in Nashik and Pune corridors. Food manufacturers in Thane-Bhiwandi industrial belts specify tanker-load procurement with Spanish cooperatives.
Karnataka
Bangalore's health-conscious consumer base exhibits underpenetration relative to comparable income profiles in western India. BIS certification pathways enable local bottlers to position refined variants against import premiums. Modern retail expansion in Whitefield and Electronic City corridors creates dedicated shelf space for Mediterranean-origin stock.
Delhi-NCR
Urban households purchase 500ml to 1 liter formats through hypermarket channels, with Mediterranean-origin labeling driving purchase decisions. FSSAI's digitized import clearance portal compresses documentation cycles for Spanish and Italian suppliers. Gurugram-based distributors pre-position bonded warehouse inventory to buffer regulatory delays.
Gujarat
Reprocessing facilities in Ahmedabad and Surat repackage imported bulk stock for Middle Eastern and Southeast Asian export markets. DGFT tariff structures on crude versus refined olive oil influence blending economics for domestic bottlers. Mundra port infrastructure facilitates containerized Mediterranean imports with reduced inland logistics costs.
Himachal Pradesh
Region-specific olive cultivation trials in Kangra and Mandi districts test domestic input sourcing viability. Cold-press extraction systems below 27 degrees Celsius modularize quality control for small-scale installations. State horticulture department programs provide technical assistance for Mediterranean cultivar adaptation.
India Olive Oil Market Competitive Landscape
Global majors compete with regional champions across import-dependent supply chains and domestic crushing infrastructure. The vendor base stratifies into three tiers: Mediterranean-origin importers with brand recognition, integrated domestic bottlers controlling refining economics, and regional packagers serving price-sensitive mass markets. Dominant competitive moves include backward integration into crushing operations and direct procurement contracts with Spanish and Italian cooperatives bypassing layered agent structures.
Within the integrated domestic tier, Oleev leverages captive crushing and refining infrastructure to control input costs across Maharashtra and Karnataka. Among Mediterranean-origin importers, Deoleo and Bertolli occupy positions anchored through modern trade channel penetration in Delhi-NCR and Mumbai. These three exemplify the structural divide between import-dependent brand positioning and domestic value-chain capture.
| Leading Market Players |
|---|
| Oleev |
| Bertolli |
| Deoleo |
| Jovial Foods |
| Shakti Apifoods |
| Borges International Group |
| Figaro Olive Oil |
| Monini |
| Rafael Salgado |
| Others |
Pricing and Supply Chain Analysis
Family-owned Mediterranean cooperatives anchor upstream supply, compressing margin capture for Indian bottlers who must absorb euro-rupee volatility while FSSAI compliance costs add fixed overhead to landed stock. This ownership pattern concentrates pricing power with Spanish and Italian crush operators, forcing domestic players to differentiate through BIS-certified refining economics rather than origin premiums.
Pricing Analysis
Euro-denominated input costs pass through to Indian retail shelves with 4-6 month lag structures, amplifying margin compression during currency depreciation cycles. Three-tier pricing structure across extra virgin, refined, and blended grades separates cold-press certification premiums from mass-market affordability tiers. Pricing pressure stems from mustard oil substitution elasticity in rural distribution networks. Food industry buyers exhibit lowest price sensitivity due to tanker-load procurement scale, while household segments in tier-two cities resist premiums above sunflower oil parity.
Supply Chain Analysis
Single-source vulnerability sits with Andalusian and Apulian crushing cooperatives that supply 80% of Indian import volume. Mediterranean harvest variability and Euro-rupee exchange rate fluctuations compound input cost unpredictability. DGFT tariff asymmetry between crude and refined grades distorts domestic blending decisions. Distribution runs through Mundra port container terminals into Maharashtra and Karnataka bottling corridors, with bonded warehouse pre-positioning in Delhi-NCR buffering FSSAI clearance delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI operates as a regulatory compounder, tightening import clearance protocols that extend product launch cycles and consolidate advantage among compliant incumbents with pre-positioned bonded inventory.
For Market Incumbents: Deepen backward integration into crushing infrastructure through PLI-subsidized Maharashtra investments, securing captive supply against Mediterranean price volatility. Reinforce channel control in modern retail through exclusive end-cap arrangements with hypermarket chains. Counter Bertolli and Deoleo origin positioning with BIS-certified "Indian refined" tier marketing. For New Entrants and Emerging Players: Bangalore's health-conscious households represent the most penetrable buyer archetype, with disposable income parity to Mumbai but 40% lower olive oil penetration. White-space targets include direct-to-corporate wellness contracts bypassing retail markups, and Karnataka-based cold-press installations sourcing from Himachal Pradesh cultivation trials. Go-to-market angle: quick-commerce partnerships with temperature-controlled last-mile guarantees. For Investors and Strategic Acquirers: Integrated food conglomerates with existing edible oil portfolios are the most active acquirer in this space, seeking PLI-eligible crushing assets to complete value-chain coverage. Five-to-ten year viability hinges on domestic olive cultivation scaling beyond trial phases. Acquisition target archetype: Maharashtra bottlers with FSSAI pre-clearance infrastructure and modern trade shelf access. Signal to watch: DGFT tariff rebalancing toward refined imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing | PLI-subsidized Maharashtra installations reduce euro-denominated input exposure. |
| BIS Certification Investment | Domestic grading standards enable refined variant positioning against import premiums. |
| Bulk Container Procurement | Tanker-load contracts with Spanish cooperatives bypass layered import-agent markups. |
| Quick-Commerce Partnership | Temperature-controlled last-mile logistics capture Bangalore millennial demand. |
| Himachal Cultivation Trials | Domestic olive sourcing modularizes supply risk from Mediterranean harvest cycles. |
Research Methodology
Direct dialogue with FSSAI compliance officers, modern trade category managers, Maharashtra crushing plant operators, and Spanish export cooperative representatives grounded qualitative findings. Secondary validation drew from DGFT import manifest records, FSSAI nutritional labeling databases, PLI scheme disbursement filings, and BIS certification registries. Bottom-up volume estimates from state-level consumption patterns triangulated against top-down import value flows.
Segment-level projections across extra virgin, refined, and blended grades, disaggregated by food industry, retail consumer, restaurant, and exporter end-use, populated the analytical framework across the projection horizon. CAGRs derived from trend extrapolation of urban household substitution rates and industrial procurement consolidation patterns. Forecast inputs incorporated euro-rupee volatility bands and FSSAI digitization rollout timelines.
Underlying measurement precision varies by segment; Maharashtra and Karnataka consumption data carry tighter precision than Himachal Pradesh cultivation trial outcomes. Forecasts reflect assumptions around PLI scheme continuity and DGFT tariff stability. Olive harvest variability and regulatory digitization pace present revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Carotenes Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Ice Cream Ingredients Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
China Soy Protein Market
Ingredients
Rose Hips Extract Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Stock Cubes Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Cottonseed Oil Market
Ingredients
Resistant Starch Market