
 Europe Amino Acid Market | 2026-2036
Europe Amino Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Amino Acid Market Analysis
Germany's expanding biotech fermentation corridor is reshaping supply dynamics for specialty amino acids across the continent. Evonik Industries AG leverages its backward integration into precursor chemicals to sustain margin resilience in L-lysine and L-threonine. Adisseo anchors its European position through dedicated production platforms serving the animal nutrition sector. DSM competes by specializing in pharmaceutical-grade amino acids for parenteral nutrition applications.
Amino acids are organic compounds containing amine and carboxyl functional groups that serve as protein building blocks, typically produced through microbial fermentation or enzymatic synthesis with purity grades ranging from feed-grade to USP/EP pharmaceutical standards. Their primary industrial purpose spans protein synthesis in animal metabolism, therapeutic nutrition in clinical settings, and muscle recovery formulations in human supplements. L-Glutamine and L-Arginine dominate the product type landscape, with the former commanding established volume in sports nutrition and the latter gaining traction in pharmaceutical applications for wound healing and immune support. Animal feed remains the largest application segment by tonnage, though dietary supplements and nutraceuticals capture disproportionate value per kilogram due to certification requirements and dosage precision.
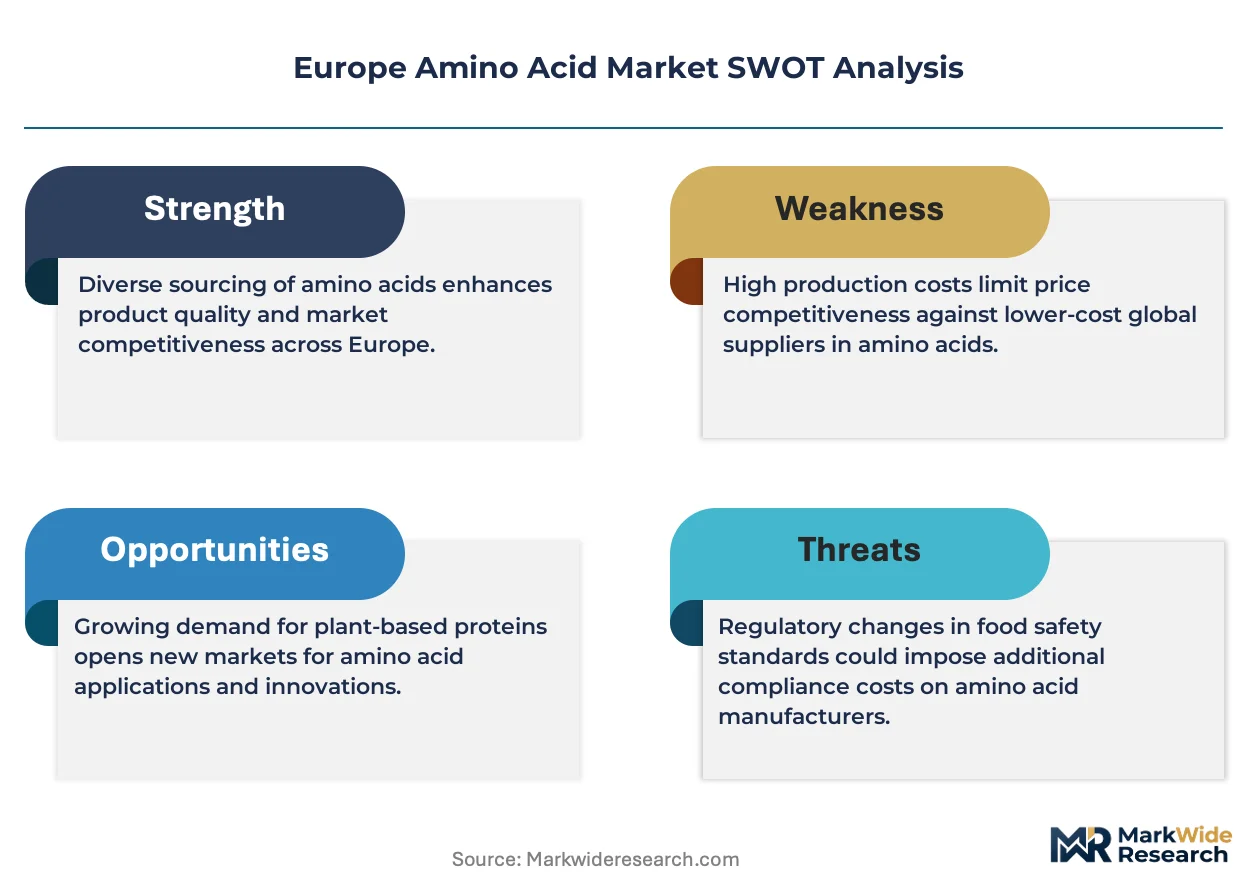
EMA guidelines on pharmaceutical-grade amino acid purity, REACH registration mandates for industrial chemical imports, and the EU Green Deal's carbon border adjustment mechanism collectively elevate compliance costs while favoring domestic fermentation capacity over imports. The F-Gas Regulation specifically targets refrigerant gases used in downstream processing, pushing manufacturers toward ammonia-based or absorption cooling retrofits. Stakeholders must monitor regulatory divergence between EU member states on novel food approvals for emerging amino acid derivatives, as national interpretations of EFSA safety assessments create uneven market access conditions.
Market Dynamics
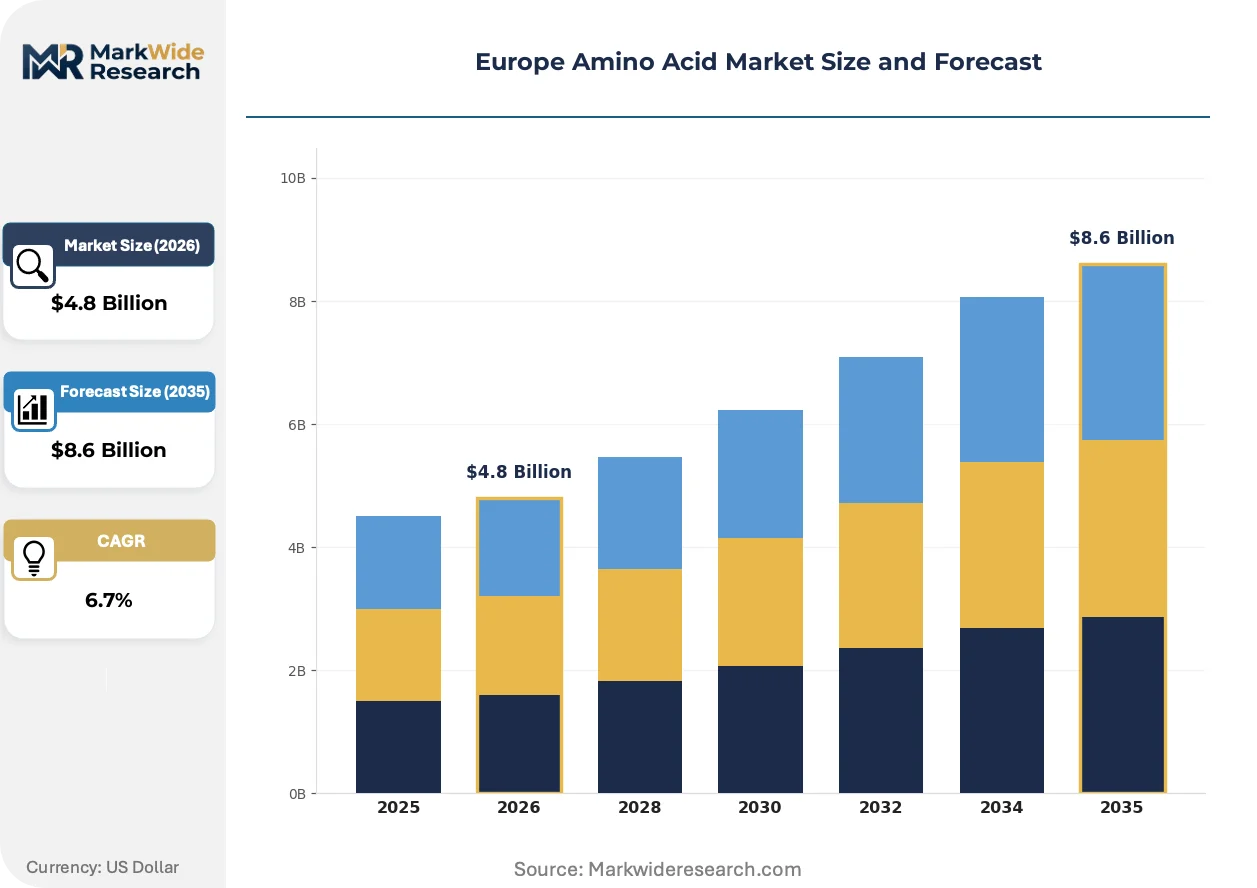
Fermentation technology maturation and the EU Green Deal's carbon border adjustment mechanism are compressing cost differentials between domestic European production and Asian imports, forcing capacity reconfiguration across the continent.
Growth Catalysts
- EU Green Deal carbon border adjustments:The CBAM framework penalizes embedded carbon in imported amino acids, tilting procurement toward EU-based fermentation facilities with verified low-carbon processes.
- Animal nutrition precision feeding:Livestock producers in Denmark and the Netherlands deploy amino acid balancing to reduce crude protein in feed formulations, cutting nitrogen excretion while maintaining growth rates.
- Biotech corridor expansion:Germany's Rhineland-Palatinate and Saxony-Anhalt regions aggregate strain development, contract fermentation, and downstream purification within 150-kilometer logistics clusters.
Market Restraints
- Natural gas price volatility:Steam and electricity costs for fermentation sterilization and lyophilization swing with TTF benchmark movements, compressing margins for continuous-process operators.
- Chinese lysine oversupply:State-subsidized capacity expansions in Heilongjiang and Shandong provinces export below European production costs, limiting price recovery windows.
- REACH registration bottlenecks:Novel amino acid derivatives face 18-24 month dossier review timelines at ECHA, freezing pipeline commercialization for mid-tier specialty producers.
Strategic Opportunities
- Poland and Romania greenfield sites:Lower labor costs and proximity to Black Sea grain corridors enable integrated feed amino acid production serving Eastern European livestock consolidation.
- Cell-culture media grade expansion:Biopharma CDMOs in Belgium and Switzerland source pharmaceutical-grade L-glutamine and L-arginine for monoclonal antibody production, commanding 8-12x feed-grade pricing.
- F-Gas Regulation retrofit incentives:Manufacturers replacing HFC-based cooling with ammonia absorption systems qualify for national decarbonization grants in France, Germany, and Italy.
Industry Challenges
- Strain engineering talent scarcity:CRISPR-enabled metabolic pathway optimization requires molecular biologists with industrial fermentation experience, a skill set concentrated at TU Delft, ETH Zurich, and TU Munich.
- Pharmaceutical-grade certification timelines:USP/EP monograph compliance for parenteral amino acids demands 24-36 month validation cycles including viral clearance studies and endotoxin control documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Amino Acid Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Arginine, L-Tyrosine, L-Leucine, L-Glutamine Application: Animal Feed, Dietary Supplements, Nutraceuticals, Pharmaceuticals End User: Agriculture, Healthcare, Sports Nutrition, Food Industry Form: Powder, Liquid, Granules, Tablet |
| Companies Covered | Adisseo, Evonik Industries AG, Ajinomoto, Archer Daniels Midland, IFF (Danisco Animal Nutrition), Kemin Industries, DSM, Sumitomo Chemical, Merck KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Amino Acid Market Emerging Trajectories
Continuous processing and digital bioprocess control are displacing batch fermentation as the dominant production paradigm, while regulatory carbon accounting and buyer sustainability auditing reshape supplier qualification criteria.
Precision fermentation platforms using engineered Corynebacterium glutamicum strains is hybridizing traditional amino acid manufacturing with synthetic biology toolsets. Contract manufacturers in Belgium and Germany adopt these systems to produce specialty amino acids at 30,000-liter single-use bioreactor scale. The technology is hybridizing product portfolios, allowing former commodity producers to enter pharmaceutical-grade and cosmetic-active segments without dedicated stainless-steel infrastructure.
The F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants forces cooling system retrofits at downstream crystallization and drying facilities. Manufacturers face capital allocation decisions between ammonia-based absorption cooling and transcritical CO2 systems, with payback periods sensitive to carbon credit valuations. Animal feed-grade producers with thin margins delay compliance investments, concentrating regulatory risk in the volume segment.
Livestock integrators in France and Spain consolidate amino acid procurement through nutrition service companies rather than direct chemical supplier relationships. These intermediaries bundle amino acid premixes with veterinary services and feed formulation software, capturing margin that previously accrued to basic manufacturers. The shift is most advanced in poultry production, where vertical integration between hatcheries and processing plants enables closed-loop nutrient management contracts.
Europe Amino Acid Market Segmentation
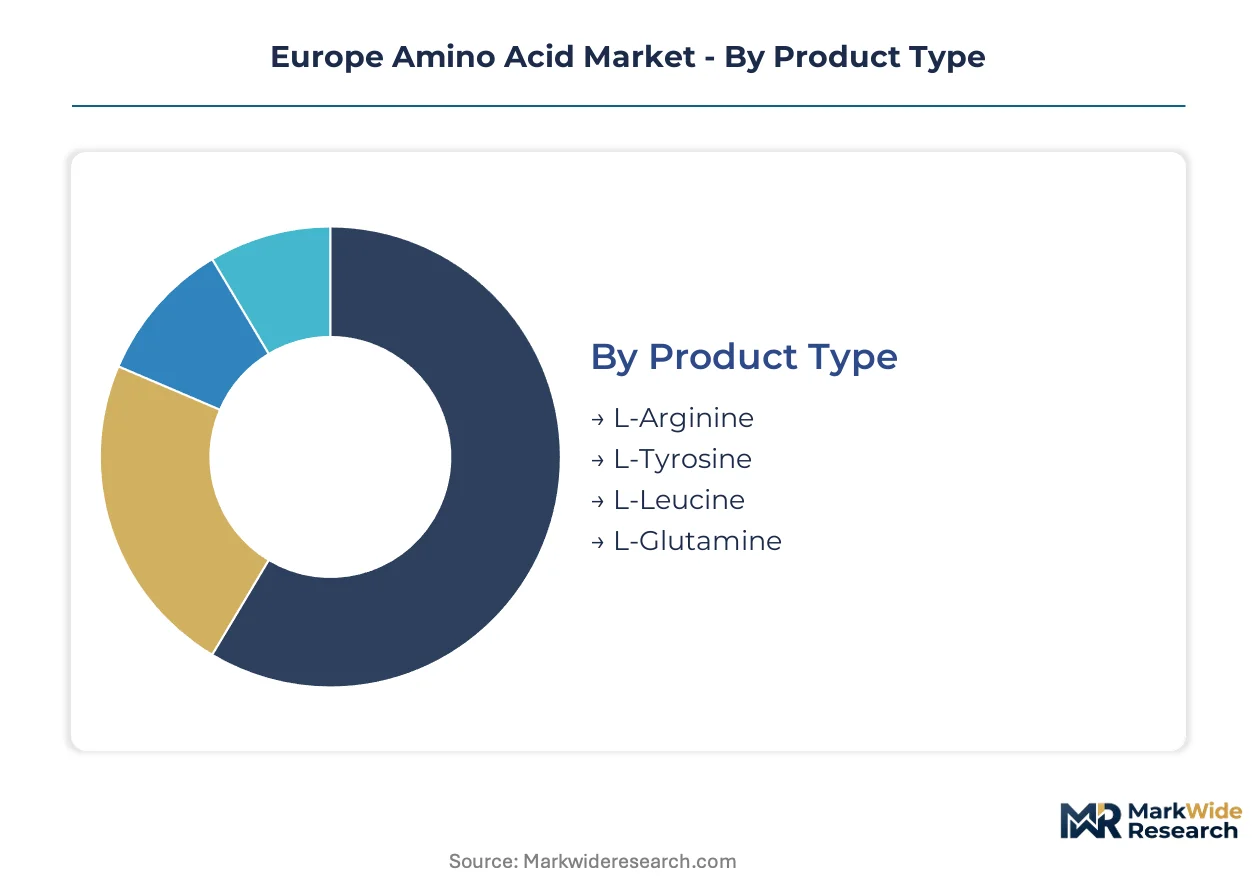
European amino acid procurement patterns diverge sharply across purity grades and end-use specifications. Feed-grade tonnage concentrates in agricultural supply chains while pharmaceutical and nutraceutical segments extract disproportionate value through certification requirements.
Product Type:
Cost tier differentiation separates commodity fermentation outputs from specialty amino acids commanding formulation premiums.
- L-Glutamine:Crystalline amino acid produced via Corynebacterium glutamicum fermentation with USP-grade specifications for parenteral nutrition. Demand concentrates in Belgian and Swiss biopharma CDMOs producing monoclonal antibody cell-culture media, driven by EMA purity guidelines tightening endotoxin thresholds.
- L-Arginine:Semi-essential amino acid synthesized through arginine biosynthesis pathway engineering with higher nitrogen content than glutamine analogs. German sports nutrition formulators in Bavaria and North Rhine-Westphalia drive powder-grade procurement, constrained by REACH registration requirements for novel derivatives.
- L-Leucine:Branched-chain amino acid critical for muscle protein synthesis signaling.
- L-Tyrosine:Precursor for catecholamine neurotransmitters used in cognitive health formulations.
L-Glutamine holds installed capacity. L-Arginine is rotating up the share rankings.
Application:
Volume distribution across end-use segments reflects divergent margin structures and regulatory intensity.
- Animal Feed:Bulk lysine, methionine and threonine formulations integrated into precision feeding programs reducing crude protein content. Dutch and Danish livestock integrators deploy amino acid balancing to cut nitrogen excretion while maintaining growth rates, aligning with EU Green Deal agricultural emissions targets.
- Pharmaceuticals:USP/EP monograph-grade amino acids for parenteral nutrition solutions and infusion therapies. Italian and Spanish hospital pharmacies source L-glutamine and L-arginine for critical care applications, facing 24-36 month validation cycles for viral clearance documentation.
- Dietary Supplements:Sports nutrition and wellness formulations in powder and capsule formats.
- Nutraceuticals:Functional food and beverage fortification targeting immune and cognitive health.
Animal Feed holds installed capacity. Pharmaceuticals is rotating up the share rankings.
End User:
Customer type specialization determines specification requirements and procurement relationship structures.
- Agriculture:Livestock producers and feed compounders purchasing feed-grade amino acids in bulk tonnage. Polish and Romanian pork and poultry operations source through nutrition service companies bundling premixes with veterinary services, capturing margin that previously accrued to basic manufacturers.
- Healthcare:Hospital pharmacies, clinical nutrition departments and homecare providers sourcing pharmaceutical-grade materials. French and German parenteral nutrition formulators demand endotoxin-controlled L-glutamine with batch-specific CoA documentation.
- Sports Nutrition:Powder and ready-to-drink brands targeting athletic performance and recovery.
- Food Industry:Processed food manufacturers deploying amino acids for flavor enhancement and protein fortification.
Agriculture holds installed capacity. Healthcare is rotating up the share rankings.
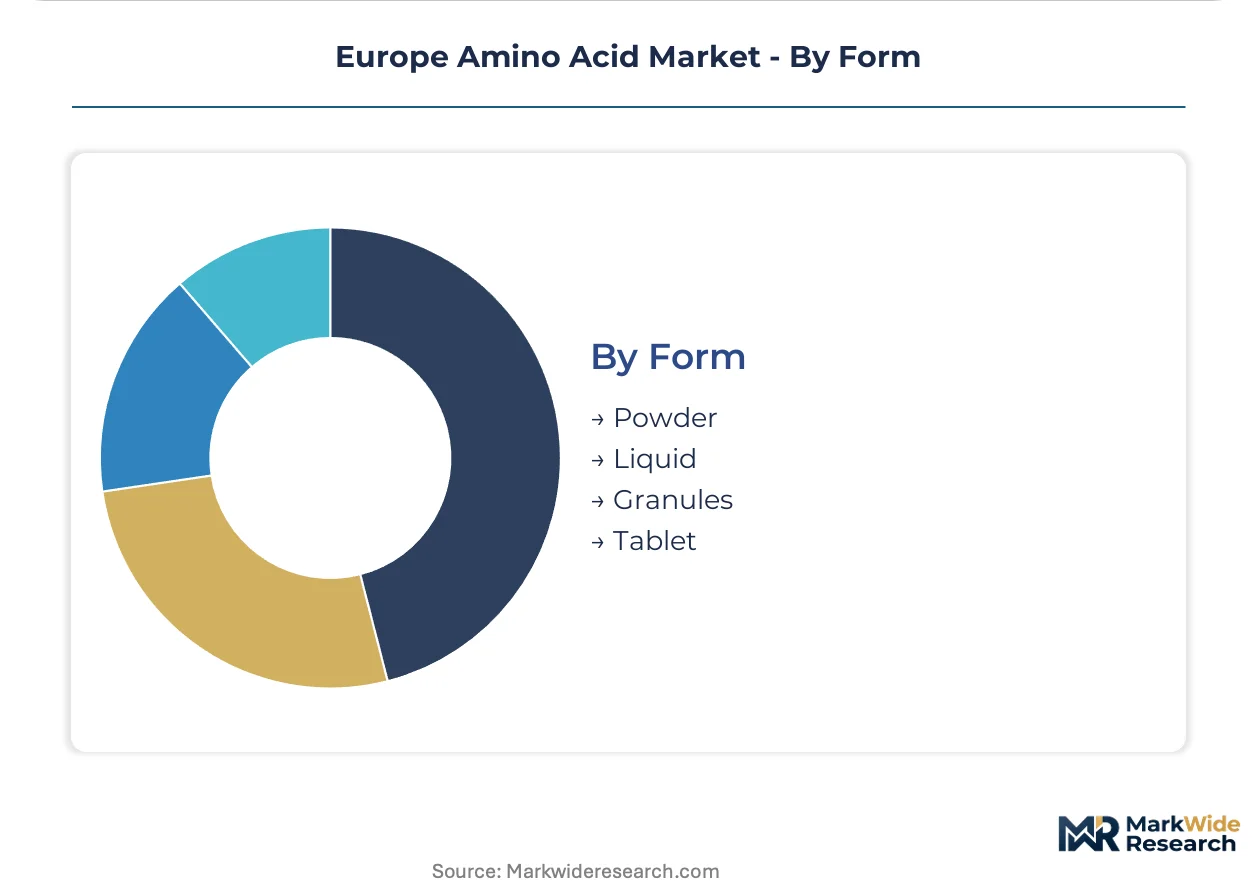
Form:
Physical presentation formats align with downstream processing requirements and dosing precision needs.
- Powder:Crystalline or spray-dried amino acids with particle size distribution optimized for tableting or direct compression. German and Swiss contract manufacturers prefer powder formats for pharmaceutical-grade L-glutamine destined for parenteral nutrition, leveraging lyophilization capacity in Baden-Württemberg.
- Liquid:Aqueous solutions or suspensions for injection and infusion applications. Belgian biopharma CDMOs source liquid L-arginine for cell-culture media, constrained by F-Gas Regulation cooling requirements for cold-chain stability.
- Granules:Agglomerated particles for controlled-release feed applications.
- Tablet:Compressed solid dosage forms for dietary supplement retail channels.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA guidelines on pharmaceutical-grade amino acid purity anchor demand concentration in Germany, where Rhineland-Palatinate and Saxony-Anhalt fermentation clusters supply continental markets. The EU Green Deal's carbon border adjustment mechanism and F-Gas Regulation cooling requirements reshape capacity location decisions across member states.
Germany
Pharmaceutical-grade L-glutamine demand from Belgian and Swiss biopharma CDMOs drives Baden-Württemberg lyophilization capacity expansion. The F-Gas Regulation forces ammonia absorption cooling retrofits at downstream crystallization facilities. Evonik Industries AG leverages backward integration into precursor chemicals at Marl Chemical Park to sustain margin resilience in L-lysine and L-threonine.
Netherlands
Livestock integrators deploy amino acid balancing to cut nitrogen excretion while maintaining growth rates in precision feeding programs. EU Green Deal agricultural emissions targets accelerate crude protein reduction in swine and poultry formulations. Dutch nutrition service companies bundle amino acid premixes with veterinary services, capturing margin from basic manufacturers.
Belgium
Biopharma CDMOs source pharmaceutical-grade L-glutamine and L-arginine for monoclonal antibody cell-culture media production. EMA purity guidelines tighten endotoxin thresholds for parenteral nutrition applications. Wallonia-based contract manufacturers adopt 30,000-liter single-use bioreactor systems for specialty amino acid production.
France
Poultry production vertical integration between hatcheries and processing plants enables closed-loop nutrient management contracts. National decarbonization grants support manufacturers replacing HFC-based cooling with ammonia absorption systems under F-Gas Regulation compliance. French hospital pharmacies source endotoxin-controlled L-glutamine for critical care parenteral nutrition.
Poland
Pork and poultry operations source feed-grade amino acids through nutrition service intermediaries bundling premixes with veterinary services. Lower labor costs and Black Sea grain corridor proximity attract greenfield integrated feed amino acid production capacity. Polish livestock consolidation creates procurement scale for regional fermentation supply.
Europe Amino Acid Market Vendor Landscape
Integrated chemical conglomerates and specialty nutrition specialists split the market into distinct capability tiers. Three to five multinational groups control pharmaceutical-grade certification infrastructure while mid-tier players concentrate in feed-grade commodity fermentation. Strategic archetypes include backward-integrated precursors-to-amino-acid producers, precision fermentation platform operators, and nutrition service intermediaries bundling formulation with distribution. Dominant competitive moves encompass fermentation technology licensing partnerships and geographic capacity reconfiguration toward Eastern European greenfield sites.
Within the integrated chemical tier, Evonik Industries AG and DSM exemplify divergent specialization strategies. Evonik anchors its position through captive precursor chemical production supporting L-lysine and L-threonine margin structures. DSM occupies a position emphasizing pharmaceutical-grade monograph compliance for parenteral nutrition applications. Adisseo represents the dedicated animal nutrition platform archetype, with production infrastructure purpose-built for feed-grade supply relationships.
| Leading Market Players |
|---|
| Adisseo |
| Evonik Industries AG |
| Ajinomoto |
| Archer Daniels Midland |
| IFF (Danisco Animal Nutrition) |
| Kemin Industries |
| DSM |
| Sumitomo Chemical |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese lysine fermentation is compressing European spot markets and forcing domestic producers toward contract-based offtake structures with integrated livestock operators. This utilization imbalance simultaneously erodes margin buffers for commodity-grade suppliers and reinforces pricing power for pharmaceutical-certified producers with locked-in biopharma CDMO relationships.
Pricing Analysis
Geographic price spreads between Rhineland-Palatinate fermentation output and Black Sea corridor imports are narrowing as carbon border adjustments offset Asian labor cost advantages. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and technical-grade certifications anchors the dominant model, with endotoxin-controlled L-glutamine commanding substantial premiums over commodity lysine. Cost compression in feed-grade tonnage is intensifying because state-subsidized Chinese capacity exports below European production economics. Livestock integrators in Poland and Romania exhibit highest price sensitivity, while Belgian biopharma CDMOs demonstrate lowest sensitivity due to regulatory qualification switching costs.
Supply Chain Analysis
Export-control regimes on CRISPR-enabled strain engineering platforms limit technology transfer from TU Delft and ETH Zurich to non-EU contract manufacturers, constraining capacity replication outside the continent. Supply concentrates in Germany, Belgium, and the Netherlands, with Baden-Württemberg lyophilization capacity and Wallonia single-use bioreactor infrastructure serving as critical nodes. Raw material dependencies include corn-derived glucose for fermentation feedstock, natural gas for sterilization steam, and ammonia-based refrigerants for downstream cooling. Single-source vulnerability in pharmaceutical-grade L-arginine purification creates structural exposure. Distribution runs through nutrition service intermediaries bundling premixes with veterinary services for feed-grade tonnage, while pharmaceutical-grade materials move through qualified CDMO direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where EMA pharmaceutical-grade certification timelines create switching costs that entrench incumbent positions against commodity-grade challengers.
For Market Incumbents: Entrench regulatory moats by accelerating USP/EP monograph compliance investments for parenteral nutrition grades before REACH registration bottlenecks tighten further. Prioritize backward integration into precursor chemicals at Marl Chemical Park and comparable sites to defend margin structures against Chinese lysine oversupply. Channel control through nutrition service intermediaries captures margin migrating from basic manufacturers in Polish and Romanian livestock consolidation zones. For New Entrants and Emerging Players: Establish a beachhead in cell-culture media grade L-glutamine and L-arginine for Belgian and Swiss biopharma CDMOs, where pharmaceutical certification barriers filter out commodity competitors. White-space targets include precision fermentation platforms using engineered Corynebacterium glutamicum strains at 30,000-liter single-use scale, and greenfield integrated feed amino acid production serving Eastern European pork and poultry consolidation. Go-to-market angle should emphasize EMA endotoxin threshold compliance and batch-specific CoA documentation for parenteral nutrition formulators. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because certification infrastructure and validation cycle investments create durable competitive separation between pharmaceutical-grade and commodity-tier returns. Acquisition target archetype: mid-tier specialty producers with pending REACH dossiers for novel amino acid derivatives and established contract fermentation relationships with Wallonia or Rhineland-Palatinate infrastructure. Signal to watch is F-Gas Regulation compliance retrofit completion rates, as delayed capital allocation in feed-grade segments concentrates regulatory risk and creates distressed positioning opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive supply of petrochemical intermediates at Marl Chemical Park sustains margin resilience in L-lysine and L-threonine against Asian import pressure. |
| Pharmaceutical-Grade Certification Investment | USP/EP monograph compliance for parenteral nutrition creates 24-36 month validation barriers that filter commodity competitors from high-value segments. |
| Precision Fermentation Platform Adoption | Engineered Corynebacterium glutamicum strains at 30,000-liter single-use scale enable entry into pharmaceutical-grade and cosmetic-active segments without dedicated stainless-steel infrastructure. |
| F-Gas Regulation Cooling Retrofit | Ammonia absorption system replacement at downstream crystallization facilities qualifies for French, German, and Italian national decarbonization grants while ensuring compliance continuity. |
| Nutrition Service Intermediary Partnership | Bundling amino acid premixes with veterinary services and feed formulation software captures margin migrating from basic manufacturers in vertically integrated poultry production. |
Methodological Framework
Operator-level perspectives from fermentation plant managers, procurement leads at Dutch livestock integrators, pharmaceutical regulatory affairs directors, and biopharma CDMO supply chain heads anchored the qualitative base. Secondary validation drew from EMA guideline documentation, REACH registration dossiers at ECHA, EU Green Deal carbon border adjustment mechanism filings, and customs trade data tracking amino acid import flows. Bottom-up capacity assessments at Rhineland-Palatinate and Saxony-Anhalt fermentation clusters were triangulated against top-down demand modeling from livestock feed formulation trends and parenteral nutrition prescription data.
Scenario-bracketing around carbon border adjustment stringency, natural gas price volatility bands, and Chinese lysine export subsidy durability framed the projection horizon. Segmentation dimensions modeled included purity grade tier, end-use application, and regional production hub concentration. CAGRs were derived from capacity utilization trajectories and substitution elasticity estimates between domestic fermentation and imported tonnage. Industry-specific forecast inputs encompassed F-Gas Regulation phasedown schedules and EFSA novel food approval timelines for emerging amino acid derivatives.
Stress conditions across TTF natural gas benchmark movements, Chinese state subsidy policy shifts, and REACH registration review duration extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around fermentation technology maturation rates and livestock precision feeding adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Carotenoids Market
Ingredients
Rice Starch Market
Ingredients
Protein Ingredients Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Agarwood Oil Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
North America Protein Ingredients Market
Ingredients
Thinned Starch Market
Ingredients
Valerian Root Oil Market
Ingredients
South America Lipid Market
Ingredients
China Beer Adjuncts Market
Ingredients
China Protein Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Marine Protein Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Cultured Non-Fat Dairy Ingredients Market