
 Herpes Infection Treatment Market | 2026-2036
Herpes Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Herpes Infection Treatment Market Intelligence
Fixed-dose combination bundling of antiviral agents with adjuvant therapies is recalibrating how physicians select first-line protocols. GSK plc leverages its established manufacturing scale to sustain dominance in nucleoside analogue production. Teva Pharmaceutical Industries Ltd. competes aggressively on generic antiviral tablets, while Viatris, Inc. anchors its position through broad pharmacy distribution networks.
Herpes infection treatment encompasses pharmaceutical interventions targeting herpes simplex virus types 1 and 2, primarily employing synthetic nucleoside analogues such as acyclovir, valacyclovir, and famciclovir that inhibit viral DNA polymerase through chain termination. These agents serve the essential commercial purpose of reducing lesion duration, suppressing recurrent outbreaks, and lowering transmission risk in immunocompetent and immunocompromised populations. Antiviral tablets occupy the largest margin pool due to superior patient compliance and established reimbursement pathways, while topical ointments retain niche utility for localized symptom relief. The prophylactic treatment application segment commands accelerating interest as long-term suppressive therapy protocols expand beyond immunocompromised cohorts to broader at-risk populations.
FDA bioequivalence standards and EMA quality guidelines shape generic antiviral entry timelines, while WHO prequalification programs influence procurement decisions in lower-income markets. The EU F-Gas Regulation indirectly affects cold-chain logistics for temperature-sensitive formulations, adding compliance cost layers to distribution economics. Stakeholders must monitor evolving pharmacovigilance requirements for neonatal herpes indications and prepare for potential label expansions driven by real-world evidence submissions.
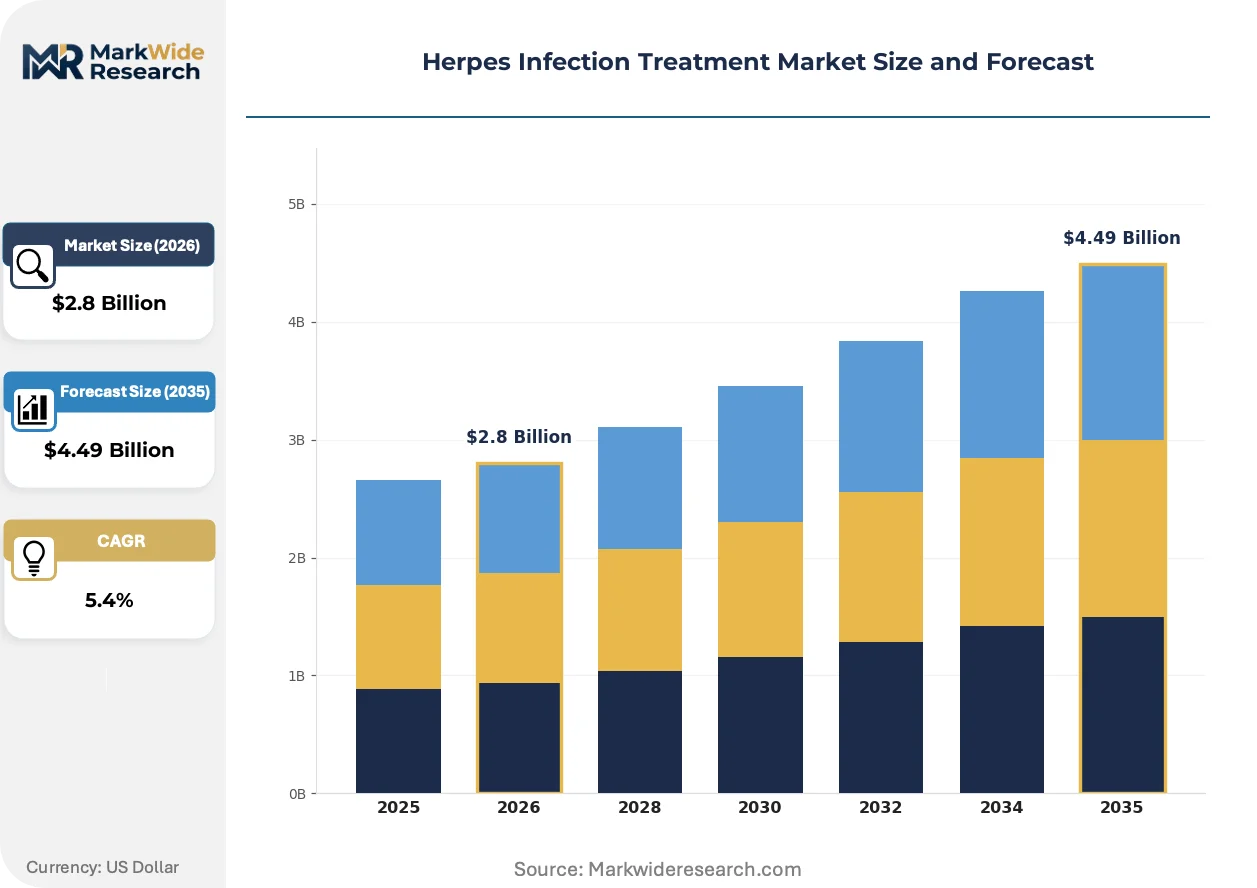
Market Dynamics
Fixed-dose combination antiviral protocols are compressing prescribing hierarchies and reordering pharmacy procurement priorities across hospital systems. Physicians now bundle nucleoside analogues with adjuvant therapies to reduce pill burden and improve adherence metrics, forcing manufacturers to reformulate single-agent portfolios into integrated regimens.
Growth Catalysts
- EMA accelerated assessment pathways:Generic antiviral manufacturers gain expedited market entry through the EMA's priority medicines scheme, compressing review timelines for bioequivalent nucleoside analogues.
- Immunocompromised oncology cohorts:Expanding prophylactic antiviral protocols in cancer treatment centers drive sustained tablet demand for HSV suppression during chemotherapy cycles.
- Japan's aging demographic concentration:Elevated herpes zoster and HSV-2 prevalence among patients over 65 sustains prescription volume growth in hospital and retail pharmacy channels.
Market Restraints
- API supply concentration:Bulk acyclovir and valacyclovir active pharmaceutical ingredient production clusters in Chinese and Indian chemical manufacturing zones, exposing formulators to geopolitical logistics disruptions.
- Generic price erosion:FDA bioequivalence approvals for multiple valacyclovir generics have collapsed unit economics for originator tablets in US pharmacy benefit manager formularies.
- Cold-chain cost layering:EU F-Gas Regulation compliance requirements for temperature-sensitive topical formulations add distribution cost burdens that compress margin pools for ointment segments.
Strategic Opportunities
- Neonatal herpes indication expansion:Real-world evidence submissions to FDA for intravenous acyclovir protocols in neonatal intensive care units could unlock label expansions with premium reimbursement tiers.
- Telehealth prescription channels:Direct-to-patient antiviral dispensing through digital health platforms bypasses traditional pharmacy networks and captures adherence data for payor contracting.
- WHO prequalification procurement:Antiviral generics securing WHO prequalification status gain preferred supplier positioning in Global Fund and PEPFAR procurement tenders for lower-income markets.
Industry Challenges
- Pharmacovigilance talent scarcity:Specialized safety surveillance capabilities for neonatal and immunocompromised indications remain concentrated among a limited pool of regulatory affairs professionals in major pharmaceutical hubs.
- Legacy manufacturing retrofit costs:Nucleoside analogue production facilities face capital-intensive upgrades to meet evolving FDA process analytical technology guidelines for continuous manufacturing transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpes Infection Treatment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Tablets, Topical Ointments, Injections, Suppositories Application: Genital Herpes, Oral Herpes, Neonatal Herpes, Prophylactic Treatment End User: Hospitals, Clinics, Homecare, Pharmacies Formulation: Liquid, Cream, Gel, Powder |
| Companies Covered | GSK plc, Novartis AG, Teva Pharmaceutical Industries Ltd., Viatris, Inc., Sanofi, Pfizer Inc., AbbVie Inc., Merck & Co., Inc., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpes Infection Treatment Market Strategic Shifts & Innovations
Long-acting injectable antiviral formulations and digital adherence monitoring tools are converging to reshape how suppressive therapy protocols are designed and reimbursed. These innovations compress the gap between clinical trial endpoints and real-world effectiveness measurement.
Novel polymer-based depot delivery systems for acyclovir prodrugs are integrating sustained-release kinetics into quarterly injection schedules. HIV and transplant medicine specialists are piloting these formulations in immunocompromised patient cohorts to eliminate daily pill burden. This technology is integrating compliance data directly into electronic health record systems, enabling outcome-based contracting with pharmacy benefit managers.
FDA's emerging guidance on real-world evidence for antiviral label expansions is accelerating post-market study requirements for generic manufacturers. The policy shifts regulatory burden toward continuous safety surveillance rather than pre-approval trial replication. Hospital pharmacy procurement committees in the United States are now conditioning formulary placement on demonstrated pharmacovigilance infrastructure.
Hospital systems are consolidating antiviral purchasing through centralized specialty pharmacy entities that negotiate direct manufacturer contracts. Retail pharmacy chains are losing volume share to these captive distribution models as integrated delivery networks seek to capture 340B drug pricing benefits. This consolidation is most advanced in United States metropolitan markets where health system mergers have concentrated buying power.
Herpes Infection Treatment Market Segmentation
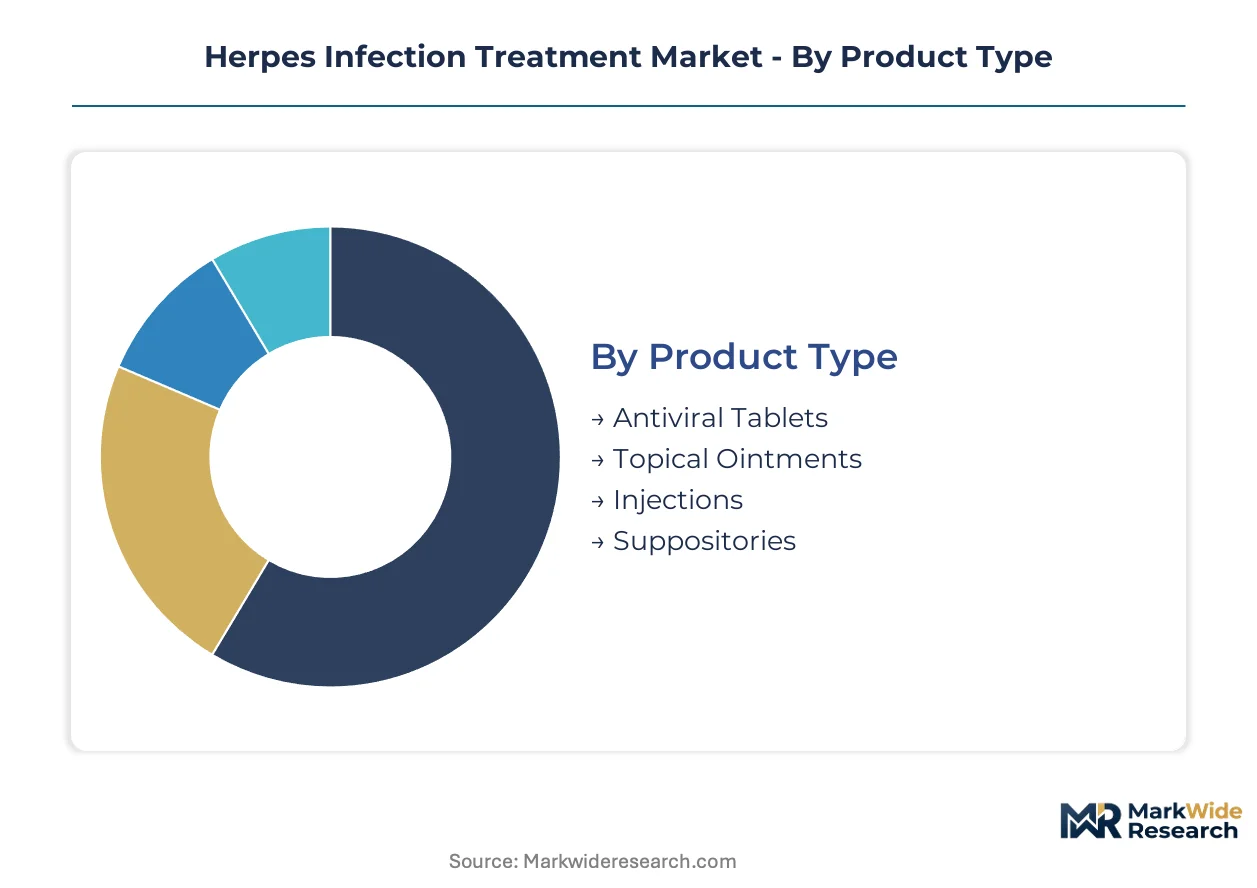
Herpes infection treatment segmentation reveals divergent margin structures across delivery modes and patient settings. Product type and application splits determine reimbursement tier access, while end-user concentration shapes distribution economics for nucleoside analogue manufacturers.
Product Type:
Volume concentration sits with oral formulations commanding pharmacy shelf space, while premium positioning attaches to specialized delivery systems requiring clinical administration.
- Antiviral Tablets:Synthetic nucleoside analogues including acyclovir, valacyclovir, and famciclovir formulated for oral bioavailability and twice-daily dosing regimens. Hospital pharmacy procurement in the United States, Germany, and Japan concentrates tablet volumes as suppressive therapy protocols broaden beyond immunocompromised cohorts. FDA bioequivalence pathways for generics compress originator margins while expanding patient access.
- Topical Ointments:Acyclovir and penciclovir creams delivering localized viral DNA polymerase inhibition for lesion-bound symptom relief. Retail pharmacy chains in Japan sustain ointment demand for HSV-1 outbreak management, though EU F-Gas Regulation compliance adds cold-chain cost layers that erode distributor margins.
- Injections:Intravenous acyclovir formulations reserved for severe disseminated infections and neonatal herpes protocols in intensive care settings.
- Suppositories:Rectal delivery systems for patients with compromised gastrointestinal absorption or swallowing difficulties.
Today's leader: Antiviral Tablets. Tomorrow's challenger: Injections.
Application:
Prophylactic protocols are displacing episodic treatment as the primary revenue anchor, with neonatal indications offering premium pricing potential.
- Genital Herpes:Suppressive therapy for HSV-2 recurrence management dominates prescription volumes in sexually transmitted infection clinics. Teva Pharmaceutical Industries Ltd. and Viatris, Inc. compete aggressively on generic valacyclovir tablets as US pharmacy benefit managers prioritize cost containment over brand loyalty.
- Prophylactic Treatment:Long-term antiviral suppression expanding from transplant and oncology wards to broader at-risk populations. Immunocompromised chemotherapy patients in German university hospitals drive sustained demand for prophylactic protocols that prevent HSV reactivation during neutropenic episodes.
- Oral Herpes:HSV-1 cold sore management through episodic or suppressive regimens, concentrated in retail pharmacy channels.
- Neonatal Herpes:Intravenous acyclovir protocols for disseminated central nervous system infections in neonatal intensive care units.
Prophylactic Treatment gains share fastest as oncology and transplant protocols broaden. Neonatal Herpes holds premium pricing power through specialized indication status.
End User:
Hospital consolidation is reordering purchasing power, with integrated delivery networks capturing 340B pricing advantages over fragmented retail channels.
- Hospitals:Centralized specialty pharmacy entities negotiate direct manufacturer contracts for antiviral formularies. US metropolitan health system mergers concentrate buying power and disintermediate traditional wholesale distribution.
- Pharmacies:Retail chains face volume erosion as hospital-owned specialty pharmacies expand, though Japan's aging demographic sustains prescription throughput in community settings.
- Clinics:Outpatient sexually transmitted infection and dermatology practices.
- Homecare:Direct-to-patient dispensing through telehealth platforms capturing adherence data.
Hospitals command procurement leverage today. Homecare channels represent the steepest expansion trajectory as digital health platforms mature.
Formulation:
Physical state determines stability requirements, storage infrastructure, and patient self-administration feasibility across climate zones.
- Cream:Semi-solid emulsions for topical lesion application with established stability profiles.
- Liquid:Oral suspensions enabling pediatric and geriatric dosing flexibility where tablet swallowing presents difficulty.
- Gel:Hydrogel matrices offering enhanced skin adhesion for mucosal surface application.
- Powder:Reconstitutable formulations for hospital pharmacy compounding and intravenous preparation.
Cream formulations anchor current topical volumes. Gel delivery systems are climbing fastest as polymer science enables sustained-release kinetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic nucleoside analogue production first achieved industrial scale in United States pharmaceutical corridors during the 1980s, establishing regulatory templates that EMA and Japan's PMDA later adapted for their own accelerated review pathways.
United States
Hospital pharmacy consolidation in metropolitan health systems concentrates antiviral procurement through captive specialty pharmacies. FDA bioequivalence standards for generic valacyclovir compress originator margins while expanding patient access. The 340B drug pricing program anchors purchasing leverage in integrated delivery networks across Boston, New York, and Philadelphia corridors.
Germany
University hospital oncology wards drive prophylactic antiviral demand for immunocompromised chemotherapy patients. EMA accelerated assessment pathways expedite generic nucleoside analogue entry through the priority medicines scheme. Chemical manufacturing clusters in North Rhine-Westphalia supply active pharmaceutical ingredients to formulators serving Central European markets.
Japan
Aging demographics elevate herpes zoster and HSV-2 prevalence among patients over 65, sustaining prescription volumes in hospital and retail channels. PMDA review harmonization with FDA standards streamlines generic antiviral approvals. Tokyo-Osaka pharmaceutical distribution networks maintain cold-chain integrity for temperature-sensitive topical formulations under METI guidance.
India
Bulk acyclovir and valacyclovir API production concentrates in Gujarat and Maharashtra chemical zones, exposing formulators to logistics disruption risks. CDSCO manufacturing facility inspections align with WHO prequalification standards for Global Fund procurement eligibility. Hyderabad and Mumbai formulation hubs supply generic antiviral tablets to lower-income African and Southeast Asian markets.
United Kingdom
Telehealth prescription channels bypass traditional pharmacy networks, capturing adherence data for NHS payor contracting. MHRA post-Brexit regulatory autonomy maintains EMA-equivalent standards for bioequivalence assessment. London and Cambridge biotech clusters pilot digital health platforms integrating antiviral dispensing with electronic health record systems.
Herpes Infection Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across patent status and manufacturing scale dimensions. Originator nucleoside analogue manufacturers retain pricing power in neonatal and immunocompromised indications where clinical data exclusivity persists. Generic tablet specialists compete on FDA bioequivalence speed and pharmacy benefit manager formulary placement. Two dominant competitive moves reshape positioning: hospital system direct contracting that disintermediates wholesale distribution, and polymer-based depot formulation licensing that extends patent life through delivery technology.
Within the originator-manufacturer tier, GSK plc anchors nucleoside analogue production through established manufacturing scale, while Novartis AG and Sanofi occupy positions in adjacent antiviral therapeutic areas. Among generic specialists, Teva Pharmaceutical Industries Ltd. and Viatris, Inc. exemplify the bioequivalence-speed competitive vector, with both representing the pharmacy distribution network archetype that negotiates directly with consolidated hospital purchasing entities.
| Leading Market Players |
|---|
| GSK plc |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Viatris, Inc. |
| Sanofi |
| Pfizer Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Fresenius Kabi AG |
| Others |
Cost & Logistics Intelligence
Generic-specialist roll-ups backed by private-equity capital now control substantial nucleoside analogue tablet volumes, compressing pricing discipline through formulary bidding wars while simultaneously locking in multi-year API offtake agreements that insulate against raw material volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by clinical indication complexity and reimbursement tier access. Price differentiation rests on FDA bioequivalence certification status and hospital formulary placement depth. Cost compression in the generic tablet tier intensifies because pharmacy benefit managers consolidate supplier panels. Retail pharmacy chains exhibit highest price sensitivity; neonatal intensive care units show lowest sensitivity due to clinical protocol rigidity.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive topical formulations remain underdeveloped, exposing distributors to write-downs when cold-chain excursions occur during returns processing. Bulk acyclovir and valacyclovir API production concentrates in India and China, with secondary formulation capacity in Germany and the United States. Raw material dependencies include guanine derivatives, specialized solvents, and polymer excipients for depot formulations. Single-source vulnerability in Chinese chemical manufacturing zones threatens continuity. Distribution runs through hospital-owned specialty pharmacies that disintermediate traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in prophylactic indication extensions and long-acting formulation platforms, with polymer-based depot delivery systems offering the clearest path to premium-tier pricing reset.
For Market Incumbents: Anchor manufacturing scale advantages through backward integration into API production in Indian chemical corridors, securing supply continuity against geopolitical logistics disruptions. Deepen hospital system direct contracting to capture 340B pricing benefits and disintermediate pharmacy benefit manager formularies. Invest in continuous manufacturing upgrades to meet FDA process analytical technology guidelines ahead of generic competitors.
For New Entrants and Emerging Players: Telehealth prescription channels offer the most penetrable route to bypass entrenched wholesale distribution and capture adherence data for payor contracting. Target homecare delivery models for immunocompromised patient cohorts seeking to eliminate clinic visit burdens. Pursue WHO prequalification status to unlock Global Fund and PEPFAR procurement tenders in lower-income African markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale generic manufacturers with underutilized nucleoside analogue production capacity and dormant FDA bioequivalence filings. Long-term viability hinges on successful pivot from commoditized oral tablets to specialized injectable and depot formulations. Monitor EMA accelerated assessment pathway approval velocity as an inflection indicator for competitive entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Quarterly injection schedules for acyclovir prodrugs eliminate daily pill burden in immunocompromised cohorts. |
| Hospital System Direct Contracting | Integrated delivery networks in Boston and Philadelphia corridors capture 340B pricing advantages over retail channels. |
| Neonatal Indication Label Expansion | FDA real-world evidence submissions for intravenous protocols unlock premium reimbursement tiers in intensive care settings. |
| API Backward Integration | In-house production of acyclovir and valacyclovir intermediates insulates against Chinese logistics disruption risks. |
| Telehealth Platform Partnership | Direct-to-patient dispensing through digital health platforms captures adherence data for pharmacy benefit manager contracting. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, hospital procurement managers, formulary directors, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis provided triangulation across the analysis window.
Historical reference periods anchored the projection horizon to documented nucleoside analogue adoption curves in oncology prophylaxis and transplant medicine. Segmentation dimensions included treatment application, dosage form, administration route, patient immunocompetence status, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to volume and value outputs. Forecast inputs incorporated immunocompromised patient population projections and generic bioequivalence approval velocity assumptions.
The model assumes a particular technology adoption path; alternative pathways for polymer-based depot delivery systems would alter the outlook if sustained-release kinetics fail to demonstrate non-inferiority to daily oral regimens. Forecasts reflect assumptions about EMA accelerated assessment pathway continuity and WHO prequalification program stability. Practitioners should monitor FDA guidance evolution on real-world evidence standards and cold-chain logistics cost trajectories under EU F-Gas Regulation compliance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Chlamydia Infection Treatment Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Efavirenz Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Viral Hemorrhagic Fever Market