
 Veterinary Infectious Disease Therapeutics Market | 2026-2036
Veterinary Infectious Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Infectious Disease Therapeutics Market Analytics
mRNA platform migration is rewriting development timelines for veterinary vaccines, compressing strain-matching cycles from years to months. Zoetis leverages its mammalian cell culture infrastructure to dominate recombinant vaccine supply for livestock operations across North America. Boehringer Ingelheim Vetmedica anchors its competitive position through backward integration into antigen production, securing captive supply of viral substrates for its European manufacturing network.
Veterinary infectious disease therapeutics comprise biologically active agents formulated for the prevention, treatment, or control of pathogenic infections in companion and production animals, typically requiring cold-chain distribution between two and eight degrees Celsius to preserve immunological potency. These products serve commercial purposes by reducing morbidity-related production losses in food-animal systems and extending life expectancy in companion species. Vaccines command the largest revenue share within product type segments due to recurring annual revaccination schedules mandated by farm assurance programs. Antiparasitics represent the fastest-expanding category as climate-driven vector range expansion intensifies tick-borne disease pressure across temperate zones. Intranasal delivery modes are gaining structural traction in companion animal protocols because mucosal administration reduces needle-associated stress responses and improves owner compliance.
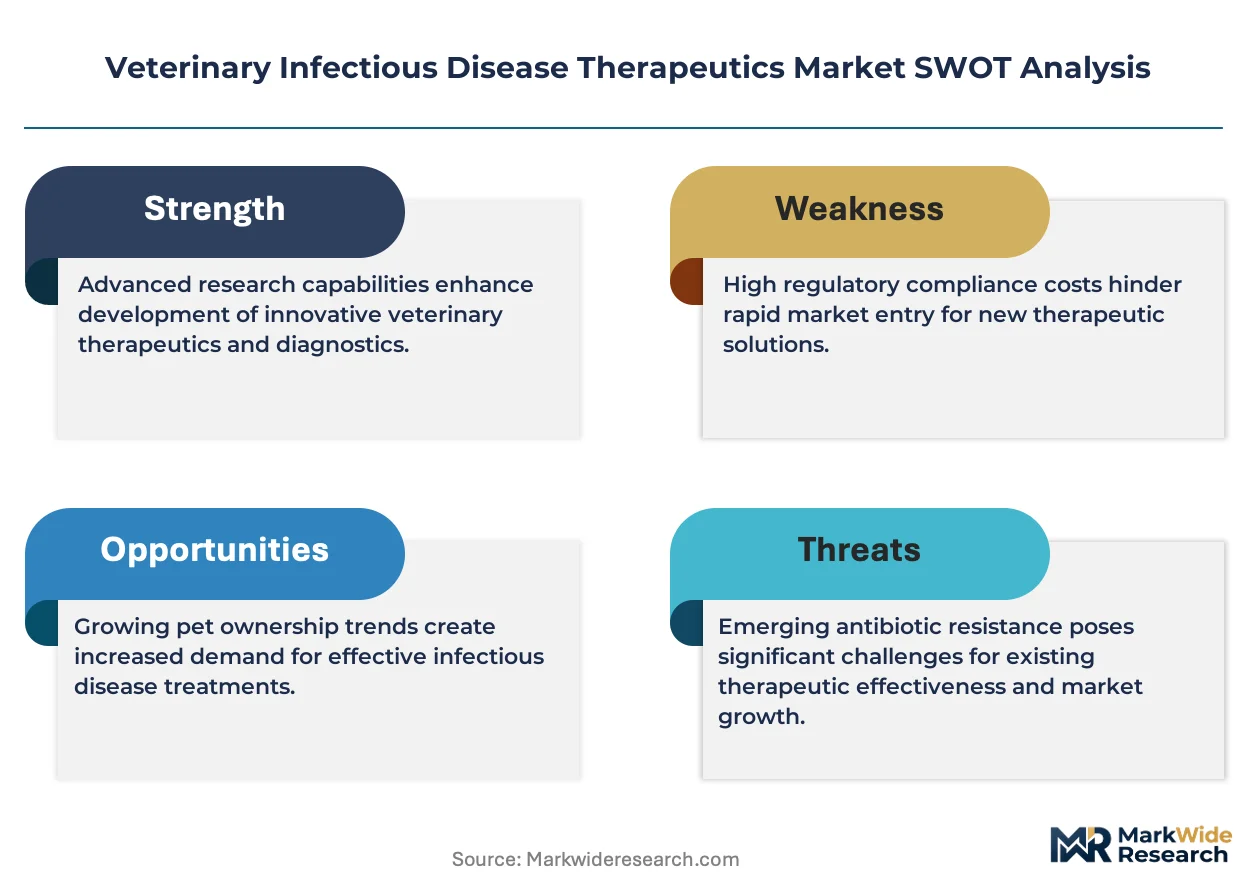
The FDA's Veterinary Feed Directive and the EU's Veterinary Medicines Regulation jointly constrain antimicrobial use, forcing reformulation toward narrow-spectrum alternatives and elevating compliance costs for cross-border suppliers. The USDA's Center for Veterinary Biologics maintains batch-release authority over all veterinary vaccines distributed in the United States, creating a procedural bottleneck that shapes market entry timelines for foreign manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions where antibiotic stewardship rules tighten and regions where disease eradication campaigns still permit mass prophylaxis, as this split determines portfolio prioritization and manufacturing location decisions.
Market Dynamics
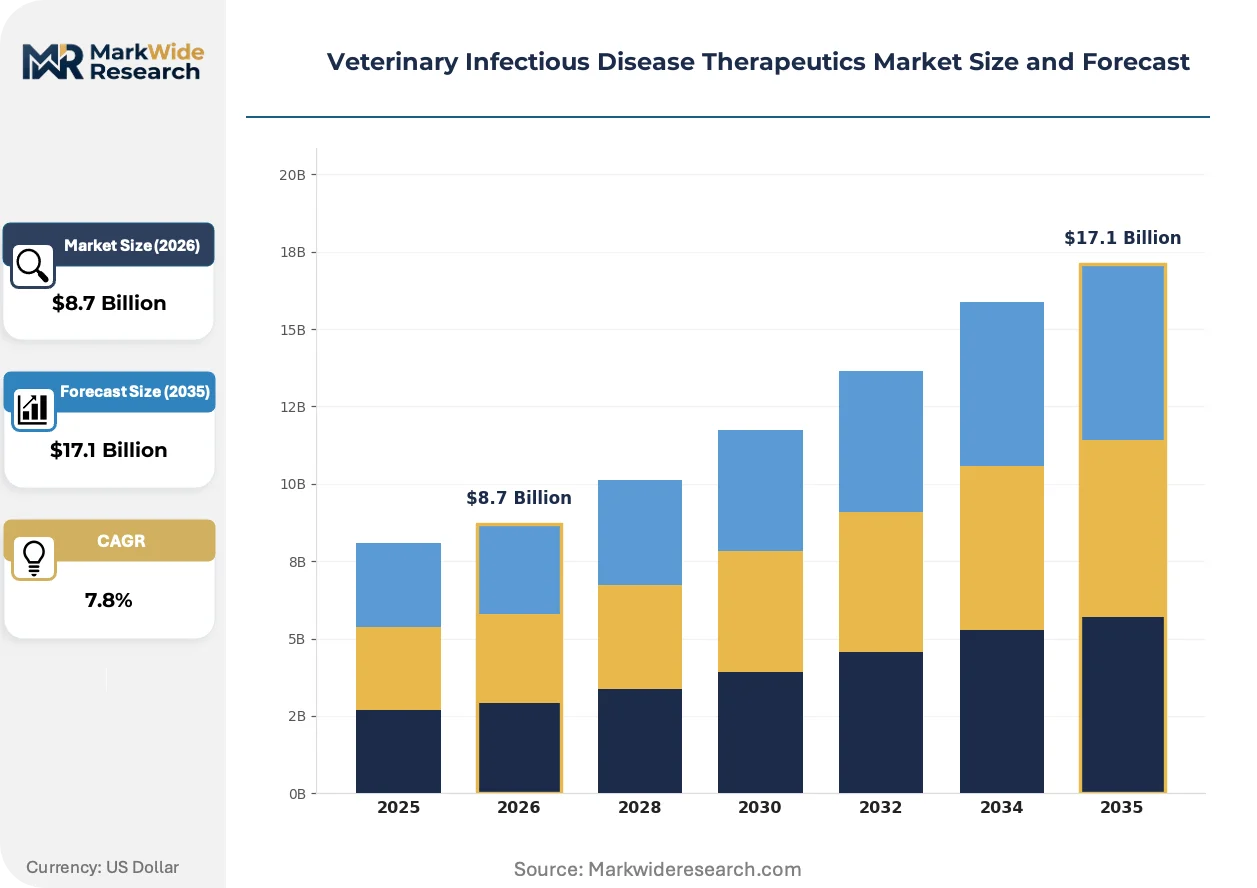
mRNA platform migration is compressing veterinary vaccine development cycles from years to months while companion animal clinics expand prophylactic budgets and FDA antibiotic oversight tightens prescription protocols across the United States.
Growth Catalysts
- Companion animal clinic expansion:Prophylactic drug budgets are rising across developed markets as pet owners prioritize preventive care over reactive treatment.
- Foot-and-mouth disease eradication programs:Brazil's cattle belt drives bulk vaccine procurement through government-mandated control campaigns.
- Cold-chain infrastructure maturation:Two-to-eight-degree Celsius distribution networks now reach remote livestock operations, preserving immunological potency for temperature-sensitive biologics.
Market Restraints
- Antimicrobial access restrictions:The FDA's Veterinary Feed Directive and the EU's Veterinary Medicines Regulation constrain mass prophylaxis, elevating compliance costs for cross-border suppliers.
- Batch-release procedural bottlenecks:The USDA's Center for Veterinary Biologics maintains release authority over all US-distributed vaccines, extending market entry timelines for foreign manufacturers.
- Strain-matching technical limitations:Traditional egg-based production requires lengthy adaptation cycles that lag behind emerging pathogen variants.
Strategic Opportunities
- Mucosal delivery innovation:Intranasal administration modes reduce needle-associated stress responses in companion animals, improving owner compliance and protocol adherence.
- Antiparasitic category expansion:Climate-driven vector range extension intensifies tick-borne disease pressure across temperate zones, creating demand for novel ectoparasiticide formulations.
- Recombinant platform adoption:Mammalian cell culture infrastructure enables rapid antigen production without egg supply dependencies.
Industry Challenges
- Regulatory divergence management:Portfolio prioritization requires simultaneous tracking of antibiotic stewardship tightening in some jurisdictions and disease eradication mass prophylaxis permissions in others.
- Manufacturing location optimization:Cross-border suppliers face complex decisions balancing proximity to demand clusters against regulatory compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Infectious Disease Therapeutics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Antivirals, Antiparasitics End User: Veterinary Clinics, Research Laboratories, Animal Shelters, Livestock Farms Application: Preventive Care, Treatment, Diagnostics, Research Delivery Mode: Injections, Oral, Topical, Intranasal |
| Companies Covered | Zoetis, Elanco, Merck & Co. Inc, Boehringer Ingelheim Vetmedica, Dechra Pharmaceuticals PLC, Ceva Sante Animale, Virbac S.A, Bayer AG, Vetoquinol S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Infectious Disease Therapeutics Market Evolving Landscape
Technology platforms, regulatory frameworks, and procurement behaviors are simultaneously restructuring how veterinary infectious disease therapeutics reach end-users across companion and production animal segments.
mRNA vaccine platforms encode pathogen antigens synthetically, eliminating egg-based production dependencies. Large livestock operations in North America are piloting these formulations for rapid strain-matching against emerging viral threats. This speed-to-market capability is rendering obsolete the multi-year development timelines that previously constrained annual vaccine updates.
The EU's Veterinary Medicines Regulation imposes antimicrobial use restrictions that force reformulation toward narrow-spectrum alternatives. European suppliers are reconfiguring product portfolios to emphasize vaccines and immunomodulators over traditional antibiotics. Production animal segments face the steepest compliance adjustments as farm assurance programs mandate documentation of reduced antimicrobial reliance.
Companion animal owners now prioritize stress-reduced administration methods over cost minimization. Veterinary clinics are replacing injectable protocols with mucosal and oral delivery options where immunological efficacy permits. This preference shift concentrates in urban markets where pet humanization trends drive willingness-to-pay premiums for improved animal experience.
Veterinary Infectious Disease Therapeutics Market Segmentation
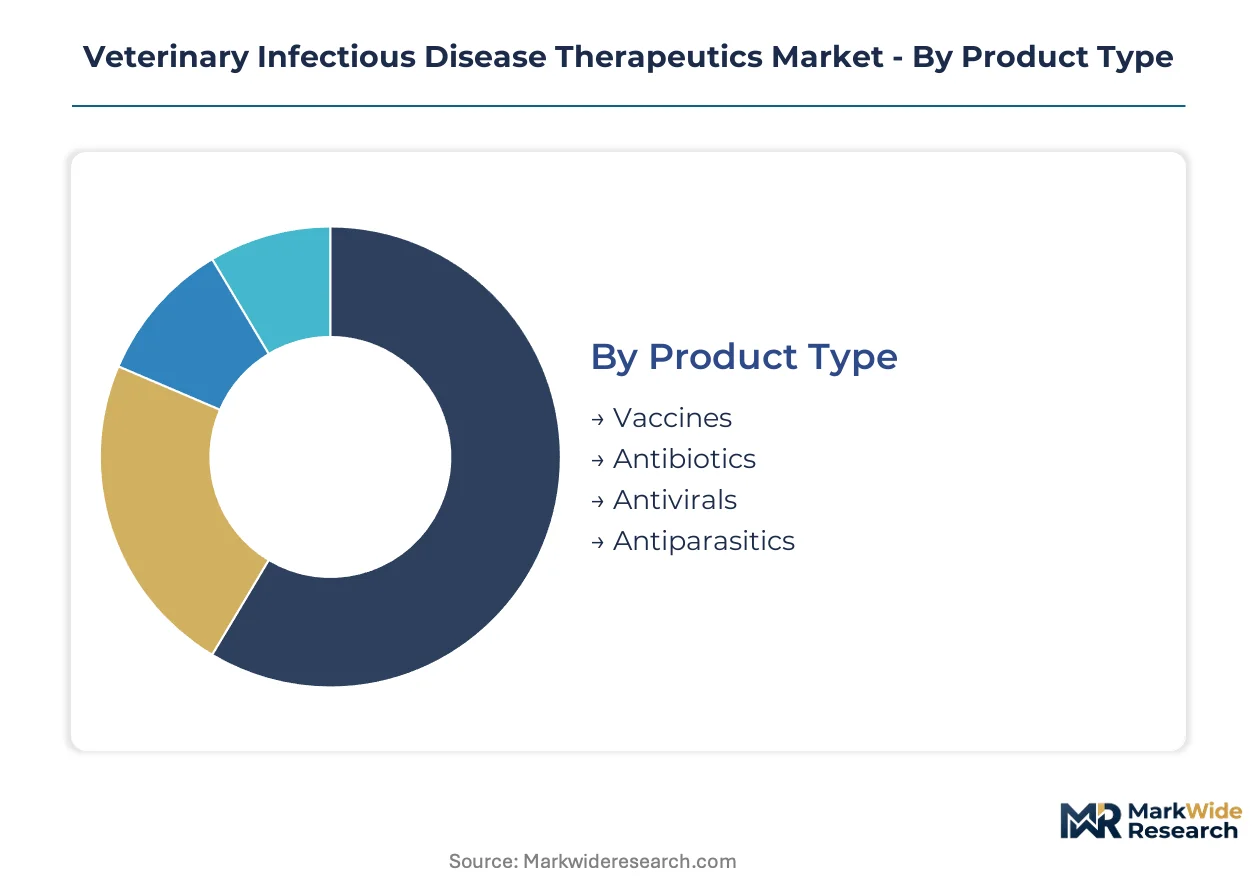
Veterinary infectious disease therapeutics segment along four functional dimensions that determine cold-chain requirements, regulatory pathways, and service intensity. Product type governs manufacturing complexity and margin structure. End user shapes procurement scale and compliance protocols.
Product Type:
After-sales service intensity varies sharply across this category, with biological products demanding continuous cold-chain monitoring and annual revaccination scheduling support.
- Vaccines:Formulated biologics requiring two-to-eight-degree Celsius distribution to preserve immunological potency. Demand concentrates in Brazil's cattle belt where government-mandated foot-and-mouth disease control programs drive bulk procurement through veterinary channels. These products command the largest revenue share due to recurring annual revaccination schedules mandated by farm assurance programs.
- Antiparasitics:Ectoparasiticide and endoparasiticide formulations targeting vector-borne pathogens. Climate-driven tick range expansion across temperate zones intensifies demand for novel formulations in companion animal clinics and livestock operations. This segment is expanding most quickly as vector-borne disease pressure mounts in previously unaffected regions.
- Antibiotics:Narrow and broad-spectrum antibacterial agents facing tightening stewardship constraints under FDA Veterinary Feed Directive and EU Veterinary Medicines Regulation.
- Antivirals:Direct-acting agents for established viral infections in companion species, with limited penetration in production animal segments due to cost constraints.
By volume, vaccines lead. By growth pace, antiparasitics are ahead.
End User:
Procurement scale and compliance sophistication create distinct service tiers across customer types, from enterprise livestock operations to fragmented shelter networks.
- Veterinary Clinics:Primary dispensing channels for companion animal therapeutics, with urban clinics expanding prophylactic drug budgets as pet humanization trends deepen. These facilities prioritize stress-reduced administration methods and cold-chain reliability over cost minimization.
- Livestock Farms:Industrial-scale operations purchasing vaccines in bulk volumes for herd-level disease control. North American feedlot operators and Brazilian cattle producers anchor demand for recombinant platform vaccines with rapid strain-matching capabilities.
- Research Laboratories:Specialized procurement of experimental therapeutics and diagnostic reagents for veterinary pathology studies and vaccine efficacy trials.
- Animal Shelters:Cost-constrained channels focusing on core vaccination protocols and mass treatment for parasitic burden in intake populations.
Livestock farms dominate procurement volume. Veterinary clinics show the steepest budget expansion trajectory.
Application:
Margin structure and regulatory burden diverge between prevention-focused and treatment-focused applications, with diagnostics emerging as a service-intensive intermediate category.
- Preventive Care:Prophylactic vaccination and routine parasiticide administration forming the revenue foundation for veterinary practice economics. Farm assurance programs and pet insurance policies increasingly mandate documented preventive protocols.
- Treatment:Reactive therapeutic intervention for established infections, constrained by antimicrobial access restrictions in major markets and shifting toward narrow-spectrum alternatives.
- Diagnostics:Pathogen identification and antimicrobial susceptibility testing guiding therapeutic selection, with point-of-care molecular platforms gaining traction in clinic settings.
- Research:Experimental therapeutic evaluation and vaccine development support, primarily serving academic and pharmaceutical research institutions.
Preventive care generates the highest recurring revenue. Diagnostics is climbing fastest as precision medicine protocols spread.
Delivery Mode:
Route of administration determines cold-chain complexity, owner compliance rates, and manufacturing formulation requirements across the product portfolio.
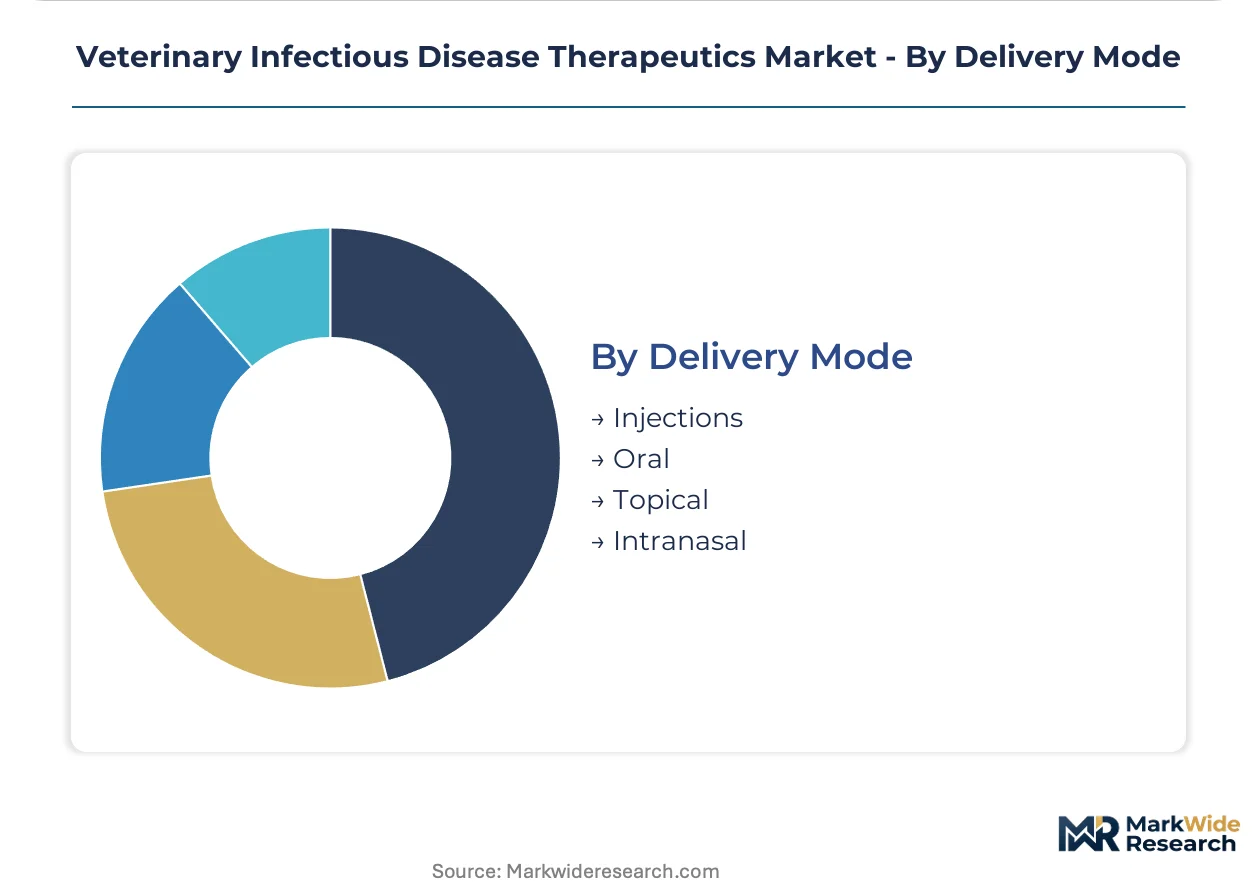
- Injections:Parenteral administration of vaccines and antibiotics requiring sterile technique and needle disposal protocols. USDA Center for Veterinary Biologics maintains batch-release authority over all injectable vaccines distributed in the United States.
- Intranasal:Mucosal delivery of modified-live vaccines inducing local immunity without systemic stress responses. Urban companion animal clinics are replacing injectable protocols with intranasal options where immunological efficacy permits.
- Oral:Feed-additive and water-soluble formulations for mass medication in livestock operations, now constrained by veterinary prescription requirements under antimicrobial stewardship rules.
- Topical:Transdermal antiparasitic applications for ectoparasite control in companion animals, offering owner convenience but limited suitability for production species.
Injections retain volume leadership. Intranasal delivery is gaining share fastest as stress-reduction preferences intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal clinics and industrial livestock operations concentrate demand differently across major markets, with regulatory frameworks and disease control programs shaping procurement patterns in each geography.
United States
Urban veterinary clinics in California and New York Metro expand prophylactic drug budgets as pet humanization trends deepen. The FDA's Veterinary Feed Directive tightens antibiotic prescription protocols, elevating compliance costs for cross-border suppliers. Research Triangle Park in North Carolina anchors vaccine development activity for rapid strain-matching platforms.
Brazil
Government-mandated foot-and-mouth disease eradication programs drive bulk vaccine procurement across São Paulo and Minas Gerais cattle operations. ANVISA regulates veterinary biologics distribution, creating procedural requirements for foreign manufacturers. The Pantanal cattle belt concentrates demand for thermostable vaccine formulations suited to tropical distribution challenges.
Germany
Industrial livestock operations in Lower Saxony and North Rhine-Westphalia anchor demand for recombinant platform vaccines with narrow-spectrum alternatives. The EU's Veterinary Medicines Regulation constrains antimicrobial use, forcing portfolio reconfiguration toward immunomodulators. Leipzig's veterinary research cluster advances mucosal delivery formulation development.
China
Integrated pork and poultry operations in Sichuan-Chongqing and Shandong Peninsula drive volume procurement for herd-level disease control. NMPA oversight of veterinary biologics shapes market entry timelines for foreign suppliers. Yangling Agricultural Hi-Tech Industrial Zone concentrates domestic vaccine manufacturing capacity expansion.
Australia
Sheep and cattle stations in New South Wales and Queensland intensify tick-borne disease management as vector ranges expand southward. TGA regulates veterinary vaccine batch release, preserving immunological potency standards. Melbourne's veterinary science precinct advances point-of-care diagnostic platform development for remote operation deployment.
Veterinary Infectious Disease Therapeutics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated structure where mammalian cell culture infrastructure and antigen production capabilities determine supply security. The vendor base clusters around three strategic archetypes: integrated pharmaceutical conglomerates with human-animal health crossovers, dedicated animal health pure-plays with captive manufacturing networks, and regional specialists with formulation expertise in specific species segments. Dominant competitive moves include backward integration into viral substrate production and strategic partnerships for mRNA platform licensing.
Within the integrated pharmaceutical tier, Zoetis and Merck & Co. Inc occupy positions exemplifying scale-driven mammalian cell culture dominance, while Boehringer Ingelheim Vetmedica anchors the European manufacturing network archetype through in-house antigen production capabilities. These three entities represent the channel-control end of the competitive spectrum where captive supply chains and regulatory navigation expertise create structural advantages in batch-release constrained markets.
| Leading Market Players |
|---|
| Zoetis |
| Elanco |
| Merck & Co. Inc |
| Boehringer Ingelheim Vetmedica |
| Dechra Pharmaceuticals PLC |
| Ceva Sante Animale |
| Virbac S.A |
| Bayer AG |
| Vetoquinol S.A |
| Others |
Value Network & Pricing Analysis
Tariff exposure on imported viral substrates determines both the premium-to-economy pricing spread across vaccine tiers and the geographic distribution of mammalian cell culture investments. Cold-chain logistics costs for two-to-eight-degree Celsius distribution further compress margins for suppliers serving remote livestock operations, forcing portfolio rationalization toward higher-value recombinant formulations.
Pricing Analysis
Cost-plus contracts with API indexation dominate bulk vaccine procurement for Brazilian cattle operations and North American feedlot systems. Three-tier pricing structure across premium recombinant, standard modified-live, and economy inactivated vaccine levels reflects differentiation by strain-matching speed and cold-chain reliability guarantees. Pricing pressure stems from antimicrobial stewardship compliance costs as FDA Veterinary Feed Directive enforcement elevates documentation burdens. Livestock farms exhibit highest price sensitivity due to herd-scale volume economics, while urban companion animal clinics prioritize stress-reduced delivery premiums over unit cost minimization.
Supply Chain Analysis
Upstream fetal bovine serum and specialized cell culture media feedstock draws from suppliers concentrated in the United States, Germany, and Australia. Viral seed stocks and antigen substrates hinge on captive production capabilities at vertically integrated manufacturers, with Boehringer Ingelheim Vetmedica and Zoetis controlling proprietary mammalian cell lines. Single-source vulnerability in egg-based production creates supply risk during avian influenza outbreaks that disrupt traditional vaccine manufacturing. Distribution runs through veterinary wholesale networks with cold-chain verification, supplemented by direct-to-clinic logistics for temperature-sensitive biologics in urban companion animal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform substitution threatens incumbent vaccine portfolios with compressed development timelines and reduced manufacturing asset intensity. Incumbents must navigate this technology displacement while defending established recombinant and modified-live product lines through accelerated R&D redeployment.
For Market Incumbents: Pre-empt mRNA platform encroachment by licensing synthetic antigen production capabilities or acquiring specialized biotech developers with validated veterinary formulations. Accelerate backward integration into viral substrate production to secure captive supply chains against raw material tariff volatility. Channel control through exclusive clinic partnerships remains essential for defending companion animal vaccine share against low-cost entrants.
For New Entrants and Emerging Players: Build out regional formulation capabilities in Brazil and Australia where ANVISA and TGA batch-release requirements create procedural barriers to incumbent imports. Target animal shelter and cost-constrained livestock segments with thermostable vaccine alternatives that reduce cold-chain dependency. Partner with established veterinary distribution networks to bypass direct regulatory navigation costs in FDA and EU jurisdictions.
For Investors and Strategic Acquirers: EU Veterinary Medicines Regulation implementation reshapes the acquisition landscape by elevating immunomodulator and vaccine asset values above traditional antibiotic portfolios. Focus diligence on mammalian cell culture infrastructure and antigen production captive supply as durable competitive moats. Watch for FDA Veterinary Feed Directive enforcement intensity as the signal indicating margin compression timing for antimicrobial-dependent suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| mRNA Platform Licensing | Accelerates strain-matching capabilities against emerging viral threats without egg supply dependencies. |
| Cold-Chain Infrastructure Expansion | Enables two-to-eight-degree Celsius distribution reach into remote Brazilian Pantanal cattle operations. |
| Backward Integration into Antigen Production | Secures captive viral substrate supply for European manufacturing network resilience. |
| Mucosal Delivery Formulation Development | Captures urban companion animal clinic preference for stress-reduced intranasal administration protocols. |
| Regulatory Batch-Release Capacity Investment | Reduces USDA Center for Veterinary Biologics procedural bottlenecks for foreign market entry. |
Research Methodology
Operator-level perspectives from veterinary clinic directors, livestock procurement managers, regulatory affairs specialists at animal health manufacturers, and cold-chain logistics coordinators anchored the qualitative base. These primary insights combined with secondary validation from FDA Veterinary Feed Directive enforcement records, USDA Center for Veterinary Biologics batch-release databases, EU Veterinary Medicines Regulation implementation guidance, and ANVISA veterinary biologics registration filings. Bottom-up demand modeling across product type, end user, application, and delivery mode segments triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing across antimicrobial stewardship intensity and mRNA platform adoption curves framed the projection horizon without discrete year anchoring. Segmentation dimensions modeled encompassed product type biologics versus pharmaceuticals, end user clinic versus farm scale, preventive versus treatment application focus, and parenteral versus mucosal delivery routes. CAGRs derived from elasticity-adjusted demand curves incorporating pet humanization expenditure trends and foot-and-mouth disease eradication program procurement cycles. Industry-specific forecast inputs included climate-driven vector range expansion parameters and cold-chain infrastructure penetration rates.
Stress conditions across regulatory enforcement intensity, avian influenza disruption to egg-based supply, and tariff exposure on imported substrates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding strain-matching technology transition timelines and companion animal owner willingness-to-pay evolution. Cross-checking against national veterinary pharmaceutical trade statistics and farm assurance program vaccination compliance benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market