
 Folic Acid Tablets Market | 2026-2036
Folic Acid Tablets Market Size, Share, and Industry Trends Forecast 2026-2036
Folic Acid Tablets Market Insights
Continuous manufacturing is narrowing the cost gap between generic and brand-name folic acid tablets, compressing batch-to-batch variability below traditional wet-granulation thresholds. BASF SE leverages its backward integration into petrochemical-derived pteroylglutamic acid precursors to sustain margin control across European supply chains. Jiangxi Tianxin Pharmaceutical Co. Ltd. anchors volume production through dedicated fermentation facilities in Jiangsu province, while DSM NV differentiates via crystal form patents that improve tablet compressibility.
Folic acid tablets contain synthetic pteroylglutamic acid, typically dosed at 400–800 micrograms for neural tube defect prophylaxis, produced through multi-step chemical synthesis or microbial fermentation followed by crystallization and direct compression. The generic segment dominates volume due to WHO Essential Medicines List inclusion and government tender programs, though customized formula tablets command premium positioning through methylfolate variants targeting MTHFR polymorphism patients. Pharmacy channels retain the largest transaction share for acute prescriptions, yet online retail is accelerating fastest where telehealth platforms bundle prenatal supplement subscriptions with virtual consultations.
The US FDA regulates folic acid tablets as dietary supplements under 21 CFR 101.79, mandating health claim language for neural tube defect risk reduction while restricting therapeutic assertions. India's CDSCO enforces BIS purity standards for domestic manufacture and import, with recent PLI scheme incentives expanding active pharmaceutical ingredient capacity in Telangana and Andhra Pradesh. China's NMPA requires bioequivalence data for folic acid tablet approvals, tightening quality benchmarks that filter substandard producers. Stakeholders must monitor evolving methylfolate regulatory classifications and telehealth distribution compliance frameworks as channel structures fragment.
Market Dynamics
Continuous manufacturing adoption is compressing production economics for folic acid tablets, eroding the traditional cost advantage that wet-granulation batch processes held over direct-compression alternatives and forcing incumbent producers to retool or cede tender contracts.
Growth Catalysts
- Brazil's ANVISA prenatal mandate:Mandatory folic acid supplementation protocols in national maternal health programs lock in institutional procurement volumes for public-sector tenders.
- Methylfolate isomer demand:Rising diagnosis rates of MTHFR polymorphism among prenatal patients pull prescribing toward bioactive folate variants that bypass metabolic conversion bottlenecks.
- Maharashtra and Gujarat state expansion:India's state-level maternal health initiatives concentrate demand growth in western industrial corridors with established pharmaceutical distribution infrastructure.
Market Restraints
- Petrochemical precursor volatility:Pteroylglutamic acid synthesis depends on petroleum-derived aromatic feedstocks exposed to crude price swings that squeeze contract manufacturing margins.
- Jiangsu province supply concentration:Fermentation-based active pharmaceutical ingredient output clusters in eastern China's industrial belt, creating single-geography risk for global tablet producers.
- Wet-granulation asset stranding:Legacy equipment designed for batch processing lacks retrofit compatibility with continuous lines, trapping mid-tier manufacturers in higher-cost production modes.
Strategic Opportunities
- Telehealth subscription bundling:Virtual prenatal care platforms in the United States integrate folic acid auto-refill programs with remote physician consultations, capturing patient adherence data.
- India's PLI scheme for APIs:Production-linked incentives for active pharmaceutical ingredient manufacturing in Telangana and Andhra Pradesh attract fermentation capacity expansion outside legacy Jiangsu clusters.
- Methylfolate regulatory reclassification:Pending determinations by the US FDA on whether L-methylfolate qualifies as a dietary supplement or prescription medical food create first-mover positioning windows.
Industry Challenges
- Continuous manufacturing talent scarcity:Process analytical technology and real-time release testing expertise remains concentrated among contract development organizations, inflating recruitment costs for in-house transitions.
- Bioequivalence study bottlenecks:China's NMPA tightened requirements for folic tablet approvals, extending timeline uncertainty for generic entrants targeting hospital procurement lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folic Acid Tablets Market |
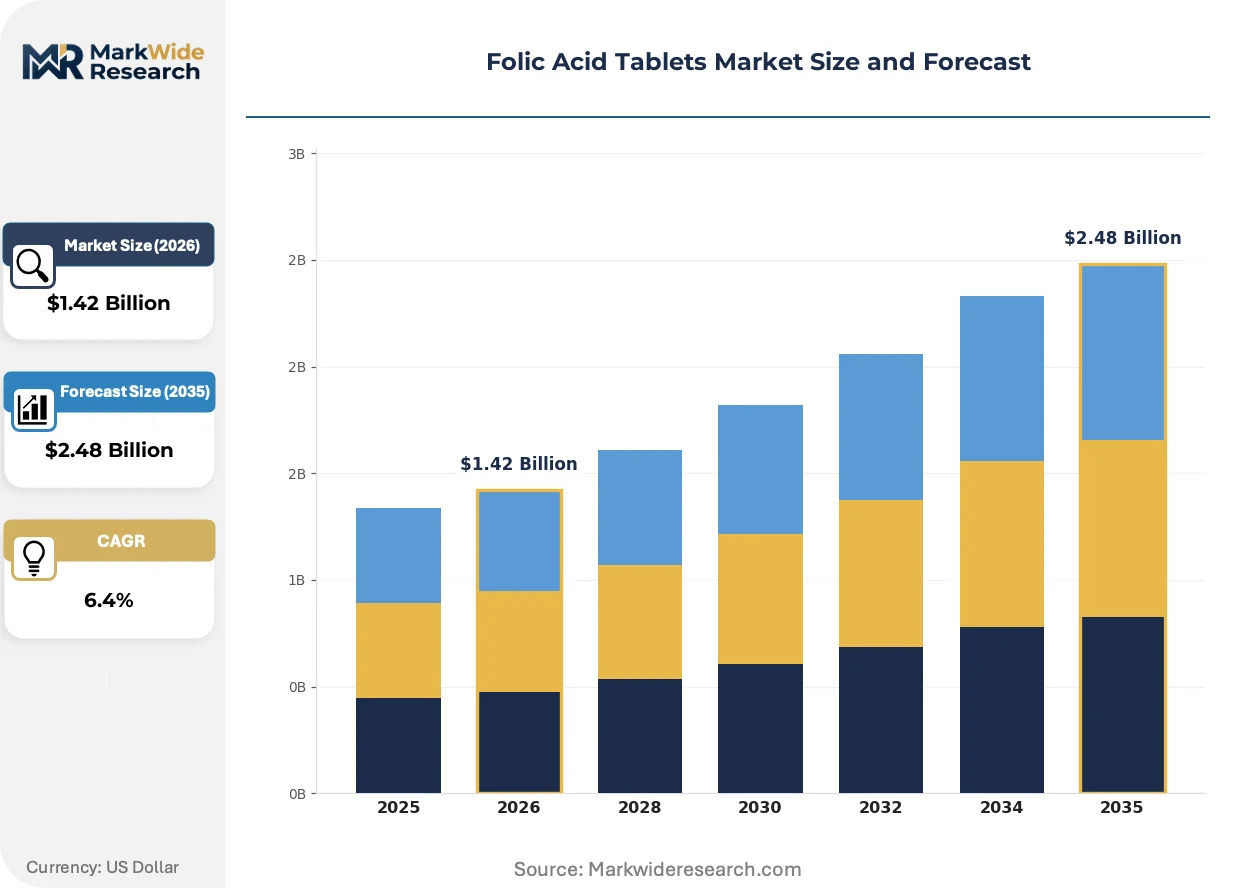
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic, Brand Name, Multivitamin, Customized Formula Dosage Form: Tablet, Capsule, Powder, Liquid Distribution Channel: Pharmacy, Online Retail, Hospital, Supermarket End User: Pregnant Women, Fertility Patients, Adults, Children |
| Companies Covered | BASF SE, Zydus Pharmaceuticals Ltd., Medicamen Biotech Ltd., Jiangxi Tianxin Pharmaceutical Co. Ltd., DSM NV, Emcure Pharmaceuticals Ltd., Parchem Fine & Specialty Chemicals, Nantong Changhai Food Additive, Xinfa Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folic Acid Tablets Market Trends and Innovations
Formulation science is converging with digital health infrastructure to reshape how folic acid reaches end-users, with manufacturing technology, regulatory data requirements, and patient access channels all undergoing simultaneous recalibration.
Direct compression with coprocessed excipients is hybridizing tablet manufacturing workflows. Prenatal supplement contract manufacturers in North America and Europe are adopting roller-compaction feed systems that eliminate wet-granulation drying steps, cutting batch cycle times by half. This process convergence is eroding the cost barrier that historically separated high-volume generic producers from specialized methylfolate formulators.
REACH and RoHS compliance documentation is tightening traceability requirements for synthetic folic acid entering European pharmaceutical supply chains. ECHA substance registration obligations now extend to residual solvent profiles in crystallization steps, forcing API suppliers to revalidate purification protocols. German and French tablet packagers are responding by consolidating supplier audits and demanding third-party certificates of analysis with every lot.
Subscription-based replenishment is displacing acute prescription fulfillment for prenatal folic acid. Telehealth platforms bundle 90-day tablet supplies with virtual obstetric consultations, bypassing traditional pharmacy channels. This channel shift concentrates most visibly in the United States, where employer-sponsored maternal health programs negotiate direct-to-patient delivery contracts that lock in brand loyalty before conception planning begins.
Folic Acid Tablets Market Segmentation
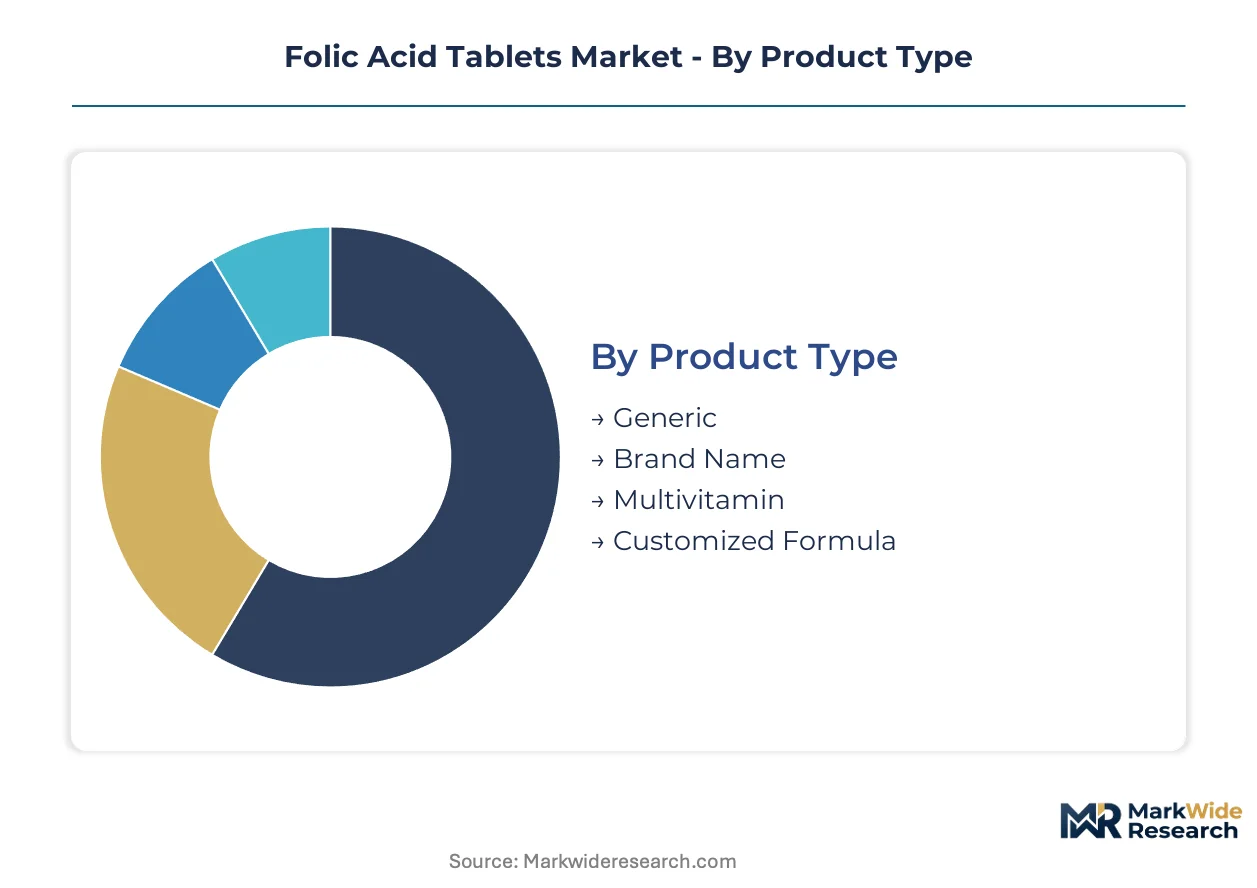
Folic acid tablet segmentation reveals how formulation economics, channel access, and patient specificity interact to determine competitive positioning. Understanding these divides exposes where margin compression threatens incumbents and where premium positioning remains defensible.
Product Type:
Mature commodity formats dominate volume throughput while emerging bioactive variants command pricing power through clinical differentiation.
- Generic:Synthetic pteroylglutamic acid at 400–800 microgram doses, manufactured through direct compression or wet-granulation batch processes. WHO Essential Medicines List inclusion locks in government tender volumes across Brazil's ANVISA-mandated prenatal programs and India's state-level maternal health initiatives.
- Customized Formula:Methylfolate isomers targeting MTHFR polymorphism patients who cannot metabolize standard folic acid. Rising diagnosis rates among US prenatal populations pull prescribing toward these bioactive variants that bypass metabolic conversion bottlenecks.
- Brand Name:Patent-protected formulations with extended-release coatings or proprietary excipient blends that improve gastric tolerability.
- Multivitamin:Folic acid bundled with iron, B12, and D3 in prenatal complexes, competing on convenience rather than folate specificity.
Generic handles the majority of throughput; Customized Formula is the fastest mover on share.
Dosage Form:
Cost tier separation runs through manufacturing complexity, with simple compression formats at the base and specialized delivery systems at the premium extreme.
- Tablet:Direct-compression tablets with coprocessed excipients now dominate high-volume output, with roller-compaction feed systems cutting batch cycle times by half versus legacy wet-granulation. Continuous manufacturing adoption in North American and European contract manufacturing facilities erodes the cost barrier between generic and specialized producers.
- Capsule:Gelatin or HPMC shells accommodate methylfolate powders sensitive to tablet compression heat, serving the MTHFR-diagnosed segment where powder integrity matters.
- Powder:Bulk folic acid for institutional compounding pharmacies and food fortification programs.
- Liquid:Pediatric and geriatric formats where swallowing difficulties prevent solid dosing, typically flavored and preserved for stability.
Tablet commands institutional procurement; Capsule climbs the fastest as methylfolate prescribing expands.
Distribution Channel:
Customer access patterns fragment across acute prescription fulfillment, subscription-based replenishment, and self-directed retail purchase.
- Pharmacy:Brick-and-mortar dispensaries retain the largest transaction share for acute prescriptions, particularly in markets with strict pharmacist counseling requirements for prenatal supplements.
- Online Retail:Telehealth platforms in the United States bundle 90-day folic acid supplies with virtual obstetric consultations, bypassing traditional pharmacy channels and capturing patient adherence data for employer-sponsored maternal health programs.
- Hospital:Inpatient and outpatient clinic dispensing for high-risk pregnancies and fertility treatment protocols.
- Supermarket:Mass-market dietary supplement aisles serving pre-conception planning and general wellness consumers.
Pharmacy retains volume leadership; Online Retail gains share fastest through subscription bundling.
End User:
Application severity stratifies from preventive population health to targeted therapeutic intervention.
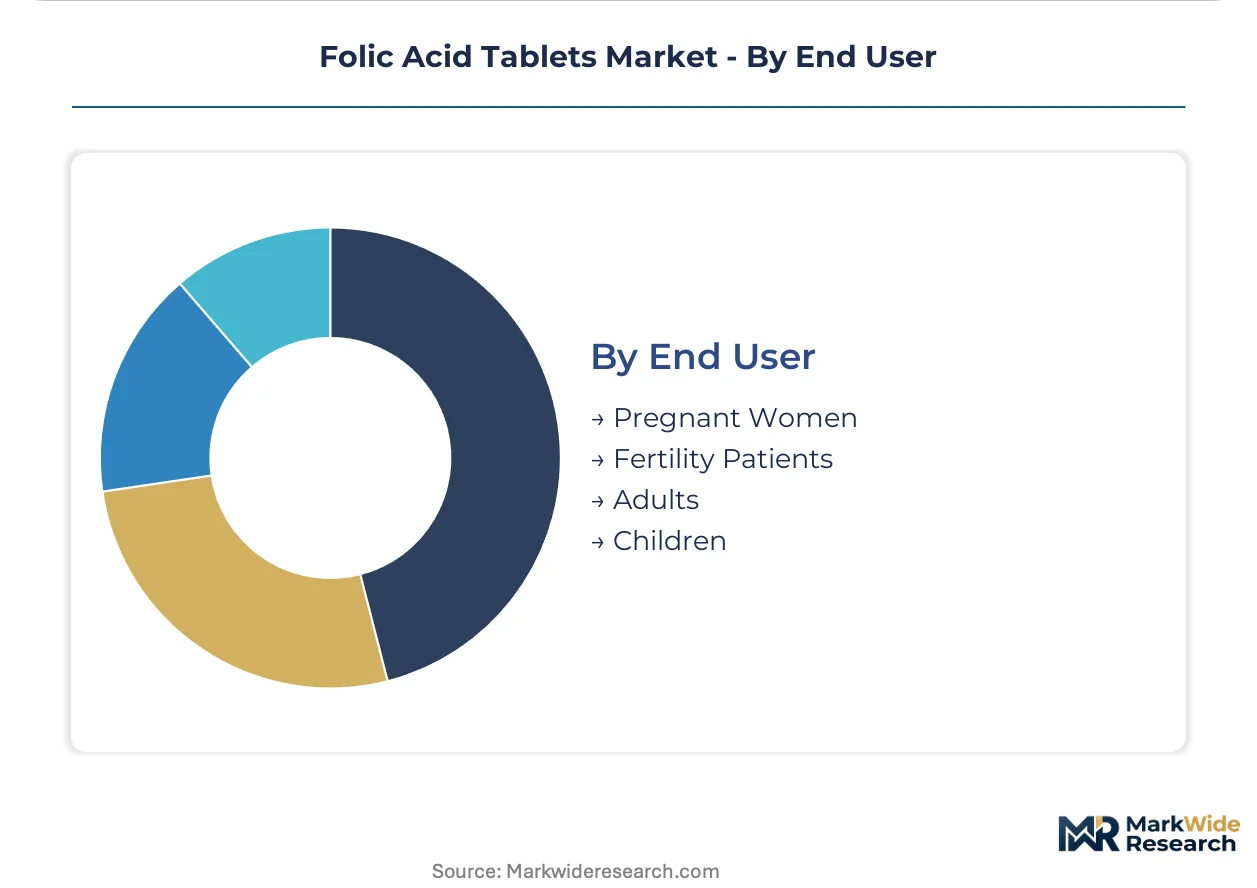
- Pregnant Women:Neural tube defect prophylaxis drives the core demand base, with Brazil's national prenatal mandate and India's Maharashtra and Gujarat state initiatives concentrating procurement in public-sector channels.
- Fertility Patients:Pre-conception loading doses and assisted reproduction support protocols require higher-dose regimens, often prescribed as methylfolate to optimize implantation outcomes in MTHFR-positive candidates.
- Adults:Cardiovascular and cognitive health applications in aging populations, competing against homocysteine-lowering alternatives.
- Children:Pediatric formulations for neural development support, typically liquid or chewable formats with masking flavors.
Pregnant Women absorb the majority of volume; Fertility Patients show the steepest expansion trajectory as pre-conception genetic screening normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports fermentation-derived folic acid active pharmaceutical ingredients to tablet formulators in Brazil and India, creating a tripolar trade flow that concentrates upstream supply in Jiangsu province while downstream demand fragments across maternal health programs in São Paulo and Mumbai.
United States
Telehealth subscription bundling drives channel innovation as virtual prenatal platforms capture patient adherence data through employer-sponsored maternal health programs. The FDA maintains strict labeling requirements under 21 CFR 101.79 for neural tube defect prevention claims. New Jersey and Pennsylvania host contract manufacturing facilities adopting continuous manufacturing lines to compress batch-to-batch variability.
Brazil
ANVISA-mandated prenatal supplementation protocols lock in institutional procurement volumes for public-sector tenders across state health systems. National maternal health programs now require folic acid distribution through primary care networks. São Paulo state concentrates pharmaceutical distribution infrastructure serving the southeastern industrial corridor.
India
Maharashtra and Gujarat state maternal health initiatives concentrate demand growth in western industrial corridors with established pharmaceutical distribution networks. CDSCO enforces BIS purity standards for domestic manufacture while PLI scheme incentives expand active pharmaceutical ingredient capacity in Telangana and Andhra Pradesh. Hyderabad anchors fermentation-based API production outside legacy Chinese supply clusters.
Germany
REACH and RoHS compliance documentation tightens traceability requirements for synthetic folic acid entering pharmaceutical supply chains. ECHA substance registration obligations extend to residual solvent profiles in crystallization steps. Bavaria and Baden-Württemberg host tablet packagers consolidating supplier audits and demanding third-party certificates of analysis with every lot.
China
Jiangsu province fermentation facilities anchor global active pharmaceutical ingredient output for tablet producers worldwide. NMPA requires bioequivalence data for folic acid tablet approvals, tightening quality benchmarks that filter substandard producers. Yangtze River Delta industrial clusters face single-geography risk concentration as global tablet producers depend on eastern Chinese supply.
Folic Acid Tablets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The market structure separates upstream active pharmaceutical ingredient fermenters from downstream formulation specialists, with mid-tier contract manufacturers caught between continuous manufacturing adoption costs and legacy wet-granulation asset bases. Three archetypes dominate: backward-integrated chemical conglomerates with petrochemical precursor control, dedicated fermentation specialists with geographic concentration risk, and formulation innovators patenting crystal forms for compressibility advantages. Competitive moves center on capacity expansion in Indian PLI scheme zones and strategic partnerships bundling telehealth subscriptions with auto-refill logistics.
Among European chemical conglomerates, BASF SE and DSM NV exemplify backward-integrated positioning through captive control over pteroylglutamic acid precursor supply chains. Jiangxi Tianxin Pharmaceutical Co. Ltd. represents the fermentation-specialist archetype with volume production anchored in dedicated eastern Chinese facilities. Zydus Pharmaceuticals Ltd. occupies a position within Indian formulation specialists leveraging domestic API incentives to diversify sourcing beyond concentrated Chinese supply clusters.
| Leading Market Players |
|---|
| BASF SE |
| Zydus Pharmaceuticals Ltd. |
| Medicamen Biotech Ltd. |
| Jiangxi Tianxin Pharmaceutical Co. Ltd. |
| DSM NV |
| Emcure Pharmaceuticals Ltd. |
| Parchem Fine & Specialty Chemicals |
| Nantong Changhai Food Additive |
| Xinfa Pharmaceutical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province fermentation facilities anchor global active pharmaceutical ingredient output, concentrating upstream capacity in eastern China's industrial belt and granting volume producers outsized leverage in contract negotiations with downstream tablet formulators across Brazil and India.
Pricing Analysis
Cost-plus contracts with petrochemical feedstock indexation dominate long-term supply agreements between API fermenters and finished dose manufacturers. Three-tier pricing structure across methylfolate premium, direct-compression standard, and wet-granulation economy levels separates bioactive variants from commodity generics. Price differentiation rests on crystal form purity grades and FDA bioequivalence certification tiers. Cost compression in standard folic acid tablets is intensifying as continuous manufacturing adoption erodes batch-process cost advantages. Government tender buyers in Brazil and India exhibit highest price sensitivity, while US telehealth subscription platforms show lowest sensitivity due to bundled service margins.
Supply Chain Analysis
Petroleum-derived aromatic precursors for pteroylglutamic acid synthesis draw from naphtha cracking outputs in China, South Korea, and Germany. Raw material dependencies center on para-aminobenzoic acid, glutamic acid, and pteridine ring structures sourced from specialty chemical intermediates. Single-geography concentration in Jiangsu province creates vulnerability to regional environmental enforcement actions or logistics disruptions. Distribution runs through pharmaceutical wholesale networks in São Paulo and Mumbai, with telehealth platforms building direct-to-patient fulfillment infrastructure in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth subscription bundling represents a service-attach opportunity expanding faster than tablet manufacturing, with virtual prenatal platforms capturing recurring revenue through auto-refill logistics and remote physician consultations.
For Market Incumbents: Build regulatory moats around methylfolate medical food classifications before FDA determinations finalize. Secure backward integration into fermentation capacity through India's PLI scheme incentives in Telangana and Andhra Pradesh. Patent crystal form improvements that enhance tablet compressibility to defend against continuous manufacturing cost compression from generic rivals.
For New Entrants and Emerging Players: Build out telehealth platform partnerships in the United States where employer-sponsored maternal health programs consolidate procurement. Target fertility patient segments in Maharashtra and Gujarat where pre-conception genetic screening penetration remains below prenatal program saturation. Pursue white-label manufacturing contracts with virtual care providers seeking bundled supplement fulfillment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with continuous manufacturing capability and methylfolate regulatory clarity. Five-to-ten year viability hinges on channel control migration from pharmacy dispensing to subscription platforms. Acquisition targets should demonstrate process analytical technology expertise and telehealth integration partnerships. Monitor FDA L-methylfolate classification determinations as the key inflection signal for premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Roller-compaction feed systems cut batch cycle times by half versus wet-granulation in North American contract facilities. |
| Backward Integration into API Fermentation | Indian PLI scheme incentives in Telangana attract capacity expansion outside concentrated Jiangsu supply clusters. |
| Methylfolate Regulatory Positioning | Pending FDA medical food determinations create first-mover windows for bioactive folate variants targeting MTHFR patients. |
| Telehealth Platform Partnerships | Virtual obstetric consultations bundled with 90-day auto-refill programs capture adherence data and employer contracts. |
| REACH Compliance Documentation | ECHA substance registration obligations force API suppliers to revalidate residual solvent profiles for European packagers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, CDSCO regulatory affairs leads, hospital procurement managers at Mumbai and São Paulo health systems, and telehealth platform operations directors; combined with secondary validation through FDA 21 CFR filings, ANVISA prenatal program tenders, ECHA REACH registrations, and Indian customs API import records. Bottom-up volume triangulation across dosage form segments was cross-checked against top-down value estimates from pharmaceutical trade databases.
Forecast inputs considered formulation technology transitions, channel migration patterns, and regulatory classification shifts across the projection horizon. Segmentation dimensions modeled include product type, dosage form, distribution channel, and end-user application severity. CAGRs were derived from normalized historical procurement volumes and projected tender program expansions, with sensitivity testing around methylfolate adoption curves and continuous manufacturing penetration rates.
Sensitivities concentrate around FDA L-methylfolate reclassification timing, Jiangsu province environmental enforcement intensity, and Brazilian state-level tender allocation shifts. Forecasts reflect documented assumptions about telehealth platform growth trajectories and PLI scheme incentive continuity. Cross-checking against WHO Essential Medicines List procurement volumes and national maternal health program budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Cold Remedies Market
Dietary Supplements
Global Oral Electrolyte Solutions Market
Dietary Supplements
Postpartum Health Supplements Market
Dietary Supplements
Global Vitamin D Therapy Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Medicated Confectionery Market
Dietary Supplements
Diabetic Food Market
Dietary Supplements
Global Slimming Aids Market
Dietary Supplements
Soft Gel Capsule Market
Dietary Supplements
Lifestyle-Related Disease Supplements Market
Dietary Supplements
Oral Clinical Nutrition Supplements Market
Dietary Supplements
Postnatal Health Supplements Market
Dietary Supplements
Bone and Joint Health Supplements Market
Dietary Supplements
Glucosamine Market
Dietary Supplements
Hair Loss Supplement Market
Dietary Supplements
Concentrated Angelica Pills Market