
 Dry Mouth Relief Market | 2026-2036
Dry Mouth Relief Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Mouth Relief Market Analysis
The capital-intensity divergence between pharmaceutical-grade manufacturers and consumer health brands is unwinding competitive dynamics across the sector. Procter & Gamble Company leverages its mass-market distribution infrastructure to sustain shelf dominance in retail pharmacies. Sun Pharmaceutical Industries Ltd anchors its position through prescription-focused formulations targeted at therapeutic indications. GlaxoSmithKline plc competes on brand equity built through decades of oral care portfolio investment.
Dry mouth relief encompasses saliva substitutes, stimulants, and moisturizing agents formulated with carboxymethylcellulose, xylitol, or electrolyte complexes to restore oral lubrication and pH balance in patients suffering from xerostomia. Mouthwash formulations command the largest revenue pool due to habitual usage patterns and broad retail availability, though gels capture superior margins through clinical channel positioning and prescription access. Lozenges represent the fastest-expanding product type as portable formats gain traction among seniors managing chronic medication side effects, while natural formulations face margin pressure from inconsistent botanical sourcing despite consumer preference tailwinds.
FDA OTC monograph reforms and EPA manufacturing facility standards jointly determine product labeling claims and production compliance costs for market participants. ISO 13485 quality management requirements for medical device-classified oral moisturizers create additional certification barriers for new entrants. Stakeholders must monitor evolving pharmacovigilance expectations around biologic saliva stimulants as regulatory scrutiny intensifies for products positioned between cosmetics and therapeutics.
Market Dynamics
FDA OTC monograph reforms are compressing product development timelines while simultaneously elevating compliance thresholds for saliva substitute manufacturers, forcing portfolio rationalization across therapeutic and cosmetic positioning strategies.
Growth Catalysts
- EMA Medical Device Classification:European regulators are streamlining pathways for oral moisturizers meeting MDR requirements, accelerating clinical channel penetration for ISO 13485-certified manufacturers.
- Oncology Palliative Care Integration:Chemotherapy-induced xerostomia protocols at major cancer centers now mandate prophylactic oral lubrication, embedding dry mouth relief into standard supportive care workflows.
- Carboxymethylcellulose Formulation Advances:Next-generation polymer matrices extend mucosal adhesion duration, improving patient compliance metrics and reducing reapplication frequency burdens.
Market Restraints
- Xylitol Supply Concentration:Birch bark and corn cob extraction capacity clusters in Chinese and Finnish processing facilities, exposing formulators to raw material availability volatility.
- Biologic Saliva Stimulant Regulatory Ambiguity:FDA positioning of peptide-based secretagogues between drug and device categories creates protracted premarket review timelines and labeling uncertainty.
- Natural Botanical Standardization Deficits:Inconsistent aloe vera and chamomile active compound profiles from Indian and Mexican agricultural sources degrade batch reproducibility and therapeutic claim defensibility.
Strategic Opportunities
- Geriatric Dental Clinic Networks:Japan's aging population density and METI-supported preventive oral health initiatives create concentrated demand nodes for prescription-grade moisturizing systems.
- Direct-to-Patient Subscription Models:Chronic medication users managing antidepressant or antihypertensive side effects represent addressable cohorts for automated replenishment platforms bypassing traditional pharmacy shelf competition.
- US IRA Preventive Care Provisions:Expanded Medicare coverage for oral health assessments associated with polypharmacy management opens reimbursement pathways for clinically positioned moisture replacement therapies.
Industry Challenges
- ISO 13485 Certification Timeline Compression:Medical device quality management system implementation demands 18-24 month validation cycles that strain mid-tier manufacturer cash reserves.
- Electrolyte Complex Stability Expertise Scarcity:Formulation chemists capable of optimizing calcium-potassium-bicarbonate equilibria for extended shelf life command premium compensation in tight labor markets.
- Legacy Distribution Contract Renegotiation:Retail pharmacy slotting fee structures established during consumer health brand dominance resist margin accommodation for clinically differentiated entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Mouth Relief Market |
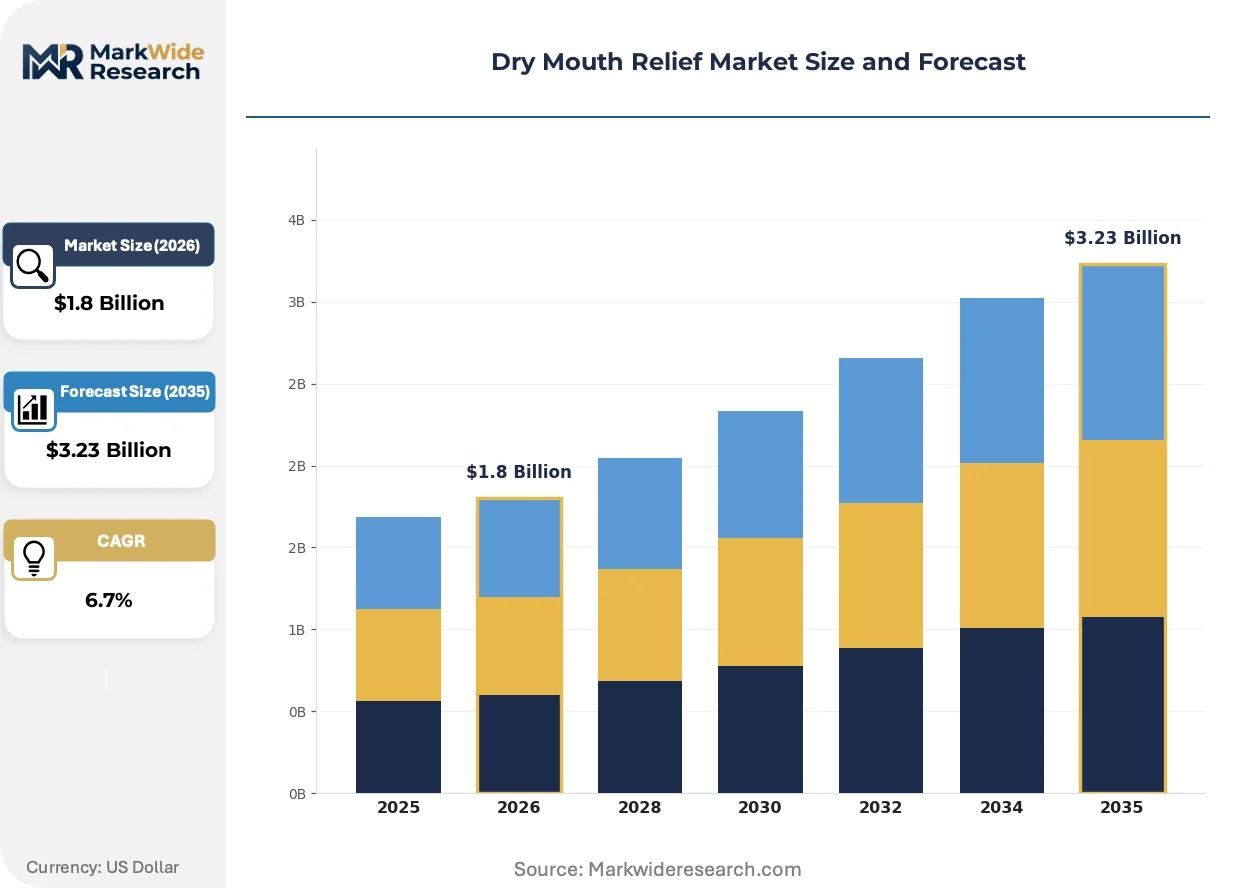
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mouthwash, Lozenges, Sprays, Gels End User: Adults, Seniors, Children, Patients Distribution Channel: Pharmacies, Supermarkets, Online Stores, Health Stores Formulation: Natural, Prescription, Over-the-Counter, Others |
| Companies Covered | Procter & Gamble Company, Sun Pharmaceutical Industries Ltd, GlaxoSmithKline plc, Chattem, Church & Dwight Co., Inc., Colgate-Palmolive Company, 3M Company, Biotène, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Mouth Relief Market Emerging Trajectories
Portable delivery formats and connected health integration are displacing conventional bottle-and-cup consumption patterns, while regulatory clarity efforts on both sides of the Atlantic reshape competitive positioning between cosmetic and therapeutic claims.
Micro-encapsulated saliva stimulant strips are miniaturizing active ingredient delivery into dissolvable polymer substrates no larger than postage stamps. Oncology outpatient departments and long-term care facilities are adopting these formats at accelerated procurement velocities to reduce nursing administration burdens. This miniaturization is compressing packaging material costs and enabling discrete patient self-management outside institutional settings.
REACH chemical substance registration requirements are extending disclosure obligations to polymer additives and flavoring compounds previously exempt from full dossier submission. European manufacturers face reformulation costs or supply chain requalification for non-compliant excipient sources. Mouthwash categories containing synthetic sweeteners and preservative systems bear the heaviest compliance burden, driving accelerated natural alternative substitution.
Hospital procurement consortia are consolidating oral care purchasing through centralized formulary committees that prioritize contract reliability over brand loyalty. Academic medical centers and integrated delivery networks in Germany and the United States are displacing fragmented individual clinic ordering with enterprise-wide agreements specifying clinical efficacy endpoints. This concentration is most visible in oncology and rheumatology service lines where xerostomia prevalence justifies volume commitment thresholds.
Dry Mouth Relief Market Segmentation
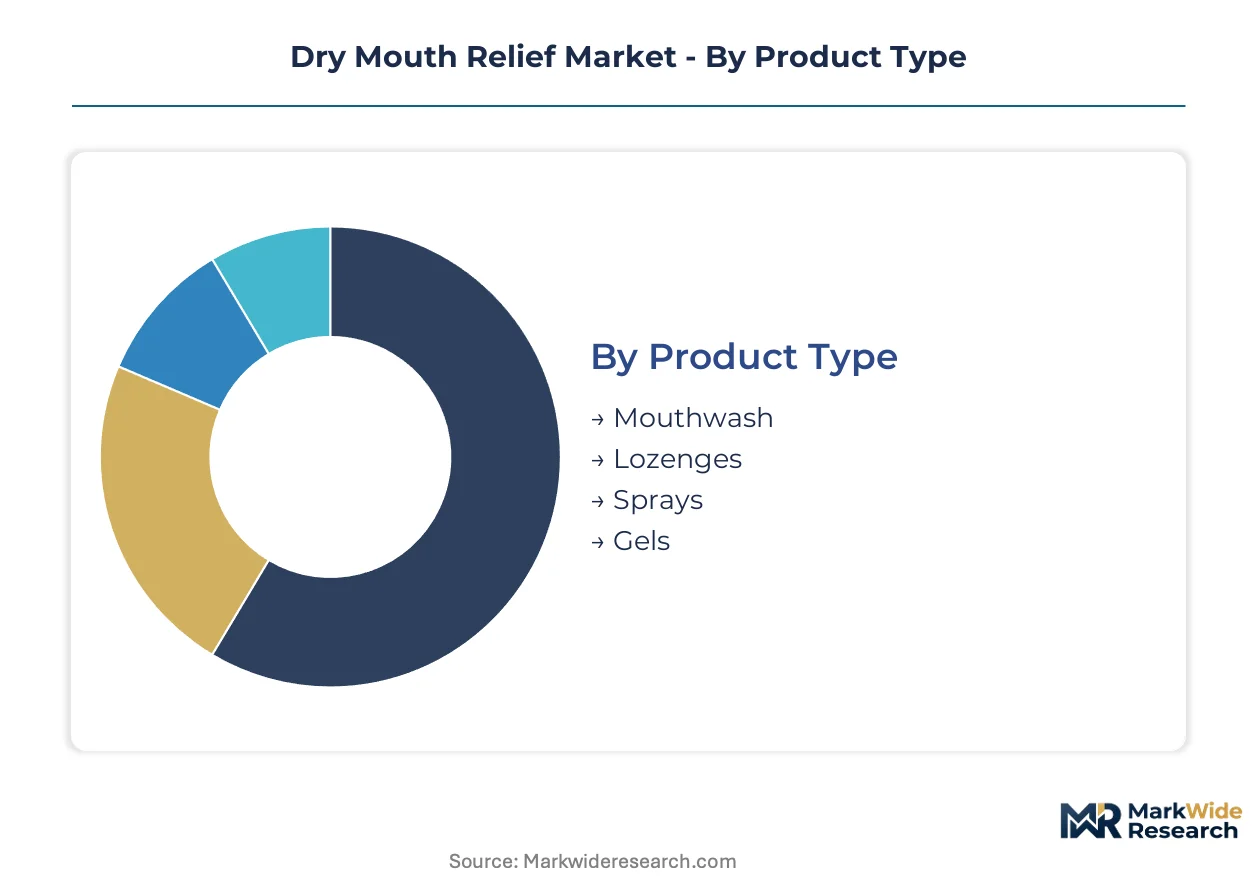
Dry mouth relief manufacturers navigate distinct margin architectures across product formats, patient demographics, and regulatory positioning. Segment-specific formulation costs and channel access determine profitability trajectories for saliva substitute portfolios.
Product Type:
Mouthwash formulations generate the deepest revenue pools through habitual consumption patterns, though margin compression intensifies in mass retail channels.
- Mouthwash:Liquid formulations incorporating carboxymethylcellulose and electrolyte complexes dominate pharmacy shelf space. United States retail chains sustain volume leadership through private-label expansion, while oncology outpatient departments in Germany specify clinical-grade variants with pH-buffering claims.
- Lozenges:Portable dissolvable formats containing xylitol and saliva stimulants are climbing the fastest as polypharmacy patients seek discrete management of antidepressant-induced xerostomia. Japan's geriatric dental clinics are standardizing lozenge protocols for dry mouth prevention.
- Sprays:Metered-dose delivery systems offer rapid mucosal coating for acute symptom relief. Hospital procurement consortia favor spray formats for bedside administration efficiency.
- Gels:High-viscosity polymer matrices command premium positioning through prescription access and extended adhesion duration. Clinical channel penetration in oncology and rheumatology service lines sustains margin premiums.
Mouthwash holds installed capacity. Lozenges is rotating up the share rankings.
End User:
Patient acuity and reimbursement eligibility create tiered pricing architecture across demographic segments.
- Adults:Working-age patients managing antihypertensive or anticholinergic side effects drive over-the-counter replenishment cycles. Direct-to-patient subscription platforms are capturing this cohort through automated delivery bypassing pharmacy intermediaries.
- Seniors:Polypharmacy prevalence and age-related salivary gland hypofunction concentrate demand in Medicare-eligible populations. United States IRA preventive care provisions are expanding reimbursement for clinically positioned moisture replacement in this segment.
- Children:Pediatric formulations require flavor masking and dosage precision for rare autoimmune conditions. Regulatory scrutiny from FDA on excipient safety elevates compliance costs for juvenile-targeted products.
- Patients:Chemotherapy recipients and Sjögren's syndrome sufferers represent the highest-acuity subset with prescription-grade requirements. Major cancer centers now embed prophylactic oral lubrication into standard supportive care workflows.
Seniors anchor volume concentration. Patients is deepening margin capture through therapeutic positioning.
Distribution Channel:
Channel control determines brand visibility and pricing autonomy for saliva substitute manufacturers.
- Pharmacies:Brick-and-mortar drugstore chains and independent dispensaries maintain category leadership through pharmacist recommendation authority. Slotting fee structures established during consumer health brand dominance resist margin accommodation for clinically differentiated entrants.
- Supermarkets:Mass merchandisers emphasize value-tier mouthwash placement with aggressive private-label substitution. REACH chemical disclosure requirements are accelerating natural alternative adoption in European grocery channels.
- Online Stores:E-commerce platforms enable chronic medication users to establish automated replenishment for lozenge and spray formats. Subscription economics bypass traditional pharmacy shelf competition.
- Health Stores:Specialty retailers emphasize botanical formulations with aloe vera and chamomile positioning despite batch reproducibility challenges from inconsistent agricultural sourcing.
Pharmacies retain recommendation leverage. Online Stores is expanding fastest through subscription infrastructure deployment.
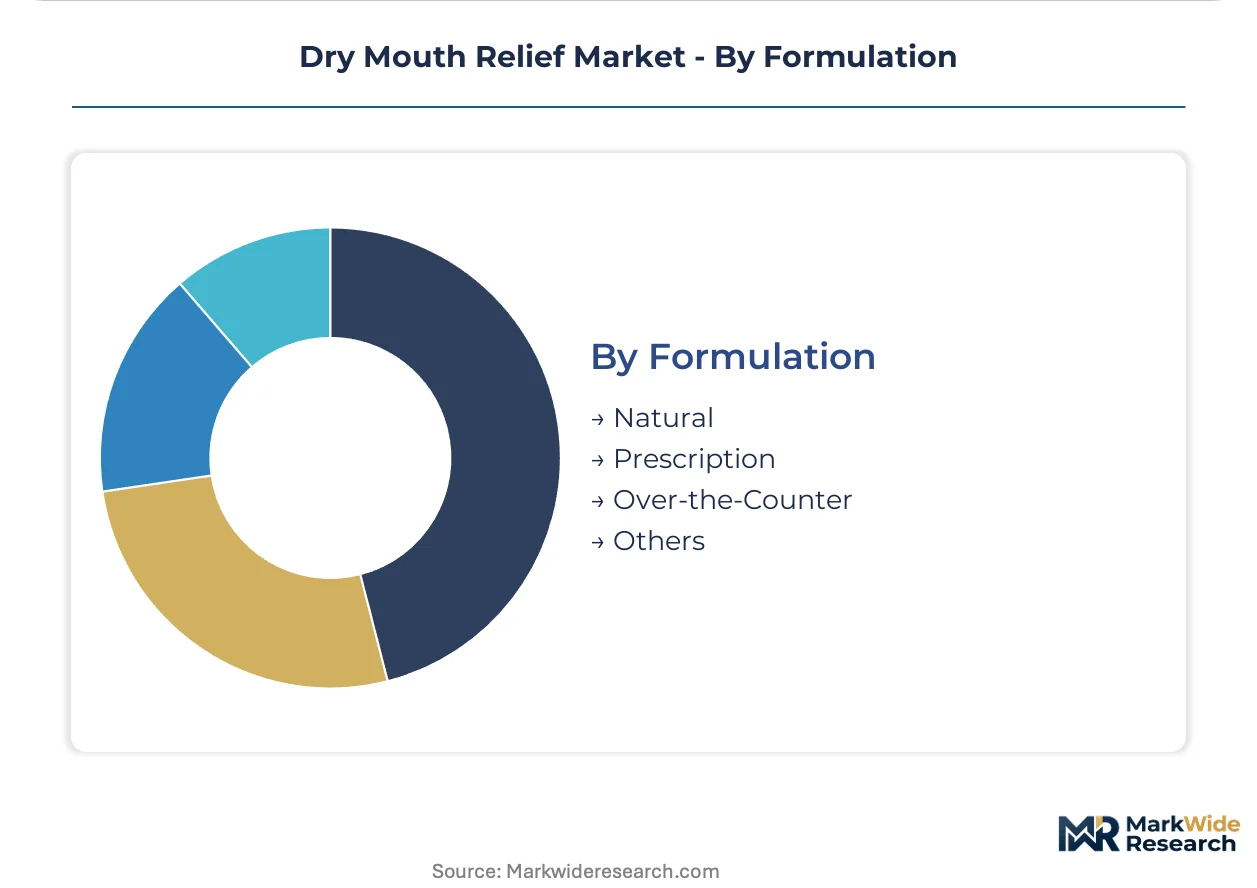
Formulation:
Regulatory classification boundaries between cosmetic and therapeutic claims reshape competitive positioning.
- Natural:Botanical-derived moisturizers face margin pressure from inconsistent aloe vera and chamomile active compound profiles. Indian and Mexican agricultural sourcing variability degrades therapeutic claim defensibility.
- Prescription:Medical device-classified oral moisturizers under FDA and EMA frameworks command premium pricing through clinical efficacy endpoints. ISO 13485 certification requirements create 18-24 month validation barriers for new entrants.
- Over-the-Counter:FDA OTC monograph reforms are compressing development timelines while elevating compliance thresholds for saliva substitute registration. Mouthwash categories with synthetic preservatives bear the heaviest reformulation burden.
- Others:Hybrid positioning strategies and compounded pharmacy preparations serve niche patient populations with specific polymer intolerance profiles.
Prescription maintains margin leadership. Over-the-Counter is broadening access through regulatory streamlining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States patients demonstrate low sensitivity to premium pricing for prescription-grade formulations. German and Japanese buyers exhibit moderate elasticity, prioritizing clinical efficacy over cost. Indian and Brazilian markets remain highly price-sensitive, driving volume through accessible over-the-counter alternatives.
United States
Aging demographics and polypharmacy prevalence sustain patient volumes for moisture replacement therapies. The FDA's expanded OTC monograph review process is compressing product development timelines while elevating compliance thresholds. Major cancer centers in Houston and Boston now embed prophylactic oral lubrication into standard chemotherapy supportive care workflows.
Germany
Hospital procurement consortia concentrate oral care purchasing through centralized formulary committees prioritizing contract reliability. REACH chemical substance registration requirements extend disclosure obligations to polymer additives and flavoring compounds. Academic medical centers in Munich and Heidelberg displace fragmented clinic ordering with enterprise-wide agreements specifying clinical efficacy endpoints.
Japan
Geriatric dental clinic networks create concentrated demand nodes for prescription-grade moisturizing systems. METI-supported preventive oral health initiatives accelerate adoption of standardized lozenge protocols. Tokyo and Osaka medical districts standardize moisture replacement for seniors managing chronic medication side effects.
India
Price-sensitive consumers drive volume through accessible over-the-counter mouthwash and gel alternatives. CDSCO regulatory pathways for medical device-classified oral moisturizers create certification barriers that favor established manufacturers. Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad supply active pharmaceutical ingredients and finished formulations to domestic and export markets.
Brazil
Rising awareness of xerostomia management among chemotherapy patients expands addressable patient populations. ANVISA pharmaceutical registration requirements govern therapeutic claim substantiation for saliva substitutes. São Paulo and Rio de Janeiro oncology service lines increasingly specify prophylactic oral lubrication in supportive care protocols.
Dry Mouth Relief Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the dry mouth relief sector. Mass-market consumer health brands leverage distribution infrastructure and shelf dominance in retail pharmacies. Prescription-focused pharmaceutical manufacturers anchor clinical channel penetration through therapeutic efficacy claims. Medical device specialists occupy premium positioning through ISO 13485 certification and extended mucosal adhesion formulations. Dominant competitive moves include portfolio rationalization between cosmetic and therapeutic positioning strategies, and strategic partnerships with hospital procurement consortia for formulary inclusion.
Among diversified consumer health conglomerates, Procter & Gamble Company exemplifies mass-market distribution leverage, while GlaxoSmithKline plc occupies a position built through decades of oral care portfolio investment. Sun Pharmaceutical Industries Ltd represents the prescription-focused archetype, anchoring therapeutic indication targeting. These three entities collectively illustrate the capital-intensity divergence between pharmaceutical-grade manufacturers and consumer health brands that is unwinding competitive dynamics across the sector.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Sun Pharmaceutical Industries Ltd |
| GlaxoSmithKline plc |
| Chattem |
| Church & Dwight Co., Inc. |
| Colgate-Palmolive Company |
| 3M Company |
| Biotène |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
ISO 13485 certification gates both supplier qualification and price differentiation simultaneously, as medical device-classified oral moisturizers command premium positioning through extended validation cycles while uncertified alternatives compete on accessible over-the-counter shelf pricing. This regulatory threshold compresses margin architecture into distinct tiers: prescription-grade formulations with clinical efficacy claims versus mass-market substitutes with cosmetic positioning.
Pricing Analysis
After-sales revenue through automated replenishment subscriptions drives lifetime value for chronic xerostomia patients managing polypharmacy side effects. Three-tier pricing structure across prescription medical devices, premium over-the-counter clinical variants, and economy mass-market mouthwashes separates reimbursement-eligible formulations from retail-accessible alternatives. Pricing pressure stems from private-label expansion in United States pharmacy chains. Medicare-eligible seniors demonstrate lowest price sensitivity, while Indian and Brazilian consumers exhibit acute elasticity.
Supply Chain Analysis
Xylitol extraction capacity clustering in Chinese and Finnish processing facilities creates raw material chokepoints that expose formulators to availability volatility. Birch bark and corn cob sourcing draws from concentrated agricultural zones, while carboxymethylcellulose polymer matrices rest on petrochemical feedstock networks. Single-source vulnerability in natural botanical supply chains from Indian and Mexican aloe vera cultivation elevates batch reproducibility risk. Distribution runs through hospital procurement consortia and retail pharmacy chains with divergent margin accommodation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as oncology patient volumes rebound post-pandemic treatment backlogs and aging demographics sustain chronic medication side-effect prevalence.
For Market Incumbents: Consolidate formulation expertise around extended-mucosal-adhesion polymer matrices and ISO 13485 certification assets to defend against mid-tier manufacturers seeking clinical channel penetration. Deepen vertical integration into xylitol sourcing through offtake agreements with Finnish and Chinese processors to mitigate raw material volatility exposure. For New Entrants and Emerging Players: Differentiate on direct-to-patient subscription infrastructure targeting antidepressant and antihypertensive users with automated lozenge replenishment, bypassing pharmacy slotting fee barriers. Target Japan's geriatric dental clinic networks as the most penetrable geography, leveraging METI-supported preventive oral health initiatives for rapid protocol adoption. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical device-classified oral moisturizers as FDA and EMA quality management requirements extend validation timelines. Acquisition candidates with established ISO 13485 certification and oncology formulary relationships offer durable positioning. Signal to monitor: FDA OTC monograph finalization timelines for biologic saliva stimulant classification clarity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks prescription channel access and medical device reimbursement pathways under FDA and EMA frameworks. |
| Direct-to-Patient Subscription Launch | Bypasses retail pharmacy slotting fees and captures chronic medication users through automated replenishment economics. |
| Hospital Procurement Consortium Partnership | Secures formulary inclusion at major cancer centers embedding prophylactic oral lubrication into chemotherapy protocols. |
| Xylitol Supply Agreement | Captive sourcing from Finnish birch bark processors mitigates raw material volatility and batch reproducibility risk. |
| Micro-Encapsulated Strip Development | Miniaturized dissolvable formats reduce nursing administration burdens in oncology outpatient departments and long-term care. |
Methodological Framework
Initial hypotheses were tested against primary input from formulary directors at hospital procurement consortia, regulatory affairs leads at saliva substitute manufacturers, oncology palliative care specialists, and pharmacy category buyers, then refined through secondary validation against FDA OTC monograph proceedings, EMA MDR classification databases, hospital procurement contract disclosures, and REACH chemical registration dossiers. Bottom-up patient volume modeling and top-down revenue triangulation converged on segment-specific estimates.
Variance decomposition across product type, end-user acuity, distribution channel control, and regulatory positioning tiers structured the analytical framework. CAGRs were derived from patient population growth, polypharmacy prevalence trajectories, and reimbursement expansion assumptions throughout the forecast period. Oncology service line expansion and geriatric dental clinic protocol standardization served as key volume drivers in the projection model.
Decision-makers should treat outputs as directional under stable FDA and EMA regulatory timelines; material deviation in biologic saliva stimulant classification would warrant model refresh. Practitioners should keep alternative scenarios live as xylitol supply concentration and REACH chemical disclosure requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Antiseptic Mouthwash Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Global Halitosis Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Adult Oral Care Products Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Oral Mucositis Market
Oral Care
Kids Toothpaste Market
Oral Care
Oral Hygiene Products Market
Oral Care
Baby Oral Care Market
Oral Care
Global Oral Care Products Market
Oral Care
Herbal Toothcare Market
Oral Care
Xerostomia Treatment Market
Oral Care
Oral Thrush Market
Oral Care
Herbal Toothpaste Market
Oral Care
Kids Oral Care Products Market