
 Actinomycosis Market | 2026-2036
Actinomycosis Market Size, Share, and Industry Trends Forecast 2026-2036
Actinomycosis Market Outlook
Hospital procurement channels for intravenous antibiotics is reshaping competitive dynamics in actinomycosis therapeutics. Pfizer Inc. leverages its broad-spectrum penicillin portfolio to sustain institutional contracts across academic medical centers. Novartis AG anchors its position through specialized anti-infective distribution networks in European markets. Merck & Co., Inc. differentiates via R&D intensity in novel anaerobic coverage formulations.
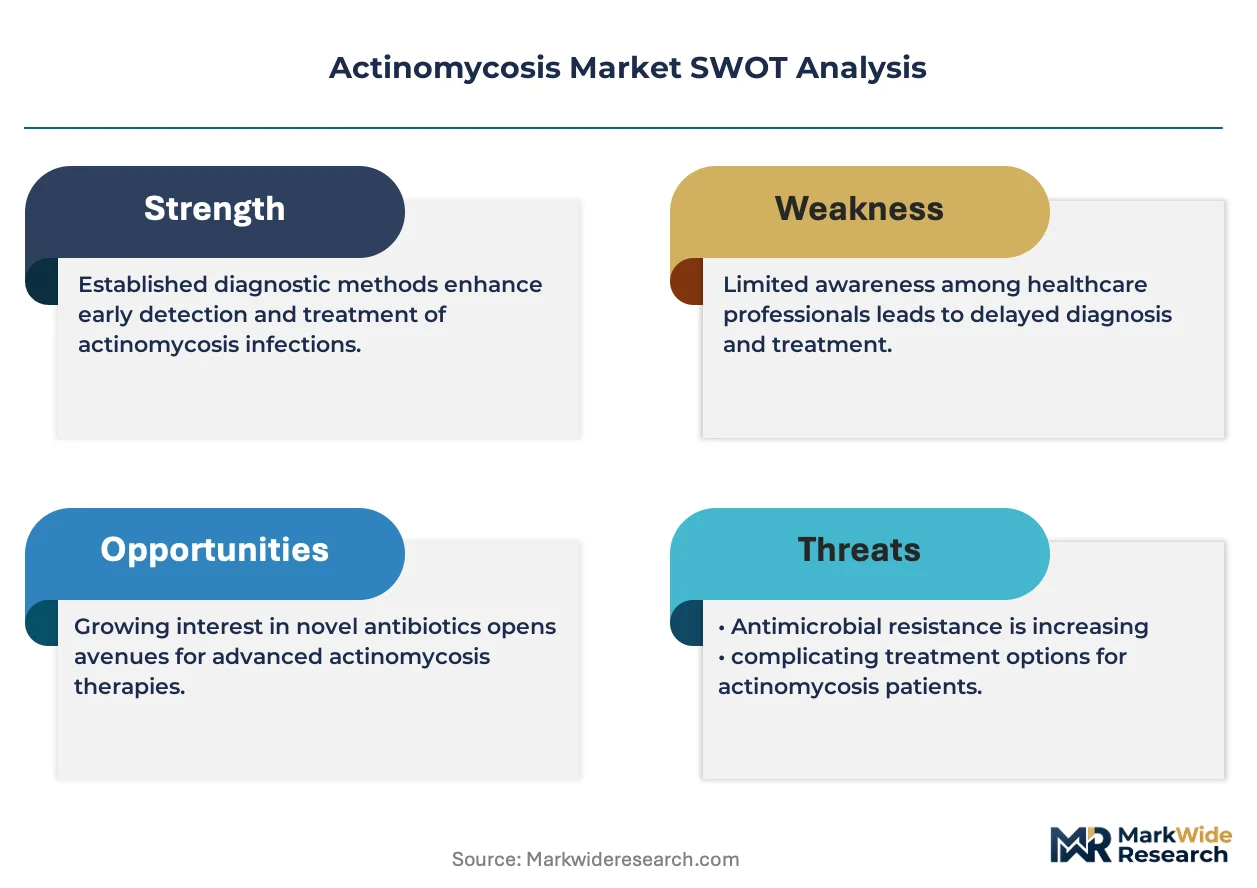
Actinomycosis denotes a chronic granulomatous infection caused by Actinomyces species, filamentous Gram-positive bacteria requiring prolonged high-dose penicillin therapy or tetracycline alternatives for six to twelve months. The condition primarily serves infectious disease and oral-maxillofacial specialists managing refractory abscesses, sulfur granule-containing lesions, and sinus tract formations. Antibiotics dominate current revenue pools due to extended treatment durations and recurrent prescribing needs, while intravenous delivery modes capture premium margins in hospitalized pulmonary and abdominal cases. Dental applications retain steady volume from odontogenic cervicofacial presentations, though pulmonary segments show faster expansion driven by diagnostic imaging advances.
FDA antimicrobial stewardship programs constrain empiric broad-spectrum use, pushing clinicians toward targeted anaerobic therapy with documented microbiological confirmation. EMA pharmacovigilance frameworks and WHO essential medicines lists shape reimbursement access and formulary inclusion across European and developing markets respectively. Stakeholders must monitor diagnostic test adoption rates and stewardship compliance metrics to anticipate shifts from empiric to precision-guided actinomycosis management.
Market Dynamics
FDA antimicrobial stewardship mandates are compressing empiric prescribing windows and forcing microbiological confirmation before anaerobic therapy initiation. Hospital formularies now require documented Actinomyces isolation from sulfur granule specimens, fundamentally altering how infectious disease specialists manage cervicofacial and thoracic presentations.
Growth Catalysts
- Diagnostic Imaging Advances:High-resolution CT and MRI protocols enable earlier detection of actinomycotic lung abscesses and sinus tracts, expanding the addressable patient pool in tertiary pulmonary units.
- EMA Pharmacovigilance Frameworks:Strengthened post-market surveillance for anti-infectives sustains reimbursement access for prolonged penicillin regimens across European hospital networks.
- Oral-Maxillofacial Surgical Volume:Rising odontogenic infection referrals from dental clinics generate steady demand for extended-duration antibiotic protocols in academic medical centers.
Market Restraints
- Penicillin Supply Concentration:API manufacturing for injectable penicillin G concentrates in Chinese and Indian chemical clusters, exposing procurement channels to geopolitical disruption and quality variance.
- Diagnostic Confirmation Delays:Anaerobic culture requirements and extended incubation periods for Actinomyces species create treatment initiation gaps that empiric stewardship protocols increasingly penalize.
- Tetracycline Substitution Pressure:Doxycycline and minocycline alternatives for penicillin-allergic patients face rising resistance surveillance and formulary restriction in US inpatient settings.
Strategic Opportunities
- Molecular Diagnostic Integration:16S rRNA sequencing and MALDI-TOF platforms collapse identification timelines from weeks to hours, creating premium service lines in reference laboratories.
- Home Infusion Channel Expansion:Extended six-to-twelve-month treatment courses position actinomycosis as an anchor indication for ambulatory antimicrobial therapy programs.
- WHO Essential Medicines List Alignment:Penicillin and doxycycline inclusion in core formularies unlocks procurement financing for public sector infectious disease programs in low-resource settings.
Industry Challenges
- Microbiology Laboratory Capacity:Anaerobic culture expertise and extended incubation protocols require specialized technologist training that community hospitals struggle to retain.
- Stewardship Compliance Documentation:FDA-mandated antimicrobial use metrics demand real-time data infrastructure that smaller infectious disease practices lack capital to deploy.
- Cross-Disciplinary Care Coordination:Effective management requires alignment between oral-maxillofacial surgeons, pulmonologists, and infectious disease specialists with fragmented electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Actinomycosis Market |
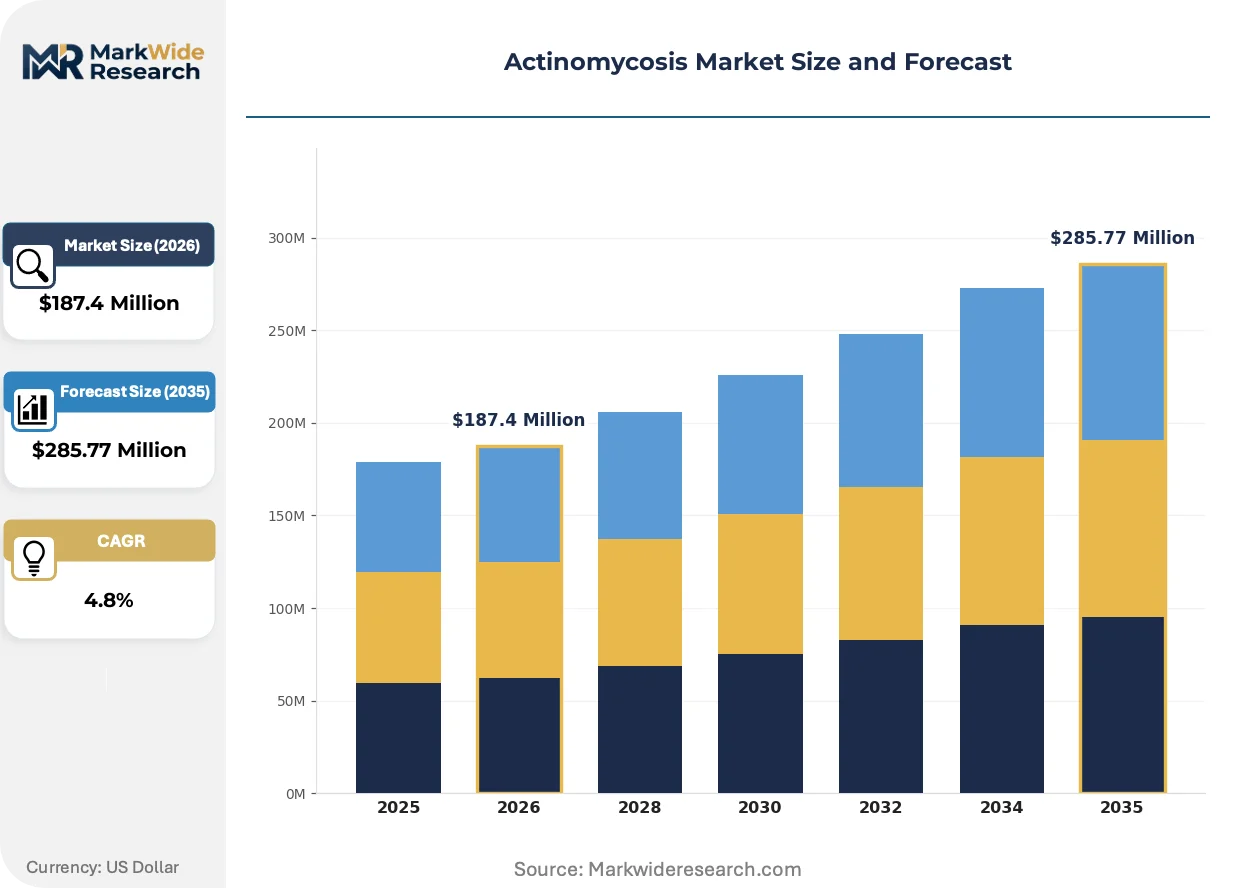
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Intervention, Supportive Care, Vaccines Application: Dental, Pulmonary, Abdominal, Cutaneous End User: Hospitals, Clinics, Research Laboratories, Home Care Delivery Mode: Oral, Intravenous, Topical, Inhalation |
| Companies Covered | Pfizer Inc., Novartis AG, GlaxoSmithKline plc, Merck & Co., Inc., Johnson & Johnson, Sanofi S.A., Roche Holding AG, AbbVie Inc., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Actinomycosis Market Strategic Shifts
Diagnostic acceleration and stewardship digitization are compressing the traditional empiric-to-targeted therapy transition. These forces reshape how actinomycosis cases flow from suspicion through confirmation to prolonged antimicrobial management.
Matrix-assisted laser desorption ionization time-of-flight mass spectrometry (MALDI-TOF) is collapsing species-level identification timelines for Actinomyces isolates. Reference laboratories and large hospital networks deploy these platforms to bypass phenotypic testing bottlenecks. The structural consequence is collapsing revenue capture for extended anaerobic culture services as rapid diagnostics commoditize front-end identification.
FDA antimicrobial stewardship mandates under the 2012 Safety and Innovation Act require documented indication, spectrum, and duration for all inpatient antibiotics. Hospital pharmacy and therapeutics committees enforce these rules through pre-authorization protocols and real-time audit dashboards. Pulmonary and abdominal actinomycosis cases face heightened scrutiny due to overlapping presentations with malignancy and nocardiosis.
Specialized infectious disease pharmacists now anchor multidisciplinary rounds in academic medical centers, replacing traditional physician-driven prescribing autonomy. These clinicians steward formulary compliance and duration optimization, displacing legacy infectious disease consultation models. The United States exhibits the most pronounced shift, where hospital reimbursement ties to antimicrobial use quality metrics.
Actinomycosis Market Segmentation
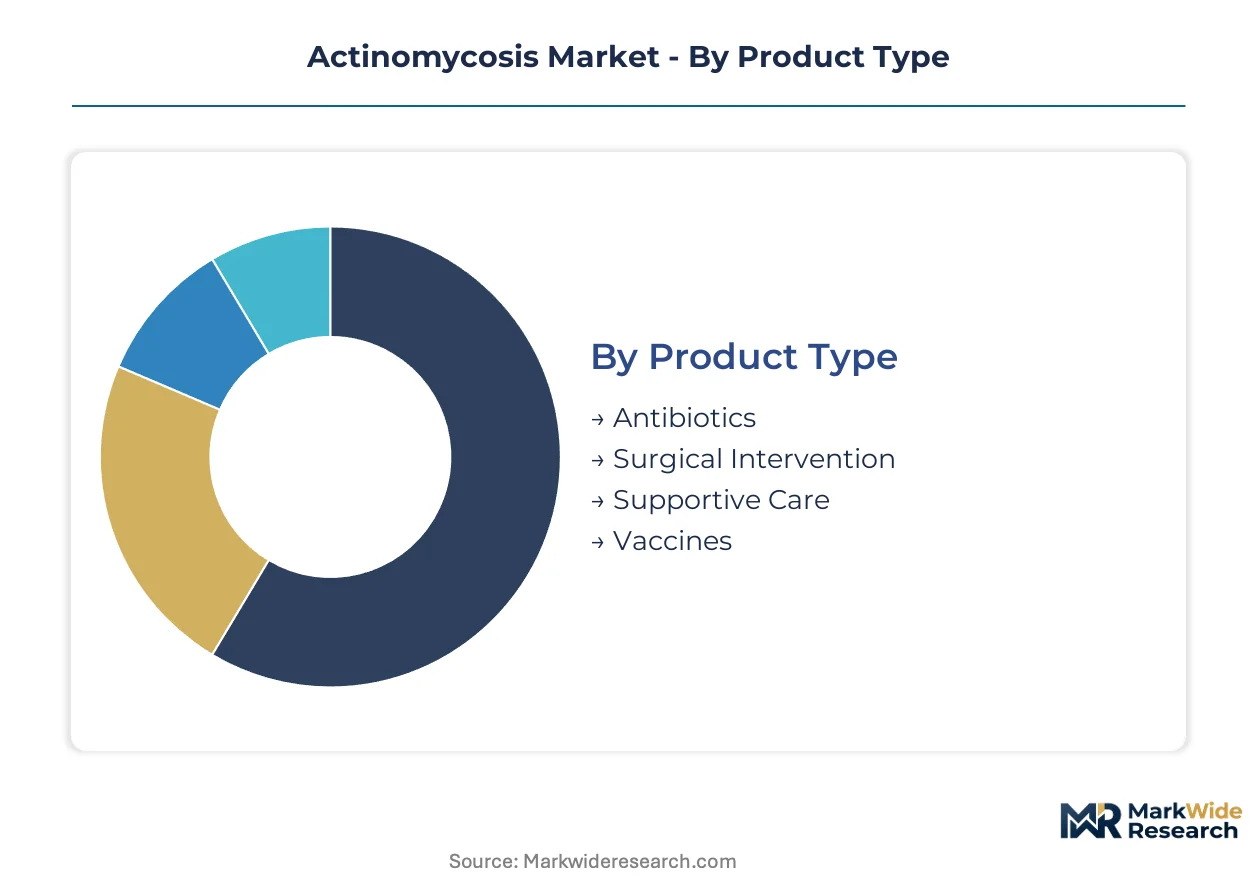
Actinomycosis treatment pathways vary dramatically by anatomical presentation and care setting, creating distinct procurement cycles and reimbursement dynamics. Segmentation reveals where extended-duration antibiotic protocols concentrate versus acute surgical intervention opportunities.
Product Type:
Antibiotics dominate replenishment cycles with six-to-twelve-month treatment courses, while surgical and supportive modalities operate on episodic, case-triggered demand patterns.
- Antibiotics:High-dose penicillin G and tetracycline alternatives form the therapeutic backbone, with IV formulations capturing premium margins in hospitalized thoracic and abdominal cases. Hospital formularies in the United States drive volume through stewardship-mandated prolonged regimens.
- Surgical Intervention:Debridement and drainage procedures address refractory abscesses and sinus tracts, particularly in cervicofacial presentations requiring oral-maxillofacial specialist referral. Tertiary academic centers concentrate this demand.
- Supportive Care:Nutritional support and pain management adjuncts accompany extended antibiotic courses in immunocompromised patient cohorts.
- Vaccines:Development-stage prophylactic candidates target high-risk dental and immunosuppressed populations with limited commercial presence.
Antibiotics anchors the volume base while Surgical Intervention gains share at the steepest rate as diagnostic imaging advances enable earlier lesion localization.
Application:
Cost tiers stratify sharply across anatomical sites, with pulmonary presentations requiring intensive diagnostic workup and prolonged hospitalization versus outpatient-managed dental cases.
- Dental:Odontogenic cervicofacial infections generate steady outpatient volume through dental clinic referrals, with oral-maxillofacial surgeons managing sulfur granule-containing lesions. United States academic medical centers concentrate specialist capacity.
- Pulmonary:Thoracic actinomycosis mimics malignancy on imaging, driving high-resolution CT utilization and invasive sampling before targeted therapy initiation. Diagnostic delays inflate episode costs substantially.
- Abdominal:Pelvic and intra-abdominal presentations require surgical consultation for mass-lesion differentiation from malignancy.
- Cutaneous:Primary skin and soft-tissue involvement remains rare, typically secondary to contiguous spread from deeper foci.
Dental commands the highest case volume while Pulmonary expands most quickly as CT protocol sensitivity improves.
End User:
Customer type determines procurement authority, with hospital pharmacy and therapeutics committees controlling IV antibiotic access versus prescriber-directed outpatient oral therapy.
- Hospitals:Inpatient units manage severe pulmonary and abdominal presentations under antimicrobial stewardship protocols requiring microbiological confirmation. FDA-mandated use metrics shape formulary compliance.
- Clinics:Outpatient infectious disease and oral-maxillofacial practices handle stable cervicofacial cases with oral antibiotic continuation after initial IV loading.
- Research Laboratories:Reference labs deploy MALDI-TOF and 16S rRNA sequencing for rapid Actinomyces speciation, collapsing traditional anaerobic culture timelines.
- Home Care:Ambulatory infusion services capture extended IV-to-oral transition phases in commercially insured populations.
Hospitals dominate value capture while Home Care climbs the fastest as payors push site-of-care migration.
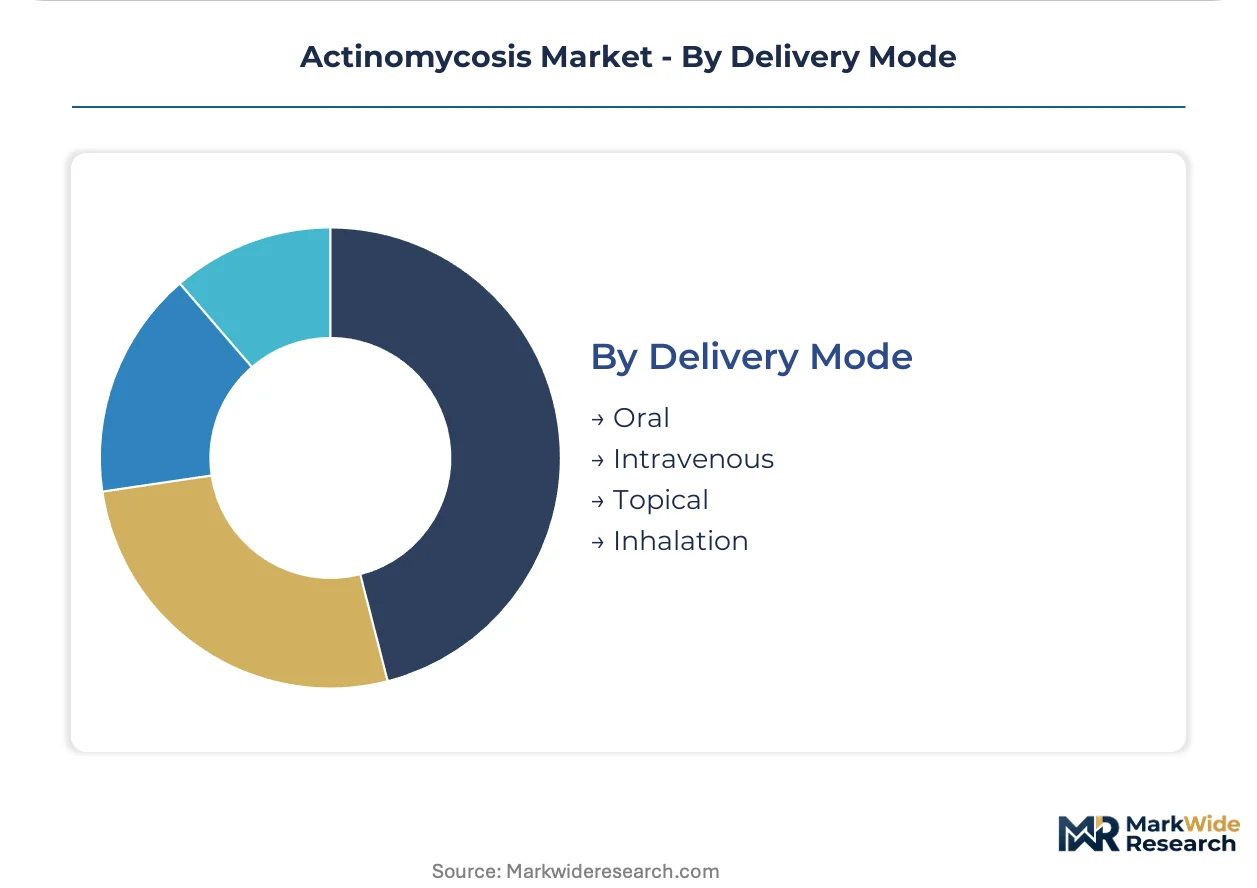
Delivery Mode:
Margin structures invert across administration routes, with hospital-based IV delivery capturing facility fees and drug markup versus thin-margin oral generic dispensing.
- Oral:Penicillin V and doxycycline tablets enable outpatient maintenance therapy after initial IV stabilization, with pharmacy benefit managers influencing formulary placement.
- Intravenous:Penicillin G and clindamycin infusions require hospital or infusion center administration for deep-seated infections, generating per-diem reimbursement.
- Topical:Limited role in wound care adjuncts for cutaneous sinus tract management.
- Inhalation:Investigational aerosolized delivery for pulmonary focal infections with minimal current utilization.
Intravenous delivery retains the highest per-patient revenue while Oral formulations expand volume through stewardship-driven duration extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics hub underwrites Europe's distribution centrality for intravenous anti-infectives, while Singapore's Changi cargo terminals anchor Asia-Pacific supply chain resilience for temperature-controlled antibiotics.
United States
Tertiary care centers in Boston, Houston, and Los Angeles manage the highest volume of refractory thoracic and cervicofacial actinomycosis presentations. FDA antimicrobial stewardship mandates under the 2012 Safety and Innovation Act enforce microbiological confirmation before anaerobic therapy initiation. The Mayo Clinic Rochester campus anchors specialist referral networks for sulfur granule pathology confirmation.
Germany
University hospitals in Berlin, Heidelberg, and Munich concentrate expertise in pulmonary actinomycosis mimicking malignancy on imaging. EMA pharmacovigilance frameworks sustain reimbursement access for prolonged penicillin regimens across statutory health insurance networks. The Rhine-Main biotech cluster near Frankfurt hosts reference laboratories deploying MALDI-TOF rapid speciation platforms.
United Kingdom
London teaching hospitals and Manchester academic centers drive diagnostic imaging protocol standardization for thoracic presentations. NHS England antimicrobial resistance strategies constrain empiric broad-spectrum use in favor of targeted anaerobic coverage. The Cambridge-Oxford corridor anchors molecular diagnostic R&D for 16S rRNA sequencing acceleration.
Japan
Tokyo and Osaka metropolitan hospitals manage odontogenic cervicofacial referrals through integrated dental-infectious disease pathways. PMDA post-market surveillance requirements shape formulary inclusion for extended-duration antibiotic protocols. The Kansai medical device cluster near Osaka pilots rapid anaerobic identification platforms for hospital network deployment.
India
Maharashtra and Karnataka state hospitals report rising pulmonary actinomycosis detection through expanding CT infrastructure in Mumbai and Bengaluru. CDSCO quality control mandates for imported penicillin API influence procurement decisions in public sector programs. The Hyderabad pharmaceutical manufacturing belt supplies generic injectable penicillin to government infectious disease initiatives.
Actinomycosis Market Competitive Environment
On the supply side, the industry is consolidated around institutional antibiotic portfolios with tiered differentiation between broad-spectrum penicillin suppliers and specialized anti-infective distributors. Three archetypes dominate: diversified pharmaceutical conglomerates with hospital formulary anchoring positions, mid-cap generic injectable specialists with API backward integration, and regional distribution networks with cold-chain logistics capabilities. Competitive moves center on antimicrobial stewardship compliance certification and molecular diagnostic co-development partnerships.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Novartis AG occupy anchor positions within hospital procurement channels, while Merck & Co., Inc. exemplifies R&D-intensive positioning in novel anaerobic coverage formulations. These entities represent the institutional-contracting archetype that dominates tertiary care center formularies. Their geographic footprints span North American academic medical centers and European hospital networks respectively, with each exemplifying distinct strategic postures toward antimicrobial stewardship digitization requirements.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Sanofi S.A. |
| Roche Holding AG |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Penicillin API concentration in Chinese and Indian chemical clusters exposes procurement channels to tariff disruption and quality variance, compressing margin spreads between originator and generic injectable tiers while forcing hospital formularies toward dual-source qualification protocols.
Pricing Analysis
Volume-discount tiering separates originator penicillin G from multi-source generic injectables and oral tablet commoditization. Hospital procurement committees extract 15-30% price concessions through annual tender aggregation across academic medical center networks. Penicillin-allergic substitution demand for doxycycline is intensifying cost compression in tetracycline alternatives as resistance surveillance tightens formulary access. Dental clinics exhibit highest price sensitivity due to thin reimbursement margins, while tertiary pulmonary units absorb premium IV pricing through diagnosis-related group bundling.
Supply Chain Analysis
Export-control scrutiny over fermentation-derived antibiotic precursors limits technology transfer to emerging manufacturing jurisdictions. Injectable penicillin G production draws from fermentation capacity in China, India, and Italy, with 7-ACA intermediate supply anchored in Shandong province chemical parks. Single-source dependency on Wuhan and Hyderabad API clusters creates vulnerability to environmental compliance shutdowns. Cold-chain distribution runs through hospital pharmacy and therapeutics committees controlling IV formulary access, with oral generics flowing through retail pharmacy benefit manager networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actinomycosis therapeutics function as a service-attach market where diagnostic confirmation and stewardship compliance layers expand faster than commodity antibiotic volume. Extended-duration therapy protocols create recurring revenue through ambulatory infusion program enrollment and molecular diagnostic co-development.
For Market Incumbents: Insulate institutional formulary positions through backward integration into penicillin API fermentation capacity in India or Italy, reducing exposure to Chinese supply disruption. Anchor contracts with antimicrobial stewardship digitization platforms that embed pre-authorization protocols for competitor substitution. Defend against MALDI-TOF reference laboratory entrants by co-developing rapid anaerobic identification assays with hospital network partners. For New Entrants and Emerging Players: Establish a beachhead in home infusion channel partnerships for six-to-twelve-month oral-to-IV transition protocols, bypassing hospital pharmacy committee gatekeeping. Target underpenetrated oral-maxillofacial specialist practices in United States academic medical centers with point-of-care 16S rRNA sequencing devices. Deploy subscription-based stewardship compliance dashboards as the primary go-to-market wedge against incumbent antibiotic suppliers. For Investors and Strategic Acquirers: The market sits at a stewardship-mandate enforcement phase that favors diagnostic-platform acquirers over pure-play antibiotic manufacturers. Long-term viability hinges on molecular diagnostic substitution for extended anaerobic culture revenue pools. Target acquisition profiles center on MALDI-TOF platform developers with hospital laboratory installed bases. Watch FDA antimicrobial use quality metric adoption rates as the inflection signal for diagnostic pull-through acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Stewardship Compliance Certification | FDA-mandated use metrics embed vendor platforms within hospital formulary decision workflows. |
| Molecular Diagnostic Co-Development | 16S rRNA sequencing partnerships collapse Actinomyces identification timelines from weeks to hours. |
| Home Infusion Channel Expansion | Ambulatory antimicrobial therapy programs capture extended-duration revenue outside inpatient DRG bundling. |
| API Backward Integration | Fermentation capacity in India or Italy reduces exposure to Chinese environmental compliance shutdowns. |
| Specialist Referral Network Anchoring | Oral-maxillofacial surgeon partnerships secure sulfur granule specimen flow for diagnostic confirmation services. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with infectious disease specialists, hospital pharmacy directors, oral-maxillofacial surgeons, and reference laboratory executives; and secondary validation through FDA antimicrobial stewardship guidance documents, EMA pharmacovigilance frameworks, hospital procurement databases, and WHO essential medicines list revisions. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation anchored volume and value estimates.
Forecast inputs encompassed treatment duration assumptions across cervicofacial, pulmonary, and abdominal presentations; IV-to-oral transition rates by payer type; and molecular diagnostic adoption curves in tertiary care centers. Segmentation dimensions included anatomical site, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from log-linear trend fitting across historical antibiotic utilization patterns and projected stewardship compliance penetration.
Macroeconomic conditions sit as an overlay; deviation in hospital reimbursement rates, penicillin API trade flows, or antimicrobial resistance surveillance intensity would shift the trajectory. Forecasts reflect assumptions about FDA mandate enforcement consistency and diagnostic platform cost curves. Cross-checking against CMS Medicare Part B drug spending data and state-level hospital discharge records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Toxoplasmosis Infection Treatment Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Chlamydia Infection Treatment Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Bronchitis Market