
 Injection Practice Pad Market | 2026-2036
Injection Practice Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Practice Pad Market Insights
Medical-grade silicone specification tiers is collapsing the gap between practice pads and live-tissue response, forcing manufacturers to recalibrate material science roadmaps. Laerdal Medical leverages its decades-long anesthesia training heritage to sustain premium positioning across academic medical centers. Simulaids anchors the mid-market through aggressive channel control over emergency response training programs. Nasco Healthcare differentiates via specialized pediatric and geriatric anatomical variants that command higher price realization.
An injection practice pad is a tactile training device, typically layered with silicone or latex composites over foam substrates, engineered to replicate subcutaneous, intramuscular, and intravenous tissue resistance for needle insertion skill development. Manufacturing employs multi-density casting processes to vary puncture feedback across anatomical zones, with durometer readings calibrated to 10-40 Shore A for realistic vessel and muscle simulation. Advanced 3D Models capture the fastest expansion as programs demand anatomical fidelity for ultrasound-guided and landmark-based techniques. Medical Training remains the dominant usage scenario, though Skill Assessment is gaining structural importance as licensing boards embed objective structured clinical examinations into credentialing pathways.
FDA regulates these devices as Class I medical training aids, while ISO 9001 and ISO 13485 certifications govern quality management for manufacturers serving regulated health education markets. The EU Medical Device Regulation imposes additional conformity assessment burdens on pads incorporating active electronic feedback systems. Stakeholders must monitor how accreditation standards evolve toward competency-based metrics rather than hour-count thresholds, as this shift will reshape procurement criteria and product specification requirements.
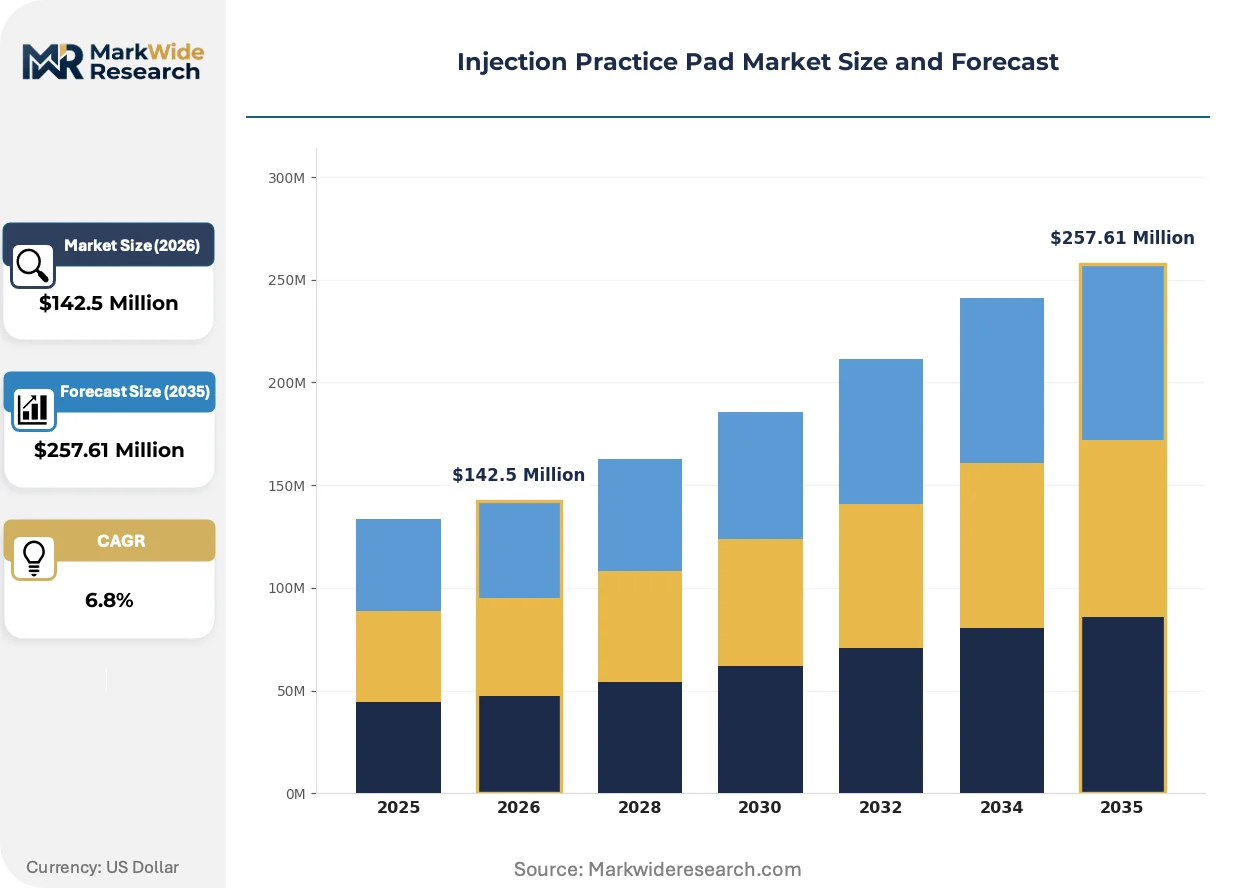
Market Dynamics
Medical-grade silicone specification tiers are collapsing the gap between practice pads and live-tissue response, forcing manufacturers to recalibrate material science roadmaps. FDA clearance pathways for clinical training devices and ISO 13485 certification requirements are elevating the technical bar for market entry.
Growth Catalysts
- Competency-Based Accreditation Mandates:Licensing boards in the United States, Germany, and Japan now embed objective structured clinical examinations into credentialing pathways, driving institutional procurement of high-fidelity training devices.
- Silicone Material Innovations:Multi-density casting processes with durometer readings calibrated to 10-40 Shore A now replicate realistic vessel and muscle simulation, expanding addressable use cases.
- Medical School Curriculum Reform:Simulation-based training programs are systematically replacing cadaver-based instruction across North American and European academic medical centers.
Market Restraints
- Medical-Grade Silicone Cost Volatility:Platinum-cured silicone feedstock prices fluctuate with petrochemical supply chains, compressing margins for manufacturers without backward integration into raw material sourcing.
- EU MDR Conformity Burdens:Pads incorporating active electronic feedback systems face additional assessment requirements under the EU Medical Device Regulation, lengthening time-to-market.
- Reusable Simulator Substitution:Full-body manikins with integrated injection modules threaten to displace standalone pad purchases in high-budget institutional settings.
Strategic Opportunities
- Underpenetrated Indian Medical Education:India's CDSCO regulatory framework for clinical training devices remains nascent, creating first-mover advantage for ISO-certified manufacturers establishing local distribution.
- Pediatric and Geriatric Anatomical Variants:Specialized demographic segments command premium price realization as nursing programs diversify patient-population training.
- Ultrasound-Guided Technique Convergence:Integration of haptic feedback with portable ultrasound training modules opens new product categories for interventional radiology education.
Industry Challenges
- Biomedical Engineer Talent Scarcity:The intersection of silicone polymer science and clinical anatomy expertise remains thinly staffed, constraining R&D velocity.
- ISO 13485 Certification Timelines:Quality management system audits for manufacturers serving regulated health education markets extend 12-18 months, delaying commercialization.
- Legacy Distribution Channel Entrenchment:Established medical supply distributors resist onboarding novel training device categories without proven volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Practice Pad Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Pads, Advanced 3D Models, Simulation Kits, Disposable Pads Usage Scenario: Medical Training, Nursing Simulations, Emergency Response, Skill Assessment End User: Medical Schools, Nursing Programs, Hospitals, Training Centers Material Composition: Silicone, Latex, Foam, PVC |
| Companies Covered | Laerdal Medical, Simulaids, 3B Scientific, SurgiReal, Nasco Healthcare, Limbs & Things, Simulab, Realityworks, Kyoto Kagaku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Practice Pad Market Trends and Innovations
Active haptic feedback systems and portable form factors are compressing the boundary between classroom training and point-of-care skill maintenance. Manufacturers now compete on anatomical fidelity rather than durability alone.
Embedded piezoelectric sensor arrays now detect needle angle, depth, and tissue plane transitions in real time. Academic medical centers in the United States are adopting these systems at accelerated procurement cycles. The technology is miniaturizing from tabletop consoles to palm-sized wireless modules that integrate with tablet-based instruction software.
Japan's PMDA has issued draft guidance classifying advanced injection trainers with electronic feedback as quasi-medical devices, triggering pre-market notification requirements. This regulatory expansion forces manufacturers to establish in-country quality representation. Product development teams are responding by segregating passive silicone pads from sensor-enabled variants to preserve simpler regulatory pathways.
Hospital procurement departments now unbundle skill assessment services from device purchases, contracting directly with competency-tracking software vendors. Medical schools are the primary channel experiencing this disintermediation, with purchasing committees favoring subscription-based proficiency analytics over capital equipment ownership. Germany's university hospital networks demonstrate the most advanced adoption of this consumption-pattern shift.
Injection Practice Pad Market Segmentation
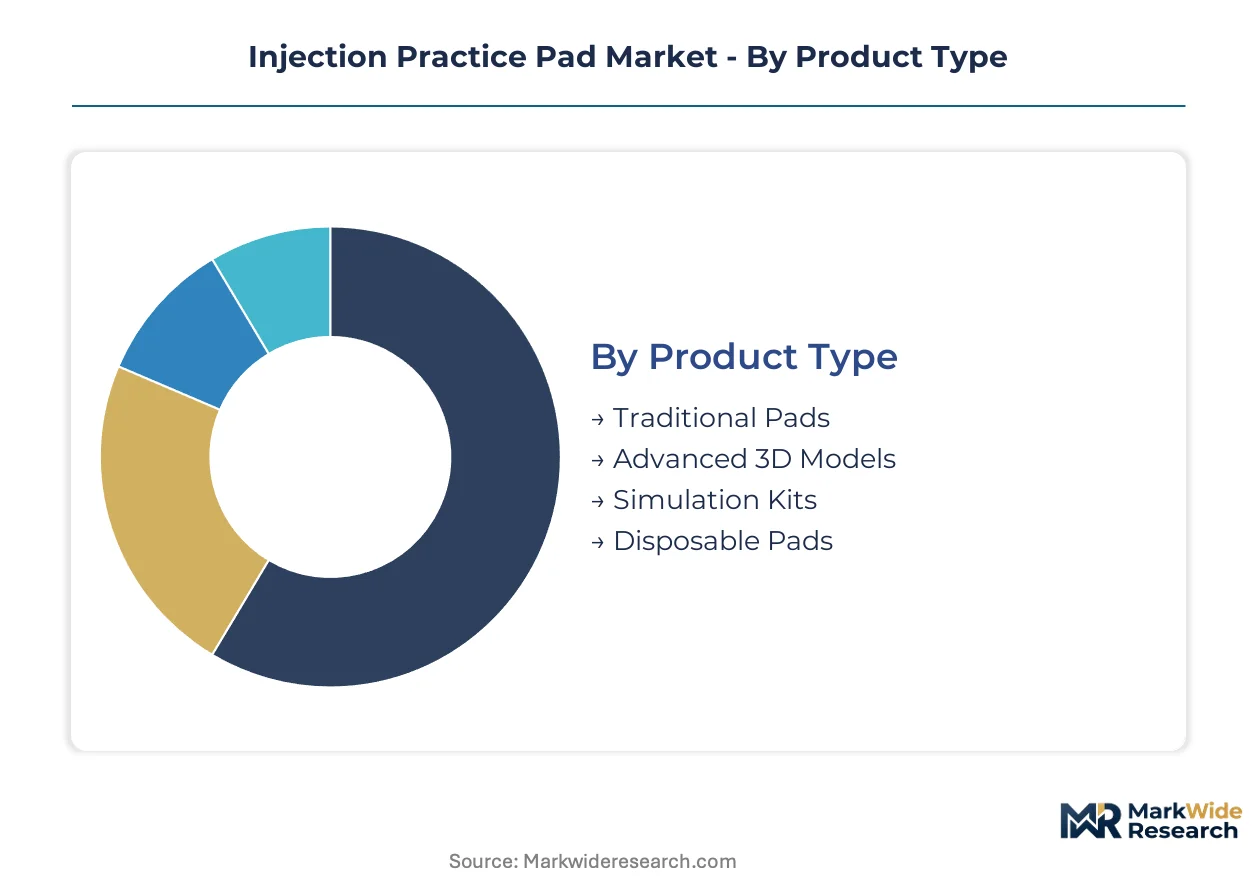
Segmentation in the injection practice pad market reflects divergent regulatory burdens and procurement criteria across training environments. Material specifications and feedback system complexity determine FDA pathway classification and institutional purchasing authority.
Product Type:
FDA regulates passive silicone pads as Class I medical training aids while sensor-enabled variants face quasi-device scrutiny under Japan's PMDA draft guidance.
- Traditional Pads:Multi-layer silicone or latex composites over foam substrates deliver calibrated tissue resistance for subcutaneous and intramuscular needle insertion. Medical schools in the United States anchor procurement volume as curriculum reform displaces cadaver-based instruction.
- Advanced 3D Models:Anatomically precise casting with variable durometer zones replicates vessel depth and muscle fascia for ultrasound-guided technique training. Germany's university hospital networks drive adoption as competency-based accreditation mandates objective structured clinical examinations.
- Simulation Kits:Modular configurations combine pads with procedural guidance accessories for standardized instruction protocols.
- Disposable Pads:Single-use designs address infection control protocols in high-throughput training environments.
Traditional Pads handles the majority of throughput; Advanced 3D Models is the fastest mover on share.
Usage Scenario:
Cost tier differentiation separates capital-intensive institutional deployments from individual skill maintenance purchases.
- Medical Training:Core curriculum integration across North American and European academic medical centers demands durable, anatomically accurate platforms for repeated student contact. Simulation-based programs now systematically replace cadaver-based instruction.
- Skill Assessment:Licensing boards in Japan and Germany embed objective structured clinical examinations into credentialing pathways, creating procurement pull for devices with embedded performance tracking. This segment climbs the fastest as competency verification displaces hour-count thresholds.
- Nursing Simulations:Specialized pediatric and geriatric anatomical variants command premium positioning in diversified patient-population training.
- Emergency Response:Rapid-deployment form factors serve pre-hospital and military medic certification programs with constrained training windows.
Medical Training commands the dominant procurement volume; Skill Assessment gains share fastest as regulatory frameworks harden around demonstrated competency.
End User:
Customer type determines specification complexity and contract structure, with academic institutions favoring capital purchases while hospital systems migrate toward subscription-based proficiency analytics.
- Medical Schools:Accreditation body mandates in the United States, Germany, and Japan drive systematic adoption of high-fidelity training devices. Purchasing committees unbundle skill assessment services from device purchases, contracting directly with competency-tracking software vendors.
- Hospitals:Point-of-care skill maintenance programs favor portable, wireless-enabled modules that integrate with tablet-based instruction software. Procurement departments in Germany's university hospital networks demonstrate the most advanced adoption of consumption-pattern shifts.
- Nursing Programs:Specialized demographic training requirements create demand for pediatric and geriatric anatomical variants.
- Training Centers:Independent facilities serving emergency response and military medic certification prioritize durability and rapid turnover capacity.
Medical Schools anchor procurement volume; Hospitals expand most quickly as point-of-care maintenance protocols proliferate.
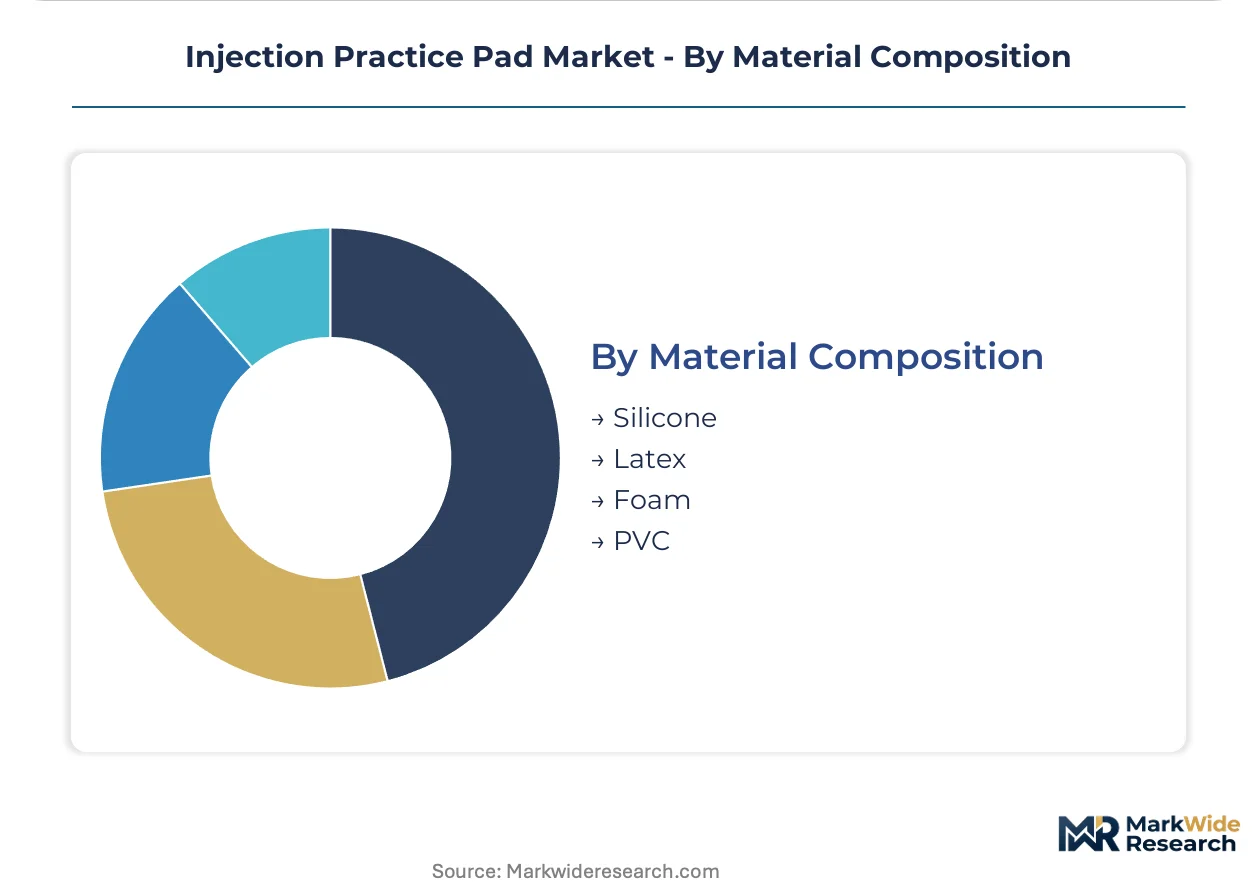
Material Composition:
Supply concentration in platinum-cured silicone feedstock creates margin pressure for manufacturers without backward integration into raw material sourcing.
- Silicone:Medical-grade platinum-cured formulations with durometer readings calibrated to 10-40 Shore A deliver the closest live-tissue response. Petrochemical supply chain volatility compresses margins for manufacturers lacking captive sourcing arrangements.
- Latex:Lower-cost alternative for budget-constrained training programs, though allergen concerns limit institutional adoption in the United States and European markets.
- Foam:Substrate material providing structural support and cost reduction in multi-layer pad construction.
- PVC:Entry-level option for high-volume disposable applications with minimal fidelity requirements.
Silicone dominates specification requirements for regulated health education markets; Latex retains position in cost-sensitive procurement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export high-fidelity silicone pads to academic medical centers across North America and East Asia, while Japanese producers supply sensor-enabled variants to domestic nursing programs and regional training institutes.
United States
Accreditation mandates from medical licensing boards drive institutional procurement of objective structured clinical examination equipment. FDA Class I clearance pathways for passive silicone pads remain streamlined, though sensor-enabled variants face emerging scrutiny. Academic medical centers in Boston and the Research Triangle anchor demand for ultrasound-guided technique trainers.
Germany
University hospital networks unbundle skill assessment services from device purchases, contracting directly with competency-tracking software vendors. EU MDR conformity requirements lengthen time-to-market for electronic feedback systems. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate precision silicone casting operations for anatomical fidelity.
Japan
Nursing programs and emergency response certification courses sustain demand for portable training modules. PMDA draft guidance classifies advanced injection trainers with electronic feedback as quasi-medical devices, triggering pre-market notification requirements. Medical device manufacturers in Osaka and Tokyo prefectures dominate domestic supply chains.
India
Medical education expansion creates procurement pull for cost-effective training devices as simulation-based curricula displace traditional instruction. CDSCO regulatory framework for clinical training devices remains nascent, lowering barriers for ISO-certified foreign manufacturers. Karnataka and Maharashtra host emerging distribution hubs serving South Asian nursing programs.
United Kingdom
Nursing schools and paramedic training centers prioritize durable, high-throughput pads for repeated student contact. NHS procurement frameworks emphasize value-based assessment metrics over capital equipment specifications. Greater London and Manchester metropolitan areas concentrate institutional purchasing authority for national training networks.
Injection Practice Pad Market Competitive Landscape
Listed medical device conglomerates compete with private specialists across material science capabilities and regulatory compliance bandwidth. Market structure tilts toward consolidated premium positioning, with three to five dominant players commanding academic medical center procurement. Strategic archetypes separate heritage anesthesia training specialists, mid-market emergency response suppliers, and anatomical fidelity innovators. Competitive moves concentrate on M&A for silicone polymer expertise and strategic partnerships with competency-tracking software vendors.
Within the heritage specialist tier, Laerdal Medical and Kyoto Kagaku exemplify decades-long positioning in anesthesia and clinical simulation training. Simulaids occupies a mid-market anchor position serving emergency response certification programs with channel-controlled distribution. These three represent divergent geographic origins and structural forms—Norwegian-based conglomerate, Japanese precision manufacturer, and private specialist—each embedding distinct regulatory navigation capabilities.
| Leading Market Players |
|---|
| Laerdal Medical |
| Simulaids |
| 3B Scientific |
| SurgiReal |
| Nasco Healthcare |
| Limbs & Things |
| Simulab |
| Realityworks |
| Kyoto Kagaku |
| Others |
Pricing and Supply Chain Analysis
Batch-scale efficiency in platinum-cured silicone casting operations concentrates manufacturing margin leverage among German and Japanese producers with captive polymer formulation capabilities, compressing price floors for mid-tier competitors sourcing feedstock through spot markets.
Pricing Analysis
Technology-generation pricing gaps separate passive silicone pads from sensor-enabled variants and next-generation haptic-integrated modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification tier and anatomical fidelity grade. Pricing pressure stems from platinum-cured silicone feedstock volatility tethered to petrochemical indices. Academic medical centers in the United States exhibit lowest price sensitivity; emergency response training programs in India demonstrate highest.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement for platinum-cured silicone, with German and Japanese manufacturers maintaining 90-day inventory buffers against petrochemical volatility. Supply concentrates in Baden-Württemberg industrial clusters, Osaka prefecture precision manufacturers, and emerging Tamil Nadu casting operations. Feedstock draws from specialty chemical producers in Germany, Japan, and the United States. Single-source vulnerability in medical-grade silicone polymer supply creates structural exposure. Distribution runs through medical supply distributors with proven volume commitments to academic procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
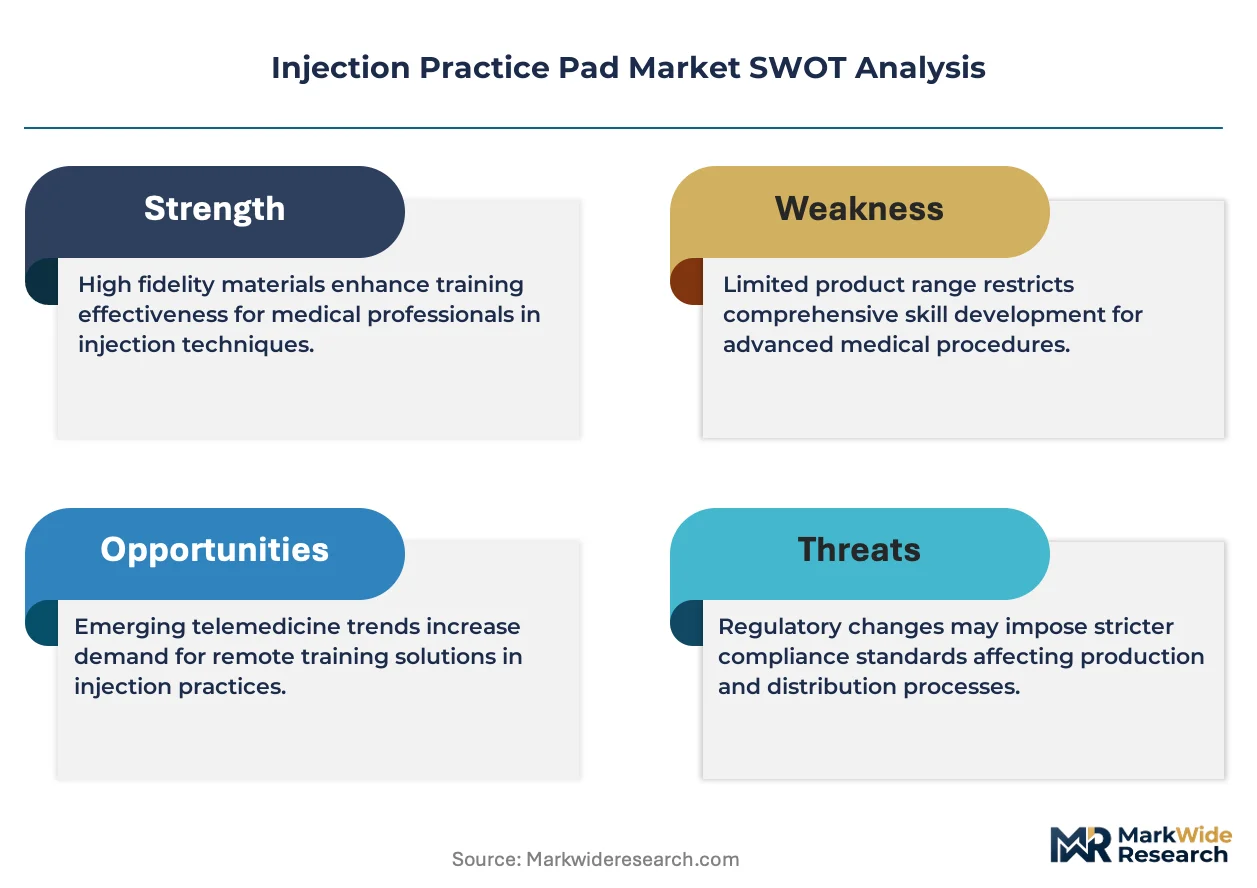
Full-body manikins with integrated injection modules threaten standalone pad demand, forcing incumbents to anchor replacement cycles through software-locked competency analytics and anatomical specialization.
For Market Incumbents: Fortify market position through backward integration into platinum-cured silicone formulation and exclusive GPO contracts with United States academic medical centers. Sensor-enabled variant development must accelerate before Japan's PMDA quasi-device classification hardens regulatory barriers. Channel control over emergency response certification programs anchors mid-market defense. For New Entrants and Emerging Players: ISO 13485 certification fast-track through European notified bodies enables entry into Germany's university hospital networks before EU MDR conformity burdens intensify. India's nascent CDSCO framework for clinical training devices offers the most penetrable geography. Pediatric and geriatric anatomical variants command premium realization with minimal incumbent specialization. For Investors and Strategic Acquirers: Silicone polymer expertise specialists with FDA master file documentation and captive raw material sourcing represent the optimal acquisition target archetype. Long-term viability hinges on substitution defense against full-body simulator convergence and competency-tracking software disintermediation. Watch for PMDA final guidance publication as inflection indicator for sensor-enabled variant regulatory burden.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined clearance for passive silicone pads preserves time-to-market advantage against sensor-enabled competitors. |
| CE Marking Under EU MDR | Conformity assessment for electronic feedback systems lengthens approval timelines and concentrates compliance bandwidth. |
| Hospital System Partnership | Direct contracting with Germany's university hospital networks bypasses distributor resistance to novel training categories. |
| Software Companion Development | Competency-tracking analytics integration defends against procurement committee preference for subscription-based assessment. |
| Reimbursement Strategy | Alignment with United States licensing board OSCE mandates embeds devices into credentialing cost structures. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and silicone polymer R&D directors; and secondary validation against FDA 510(k) filings, ISO 13485 certification databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up and top-down triangulation reconciled manufacturer shipment estimates with institutional purchasing survey responses.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type tier, usage scenario intensity, end-user procurement authority, and material composition grade. CAGRs derived from fitted growth curves applied to disclosed manufacturer capacity expansions and accreditation body mandate implementation timelines. Ultrasound-guided technique adoption curves and PMDA regulatory classification scenarios served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of steady ISO 13485 certification timeline stability and no radical substitution by full-body manikins; material deviation would warrant model refresh. Forecasts hinge on petrochemical supply chain continuity and licensing board OSCE mandate expansion trajectories. Revision becomes warranted when PMDA final guidance crosses thresholds triggering sensor-enabled variant reclassification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Massage Equipment Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Liposuction Devices Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
China Contraceptive Devices Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Blood Collection Devices Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Tumour Ablation Devices Market