
 Retropharyngeal Abscess Treatment Market | 2026-2036
Retropharyngeal Abscess Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Retropharyngeal Abscess Treatment Market Outlook
Surgical drainage procedure revenue is tilting toward tertiary care centers with integrated ENT-critical care capabilities. Johnson & Johnson leverages its broad surgical portfolio to anchor hospital supply contracts across North American and European networks. Pfizer competes through antibiotic formulation depth, while Medtronic specializes in powered instrumentation for deep-neck-space surgical access.
A retropharyngeal abscess is a purulent infection of the potential space between the anterior cervical vertebrae and the posterior pharyngeal wall, typically polymicrobial with Staphylococcus aureus and Group A Streptococcus predominance, requiring either broad-spectrum intravenous antibiotics or operative drainage when airway compromise or failed medical therapy occurs. The product type dimension shows antibiotics occupying the volume base while surgical drainage commands premium reimbursement in complicated cases. Among end users, pediatric patients generate disproportionate incidence-driven demand, whereas hospitals capture the highest acuity procedures and associated margin pools.
FDA antibiotic labeling requirements and EMA pharmacovigilance frameworks constrain empiric prescribing, pushing clinicians toward culture-directed therapy and narrower-spectrum agents. In Japan, PMDA manufacturing standards for implantable surgical devices add compliance layers for drainage hardware suppliers. Stakeholders must monitor evolving resistance patterns and reimbursement shifts between inpatient surgical and prolonged intravenous antibiotic administration.
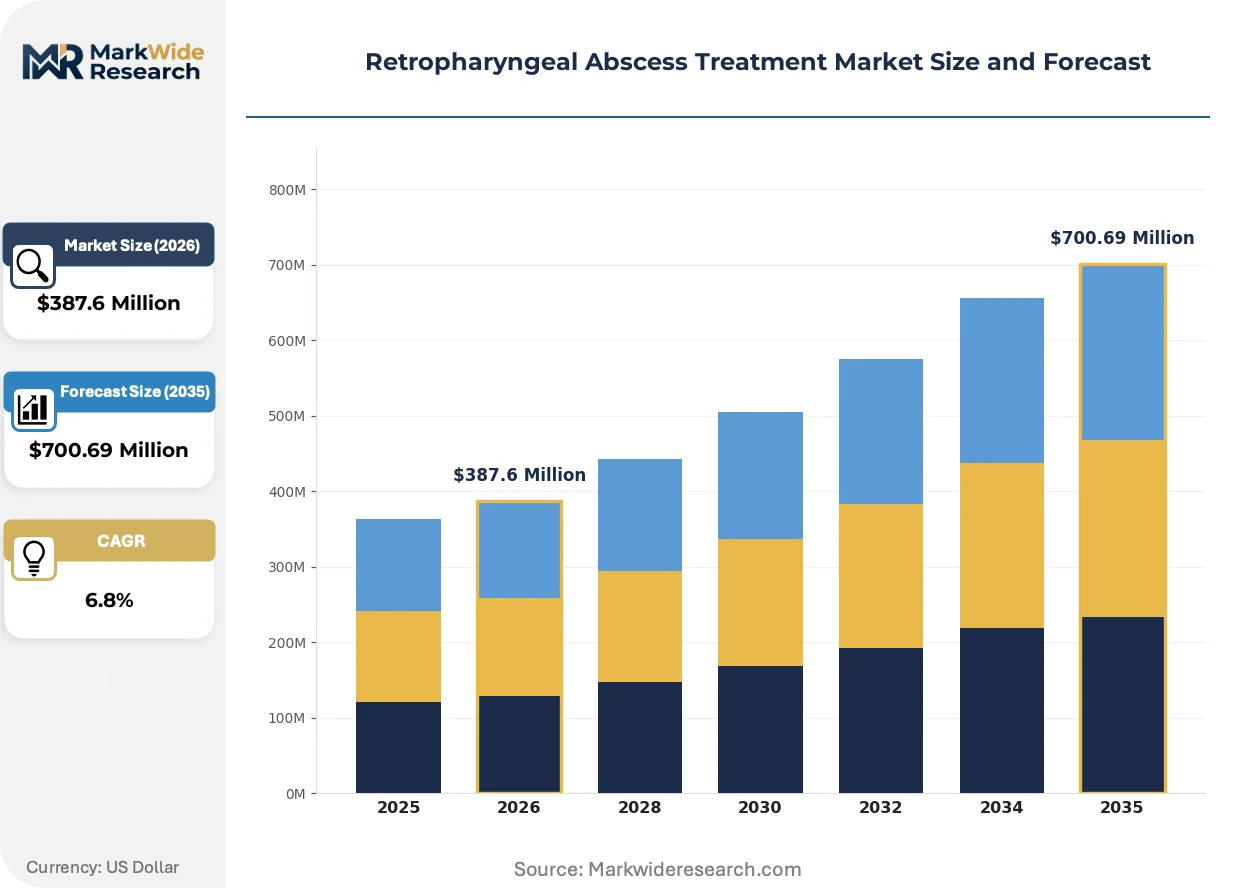
Market Dynamics
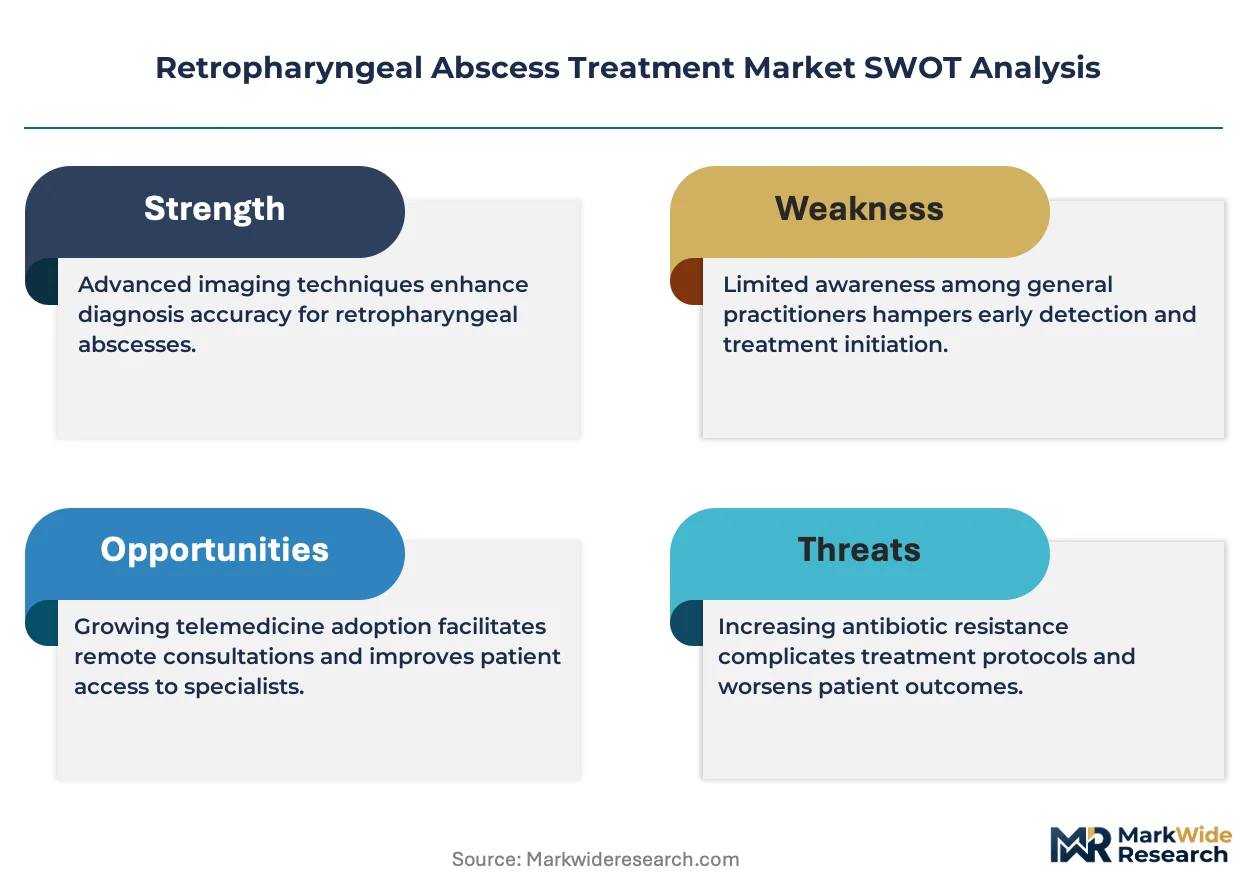
Antibiotic stewardship mandates from FDA and EMA are compressing empiric prescribing windows, forcing clinicians toward culture-directed protocols and narrowing the therapeutic latitude that once defined first-line management.
Growth Catalysts
- Pediatric ENT Infrastructure:Tertiary care centers in the United States, Germany, and Japan are expanding dedicated airway surgery suites to address rising pediatric incidence. These facilities capture complicated cases requiring combined antibiotic and surgical intervention.
- Powered Surgical Instrumentation:Advances in microdebrider and suction-irrigation systems enable safer deep-neck-space access. Surgeons adopt these tools for transoral approaches that reduce external incision rates.
- CE Marking Pathways:Streamlined EMA device certification for drainage hardware accelerates European commercialization timelines. Manufacturers leverage this regulatory efficiency to secure hospital supply contracts.
Market Restraints
- Antibiotic Resistance Surveillance:Rising MRSA and anaerobic resistance patterns in Staphylococcus aureus isolates complicate empiric selection. Clinicians face narrower effective options before culture results return.
- Implantable Device Compliance:PMDA manufacturing standards in Japan impose additional validation layers on surgical drainage hardware. These requirements extend time-to-market for foreign suppliers.
- Airway Surgery Skill Concentration:Deep-neck-space procedures require fellowship-trained otolaryngologists. Geographic maldistribution of these specialists limits intervention capacity outside major metropolitan clusters.
Strategic Opportunities
- Outpatient Parenteral Antibiotic Programs:OPAT protocols in the United States shift stable patients from inpatient to home-based intravenous administration. This model reduces hospital length-of-stay while maintaining therapeutic intensity.
- Image-Guided Drainage Convergence:Integration of intraoperative ultrasound with endoscopic navigation improves abscess localization accuracy. Combined modality approaches reduce revision surgery rates.
- Antibiotic Formulation Innovation:Long-acting liposomal preparations and extended-infusion beta-lactams offer pharmacokinetic advantages. These technologies support abbreviated hospitalization without efficacy compromise.
Industry Challenges
- Pediatric Airway Anesthesia Coordination:Shared airway management between anesthesiology and otolaryngology demands specialized team protocols. Case volume concentration at children's hospitals limits general hospital competence development.
- Multidisciplinary Care Pathway Integration:Coordinating infectious disease, radiology, and surgical teams around time-sensitive intervention windows requires institutional investment in communication infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retropharyngeal Abscess Treatment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Drainage, Pain Management, Supportive Care End User: Pediatric Patients, Adult Patients, Outpatient Clinics, Hospitals Delivery Mode: Oral, Intravenous, Topical, Inhalation Therapy Area: ENT, Infectious Disease, Critical Care, Emergency Medicine |
| Companies Covered | Johnson & Johnson, Medtronic, Stryker, Pfizer, Sanofi, Novartis, GlaxoSmithKline, AstraZeneca, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retropharyngeal Abscess Treatment Market Strategic Shifts
Digital workflow integration and point-of-care diagnostics are compressing the diagnostic-to-intervention timeline, while regulatory frameworks on both sides of the Atlantic reshape how therapeutic decisions are documented and reimbursed.
Intraoperative navigation systems paired with high-resolution endoscopy are digitizing surgical planning for deep-neck-space abscesses. Pediatric tertiary centers in the United States and Germany deploy these platforms to map abscess extension relative to carotid sheath and prevertebral fascia. The technology is digitating preoperative risk stratification, enabling selective surgical candidacy determination that reduces unnecessary operative exposure.
EMA pharmacovigilance frameworks and FDA antibiotic labeling requirements now mandate culture documentation before broad-spectrum initiation in hospitalized patients. These rules compress empiric prescribing windows and elevate microbiology laboratory turnaround expectations. European hospitals respond by investing in rapid molecular diagnostics, while US facilities face Medicare reimbursement penalties for non-compliant antibiotic utilization patterns.
Consolidated procurement by integrated delivery networks is displacing individual hospital purchasing autonomy for surgical drainage hardware. Large US health systems negotiate enterprise-wide contracts with preferred device vendors, compressing price points and marginalizing smaller manufacturers. This concentration is most visible in the southeastern and midwestern United States, where regional IDN dominance exceeds sixty percent of acute care beds.
Retropharyngeal Abscess Treatment Market Segmentation
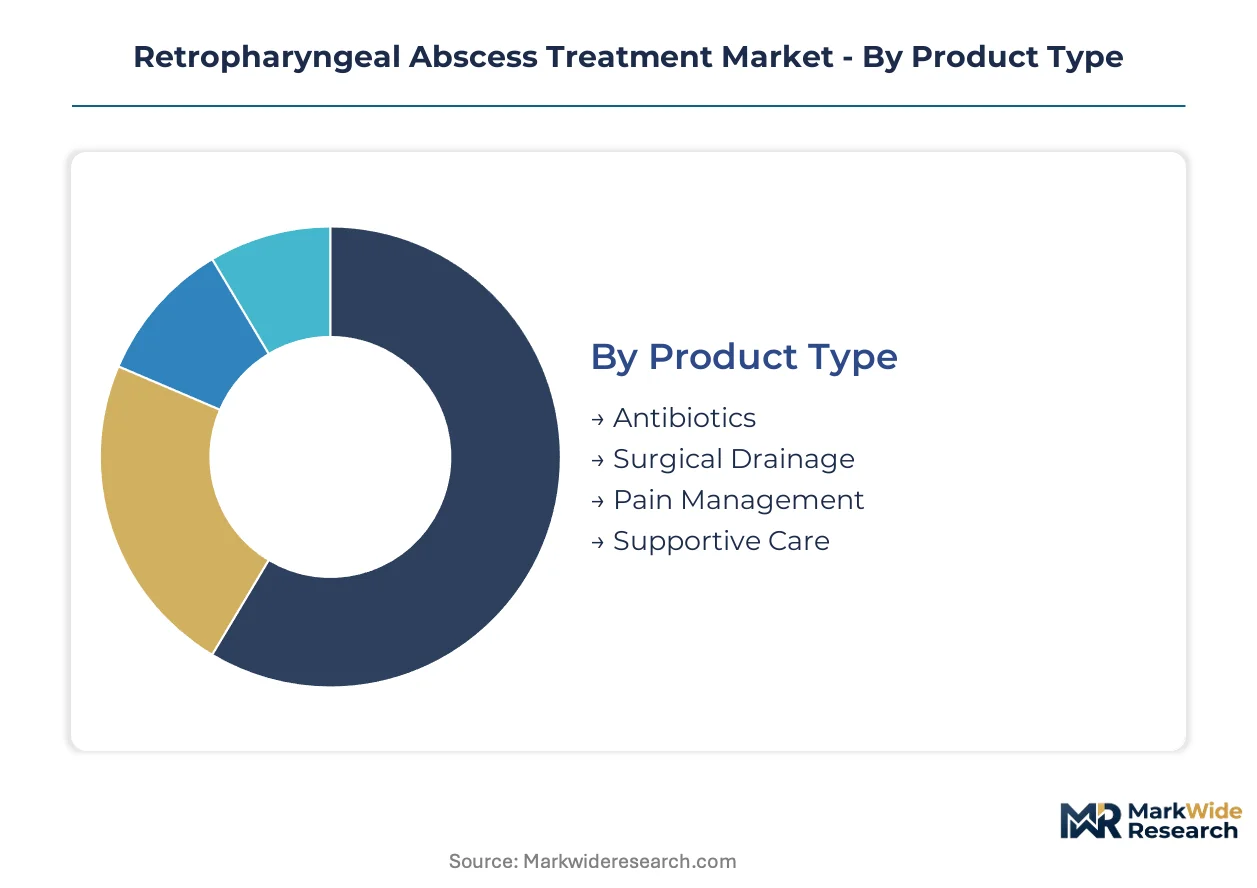
Retropharyngeal abscess treatment segmentation reveals divergent margin profiles across therapeutic modalities. Surgical drainage hardware demands intensive technical support and training, while antibiotic formulations compete on formulary access and stewardship compliance.
Product Type:
After-sales service intensity varies sharply across this category, with powered surgical instruments requiring field engineering support that antibiotics manufacturers rarely provide.
- Surgical Drainage:Powered microdebriders and suction-irrigation systems enable transoral deep-neck-space access. Tertiary pediatric ENT centers in the United States and Germany drive procurement of integrated navigation-capable platforms. FDA 510(k) clearance pathways and EMA CE marking create divergent service footprints for device manufacturers.
- Antibiotics:Intravenous formulations dominate inpatient empiric therapy before culture-directed narrowing. Hospital antimicrobial stewardship programs reshape purchasing decisions, with formulary committees prioritizing agents that satisfy FDA labeling requirements for resistant pathogen coverage.
- Pain Management:Multimodal analgesia protocols combine acetaminophen, NSAIDs, and short-course opioids for postoperative patients.
- Supportive Care:Airway monitoring hardware and nutritional support products address complications in prolonged hospitalizations.
By volume, Antibiotics leads. By growth pace, Surgical Drainage is ahead.
End User:
Cost tier stratification separates high-acuity inpatient surgical intervention from ambulatory antibiotic completion protocols.
- Hospitals:Integrated ENT-critical care units capture complicated cases requiring combined surgical drainage and intravenous antibiotics. Medicare reimbursement penalties for non-compliant antibiotic utilization patterns influence purchasing committee priorities in US facilities.
- Pediatric Patients:Anatomically narrower airways and higher incidence rates concentrate demand at children's hospitals with fellowship-trained otolaryngology teams. These facilities require specialized anesthesia coordination protocols for shared airway management.
- Adult Patients:Comorbidity burden drives longer intravenous antibiotic courses and higher complication rates.
- Outpatient Clinics:Stable post-drainage patients transition to parenteral antibiotic programs under infectious disease oversight.
By procedure volume, Pediatric Patients generates disproportionate incidence. By revenue per case, Hospitals captures the highest margin pool.
Delivery Mode:
Application context determines route selection, with airway security concerns overriding pharmacokinetic preferences in acute presentations.
- Intravenous:Beta-lactam and clindamycin combinations achieve reliable tissue penetration in deep-neck-space infections. Extended-infusion protocols and long-acting liposomal preparations support abbreviated hospitalization without efficacy compromise in US tertiary centers.
- Oral:Step-down therapy following clinical improvement enables outpatient parenteral antibiotic program completion. Bioavailability concerns limit oral options to fluoroquinolones and linezolid in select resistant cases.
- Topical:Anesthetic sprays facilitate transoral examination and procedural tolerance in pediatric populations.
- Inhalation:Nebulized therapies play adjunctive roles in airway edema management perioperatively.
By utilization frequency, Intravenous dominates acute management. By transition efficiency, Oral is gaining share fastest in stable patients.
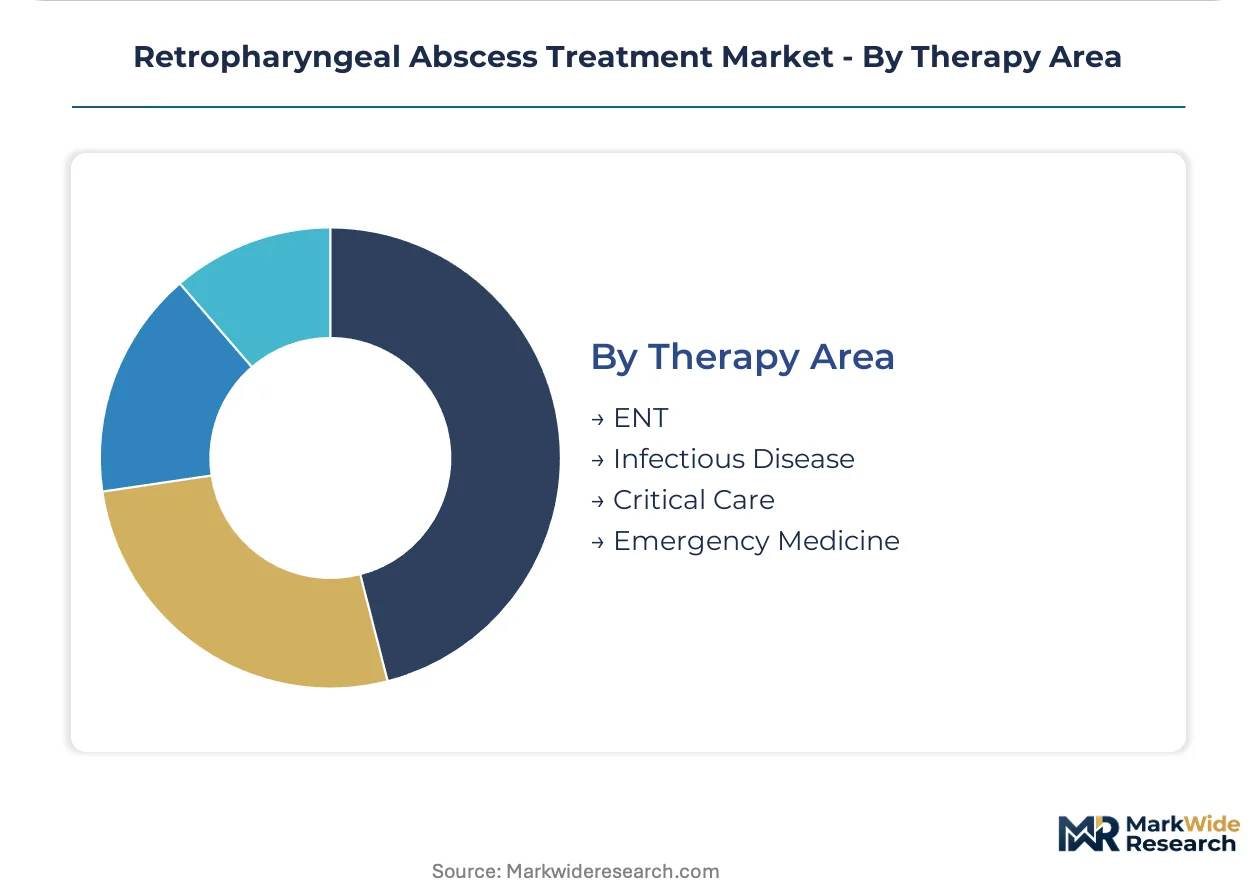
Therapy Area:
Customer type specialization creates distinct purchasing authority patterns across clinical service lines.
- ENT:Fellowship-trained otolaryngologists control surgical candidacy decisions and device selection for transoral approaches. Geographic concentration of these specialists in metropolitan clusters limits intervention capacity outside major US, German, and Japanese cities.
- Infectious Disease:Stewardship programs mandate culture documentation before broad-spectrum initiation under EMA pharmacovigilance frameworks. European hospitals invest in rapid molecular diagnostics to compress laboratory turnaround times.
- Critical Care:Airway management protocols and hemodynamic support coordinate with surgical teams in complicated cases.
- Emergency Medicine:Initial recognition and stabilization decisions trigger referral pathways to definitive care.
By procedural control, ENT directs surgical margins. By protocol influence, Infectious Disease is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity for surgical drainage hardware, while Japanese procurement committees apply stringent cost-effectiveness thresholds under universal coverage. European markets occupy a middle position where CE marking efficiency accelerates adoption but national health technology assessments cap reimbursement.
United States
Pediatric tertiary centers in Boston and Philadelphia drive demand for integrated navigation-capable surgical platforms. FDA 510(k) clearance pathways enable rapid device commercialization compared to European counterparts. The Southeast and Midwest concentrate procurement authority within integrated delivery networks exceeding sixty percent of acute care beds.
Germany
University hospitals in Munich and Hamburg anchor ENT-critical care unit expansion for complicated deep-neck-space infections. EMA pharmacovigilance frameworks mandate culture documentation before broad-spectrum antibiotic initiation. Baden-Württemberg manufacturing clusters supply powered microdebrider components to domestic device assemblers.
Japan
Tokyo and Osaka children's hospitals generate disproportionate surgical case volume among pediatric populations with anatomically narrow airways. PMDA manufacturing standards impose additional validation layers on implantable drainage hardware, extending time-to-market for foreign suppliers. Kansai-region procurement committees prioritize domestic vendors for maintenance responsiveness.
United Kingdom
London and Manchester tertiary centers concentrate fellowship-trained otolaryngology capacity for transoral approaches. National Health Service antimicrobial stewardship programs reshape formulary committee priorities toward narrow-spectrum agents. Scotland and Wales face geographic maldistribution of deep-neck-space surgical specialists.
India
Delhi-NCR and Mumbai private hospital chains invest in pediatric ENT infrastructure as medical tourism destinations. CDSCO regulatory pathways for imported surgical devices create compliance bottlenecks for drainage hardware suppliers. Karnataka and Tamil Nadu manufacturing zones produce cost-competitive suction-irrigation system components.
Retropharyngeal Abscess Treatment Market Competitive Environment
Diversified health conglomerates and specialized surgical device manufacturers split the market along therapy modality lines. Antibiotic formulation specialists compete on stewardship compliance and formulary access rather than technical service intensity. Three archetypes dominate: integrated surgical portfolio holders, pharmaceutical antibiotic developers, and powered instrumentation specialists. Consolidated procurement by United States health systems and European hospital networks drives preferred vendor contracting, while Japanese market entry demands regulatory compliance partnerships with local distributors.
Among diversified health conglomerates, Johnson & Johnson and Pfizer occupy positions spanning surgical hardware and pharmaceutical supply. Medtronic exemplifies the powered instrumentation specialist archetype with deep-neck-space surgical access expertise. These three anchors represent distinct competitive vectors—broad surgical portfolio breadth, antibiotic formulation depth, and device technical specialization—without overlapping core competencies.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Stryker |
| Pfizer |
| Sanofi |
| Novartis |
| GlaxoSmithKline |
| AstraZeneca |
| Boston Scientific |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German microdebrider component suppliers determines both the premium tier spreads for navigation-capable surgical platforms and the elongated supply chain shape that foreign device manufacturers must navigate. FDA 510(k) clearance pathways compress time-to-market for US-based assemblers, while PMDA validation layers in Japan extend procurement cycles and inflate landed costs for identical hardware specifications.
Pricing Analysis
After-sales service revenue from field engineering support and extended maintenance contracts drives lifetime value for powered surgical instrument vendors. Three-tier pricing structure across premium navigation-integrated platforms, standard suction-irrigation systems, and economy drainage kits separates academic medical centers from community hospitals and cost-constrained clinics. Cost compression in the economy tier intensifies because Indian and Chinese component suppliers undercut Baden-Württemberg manufacturing clusters on suction-irrigation subassemblies. Pediatric tertiary centers demonstrate the lowest price sensitivity, whereas regional health systems in the US Southeast and Midwest exhibit acute responsiveness to bundled procurement discounts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for drainage hardware manufacturers sourcing electronic navigation components. Manufacturing concentration clusters in Germany, Japan, and the United States for precision microdebrider motors, with secondary sourcing from Karnataka and Tamil Nadu zones for molded suction-irrigation housings. Raw material dependencies include surgical-grade stainless steel, medical device polymers, and rare-earth magnets for powered instrumentation motors. Distribution runs through integrated delivery network procurement committees in North America, hospital supply consortia in Germany, and regional distributor partnerships mandated by Japanese PMDA compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern anchored to pediatric ENT infrastructure buildouts, with capital equipment replacement cycles and antibiotic stewardship program maturation creating alternating waves of surgical and pharmaceutical demand intensity.
For Market Incumbents: Insulate service revenue streams by embedding field engineering teams within pediatric tertiary center accounts, locking out competitors through exclusive maintenance contracts for navigation-capable platforms. Deepen backward integration into suction-irrigation component production to offset tariff exposure on Chinese-sourced electronics. Pursue FDA 510(k) clearance for next-generation microdebrider iterations before EMA CE marking pathways accelerate European competitor launches.
For New Entrants and Emerging Players: India's Delhi-NCR and Mumbai private hospital chains present the most penetrable geography, with CDSCO regulatory bottlenecks creating defensible moats for first-movers establishing local manufacturing partnerships. Target outpatient parenteral antibiotic program infrastructure as the lowest-barrier entry vector, avoiding capital-intensive surgical hardware competition. Deploy infectious disease specialist detailing teams to formulary committees as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA antibiotic labeling requirement enforcement reshapes the acquisition landscape toward culture-directed therapy enablers and rapid molecular diagnostic platforms. The five-to-ten year viability window favors device manufacturers with integrated navigation software capabilities and pharmaceutical developers with long-acting liposomal formulation pipelines. Acquisition target archetypes include powered instrumentation specialists lacking hospital supply contract scale. Monitor EMA pharmacovigilance penalty implementation rates as the signal to watch for antibiotic stewardship compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EMA streamlined certification reduces European commercialization timelines for drainage hardware suppliers. |
| Hospital System Partnership | Integrated delivery network contracting secures preferred vendor status across sixty percent of US acute care beds. |
| Software Companion Development | Intraoperative navigation platforms digitize surgical planning for deep-neck-space abscess interventions. |
| Reimbursement Strategy | Medicare penalty avoidance for non-compliant antibiotic utilization reshapes US hospital purchasing priorities. |
| FDA Submission | 510(k) clearance pathways enable rapid device commercialization compared to PMDA validation layers in Japan. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with otolaryngology department chairs, hospital procurement managers, infectious disease stewardship leads, and biomedical engineering directors; and secondary validation against FDA 510(k) filings, EMA CE marking databases, PMDA approval registries, hospital procurement contract disclosures, and Medicare reimbursement penalty reports. Bottom-up segmentation modeling triangulated against top-down epidemiological incidence projections for pediatric deep-neck-space infections.
Forecast inputs included procedural volume trajectories across the projection horizon, with segmentation dimensions covering product type (surgical drainage hardware, antibiotic formulations, pain management, supportive care), end user (pediatric patients, adult patients, hospitals, outpatient clinics), and therapy area (ENT, infectious disease, critical care, emergency medicine). CAGRs were derived from regression analysis of historical procedure volumes and antibiotic utilization patterns, incorporating antibiotic resistance surveillance data and powered instrumentation adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified health conglomerates or rapid OPAT protocol expansion by retail pharmacy chains would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Valley Fever Market
Infectious Disease
Efavirenz Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Pork Tapeworm Infection Treatment Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Virology Market
Infectious Disease
Chlamydia Infection Treatment Market