
 Efavirenz Market | 2026-2036
Efavirenz Market Size, Share, and Industry Trends Forecast 2026-2036
Efavirenz Market Analysis
Consolidation among national HIV treatment programs and global procurement bodies is repositioning how efavirenz manufacturers secure volume commitments. Cipla anchors its position through backward integration into active pharmaceutical ingredient production for antiretroviral compounds. Mylan competes aggressively on tenders via its established presence in WHO-prequalified manufacturing facilities across India. Hetero differentiates through dedicated capacity for efavirenz and lamivudine fixed-dose combinations serving African public health systems.
Efavirenz is a non-nucleoside reverse transcriptase inhibitor with a molecular weight of 315.68 g/mol, formulated primarily as 600 mg tablets for once-daily administration in first-line HIV regimens. The compound functions by binding directly to reverse transcriptase and blocking RNA-dependent and DNA-dependent polymerase activity, thereby suppressing viral replication in combination with nucleoside analogues. Tablet formulations dominate procurement volumes due to stability advantages and alignment with directly observed therapy programs in resource-limited settings, while oral solutions retain niche demand for pediatric populations and patients with swallowing difficulties. Hospitals and clinics capture the bulk of institutional purchasing, though home care channels are expanding as treatment literacy improves and three-month dispensing policies take hold in several high-burden countries.
FDA bioequivalence standards and WHO prequalification requirements govern market access for generic efavirenz suppliers, creating a dual-track compliance burden that filters out smaller manufacturers. The EPA oversees environmental discharge limits for efavirenz production facilities, particularly concerning API synthesis waste streams. EMA guidelines on impurity profiles and dissolution specifications further shape quality benchmarks for products entering European donor-funded channels. Stakeholders must monitor evolving WHO treatment guideline revisions and their ripple effects on procurement specifications.
Market Dynamics
Consolidation of procurement power among national HIV programs and global health bodies is restructuring how efavirenz manufacturers secure volume commitments, favoring suppliers with WHO prequalification and backward integration into active pharmaceutical ingredient production.
Growth Catalysts
- First-line ART expansion:Sub-Saharan African governments are scaling national treatment programs to reach the remaining undiagnosed population, directly expanding tablet demand through public procurement channels.
- WHO prequalification alignment:Manufacturers achieving WHO prequalification gain automatic eligibility for Global Fund and PEPFAR tenders, creating a regulatory fast-track into high-volume markets.
- Three-month dispensing policies:South Africa and Kenya have adopted extended prescription periods that reduce clinic burden and stabilize patient adherence, increasing per-patient annual tablet requirements.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Indian manufacturing zones, creating geographic vulnerability to environmental compliance shutdowns or export restrictions.
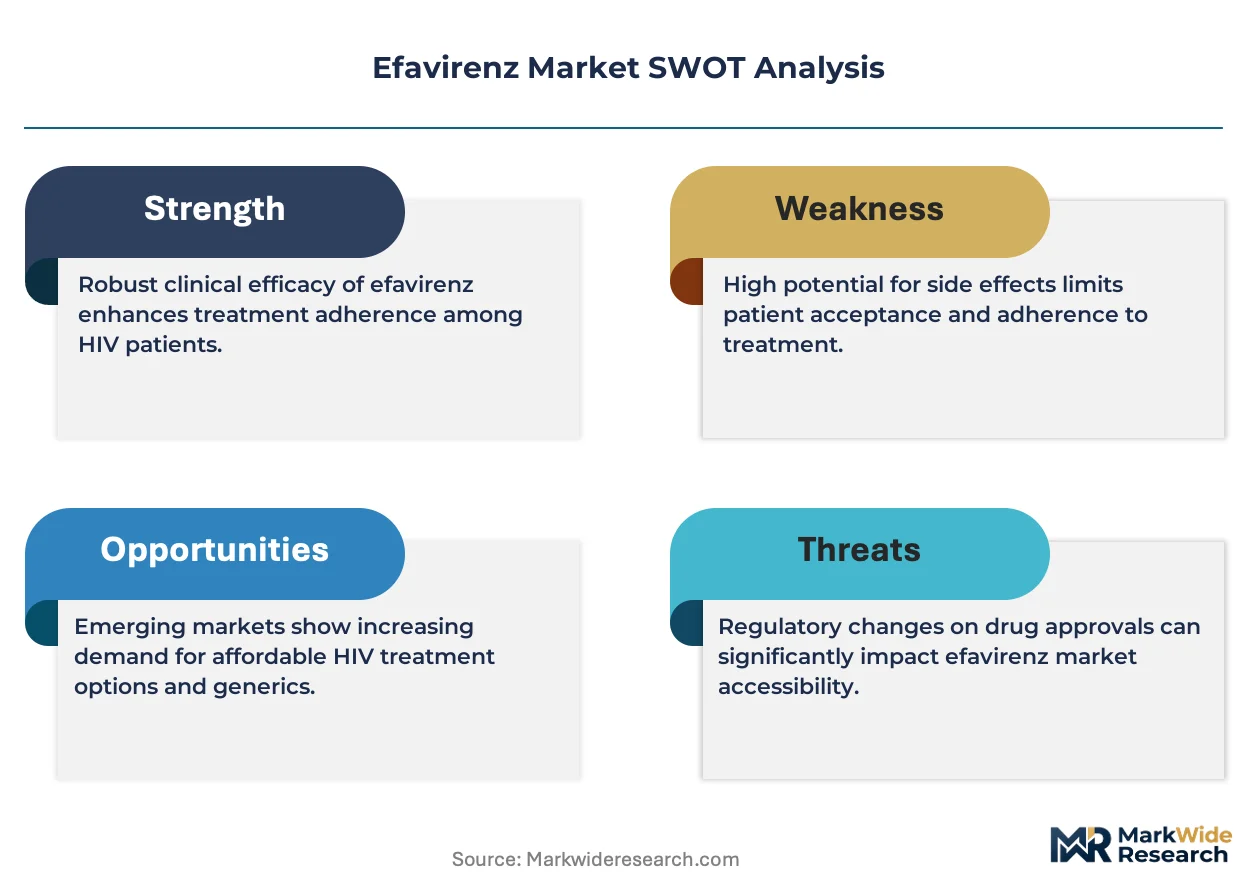
- Dolutegravir substitution pressure:WHO guidelines now favor dolutegravir-based regimens for first-line therapy in most populations, compressing efavirenz demand growth in donor-funded programs.
- Bioequivalence compliance burden:FDA and EMA dissolution specifications require costly biostudies and analytical method development that filter out smaller generic manufacturers.
Strategic Opportunities
- Pediatric formulation gaps:Oral solution demand for children under 10 kilograms remains underserved, with few WHO-prequalified suppliers competing for niche procurement lots.
- Home care channel development:Treatment literacy improvements in Nigeria and Kenya enable community-based distribution models that bypass traditional clinic stockouts.
- Fixed-dose combination expansion:Tenofovir-lamivudine-efavirenz triple therapy alignment with national formularies creates bundling advantages for manufacturers with dedicated FDC capacity.
Industry Challenges
- Analytical method transfer complexity:Moving dissolution and impurity testing protocols between contract laboratories and in-house quality units delays product launches by 12-18 months.
- Environmental discharge compliance:API synthesis waste streams containing efavirenz residues face tightening EPA and state pollution control board limits, requiring capital-intensive effluent treatment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Efavirenz Market |
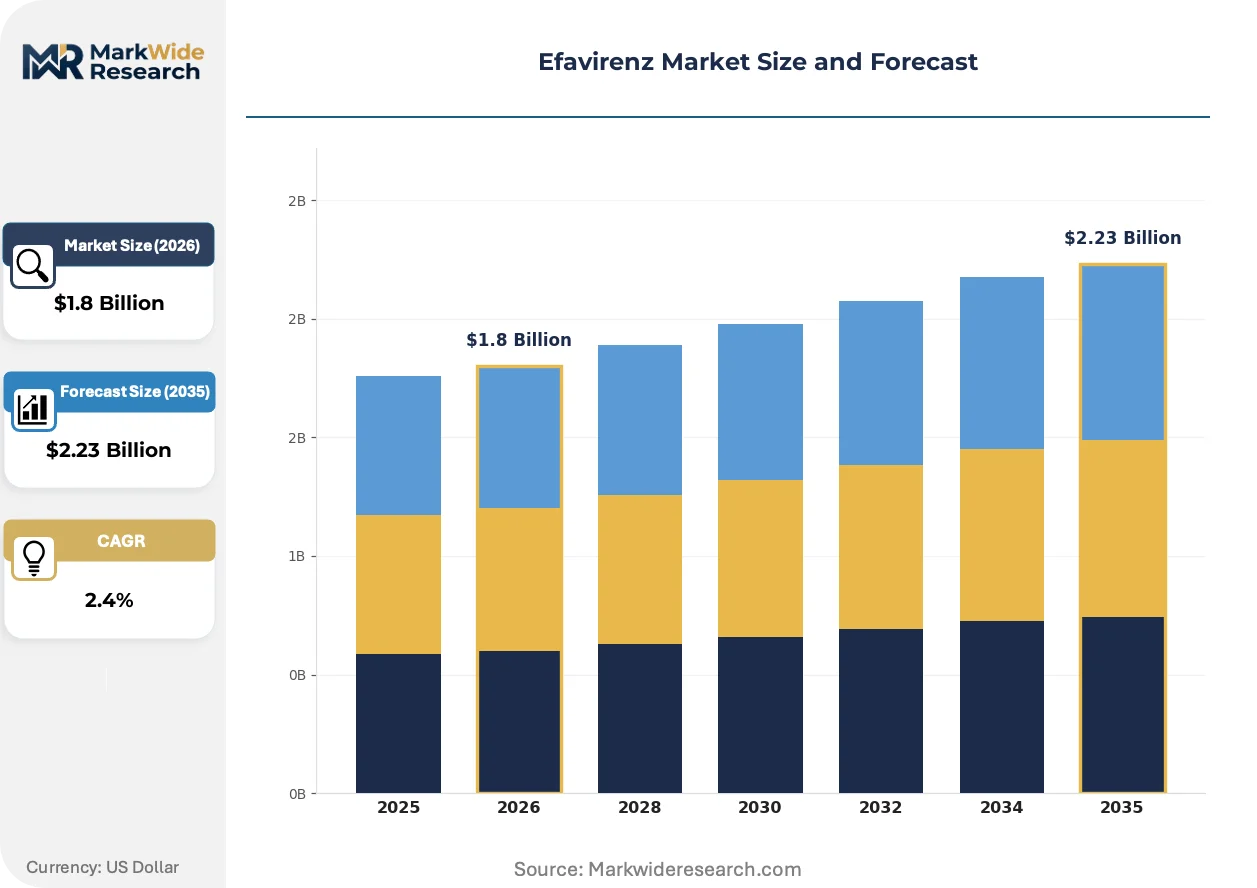
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Oral Solutions, Injectable Solutions Delivery Mode: Oral, Parenteral, Transdermal, Biologic End User: Hospitals, Clinics, Home Care, Pharmaceuticals Therapy Area: HIV/AIDS, Viral Infections, Infectious Diseases, Immunology |
| Companies Covered | Macleods Pharmaceuticals, Strides Pharma, Hetero, Bristol-Myers Squibb, Aurobindo Pharma, Mylan, Gilead Sciences, Cipla, Teva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Efavirenz Market Emerging Trajectories
Process intensification in active pharmaceutical ingredient synthesis and evolving procurement modalities are compressing cost structures while reshaping how manufacturers compete for public health contracts.
Continuous flow chemistry is overtaking traditional batch synthesis for efavirenz API production. Indian contract manufacturers serving WHO-prequalified facilities are adopting microreactor systems that reduce solvent volumes and improve yield consistency. This technology is overtaking capital-intensive batch equipment investments and enabling smaller footprint facilities to achieve regulatory compliance.
South Africa's national health department has mandated local pharmaceutical manufacturing commitments as a condition for tender participation. This industrial policy requires foreign suppliers to establish joint ventures or technology transfer agreements with domestic producers. Multinational generic manufacturers are responding by licensing process technology to South African partners rather than competing purely on import price.
Community-based antiretroviral delivery is displacing clinic-centric dispensing in high-burden districts. Trained community health workers in Kenya and Nigeria now manage three-month drug distribution to stable patients, reducing facility congestion and transportation costs. This channel shift is most visible in rural catchment areas where clinic density remains inadequate for patient volumes.
Efavirenz Market Segmentation
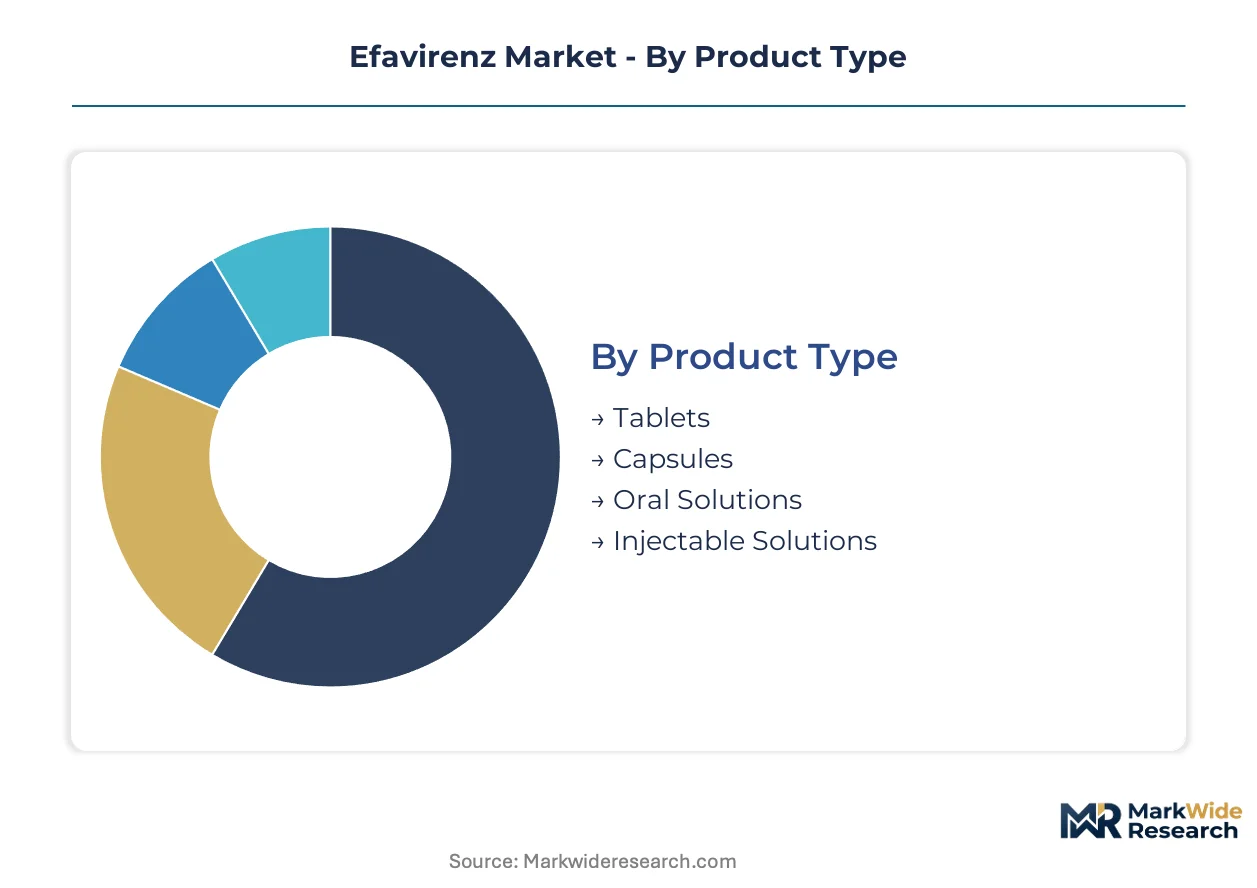
Efavirenz procurement patterns diverge sharply across formulation types and delivery channels. Segment boundaries reflect regulatory pathways, patient adherence requirements, and the operational constraints of public health distribution systems.
Product Type:
Upgrade cycles in first-line HIV therapy favor formulations with superior stability profiles and simpler supply chain handling.
- Tablets:The 600 mg solid oral dosage dominates procurement volumes due to thermal stability and alignment with directly observed therapy programs. South Africa's national health department specifies tablet-only procurement for adult first-line regimens, locking in volume concentration.
- Oral Solutions:Liquid formulations serve pediatric populations below 10 kilograms and patients with dysphagia. WHO prequalification gaps limit supplier competition, creating procurement bottlenecks in Nigeria's pediatric treatment expansion.
- Capsules:Gelatin-shell alternatives retain niche demand in specific national formularies with historical procurement preferences.
- Injectable Solutions:Parenteral efavirenz remains experimental with no commercial scale production for HIV indications.
Volume placements concentrate in tablets; the faster expansion belongs to oral solutions.
Delivery Mode:
Cost tier differentiation separates mass-market oral administration from specialized parenteral and biologic channels with premium handling requirements.
- Oral:Gastrointestinal absorption via tablets and solutions captures nearly all commercial efavirenz demand. Kenya's three-month dispensing policy depends entirely on oral formulation stability during community distribution.
- Parenteral:Intravenous and intramuscular routes serve hospitalized patients with severe opportunistic infections requiring supervised administration.
- Transdermal:Patch-based delivery remains developmental with no regulatory approval for efavirenz pharmacokinetics.
- Biologic:Antibody-drug conjugates and targeted delivery systems are preclinical with no near-term commercial pathway.
Oral delivery commands procurement volumes; biologic research investment is climbing the fastest.
End User:
Application concentration shifts from institutional purchasing toward community-based channels as treatment literacy matures.
- Hospitals:Acute care facilities manage treatment initiation and opportunistic infection complications. South Africa's referral hospitals anchor procurement for complex cases requiring therapeutic drug monitoring.
- Home Care:Community health workers in Kenya and Nigeria now distribute three-month supplies to stable patients, bypassing clinic congestion. This channel expansion is reshaping last-mile logistics requirements.
- Clinics:Primary health centers retain volume for new patient enrollment and adherence counseling.
- Pharmaceuticals:Private pharmacy channels serve insured populations outside public procurement systems.
Hospitals retain the highest per-patient value; home care is gaining share fastest.
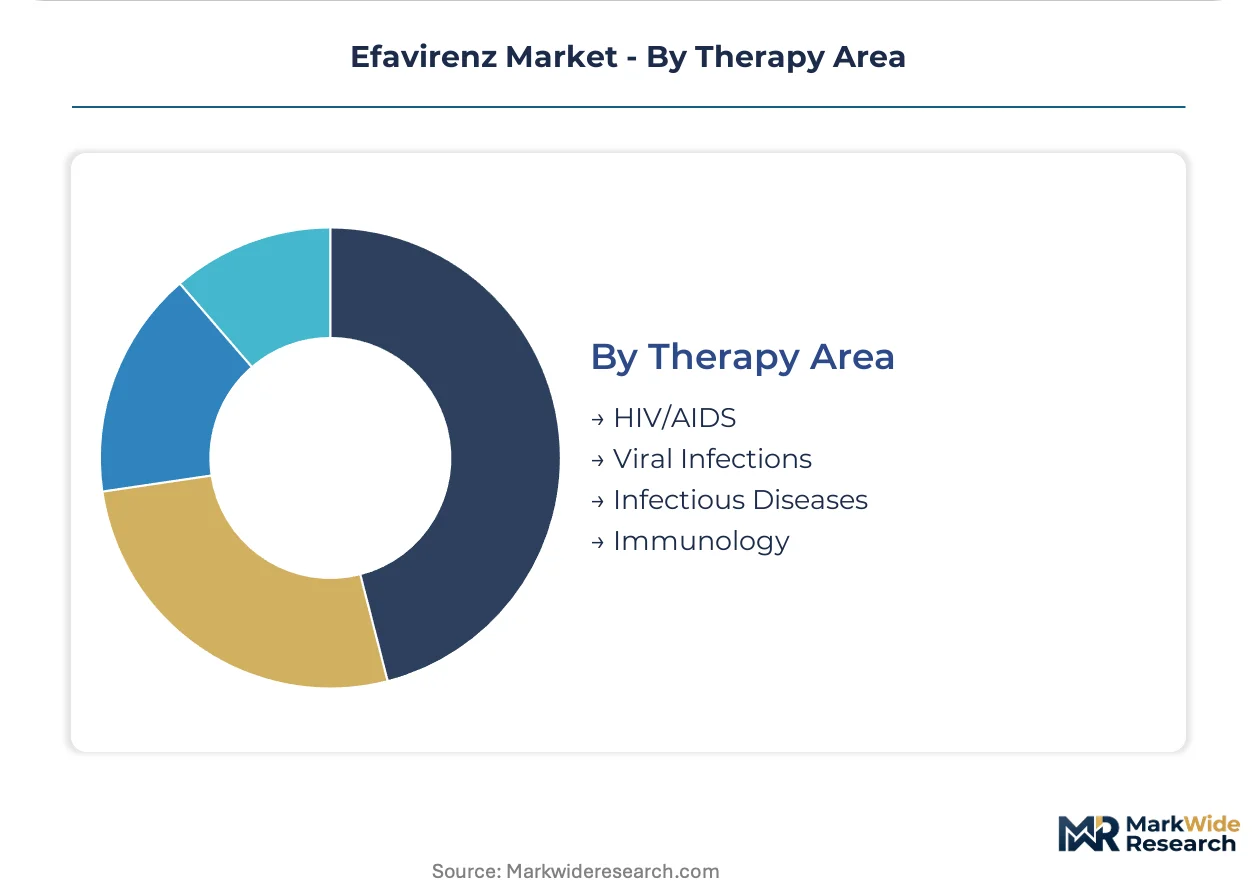
Therapy Area:
Maturity gradients separate established HIV/AIDS protocols from emerging applications in broader infectious disease management.
- HIV/AIDS:First-line antiretroviral therapy represents the sole approved indication with documented clinical outcomes. WHO guidelines and national formularies lock efavirenz into triple-combination regimens with tenofovir and lamivudine.
- Viral Infections:Investigational use against hepatitis B and other retroviruses shows preliminary activity but no regulatory pathway.
- Infectious Diseases:Broad-spectrum antiviral research explores efavirenz derivatives for emerging pathogens.
- Immunology:Immunomodulatory properties are preclinical with no therapeutic application.
HIV/AIDS anchors all commercial volume; viral infection research represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in sub-Saharan African markets where national HIV treatment programs drive procurement volumes. South Africa, Nigeria, and Kenya anchor tablet consumption through public sector tenders. Procurement patterns diverge between mature programs with three-month dispensing policies and expanding systems still building clinic infrastructure.
South Africa
The national health department specifies tablet-only procurement for adult first-line regimens, locking in volume concentration for 600 mg formulations. Local pharmaceutical manufacturing commitments now condition tender participation, requiring foreign suppliers to establish joint ventures or technology transfer agreements with domestic producers. Johannesburg and Cape Town anchor the country's distribution infrastructure for antiretroviral supply chains.
Nigeria
Pediatric treatment expansion drives oral solution demand for children below 10 kilograms, though WHO prequalification gaps limit supplier competition. The country's national agency for food and drug administration and control regulates importation and quality standards for all antiretroviral products. Lagos and Abuja concentrate procurement coordination for the federal HIV treatment program.
Kenya
Three-month dispensing policies for stable patients reshape last-mile logistics requirements through community health worker networks. The Pharmacy and Poisons Board governs product registration and post-market surveillance for efavirenz formulations. Nairobi anchors the central medical stores system that distributes to rural catchment areas where clinic density remains inadequate.
India
Active pharmaceutical ingredient production clusters in specific manufacturing zones, creating geographic concentration for efavirenz synthesis inputs. The Central Drugs Standard Control Organization oversees manufacturing licenses and export certifications for WHO-prequalified facilities. Hyderabad and Ahmedabad anchor contract manufacturing operations serving African procurement channels.
United States
PEPFAR funding shapes procurement specifications for donor-supported programs in partner countries rather than domestic consumption. The FDA maintains bioequivalence standards that generic manufacturers must satisfy for tentative approval eligibility. Maryland and Washington D.C. concentrate program administration and technical assistance coordination for global HIV treatment scale-up.
Efavirenz Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pediatric formulation niches and community distribution partnerships. The supplier base concentrates among WHO-prequalified manufacturers with backward integration into active pharmaceutical ingredient production. Three archetypes dominate: Indian contract manufacturers with dedicated antiretroviral capacity, multinational generic firms with African distribution infrastructure, and originators maintaining limited branded presence. Competitive moves center on tender positioning through price-volume commitments and technology licensing to satisfy local manufacturing requirements.
Among Indian pharmaceutical manufacturers, Cipla, Hetero, and Aurobindo Pharma exemplify the contract manufacturing archetype serving public health procurement channels. Cipla represents the established tier with historical positioning in African antiretroviral markets. Hetero occupies a specialist position in fixed-dose combination capacity. Aurobindo Pharma sits within the scale-driven segment of API-integrated suppliers. These companies anchor the competitive structure without dominating through proprietary formulation advantages.
| Leading Market Players |
|---|
| Macleods Pharmaceuticals |
| Strides Pharma |
| Hetero |
| Bristol-Myers Squibb |
| Aurobindo Pharma |
| Mylan |
| Gilead Sciences |
| Cipla |
| Teva |
| Others |
Supply Flow & Price Mechanics
API feedstock cost indices for cyclopropylacetylene and 4-chloroaniline cascade through Indian manufacturing zones into three-tier pricing structures across premium WHO-prequalified, standard national tender, and economy spot-purchase tiers. Procurement officers at Nigeria's national agency for food and drug administration and control leverage this concentration to compress margins on volume commitments.
Pricing Analysis
Volume-margins split sharply between tender-winning manufacturers capturing 80-plus percent of procurement lots at compressed rates and niche pediatric suppliers commanding premium pricing for oral solutions. Price differentiation hinges on WHO prequalification status and backward integration into active pharmaceutical ingredient synthesis. Pricing pressure intensifies as dolutegravir substitution in South Africa's national formulary reduces efavirenz volume guarantees. Public procurement channels exhibit extreme price sensitivity; private pharmacy segments retain modest premium tolerance for branded formulations.
Supply Chain Analysis
Freight cost volatility on India-East Africa shipping lanes amplifies landed cost disparities between Hyderabad-anchored API producers and Mombasa-dispatched finished goods. Supply concentrates in Indian manufacturing zones around Hyderabad and Ahmedabad, with secondary formulation capacity in South Africa through joint venture structures. Raw material dependencies include cyclopropylacetylene, lithium amide, and specialized solvent systems. Single-source vulnerability in API synthesis creates exposure to environmental compliance shutdowns. Distribution runs through central medical stores in Nairobi and Lagos, then community health worker networks for last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races dominate competitive positioning as manufacturers pursue captive API supply to defend tender margins against procurement consolidation. Control over cyclopropylacetylene synthesis and WHO prequalification timelines represents the decisive upstream lever.
For Market Incumbents: Deploy technology licensing to satisfy South Africa's local manufacturing mandates while preserving API supply control. Consolidate fixed-dose combination capacity to bundle efavirenz with tenofovir and lamivudine in single-tablet tenders. Dolutegravir substitution pressure demands accelerated pediatric formulation development to retain volume in shrinking adult markets.
For New Entrants and Emerging Players: CDSCO export certification pathways in India open a window for WHO prequalification pursuit without immediate African distribution infrastructure. Target oral solution gaps for children below 10 kilograms in Nigeria's pediatric expansion. Community health worker partnership models in Kenya offer a go-to-market angle bypassing congested central medical store channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor API-integrated mid-cap specialists with dormant WHO prequalification applications in Indian manufacturing zones. Long-term viability hinges on diversification into dolutegravir-compatible production lines. Monitor South Africa's local content enforcement intensity as the inflection signal for technology licensing valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks Global Fund and PEPFAR tender eligibility for high-volume African procurement. |
| Backward Integration into API | Cyclopropylacetylene captive supply defends margins against feedstock cost volatility. |
| Local Manufacturing Licensing | Satisfies South Africa's joint venture requirements for national tender participation. |
| Pediatric Formulation Development | Oral solution capacity addresses underserved Nigeria market below 10 kilograms. |
| Community Distribution Partnership | Kenya's three-month dispensing policy rewards bypass of clinic-centric logistics. |
Methodological Framework
Multi-period observation of WHO prequalification timelines, national tender award patterns, and API import volumes anchored the trend analysis, supplemented by interviews with regulatory affairs leads at Indian contract manufacturers, procurement officers at Nigeria's national agency for food and drug administration and control, formulary directors in South Africa's national health department, and supply chain managers at Kenya's central medical stores. Secondary validation drew from FDA tentative approval databases, WHO prequalification lists, Global Fund procurement disclosures, and CDSCO manufacturing license records. Bottom-up patient volume estimates and top-down procurement spend analysis were triangulated against manufacturer capacity disclosures.
Input-output matrices mapped API synthesis costs through formulation, packaging, and distribution stages across the projection horizon. Segmentation dimensions modeled include dosage form, patient population, procurement channel, and regional regulatory cluster. CAGRs were derived from epidemiological projections of treatment-eligible populations, national program expansion commitments, and substitution rates from efavirenz to dolutegravir-based regimens. Forecast inputs incorporated environmental compliance enforcement intensity at Indian pollution control boards and South Africa's local content policy implementation pace.
The model assumes a particular technology adoption path; alternative pathways for continuous flow chemistry in API synthesis would alter the outlook for manufacturing cost structures and environmental compliance capital requirements. Forecasts reflect documented assumptions about WHO guideline stability and national program funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Bronchitis Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Measles Market
Infectious Disease
Brucellosis Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market