
 Dry Chemistry Analyzers Market | 2026-2036
Dry Chemistry Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Chemistry Analyzers Market Foresight
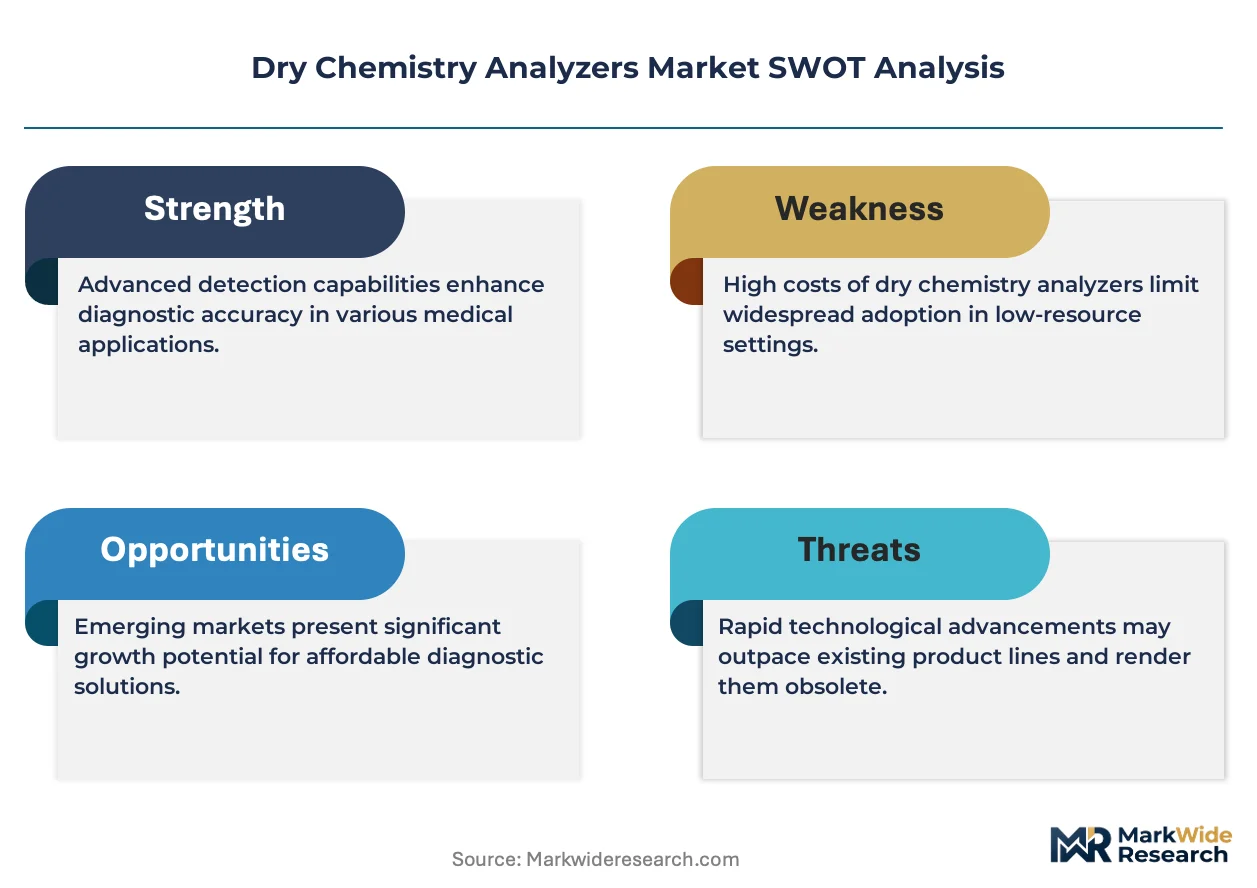
REACH compliance is realigning the cost-of-entry calculus for European manufacturers of dry chemistry consumables. Fujifilm Corporation leverages its film-coating heritage to dominate reagent strip precision, while Danaher Corporation anchors its position through Beckman Coulter's installed base in hospital laboratories. Abbott Laboratories differentiates via Alinity's integrated platform architecture across point-of-care and core lab settings.
Dry chemistry analyzers are automated diagnostic instruments that process patient samples on pre-coated reagent strips or slides without liquid reagent preparation, typically operating through reflectance photometry or electrochemical detection to quantify analytes in blood, urine, or serum. These systems eliminate water-intensive workflows and reduce operator variability, making them essential for high-throughput clinical screening and near-patient testing environments. Benchtop analyzers occupy the largest installed base due to their balance of throughput and footprint, while portable analyzers represent the fastest-expanding segment as ambulatory care networks decentralize testing capacity. Reflectance technology commands mature margin pools in routine biochemistry panels, whereas fluorescent analysis captures premium positioning in immunochemistry applications where sensitivity thresholds drive purchasing decisions.
The FDA's quality system regulation and the EU's In Vitro Diagnostic Regulation impose divergent clinical evidence requirements that fragment product registration strategies across major markets. ISO 15189 accreditation standards for medical laboratories further shape analyzer specification requirements, particularly in Europe where centralized purchasing consortia reference compliance status in tender evaluations. Stakeholders must monitor how the FDA's proposed rulemaking on laboratory-developed tests intersects with analyzer manufacturer liability frameworks.
Market Dynamics
Decentralization of diagnostic workflows is fragmenting purchasing authority from centralized hospital laboratories toward ambulatory clinics and retail health settings, forcing manufacturers to reconfigure service architectures and pricing models for lower-volume, distributed installed bases.
Growth Catalysts
- Point-of-care testing mandates:Germany's hospital reimbursement incentives prioritize rapid turnaround biochemistry panels, accelerating benchtop analyzer placements in emergency departments and satellite clinics.
- REACH compliance automation:ECHA's substance restriction timelines are compelling consumables manufacturers to reformulate reagent coatings, creating replacement demand for next-generation strip architectures.
- Reflectance photometry miniaturization:Advances in LED-based optical detection are shrinking portable analyzer footprints without sacrificing analyte precision, opening veterinary and home monitoring applications.
Market Restraints
- Reagent strip input concentration:Polymer substrate and enzyme coating supply chains concentrate among Japanese and German specialty chemical suppliers, exposing margins to petrochemical volatility.
- IVD-MDR clinical evidence burden:The EU's In Vitro Diagnostic Regulation demands expanded performance studies for Class C devices, extending registration timelines and freezing product pipeline releases.
- Liquid chemistry substitution:Wet reagent analyzers retain cost advantages for high-throughput core laboratories running panels above 50 tests per hour, capping dry chemistry penetration in centralized reference labs.
Strategic Opportunities
- India's district hospital network:The country's PLI scheme for medical devices incentivizes domestic manufacturing of diagnostic platforms, creating localized production partnerships for cost-optimized portable units.
- Fluorescent immunochemistry convergence:Integration of time-resolved fluorescence with dry slide substrates enables high-sensitivity cardiac marker detection at point-of-care, capturing premium positioning from core lab immunoassays.
- Direct-to-clinic distribution:Bypassing traditional laboratory distributor networks through manufacturer-managed e-commerce portals reduces channel margins and captures end-user data for consumable replenishment algorithms.
Industry Challenges
- ISO 15189 accreditation complexity:Medical laboratory quality standards require traceable calibration verification protocols that strain portable analyzer firmware capabilities and field service training programs.
- Legacy LIS integration friction:Hospital information system interoperability demands HL7/FHIR middleware development, extending deployment timelines and inflating professional services costs for decentralized installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Chemistry Analyzers Market |
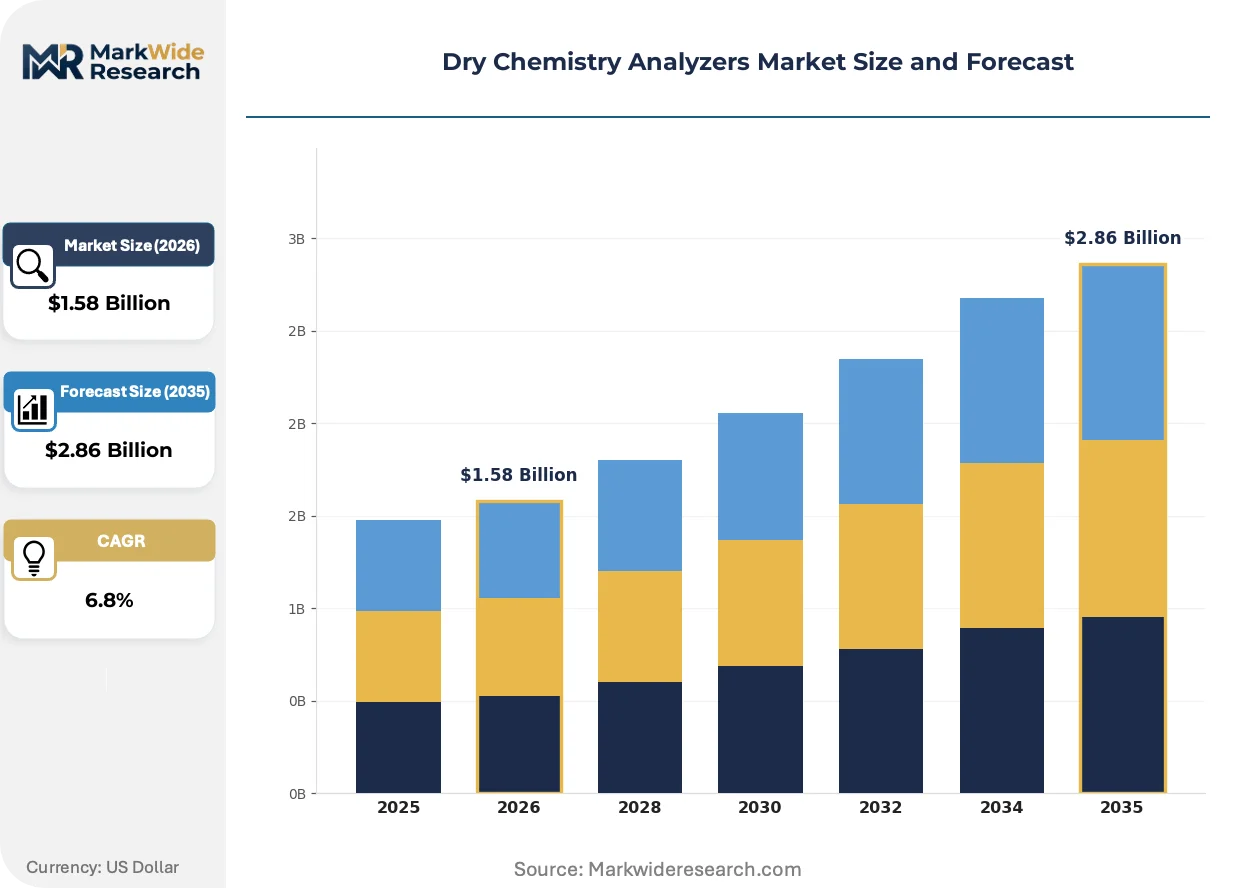
| Market Size in 2026 | $1.58 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Compact Analyzers, High-Throughput Analyzers End User: Clinical Laboratories, Hospital Laboratories, Research Institutions, Point-of-Care Settings Application: Biochemistry, Immunochemistry, Hematology, Toxicology Technology: Colorimetric Analysis, Fluorescent Analysis, Electrochemical Analysis, Reflectance Technology |
| Companies Covered | Ortho Clinical Diagnostics, Fujifilm Corporation, F. Hoffmann-La Roche Ltd., Danaher Corporation, Thermo Fisher Scientific Inc., Abbott Laboratories, ARKRAY, Diatest GmbH, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Chemistry Analyzers Market Shifts & Advancements
Instrument architectures are fragmenting into interchangeable subsystems as manufacturers compete to serve heterogeneous deployment environments from reference laboratories to retail pharmacy counters.
Microfluidic cartridge technology is modularizing assay workflows by embedding reagent storage, sample processing, and waste containment within disposable plastic housings. Emergency departments in France and the Netherlands are adopting these plug-and-play consumables to eliminate daily maintenance protocols. The shift is compressing competitive differentiation toward cartridge reliability and lot-to-lot consistency rather than analyzer hardware specifications.
MDR's post-market surveillance requirements are mandating systematic vigilance reporting for device malfunctions and serious incidents across EU member states. Manufacturers must now maintain quality management systems with notified body oversight extending through entire product lifecycles. High-risk immunochemistry analyzers face the steepest compliance burden, with several firms withdrawing legacy platforms rather than funding clinical evidence regeneration.
After-sales service unbundling is separating preventive maintenance contracts from reagent supply agreements, allowing ambulatory clinic chains to negotiate multi-vendor service coverage. Third-party independent service organizations in Texas and Florida are capturing calibration and repair work previously captive to original equipment manufacturers. This procurement fragmentation is most advanced among urgent care networks operating fifty-plus sites where standardized service level agreements outweigh brand loyalty.
Dry Chemistry Analyzers Market Segmentation
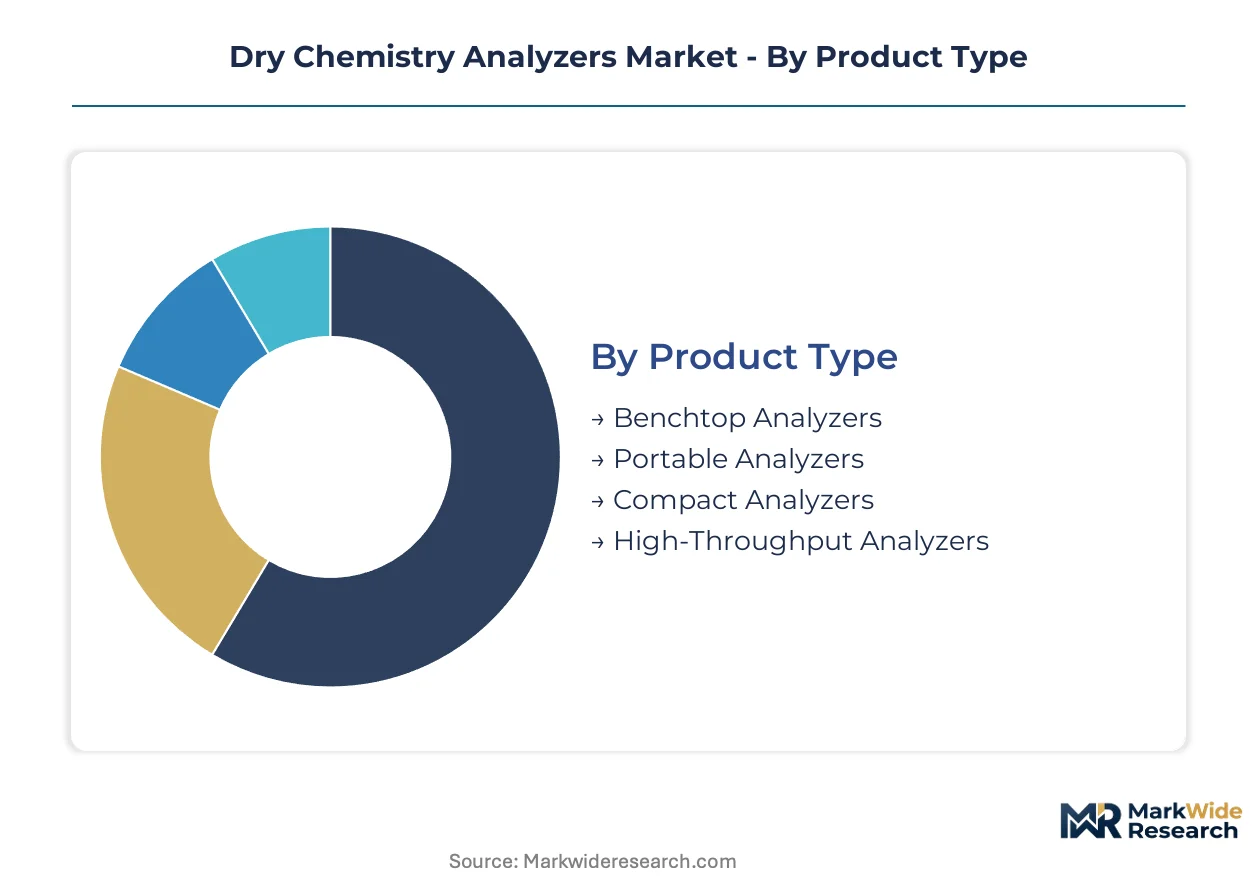
Segmentation in dry chemistry analyzers reveals how procurement authority fragments across care settings and how technology choices lock in consumable revenue streams. Understanding these divides exposes where upgrade cycles concentrate and where new entrants can bypass incumbent installed bases.
Product Type:
Replacement cycles vary sharply by footprint and throughput tier, with mid-range systems facing the steepest competitive pressure from portable alternatives.
- Benchtop Analyzers:These systems balance moderate throughput with laboratory-grade precision, typically housing 40-60 test positions and automated sample handling. Germany's hospital emergency departments favor these units for STAT biochemistry panels where reimbursement rewards rapid turnaround. Fujifilm and Beckman Coulter dominate this tier through reagent lock-in strategies.
- Portable Analyzers:Battery-powered units weighing under 5 kilograms enable testing at ambulance bays, retail clinics, and veterinary field stations. India's district hospital expansion under PLI scheme incentives is accelerating demand for cost-optimized portable architectures that operate without climate-controlled environments.
- Compact Analyzers:Intermediate footprint systems designed for satellite laboratories and urgent care chains seeking core-lab performance without infrastructure investment.
- High-Throughput Analyzers:Industrial-scale platforms processing 800+ samples hourly, reserved for centralized reference laboratories where wet chemistry substitution limits dry chemistry penetration.
Benchtop analyzers sit at the top of the volume ranking, with portable analyzers climbing the fastest as ambulatory networks decentralize testing capacity.
End User:
Procurement authority is migrating downward from centralized laboratory directors toward clinic administrators with different price sensitivity and service expectations.
- Clinical Laboratories:Independent diagnostic chains and physician office laboratories prioritize cost-per-test economics and multi-analyte menu breadth. ISO 15189 accreditation requirements in Europe shape analyzer specification checklists, particularly for calibration traceability protocols.
- Hospital Laboratories:Emergency departments and satellite clinics within hospital systems drive placements where STAT turnaround times affect patient throughput metrics. FDA quality system regulations extend compliance burdens through entire product lifecycles.
- Research Institutions:Academic medical centers and CROs demand open-system architectures enabling custom assay development on dry slide substrates.
- Point-of-Care Settings:Retail pharmacy chains and ambulatory surgery centers prioritize one-operator workflows with minimal training requirements and remote quality monitoring capabilities.
Hospital laboratories command the largest installed base value, though point-of-care settings are expanding most quickly as retail health formats proliferate.
Application:
Assay complexity determines whether reflectance photometry suffices or fluorescent detection commands premium positioning.
- Biochemistry:Routine panels for glucose, liver enzymes, and renal function represent mature demand where cost-per-test competition is fiercest. Reflectance technology dominates this high-volume, low-margin segment.
- Immunochemistry:Cardiac markers, hormones, and tumor antigens require sensitivity thresholds that fluorescent analysis achieves through time-resolved detection. EU MDR Class C classification imposes steep clinical evidence burdens on immunochemistry analyzer registrations.
- Hematology:Dry chemistry approaches face technical constraints for complete blood count parameters, limiting penetration to specialized electrolyte and hemoglobin applications.
- Toxicology:Drugs-of-abuse screening and therapeutic drug monitoring employ dry chemistry for rapid qualitative results in emergency and workplace settings.
Biochemistry generates the highest test volume, while immunochemistry delivers the steepest margin expansion trajectory.
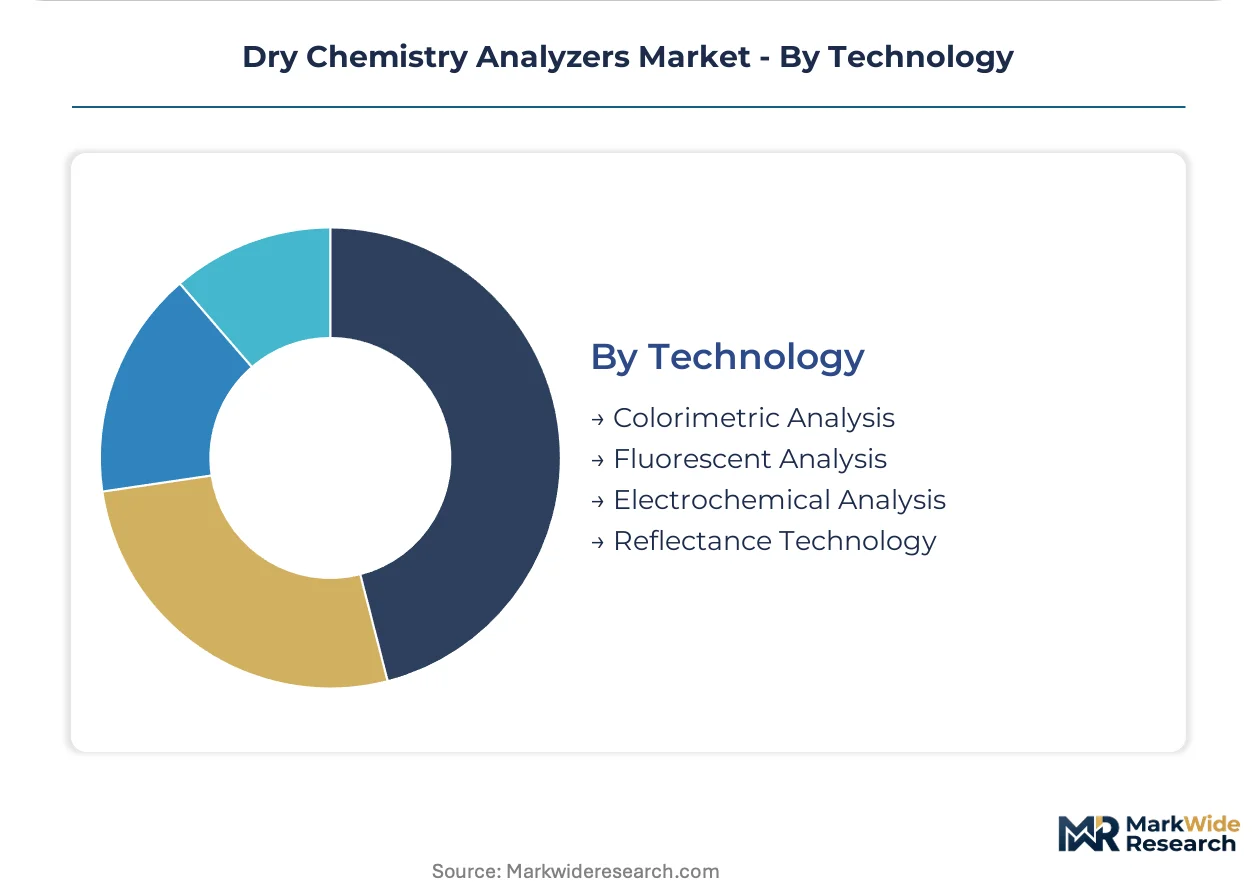
Technology:
Optical detection architectures are converging as LED miniaturization and embedded computing collapse cost differentials between legacy methods.
- Reflectance Technology:Mature photometric measurement of color change on dry reagent strips, dominant in routine biochemistry for its simplicity and cost efficiency. Danaher's installed base leverages this technology through consumable bundling contracts.
- Fluorescent Analysis:Time-resolved fluorescence enables picomolar detection limits for high-sensitivity immunoassays, capturing premium positioning from core laboratory chemiluminescence systems. Abbott's Alinity platform integrates this technology across point-of-care and core lab deployments.
- Colorimetric Analysis:Visible-light absorbance measurement for basic metabolic panels where sensitivity requirements remain modest.
- Electrochemical Analysis:Ion-selective electrodes and amperometric detection for blood gas, electrolyte, and glucose applications in critical care settings.
Reflectance technology anchors the largest installed base, with fluorescent analysis gaining share fastest as cardiac marker testing decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biomedical engineering talent clusters in Germany, Japan, and the United States anchor the geographic concentration of dry chemistry analyzer development and manufacturing expertise.
United States
Emergency department throughput metrics and retail clinic expansion drive analyzer placements across hospital systems and ambulatory networks. FDA quality system regulations for in vitro diagnostics extend compliance obligations through entire product lifecycles, reshaping development timelines. The Boston-Cambridge corridor concentrates R&D activity for next-generation optical detection platforms.
Germany
Hospital reimbursement incentives prioritize rapid-turnaround biochemistry panels in emergency and satellite laboratory settings. REACH compliance through ECHA mandates systematic reformulation of reagent coatings, generating replacement demand for consumables. The Rhine-Ruhr metropolitan region hosts precision polymer substrate suppliers serving strip manufacturing operations.
Japan
Aging demographics and decentralized primary care networks accelerate point-of-care testing adoption in clinic and home monitoring applications. PMDA regulatory frameworks align with international harmonization initiatives while maintaining distinct clinical evidence requirements. The Kanto region around Tokyo concentrates electrochemical sensor development for portable glucose and electrolyte applications.
India
District hospital network expansion under the PLI scheme for medical devices creates localized production partnerships for cost-optimized portable units. CDSCO registration pathways for Class C in vitro diagnostics are streamlining for domestically manufactured platforms. Karnataka's Bangalore-Pune corridor attracts contract manufacturing for strip-based consumables targeting South Asian and African export markets.
China
County-level hospital upgrading programs and tiered diagnosis policies push diagnostic capacity toward lower-tier medical institutions. NMPA regulatory reforms for innovative medical devices are accelerating review timelines for domestically developed platforms. The Yangtze River Delta around Shanghai concentrates reflectance photometry module assembly and LED optical component sourcing.
Dry Chemistry Analyzers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven portfolio breadth confronts targeted clinical application depth. The vendor base organizes around three archetypes: integrated diagnostics conglomerates with multi-modality platforms, film and imaging heritage companies leveraging coating precision, and regional specialists serving price-sensitive emerging markets. Consolidation pressure operates through consumable bundling contracts and installed base lock-in rather than hardware differentiation alone. Strategic moves concentrate on reagent strip supply chain control and point-of-care workflow integration partnerships.
Within the diversified conglomerate tier, Danaher Corporation and Abbott Laboratories occupy positions defined by breadth across laboratory and near-patient settings. Fujifilm Corporation exemplifies the precision manufacturing heritage archetype, translating film-coating capabilities into reagent strip architectures. Ortho Clinical Diagnostics sits within the specialized clinical chemistry segment, representing focused application depth against broader platform competitors.
| Leading Market Players |
|---|
| Ortho Clinical Diagnostics |
| Fujifilm Corporation |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| ARKRAY |
| Diatest GmbH |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Petrochemical index volatility cascades through polymer substrate costs into analyzer pricing tiers, compressing margins on economy-grade portable units while premium benchtop systems absorb input swings through consumable bundling contracts. REACH-mandated coating reformulations in Germany and ECHA substance restrictions are forcing tiered price adjustments across European consumables portfolios.
Pricing Analysis
Bundled service contracts separating preventive maintenance from reagent supply agreements are fragmenting procurement negotiations across ambulatory clinic chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 15189 accreditation status and after-sales coverage depth. Price differentiation stems from LED optical module precision grades and multi-analyte menu breadth. Cost compression in portable analyzer tiers is intensifying because Indian PLI scheme incentives attract domestic manufacturers with lower labor and facility overhead. Point-of-care settings in retail pharmacy chains exhibit the sharpest price sensitivity, while hospital emergency departments prioritize turnaround-time guarantees over per-unit economics.
Supply Chain Analysis
Photoresist-grade polymer substrates and enzyme coating precursors rest on Japanese specialty chemical producers and German precision polymer suppliers, with secondary sourcing from South Korean electrochemical sensor foundries. Dry chemistry analyzers draw from PET film substrates, rare-earth phosphors for fluorescent detection, and ion-selective electrode membranes. Single-source vulnerability concentrates in photoresist coating formulations where Fujifilm's film heritage anchors proprietary know-how. Distribution runs through laboratory distributor networks in developed markets, while direct-to-clinic e-commerce portals are capturing ambulatory segments in Texas and Florida urgent care chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through fluorescent immunochemistry convergence, where cardiac marker sensitivity thresholds command premium positioning away from commoditized reflectance biochemistry panels.
For Market Incumbents: Hedge against wet chemistry substitution in high-throughput reference laboratories by deepening reagent strip supply chain control through captive polymer substrate operations in the Rhine-Ruhr region. Accelerate firmware development for ISO 15189 calibration traceability protocols to defend installed base lock-in against third-party independent service organizations capturing preventive maintenance contracts in multi-site urgent care networks. For New Entrants and Emerging Players: Launch via direct-to-clinic e-commerce portals targeting India's district hospital expansion under PLI scheme incentives, where cost-optimized portable architectures face minimal incumbent bundling resistance. White-space opportunities concentrate in veterinary field monitoring applications and home electrolyte tracking devices, with fluorescent immunochemistry cardiac markers offering the most penetrable premium tier for point-of-care sensitivity requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with precision coating specialists possessing transferable film-manufacturing heritage applicable to reagent strip architectures. Long-term viability over the coming decade hinges on consumable revenue durability rather than hardware shipment cycles. Acquisition targets should demonstrate notified body relationships for EU MDR Class C device registrations. The signal to watch is withdrawal patterns among legacy immunochemistry platform manufacturers unable to fund clinical evidence regeneration under expanded performance study requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Strip Supply Chain Integration | Captive polymer substrate production in Germany insulates margins from petrochemical volatility and REACH reformulation costs. |
| Fluorescent Detection Platform Development | Time-resolved fluorescence modules capture cardiac marker testing volume migrating from core laboratory chemiluminescence systems. |
| Direct-to-Clinic Distribution Portal Launch | Manufacturer-managed e-commerce in Texas and Florida urgent care networks bypasses traditional laboratory distributor markups. |
| ISO 15189 Firmware Certification Investment | Traceable calibration verification protocols satisfy European centralized purchasing consortium tender requirements. |
| India PLI Scheme Manufacturing Partnership | Domestic production in Karnataka's Bangalore-Pune corridor targets cost-optimized portable units for South Asian and African export markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital laboratory directors, biomedical engineers at emergency departments, GPO contracts managers, and point-of-care clinic administrators with secondary validation against FDA 510(k) filings, EUDAMED device registrations, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up analyzer shipment modeling and top-down diagnostic equipment spending triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic baselines through regulatory transition phases established trajectory anchors across the projection horizon. Segmentation dimensions modeled include product footprint tier, end-user setting, assay application complexity, and optical detection architecture. CAGRs derived from installed base replacement cycles, ambulatory network expansion rates, and consumable pull-through coefficients. Forecast inputs incorporated REACH substance restriction timelines and FDA quality system regulation compliance cost burdens.
Several conditions sit outside the modeled scope, including laboratory-developed test regulatory reclassification outcomes and unforeseen polymer substrate supply disruptions. Forecasts reflect documented assumptions about reimbursement incentive stability and MDR notified body capacity expansion. A small set of named triggers warrants ongoing watch: EU MDR Class C clinical evidence requirement enforcement intensity, India PLI scheme incentive continuity, and LED optical component cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market