
 Warm Autoimmune Hemolytic Anemia Market | 2026-2036
Warm Autoimmune Hemolytic Anemia Market Size, Share, and Industry Trends Forecast 2026-2036
Warm Autoimmune Hemolytic Anemia Market Outlook
A shift from single-source corticosteroid dependence toward multi-source biologic sourcing is realigning procurement strategies across hematology practices. Novartis leverages its established immunology infrastructure to sustain pipeline visibility for complement-targeted approaches. Bristol Myers Squibb anchors its position through deep oncology-hematology crossover expertise. Rigel Pharmaceuticals differentiates via focused rare hematology development, occupying a narrow but defensible niche.
Warm autoimmune hemolytic anemia is an acquired hemolytic disorder characterized by IgG autoantibodies targeting erythrocyte surface antigens at body temperature, triggering extravascular destruction primarily through splenic macrophage-mediated clearance and requiring immunosuppressive or biologic intervention to preserve red cell mass. The condition serves as a critical indication for second-line and third-line therapies when corticosteroids fail or relapse occurs. Monoclonal antibodies command the most favorable margin profile among product types, reflecting manufacturing complexity and targeted mechanism premiums. The intravenous delivery mode retains dominant clinical share, though subcutaneous formulations are gaining traction in homecare and clinic settings where patient convenience drives formulary decisions.
The FDA orphan drug program and EMA's parallel designation framework shape development economics by extending market exclusivity and reducing trial burden for sponsors targeting this indication. Health Canada and Japan's PMDA maintain aligned but distinct evidentiary standards that influence multinational trial design and staggered launch sequencing. Stakeholders must monitor evolving complement inhibition data and payer willingness to cover biologic transitions ahead of steroid failure, as these forces will determine which therapeutic modalities achieve standard-of-care status.
Market Dynamics
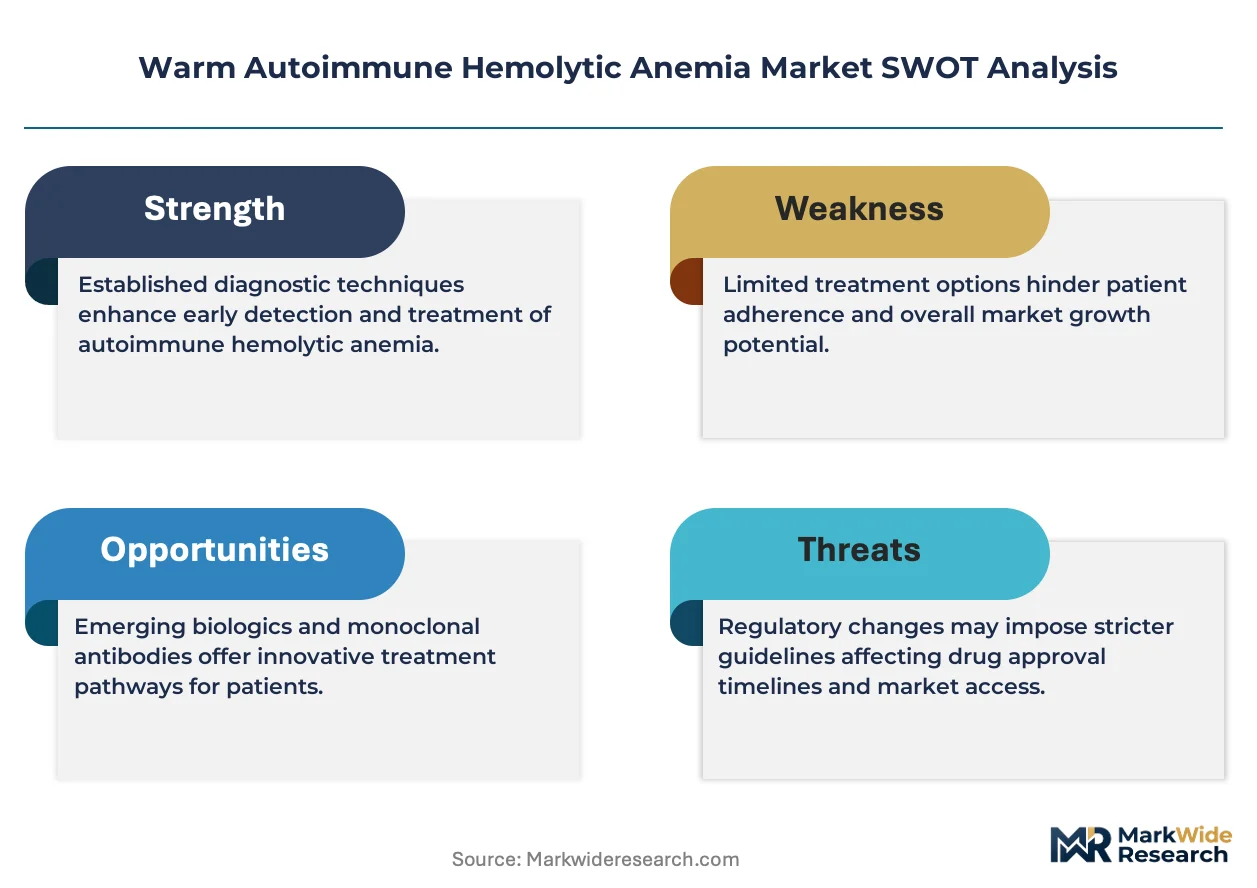
The transition from corticosteroid-first protocols toward complement-targeted biologics is restructuring prescriber behavior, procurement budgets, and clinical trial investment across hematology departments.
Growth Catalysts
- FDA Orphan Drug Designation:The extended market exclusivity and tax incentives accelerate sponsor commitment to rare hematology indications, shortening development timelines for novel biologics.
- Extravascular hemolysis pathway targeting:Advances in FcRn and C3 inhibition mechanisms address the underlying IgG-mediated red cell destruction that corticosteroids fail to control.
- Tertiary hospital hematology expansion:Specialized treatment centers in the United States are building dedicated autoimmune hemolytic anemia units with integrated infusion capabilities.
Market Restraints
- Biologic manufacturing complexity:Monoclonal antibody production requires mammalian cell culture systems with extended batch timelines and cold chain distribution infrastructure.
- Reimbursement pathway uncertainty:Payer willingness to cover second-line biologics ahead of documented steroid failure varies across commercial and Medicare Advantage plans.
- Small patient population dispersion:The orphan disease prevalence limits site recruitment for head-to-head trials and stretches field medical team coverage.
Strategic Opportunities
- Subcutaneous formulation development:Home administration routes reduce infusion center burden and expand addressable geography beyond tertiary hospital catchment areas.
- EMA parallel scientific advice:Coordinated FDA-EMA development programs enable synchronized regulatory submissions and earlier European market entry.
- Real-world evidence collection:Prospective registries tracking corticosteroid failure patterns support label expansion and payer negotiation for earlier biologic intervention.
Industry Challenges
- Immunology-hematology crossover expertise scarcity:Clinical development teams require rare blood disorder experience combined with complement biology knowledge, narrowing the qualified talent pool.
- Legacy steroid protocol entrenchment:Community hematologists maintain first-line prednisone prescribing habits despite relapse data, requiring extensive medical education investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warm Autoimmune Hemolytic Anemia Market |
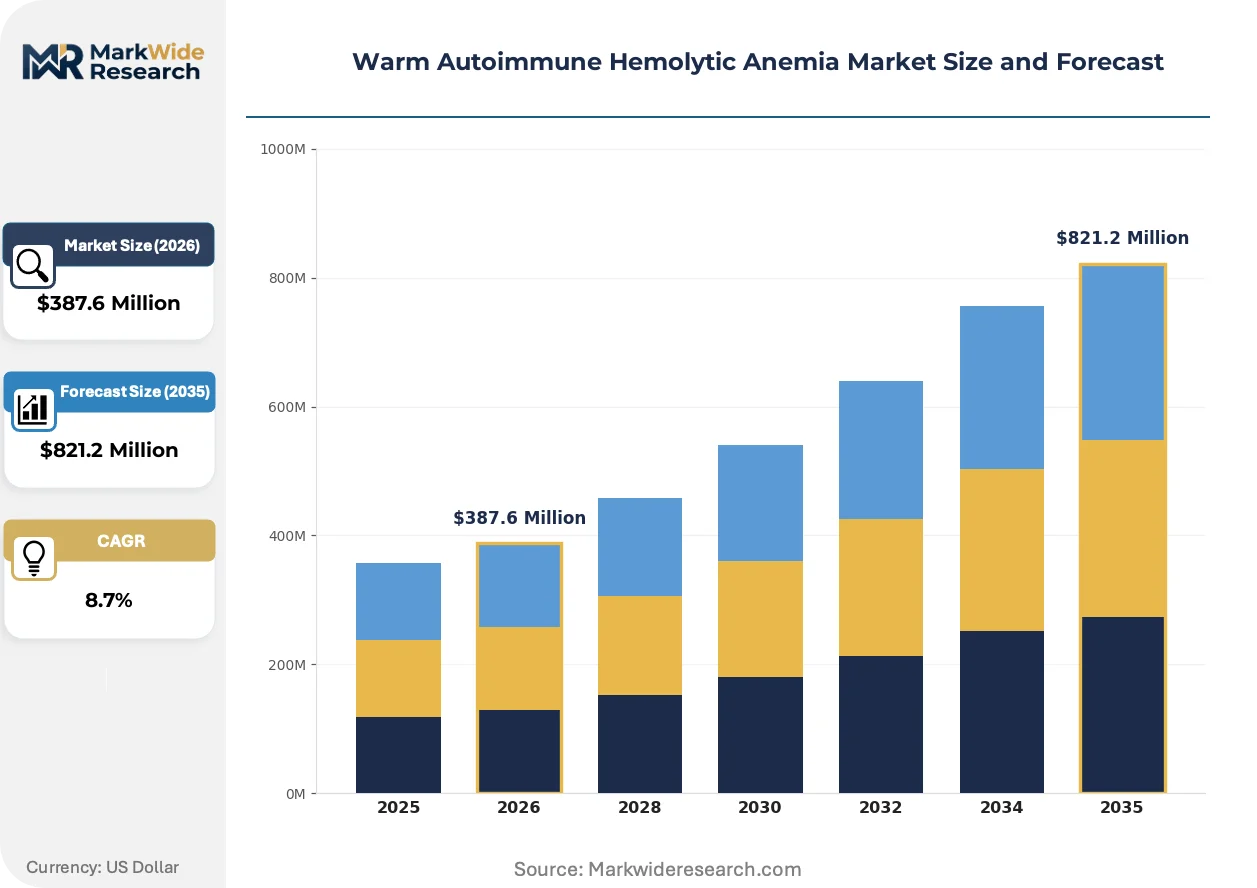
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Intravenous Immunoglobulin, Eculizumab Therapy Area: Hematology, Immunology, Oncology, Transfusion Medicine End User: Hospitals, Clinics, Homecare, Blood Banks Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation |
| Companies Covered | Novartis, Johnson & Johnson, Roche, Sanofi, AstraZeneca, Incyte Corporation, Bristol Myers Squibb, Apellis Pharmaceuticals, Rigel Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warm Autoimmune Hemolytic Anemia Market Strategic Shifts
Complement pathway science is migrating from research settings into standard clinical practice, while regulatory frameworks and care delivery models adapt to accommodate precision immunotherapy.
Complement C3 and C5 inhibition technologies are consolidating treatment paradigms in steroid-refractory cases. Hematology departments at academic medical centers are adopting these agents as second-line standards within twelve to eighteen months of approval. The shift is compressing the window for corticosteroid tapering protocols and accelerating biologic initiation timelines.
Health Canada's Priority Review pathway for drugs addressing serious unmet medical needs is compressing regulatory timelines for sponsors with Canadian trial data. The streamlined assessment reduces the gap between FDA and Health Canada approvals from historical eighteen-month lags toward six-month synchronization. Biologics with U.S. orphan designation receive expedited Canadian review, aligning North American launch sequencing.
Patient advocacy organizations are reshaping trial design priorities by demanding home administration options and reduced visit burdens. The NORD and Aplastic Anemia and MDS International Foundation are incorporating patient-reported outcome measures into protocol endpoints. This pressure is most visible in United States Phase III designs, where subcutaneous arms and decentralized monitoring are becoming standard.
Warm Autoimmune Hemolytic Anemia Market Segmentation
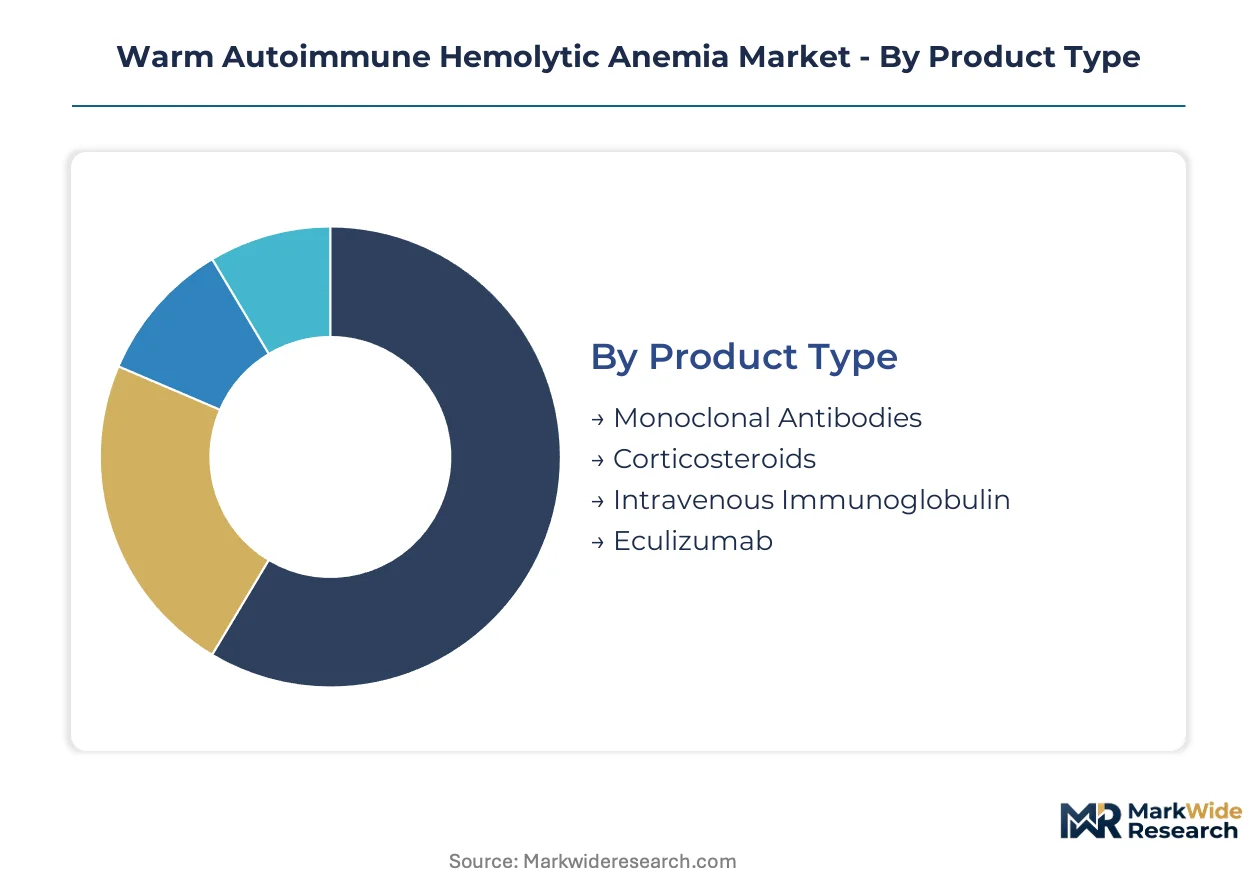
Segmentation in warm autoimmune hemolytic anemia reveals how capital allocation, clinical infrastructure, and reimbursement pathways fragment opportunity across distinct therapeutic modalities and care settings. Understanding these divisions exposes where manufacturing investment concentrates and where patient access bottlenecks emerge.
Product Type:
Capital intensity varies sharply across this category, with biologic manufacturing requiring mammalian cell culture facilities that dwarf small-molecule production costs.
- Monoclonal Antibodies:These therapeutics demand multi-hundred-million-dollar biomanufacturing infrastructure with single-use bioreactor systems and extended batch timelines. United States academic medical centers are prioritizing these agents for steroid-refractory cases, though cold chain distribution requirements limit rural access.
- Corticosteroids:Generic prednisone and methylprednisolone require minimal capital outlay for synthesis, with established API sourcing from Indian and Chinese contract manufacturers. Community hematologists in the United States continue prescribing these as first-line therapy despite documented relapse rates, preserving volume concentration in outpatient oral dispensing.
- Intravenous Immunoglobulin:Plasma fractionation dependency creates supply vulnerability tied to donor collection economics.
- Eculizumab:Terminal complement inhibition carries premium pricing and restricted distribution through specialty pharmacy networks.
Monoclonal antibodies absorb the bulk of installed capacity; corticosteroids are expanding most quickly in emerging markets with constrained biologic access.
Therapy Area:
Cross-functional expertise requirements determine where clinical trial investment concentrates and which medical specialties drive prescribing authority.
- Hematology:Academic departments at tertiary hospitals house the specialized phlebotomy, transfusion, and apheresis infrastructure required for severe hemolysis management. The American Society of Hematology treatment guidelines position these centers as gatekeepers for second-line biologic authorization.
- Immunology:Autoimmune mechanism expertise from rheumatology and allergy-immunology practices is migrating into wAIH management as complement-targeted therapies advance. United States integrated delivery networks are creating combined hematology-immunology clinics to capture this convergence.
- Oncology:Lymphoproliferative disorder overlap drives co-management in malignancy-associated secondary wAIH cases.
- Transfusion Medicine:Blood bank protocols and compatibility testing complexity create consultative demand within hospital-based transfusion services.
Hematology controls the majority of current patient volume; immunology is climbing the fastest as mechanism-based therapies reshape referral patterns.
End User:
Site-of-care economics and infusion infrastructure availability determine where biologic administration concentrates versus where oral therapy dominates.
- Hospitals:Tertiary centers with dedicated infusion suites capture complex wAIH cases requiring inpatient hemolysis management and emergency transfusion support. Medicare reimbursement for hospital outpatient infusion creates favorable economics for complement inhibitor administration in United States academic medical centers.
- Clinics:Community hematology practices manage stable patients through corticosteroid tapering protocols and routine monitoring. United States physician office infusion suites are expanding biologic capacity as subcutaneous formulations reduce nursing time requirements.
- Homecare:Subcutaneous monoclonal antibody delivery is shifting administration from facility-based to home health nursing visits.
- Blood Banks:Specialized reference laboratories handle complex antibody identification and phenotyped unit provision for transfusion-dependent patients.
Hospitals retain the largest share of biologic administration; homecare is gaining share fastest as subcutaneous formulations receive regulatory approval.
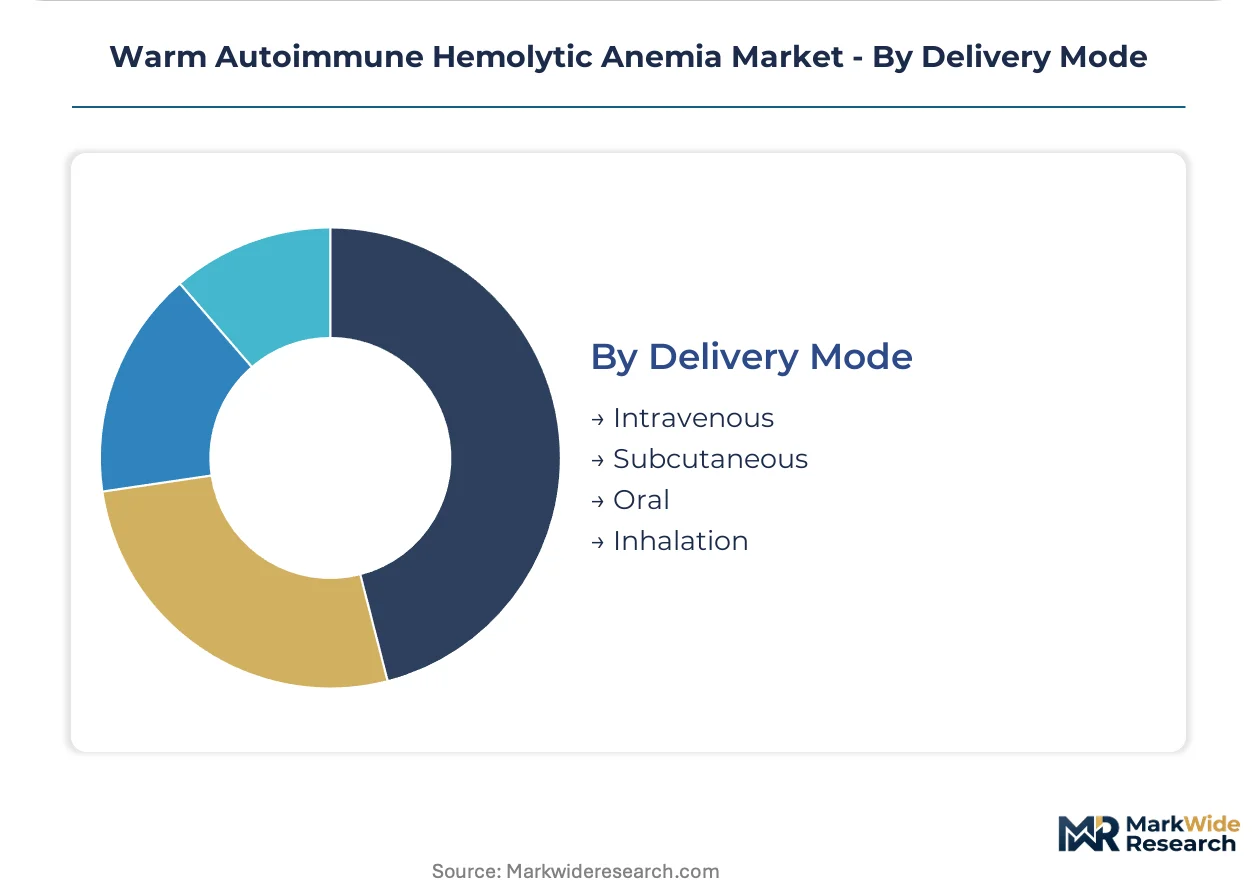
Delivery Mode:
Formulation technology investments and patient convenience preferences are restructuring administration site selection and nursing resource allocation.
- Intravenous:Infusion center capacity constraints at United States tertiary hospitals create access bottlenecks for complement inhibitors requiring weight-based dosing over extended infusion periods. Hospital pharmacy budgets absorb high per-dose costs under buy-and-bill arrangements.
- Subcutaneous:Prefilled syringe and autoinjector development is reducing dependence on infusion suite scheduling and enabling home administration. Patient advocacy organizations in the United States are pressing for subcutaneous options in Phase III trial designs.
- Oral:Prednisone tablets remain the universal first-line access point, with tapering protocols spanning months.
- Inhalation:No current approved therapies utilize this route; investigational approaches remain preclinical.
Intravenous delivery dominates current biologic volume; subcutaneous administration is expanding most quickly as formulation investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized treatment centers in the United States absorb the largest share of wAIHA biologic therapy demand, though regulatory harmonization across North America and Europe is compressing multinational launch timelines. Tertiary hospital infrastructure and payer frameworks determine where novel complement inhibitors achieve commercial traction first.
United States
Academic medical centers in Boston, New York, and Houston house dedicated autoimmune hemolytic anemia units with integrated infusion capabilities. FDA orphan drug designation accelerates development timelines through tax incentives and extended exclusivity periods. Medicare reimbursement for hospital outpatient infusion creates favorable economics for complement inhibitor administration at tertiary sites.
Germany
University hospitals in Munich, Heidelberg, and Berlin anchor European wAIHA clinical trial enrollment and early access programs. EMA parallel scientific advice with FDA enables synchronized regulatory submissions for sponsors targeting the indication. The country's hematology-immunology crossover expertise concentrates in Baden-Württemberg and Bavaria, driving adoption of mechanism-based therapies.
Japan
PMDA's Sakigake designation system provides priority review for drugs addressing serious unmet needs in rare hematology. Tokyo and Osaka metropolitan areas concentrate the specialized transfusion medicine infrastructure required for severe hemolysis management. Domestic pharmaceutical sponsors leverage this pathway to compress development timelines relative to historical lags behind FDA approvals.
United Kingdom
NHS England's specialized commissioning framework routes wAIHA patients toward designated tertiary centers in London, Manchester, and Birmingham. The MHRA's post-Brexit recognition pathway for FDA-approved orphan drugs accelerates market entry for complement-targeted biologics. Scotland and Wales maintain parallel but distinct access assessment processes that influence UK-wide launch sequencing.
Canada
Health Canada's Priority Review pathway compresses regulatory timelines for sponsors with Canadian trial data in rare hematology indications. Toronto's University Health Network and Vancouver's St. Paul's Hospital anchor national referral patterns for refractory autoimmune hemolytic anemia. Provincial formularies vary in biologic coverage ahead of documented steroid failure, creating access fragmentation.
Warm Autoimmune Hemolytic Anemia Market Competitive Environment
Portfolio diversification dominates the current landscape as established immunology players extend into rare hematology indications. The market structure concentrates around large-cap biopharmaceuticals with existing complement biology infrastructure, mid-cap rare disease specialists, and emerging biotechnology firms with targeted platform technologies. Three archetypes prevail: diversified immunology giants, focused rare hematology developers, and platform-based biotechs. Strategic partnerships and regulatory pathway optimization represent the dominant competitive moves as sponsors seek to compress development timelines and secure orphan exclusivity.
Within the diversified immunology tier, Novartis and Bristol Myers Squibb occupy positions anchored by established infrastructure. Novartis leverages its immunology and hematology crossover capabilities to sustain pipeline visibility for complement-targeted approaches. Bristol Myers Squibb draws upon deep oncology-hematology expertise to anchor its position in autoimmune blood disorders. Rigel Pharmaceuticals exemplifies the focused rare hematology specialist archetype, occupying a narrow but defensible niche through concentrated development in autoimmune hemolytic indications.
| Leading Market Players |
|---|
| Novartis |
| Johnson & Johnson |
| Roche |
| Sanofi |
| AstraZeneca |
| Incyte Corporation |
| Bristol Myers Squibb |
| Apellis Pharmaceuticals |
| Rigel Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Plasma protein fractionation costs cascade through the warm autoimmune hemolytic anemia supply chain, compressing margins for intravenous immunoglobulin while amplifying pricing power for recombinant monoclonal antibodies with mammalian cell culture sourcing.
Pricing Analysis
Volume concentrates in generic corticosteroids while margin pools in monoclonal antibodies. Three-tier pricing structure across premium complement inhibitors, standard biologics, and economy corticosteroids reflects manufacturing complexity and orphan exclusivity premiums. Price differentiation hinges on cold chain requirements and infusion infrastructure bundling. Pricing pressure stems from payer pre-authorization requirements for second-line biologics. Community hematology practices exhibit highest price sensitivity; academic medical centers absorb premium pricing for mechanism-based therapies.
Supply Chain Analysis
Mammalian cell culture supply rests on United States, Switzerland, and Singapore biomanufacturing hubs with single-use bioreactor infrastructure. Raw material dependencies span recombinant proteins, cell culture media, and chromatography resins. Supply chain risk centers on single-source vulnerability for specialty plasma-derived products. Distribution runs through specialty pharmacy networks with restricted distribution protocols for complement inhibitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around biologic developers with existing complement biology infrastructure, as biomanufacturing capital intensity forces subscale players toward partnership or exit.
For Market Incumbents: Anticipate payer consolidation by embedding real-world evidence generation into post-marketing commitments. Defensive positioning requires backward integration into plasma fractionation or captive cell culture capacity to secure input supply. Threat substitution from biosimilar entrants in the immunoglobulin category demands mechanism differentiation through FcRn or C3 inhibition platforms. For New Entrants and Emerging Players: The mid-tier pricing gap between premium complement inhibitors and generic corticosteroids offers white-space entry for subcutaneous formulation developers. Target United States community hematology practices with limited infusion capacity through home administration protocols. Go-to-market leverage rests on payer pharmacoeconomic data demonstrating reduced hospitalization costs versus intravenous alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor platform biotechs with validated C3 or FcRn mechanisms in United States clinical development. Long-term viability hinges on regulatory exclusivity duration and label expansion potential into related autoimmune hemolytic indications. Watch FDA orphan drug designation grants as inflection signals for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA and EMA parallel submissions compress development timelines and secure market exclusivity for complement-targeted biologics. |
| Subcutaneous Formulation Development | Home administration routes expand addressable geography beyond tertiary hospital catchment areas and reduce infusion center burden. |
| Real-World Evidence Registry Investment | Prospective corticosteroid failure tracking supports label expansion and payer negotiation for earlier biologic intervention. |
| Hematology-Immunology Crossover Hiring | Scarce clinical talent with complement biology and rare blood disorder expertise accelerates trial execution and KOL engagement. |
| Specialty Pharmacy Network Partnership | Restricted distribution agreements for complement inhibitors ensure cold chain integrity and patient monitoring compliance. |
Study Parameters
Document review covered FDA orphan drug filings, EMA scientific advice records, ClinicalTrials.gov protocols, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from SEC 10-K disclosures, CMS Medicare reimbursement data, and hematology society treatment guidelines. Bottom-up patient flow modeling and top-down biologic revenue triangulation anchored market sizing.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode, with regional regulatory clusters as an overlay. CAGRs derived from epidemiology-adjusted patient share projections and pricing trajectory assumptions. Forecast inputs incorporated corticosteroid failure rates and biologic penetration curves by treatment line.
Inputs from clinical trial registries and payer policy documents were available through the study window; gaps in real-world corticosteroid tapering outcome data introduce uncertainty bands around second-line biologic adoption assumptions. Forecasts reflect documented assumptions regarding regulatory approval timelines and reimbursement pathway evolution. Regulatory pathway delays, payer access restrictions, and manufacturing capacity constraints represent revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Malignant Lymphoma Market
Hematology
Sickle Cell Disease Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Anemia Drugs Market
Hematology
Blood Screening Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Haematocrit Centrifuge Market