
 Global Bleeding Disorders Market | 2026-2036
Global Bleeding Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bleeding Disorders Market Analysis
Buyer concentration among hemophilia treatment centers is pivoting toward integrated delivery networks and specialty pharmacy consolidators. Novo Nordisk A/S anchors European recombinant factor production through its Danish manufacturing footprint. CSL Behring leverages plasma fractionation scale across Australian and Swiss facilities. Roche Holding AG differentiates through its bispecific antibody platform for hemophilia A patients with inhibitors.
Bleeding disorders encompass coagulopathies characterized by deficient or dysfunctional clotting factors, platelet abnormalities, or vascular defects requiring replacement therapy, hemostatic agents, or bypassing agents to restore hemostasis. Factor Replacement Therapies dominate current revenue pools due to chronic prophylactic dosing requirements in severe hemophilia A and B populations. Recombinant Products command premium positioning as plasma-derived alternatives face supply constraints and viral safety scrutiny. Homecare Settings represent the fastest-expanding end-user channel as subcutaneous and extended half-life formulations enable patient self-administration outside institutional settings.
FDA orphan drug exclusivity and EMA PRIME designation accelerate gene therapy development timelines while WHO prequalification standards shape access in lower-income markets. The EU F-Gas Regulation and US EPA emission controls constrain cold-chain logistics infrastructure for temperature-sensitive biologics distribution. Stakeholders must monitor gene therapy durability data and payer willingness to fund one-time curative interventions against chronic replacement regimens.
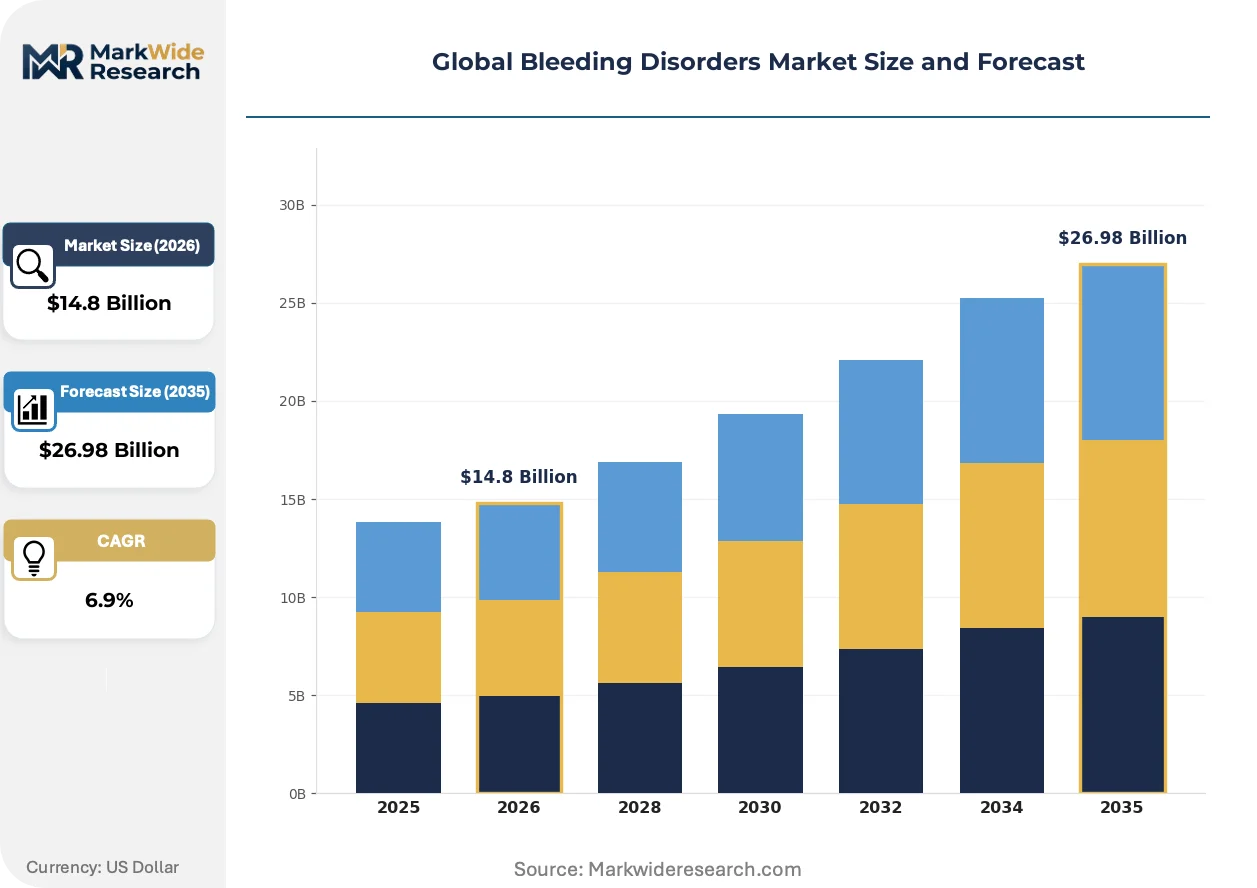
Market Dynamics
Gene therapy durability data is redirecting manufacturer investment away from chronic replacement regimens toward one-time curative interventions, compressing the addressable patient pool for traditional factor products while elevating payer scrutiny on long-term value claims.
Growth Catalysts
- EMA PRIME Designation:Accelerated approval timelines for gene therapies in Europe compress development cycles and unlock earlier revenue recognition for novel modalities.
- Homecare Self-Administration:Subcutaneous extended half-life formulations enable patients to manage prophylaxis outside hematology treatment centers, expanding addressable hours and reducing institutional burden.
- Integrated Delivery Networks:Hospital procurement consolidation across United States hemophilia treatment centers concentrates volume and standardizes formularies toward recombinant factor portfolios.
Market Restraints
- Plasma Supply Volatility:Plasma-derived product manufacturers face raw material constraints as donor frequency fluctuates and collection center capacity plateaus in key geographies.
- Cold-Chain Infrastructure Costs:EU F-Gas Regulation and US EPA emission controls constrain refrigeration capacity for temperature-sensitive biologics, elevating distribution capex requirements.
- Gene Therapy Substitution Threat:One-time curative interventions for hemophilia A and B compress lifetime value per patient and destabilize chronic replacement revenue models.
Strategic Opportunities
- Lower-Income Market Access:WHO prequalification standards create pathway for recombinant factor penetration in markets historically dependent on plasma-derived alternatives.
- Extended Half-Life Convergence:Fusion protein and PEGylation technologies enable dosing interval extension, differentiating prophylactic regimens from standard half-life competitors.
- Specialty Pharmacy Channel:Hub services and patient support programs through consolidated pharmacy networks improve adherence monitoring and capture margin from institutional settings.
Industry Challenges
- Gene Therapy Manufacturing Scale-Up:Viral vector production capacity constraints and batch-to-batch variability complicate commercial supply planning for one-time therapies.
- Payer Value Demonstration:Hematology centers must assemble real-world evidence on durability and total cost of ownership to justify premium pricing against chronic regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bleeding Disorders Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Factor Replacement Therapies, Antifibrinolytics, Desmopressin, Recombinant Products End User: Hospitals, Homecare Settings, Specialty Clinics, Blood Banks Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers Therapy Area: Hemophilia A, Hemophilia B, von Willebrand Disease, Platelet Disorders |
| Companies Covered | Takeda Pharmaceutical Company Limited, Roche Holding AG, Novo Nordisk A/S, Pfizer Inc., Bayer AG, CSL Behring, Sanofi S.A., Grifols, S.A., Octapharma AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bleeding Disorders Market Emerging Trajectories
Bispecific antibody platforms, gene editing modalities, and patient-centric delivery formats are simultaneously expanding therapeutic options and compressing traditional factor replacement economics across severe hemophilia populations.
Extended half-life recombinant factors through Fc-fusion and PEGylation chemistries are absorbing prophylactic patient volume from standard half-life products. Hemophilia A patients in Germany and Japan are transitioning to these formulations at accelerated rates. This absorption is compressing the commercial runway for legacy recombinant factors without half-life extension.
FDA orphan drug exclusivity provisions and EMA PRIME designation frameworks are compressing gene therapy development timelines from discovery to commercial approval. Manufacturers are front-loading regulatory investment to secure priority review vouchers and accelerated assessment pathways. Hemophilia B programs are most affected, with sponsors racing to establish first-mover advantage before competitive readouts.
Home infusion training and remote monitoring platforms are displacing institutional prophylaxis administration across United States hemophilia treatment centers. Specialty pharmacy networks are capturing patient relationships previously held by hospital-based hemophilia teams. This shift is most visible in pediatric and young adult segments where self-efficacy and travel burden drive preference for home-based care.
Global Bleeding Disorders Market Segmentation
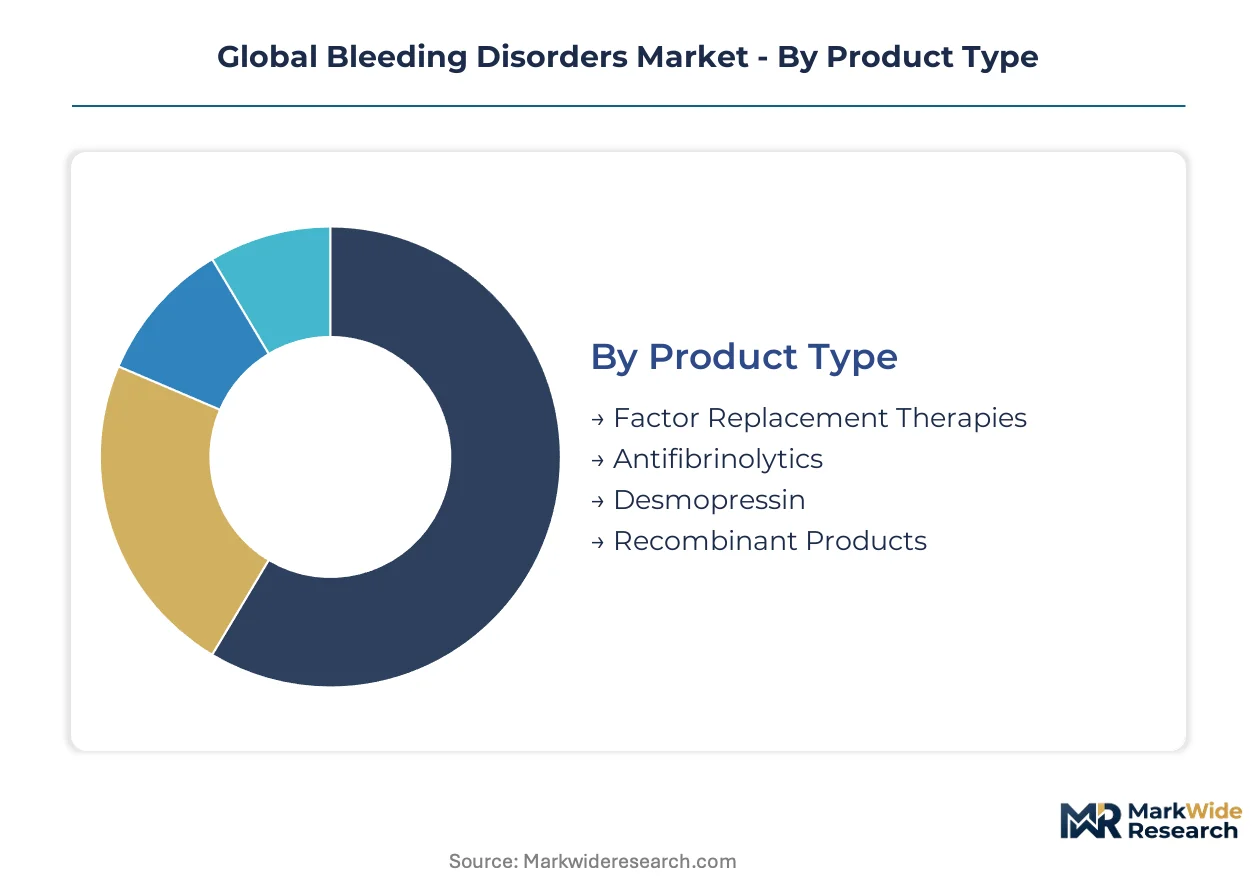
Bleeding disorders segmentation reflects divergent procurement economics across institutional versus home-based care, with therapy modality and distribution channel choices directly shaping patient adherence and lifetime value capture for manufacturers.
Product Type:
Procurement committees at hemophilia treatment centers weigh viral safety profiles against dosing convenience when selecting factor replacement portfolios.
- Factor Replacement Therapies:Plasma-derived and recombinant clotting factor concentrates restore hemostasis through intravenous infusion. Demand concentrates in severe hemophilia A populations across United States and German treatment centers where prophylactic regimens dominate clinical practice.
- Recombinant Products:Genetically engineered factors VIII and IX eliminate plasma-sourced viral transmission risk through cell culture production. Japanese and German payers mandate recombinant first-line positioning, compressing plasma-derived market share in these geographies.
- Antifibrinolytics:Tranexamic acid and epsilon-aminocaproic acid stabilize fibrin clots through plasmin inhibition. Adjunctive use in dental procedures and menorrhagia management drives volume in European markets.
- Desmopressin:Synthetic vasopressin analog releases endogenous von Willebrand factor from endothelial stores. Mild hemophilia A and type 1 von Willebrand Disease patients in outpatient settings favor this non-replacement option.
Factor Replacement Therapies lead on scale; Recombinant Products lead on momentum.
End User:
Site-of-care migration is redistributing revenue capture away from hospital infusion centers toward patient-directed administration environments.
- Homecare Settings:Self-administered subcutaneous and extended half-life formulations enable prophylaxis outside institutional walls. United States pediatric and young adult segments are transitioning fastest as specialty pharmacy networks build hub-and-spoke infrastructure for remote patient monitoring.
- Hospitals:Acute bleeding episodes and surgical interventions require inpatient factor replacement with pharmacy oversight. German hemophilia treatment centers maintain stronger hospital-based prophylaxis models than Anglo-Saxon markets.
- Specialty Clinics:Dedicated hemophilia treatment centers coordinate multidisciplinary care including physiotherapy and genetic counseling. United Kingdom and Netherlands networks emphasize these centralized models.
- Blood Banks:Plasma collection and fractionation operations supply raw material for derived factor products. Australian and Swiss facilities anchor CSL Behring's vertical integration strategy.
Hospitals retain the largest installed base; Homecare Settings are expanding most quickly.
Distribution Channel:
Cold-chain reliability and patient data integration determine channel preference for temperature-sensitive biologics.
- Hospital Pharmacies:Integrated delivery networks consolidate factor purchasing across United States hemophilia treatment centers, capturing volume discounts and standardizing formularies toward extended half-life portfolios.
- Specialty Pharmacy Networks:Hub services providers manage prior authorization, benefits investigation, and home nursing coordination. United States market structure favors this channel for chronic prophylactic patients.
- Retail Pharmacies:Community access points serve episodic desmopressin and antifibrinolytic demand. Limited penetration for factor concentrates due to storage and handling requirements.
- Wholesalers:Three-tier distribution infrastructure moves product from manufacturer to institutional settings. EU F-Gas Regulation compliance adds refrigeration capex burden to this channel.
Hospital Pharmacies dominate transaction volume; Specialty Pharmacy Networks show the steepest expansion trajectory.
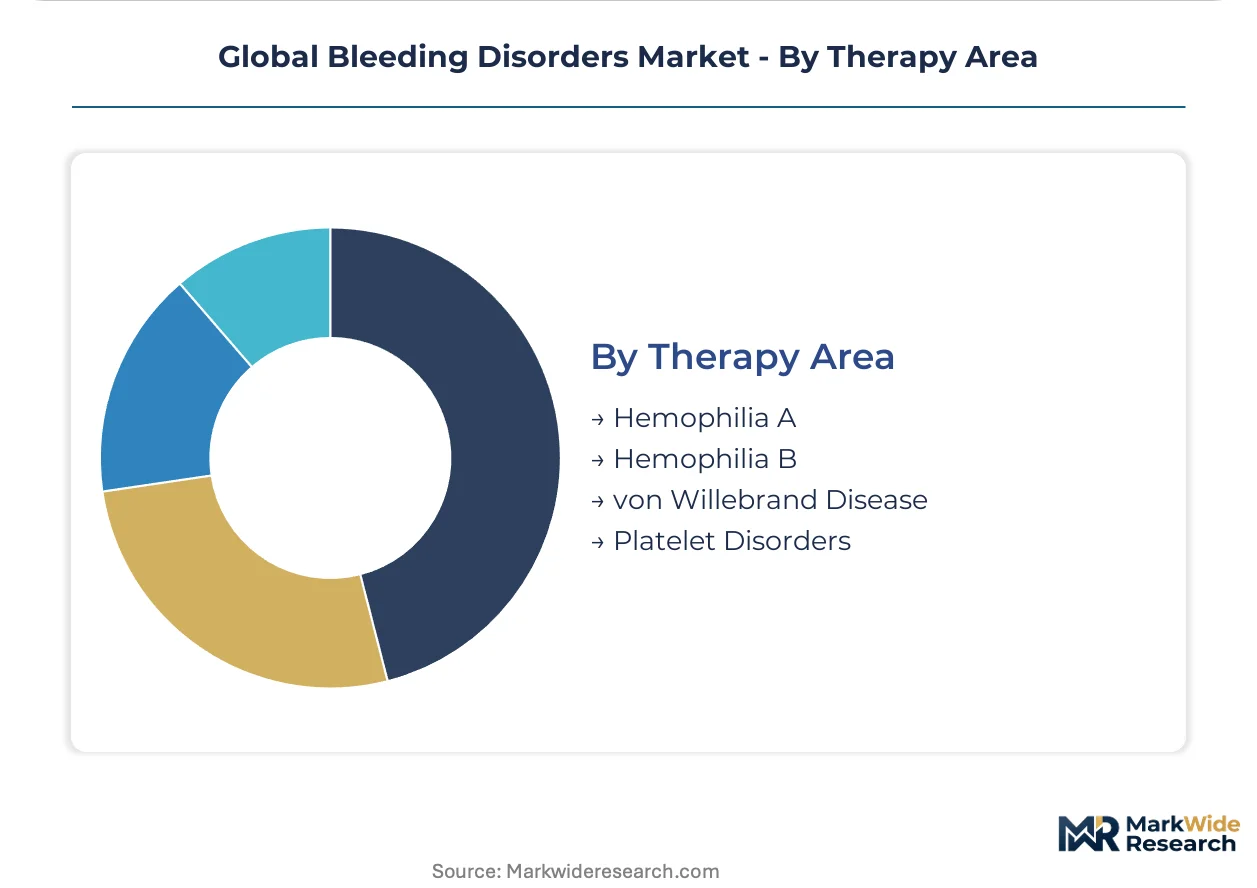
Therapy Area:
Genetic prevalence and severity distribution shape addressable patient pools and pricing power across clotting factor deficiencies.
- Hemophilia A:Factor VIII deficiency represents the largest addressable population among inherited bleeding disorders. United States and Japanese severe patient cohorts drive prophylactic factor consumption.
- Hemophilia B:Factor IX deficiency offers more favorable gene therapy vector payload economics due to smaller coding sequence. EMA PRIME designation acceleration targets this indication for first curative approvals.
- von Willebrand Disease:Most common inherited bleeding disorder with variable severity and type-dependent treatment algorithms. Desmopressin-responsive type 1 patients limit factor concentrate penetration.
- Platelet Disorders:Thrombocytopenia and platelet function defects require distinct hemostatic approaches including platelet transfusion and bypassing agents. Smaller commercial opportunity due to heterogeneity and acute treatment paradigms.
Hemophilia A leads on scale; Hemophilia B leads on innovation investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains denser hemophilia treatment center networks per capita than the United States, while Japan's PMDA accelerates gene therapy review timelines faster than FDA counterpart pathways. National reimbursement frameworks and regulatory agility determine where manufacturers prioritize launch sequencing.
United States
Integrated delivery networks consolidate purchasing across hemophilia treatment centers in Boston, Chicago, and Los Angeles. FDA orphan drug exclusivity provisions accelerate gene therapy development timelines for hemophilia B programs. Specialty pharmacy networks in Florida and Texas capture patient relationships through hub-and-spoke infrastructure for home infusion.
Germany
Hospital-based prophylaxis models persist stronger than Anglo-Saxon markets, with hematology centers in Munich and Hamburg anchoring recombinant factor demand. EMA PRIME designation frameworks compress assessment timelines for novel modalities. Bavarian and North Rhine-Westphalian treatment networks emphasize multidisciplinary care coordination including physiotherapy access.
Japan
PMDA's Sakigake designation system prioritizes hemophilia gene therapy applications for expedited review. Severe hemophilia A patient cohorts in Tokyo and Osaka drive prophylactic factor consumption. METI reimbursement frameworks mandate recombinant first-line positioning, compressing plasma-derived market share.
Switzerland
Swissmedic's accelerated access pathways attract gene therapy sponsors seeking early European approval. Plasma fractionation facilities in Bern and Zurich anchor CSL Behring's vertical integration strategy. The country's centralized healthcare procurement concentrates volume toward extended half-life recombinant portfolios.
Australia
TGA's priority review pathways align with hemophilia gene therapy development timelines. Blood bank infrastructure in Melbourne and Sydney supplies raw material for plasma-derived production. The national blood service's centralized purchasing standardizes formularies across state-based treatment networks.
Global Bleeding Disorders Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across recombinant factor, plasma-derived, and gene therapy modalities. Market structure tilts toward consolidation as hematology center procurement concentrates volume among manufacturers with cold-chain reliability and extended half-life portfolios. Three archetypes dominate: plasma fractionation specialists with captive collection infrastructure, recombinant biotech platforms with Danish or Swiss manufacturing footprints, and gene therapy developers racing for first-mover advantage in hemophilia B. Competitive moves center on M&A for viral vector manufacturing capacity and strategic partnerships for patient hub services.
Among European recombinant specialists, Novo Nordisk A/S and Roche Holding AG occupy positions anchored by manufacturing scale and bispecific platform differentiation respectively. CSL Behring represents the plasma fractionation archetype with Australian and Swiss production assets. These three companies exemplify how geographic manufacturing concentration and modality specialization determine competitive positioning as gene therapies threaten traditional replacement economics.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Roche Holding AG |
| Novo Nordisk A/S |
| Pfizer Inc. |
| Bayer AG |
| CSL Behring |
| Sanofi S.A. |
| Grifols, S.A. |
| Octapharma AG |
| Others |
Supply Flow & Price Mechanics
Captive plasma collection networks across Australian and Swiss facilities anchor CSL Behring's supply position while simultaneously insulating its recombinant factor pricing from raw material volatility that compresses competitors' margins. This backward integration into donor pools creates asymmetric pricing power against manufacturers dependent on third-party plasma sourcing.
Pricing Analysis
Capacity additions in Denmark and Switzerland are reshaping price floors for extended half-life recombinant factors as Novo Nordisk and Roche scale manufacturing output. Contract-based long-term offtake agreements dominate procurement between integrated delivery networks and manufacturers, with price differentiation hinging on cold-chain reliability certification and dosing interval performance. Cost compression in standard half-life tiers is intensifying because gene therapy substitution threatens chronic replacement revenue models. Pediatric hemophilia treatment centers exhibit highest price sensitivity due to budget constraints, while adult prophylactic patients with inhibitor complications command premium positioning.
Supply Chain Analysis
Freight cost escalation across EU F-Gas Regulation compliance routes is elevating distribution capex for temperature-sensitive biologics moving between Swiss fractionation facilities and German treatment centers. Supply concentrates in Australia, Switzerland, and Denmark for plasma-derived and recombinant production, with raw material dependencies spanning plasma donor pools, cell culture media, and viral vector feedstocks. Single-source vulnerability in viral vector manufacturing capacity complicates gene therapy commercial supply planning. Distribution runs through three-tier wholesaler infrastructure with hospital pharmacy and specialty pharmacy network terminations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bleeding disorders market represents a late-cycle quality story as hemophilia treatment centers consolidate procurement around manufacturers demonstrating durable gene therapy data and extended half-life formulation superiority.
For Market Incumbents: Acquire viral vector manufacturing capacity to secure gene therapy supply position against batch-to-batch variability constraints. Deepen backward integration into plasma collection infrastructure to defend margin position against donor frequency fluctuations. Prioritize EMA PRIME designation acceleration for hemophilia B programs before competitive readouts compress first-mover returns. For New Entrants and Emerging Players: Enter via WHO prequalification pathways for recombinant factor penetration in lower-income markets historically dependent on plasma-derived alternatives. Target pediatric homecare segments in United States specialty pharmacy networks where patient self-administration training creates sticky relationships. Pursue licensing agreements with established cold-chain logistics providers rather than building proprietary distribution infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where gene therapy durability data validates one-time curative interventions against chronic replacement economics. Long-term viability favors manufacturers with diversified modality portfolios spanning recombinant, plasma-derived, and gene therapy platforms. Watch EMA PRIME designation timelines and payer coverage decisions for hemophilia B gene therapies as inflection indicators for traditional factor replacement valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Viral vector capacity expansion in Swiss and Danish facilities secures gene therapy commercial supply. |
| Regulatory Approval Pathway | EMA PRIME designation acceleration compresses hemophilia B development timelines against FDA counterparts. |
| Strategic Partnership | Specialty pharmacy hub services partnerships capture patient relationships from hospital-based hemophilia teams. |
| Pipeline Diversification | Bispecific antibody platforms extend Roche's addressable population to inhibitor-positive hemophilia A patients. |
| Long-term Supply Agreement | Integrated delivery network contracts standardize formularies toward extended half-life recombinant portfolios. |
Methodological Framework
Bottom-up hemophilia treatment center demand modeling reconciled against top-down plasma fractionation and recombinant manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Triangulation between patient volume estimates and production output data ensures segmentation integrity across therapy modalities.
Historical trendline analysis of factor consumption patterns across severe hemophilia A and B populations informs projection mechanics over the analysis window. Segmentation dimensions modeled include product type, end-user setting, distribution channel, and therapy area with regional regulatory cluster overlays. CAGRs were derived from elasticity-adjusted demand curves incorporating gene therapy substitution scenarios and extended half-life formulation uptake trajectories. Forecast inputs incorporate EMA PRIME designation timelines and integrated delivery network procurement consolidation patterns.
Inputs from clinical trial registries and hemophilia treatment center pharmacy directors were available through the study window; gaps in gene therapy durability data beyond initial follow-up periods introduce uncertainty bands around long-term revenue projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Malignant Lymphoma Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Neutropenia Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Thalassemia Treatment Market
Hematology
Blood Screening Market
Hematology
Sickle Cell Anemia Market
Hematology
At-Home Hematology Testing Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Hematology Analyzers Market
Hematology
Blood Plasma Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Hematologic Malignancies Market