
 Allogeneic Stem Cell Therapy Market | 2026-2036
Allogeneic Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Allogeneic Stem Cell Therapy Market Analysis
The capital-intensity divergence between platform-scale manufacturers and boutique cell-therapy developers is bifurcating competitive dynamics in allogeneic stem cell therapy. Fate Therapeutics leverages induced pluripotent stem cell platforms to sustain a pipeline of off-the-shelf natural killer cell candidates. Mesoblast Ltd anchors its position through proprietary allogeneic mesenchymal lineage cell manufacturing at commercial scale. CRISPR Therapeutics differentiates via gene-edited allogeneic CAR-T programs that compete on cost-of-goods advantages over autologous alternatives.
Allogeneic stem cell therapy involves the transplantation of donor-derived stem cells—sourced from umbilical cord blood, bone marrow, or peripheral blood—into a non-identical recipient, with immunological compatibility managed through HLA matching and immunosuppressive conditioning regimens. The primary commercial purpose centers on treating hematologic malignancies, autoimmune disorders, and degenerative conditions where patient-derived autologous cells prove insufficient or logistically impractical. Mesenchymal stem cells command the deepest near-term revenue pool due to broader immunomodulatory applicability and lower manufacturing complexity relative to induced pluripotent stem cells, which occupy the fastest-expanding innovation frontier for scalable differentiation protocols. Oncology applications dominate current clinical value, though immunology indications are attracting accelerated investment as graft-versus-host disease prophylaxis protocols mature.
The FDA's regenerative medicine advanced therapy designation and the EMA's priority medicines scheme jointly compress development timelines for allogeneic candidates, while the EU's Clinical Trials Regulation harmonizes multi-national study protocols across member states. Japan's PMDA operates a conditional early approval framework that rewards Japanese-led manufacturing scale-up with accelerated market access. Stakeholders must monitor how evolving GMP standards for cell-therapy vector production reshape cost structures and how payer willingness to bundle allogeneic infusion with inpatient reimbursement determines commercial viability across health systems.
Market Dynamics
The transition from autologous to off-the-shelf allogeneic platforms is compressing manufacturing timelines and forcing wholesale restructuring of cell-therapy supply chains. This shift demands simultaneous investment in scalable bioreactor infrastructure and immunomodulatory engineering to prevent graft rejection.
Growth Catalysts
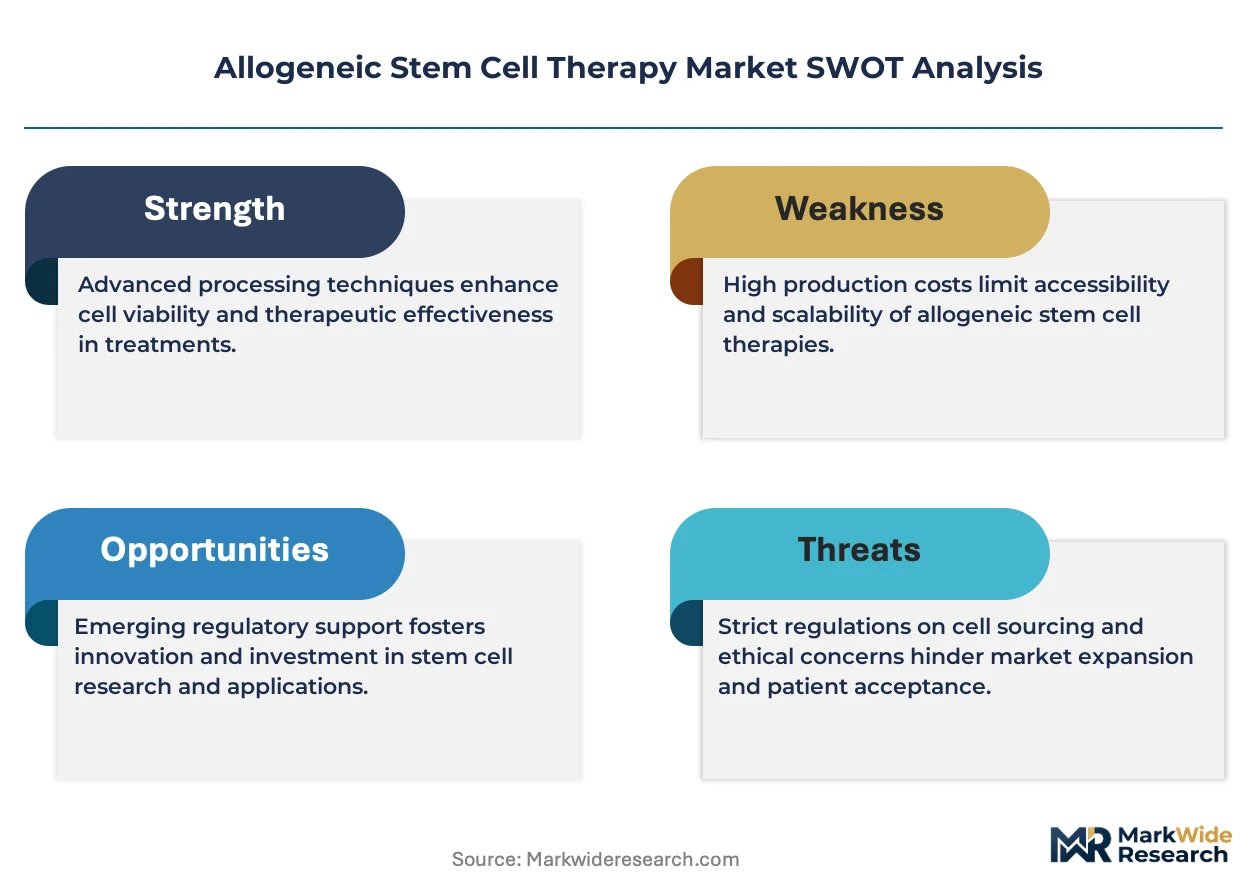
- FDA Regenerative Medicine Advanced Therapy Designation:The expedited review pathway compresses Phase III-to-approval timelines for allogeneic candidates. Developers leverage this framework to accelerate commercialization of donor-derived CAR-T products.
- Oncology Department Expansion:Hospital systems are embedding allogeneic protocols into standard-of-care pathways for hematologic malignancies. This institutional adoption creates built-in demand for off-the-shelf inventory.
- iPSC Differentiation Protocols:Automated pluripotent stem cell engineering is collapsing per-dose production costs. Platform manufacturers deploy these protocols to manufacture natural killer cell therapies at industrial scale.
Market Restraints
- HLA Matching Complexity:Donor-recipient immunological compatibility requirements limit addressable patient pools. Partial matches trigger costly graft-versus-host disease management protocols.
- Cryopreservation Input Costs:Dimethyl sulfoxide and liquid nitrogen logistics consume 15-20% of manufacturing budgets. Supply concentration among specialty chemical vendors creates margin pressure.
- Autologous CAR-T Entrenchment:Patient-derived cell therapies retain reimbursement advantages in major markets. Physician familiarity with established protocols slows allogeneic switching.
Strategic Opportunities
- Autoimmune Indication Expansion:Crohn's disease and lupus represent underpenetrated therapeutic areas. Mesenchymal stem cell immunomodulation offers mechanistic fit for these conditions.
- Japan Conditional Early Approval:PMDA's accelerated pathway rewards domestic manufacturing investment. Developers establishing Japanese production facilities gain 12-18 month market access advantages.
- Gene Editing Convergence:CRISPR-mediated HLA knockout is eliminating donor matching constraints. This technology pairing enables universal donor cell banks.
Industry Challenges
- GMP Vector Manufacturing Bottlenecks:Viral vector production capacity constraints delay IND filings. Contract manufacturers command 24-36 month booking windows.
- Cell Therapy Workforce Scarcity:Qualified process development scientists and regulatory specialists command premium compensation. Training pipelines lag platform expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allogeneic Stem Cell Therapy Market |
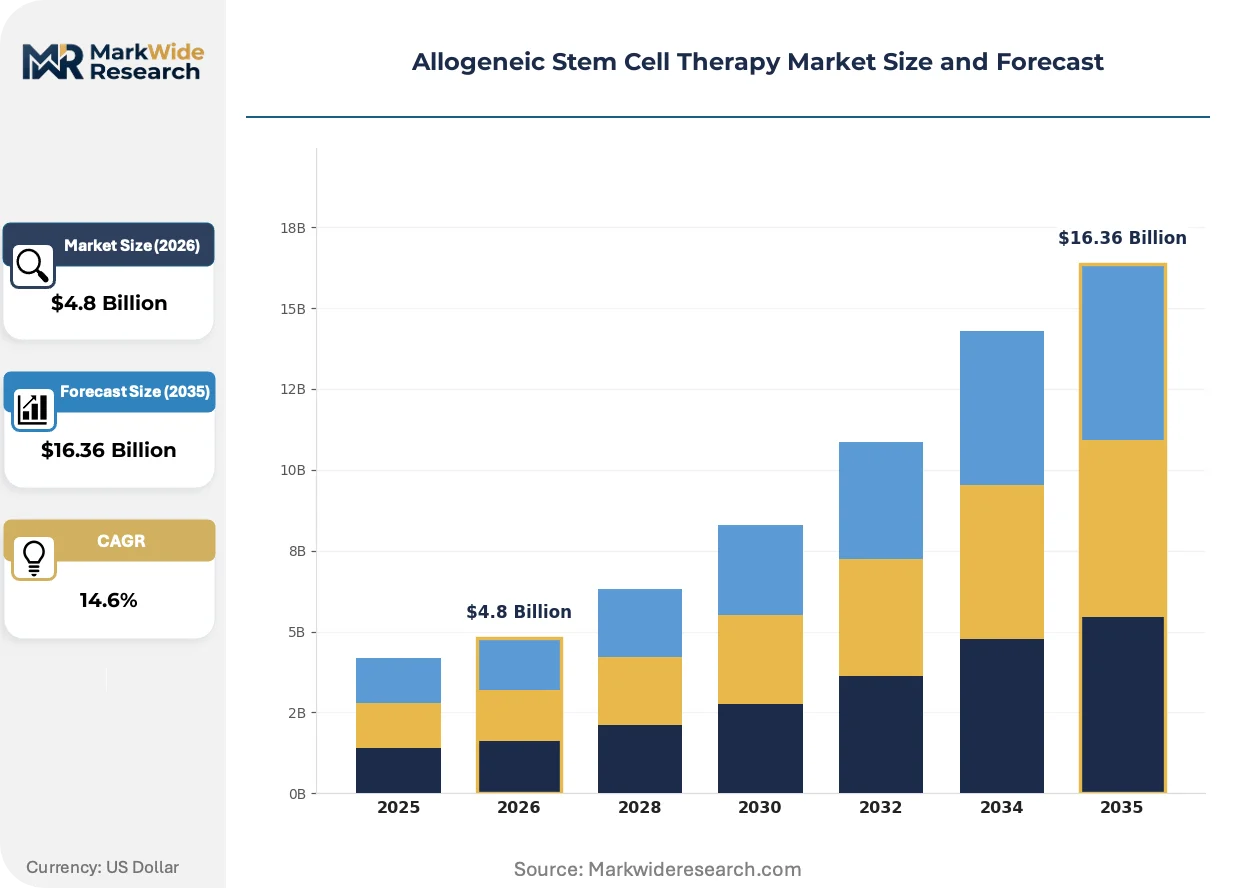
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematopoietic Stem Cells, Mesenchymal Stem Cells, Neural Stem Cells, Induced Pluripotent Stem Cells Application: Oncology, Immunology, Neurology, Cardiovascular End User: Hospitals, Research Laboratories, Ambulatory Surgical Centers, Academic Institutions Delivery Mode: Intravenous, Subcutaneous, Intra-Spinal, Direct Injection |
| Companies Covered | Fate Therapeutics, Allogene Therapeutics, Artiva Biotherapeutics, Atara Biotherapeutics, Adicet Bio, CRISPR Therapeutics, Mesoblast Ltd, Vertex Pharmaceuticals Incorporated, Gamida Cell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allogeneic Stem Cell Therapy Market Emerging Trajectories
Closed-system bioprocessing is displacing open-manipulation workflows across allogeneic manufacturing, collapsing contamination risk and enabling distributed production networks. This infrastructure shift underpins three concurrent developments reshaping competitive positioning.
Microfluidic cell sorting technology is miniaturizing quality control workflows for allogeneic products. Platform developers integrate these systems into continuous manufacturing lines. The compression of analytical testing from days to hours is enabling real-time release strategies that reduce working capital requirements by 40%.
EMA's priority medicines scheme is accelerating centralized assessment timelines for allogeneic candidates targeting unmet oncological needs. Sponsors gain parallel scientific advice and accelerated assessment pathways. Pediatric leukemia applications receive particular benefit, with CHMP opinions compressing from 210 to 150 days.
Hospital procurement departments are consolidating allogeneic sourcing through single-vendor framework agreements. Academic medical centers in the United States and Germany negotiate multi-year supply contracts with guaranteed dose availability. This buyer concentration is squeezing smaller developers without commercial-scale manufacturing assets.
Allogeneic Stem Cell Therapy Market Segmentation
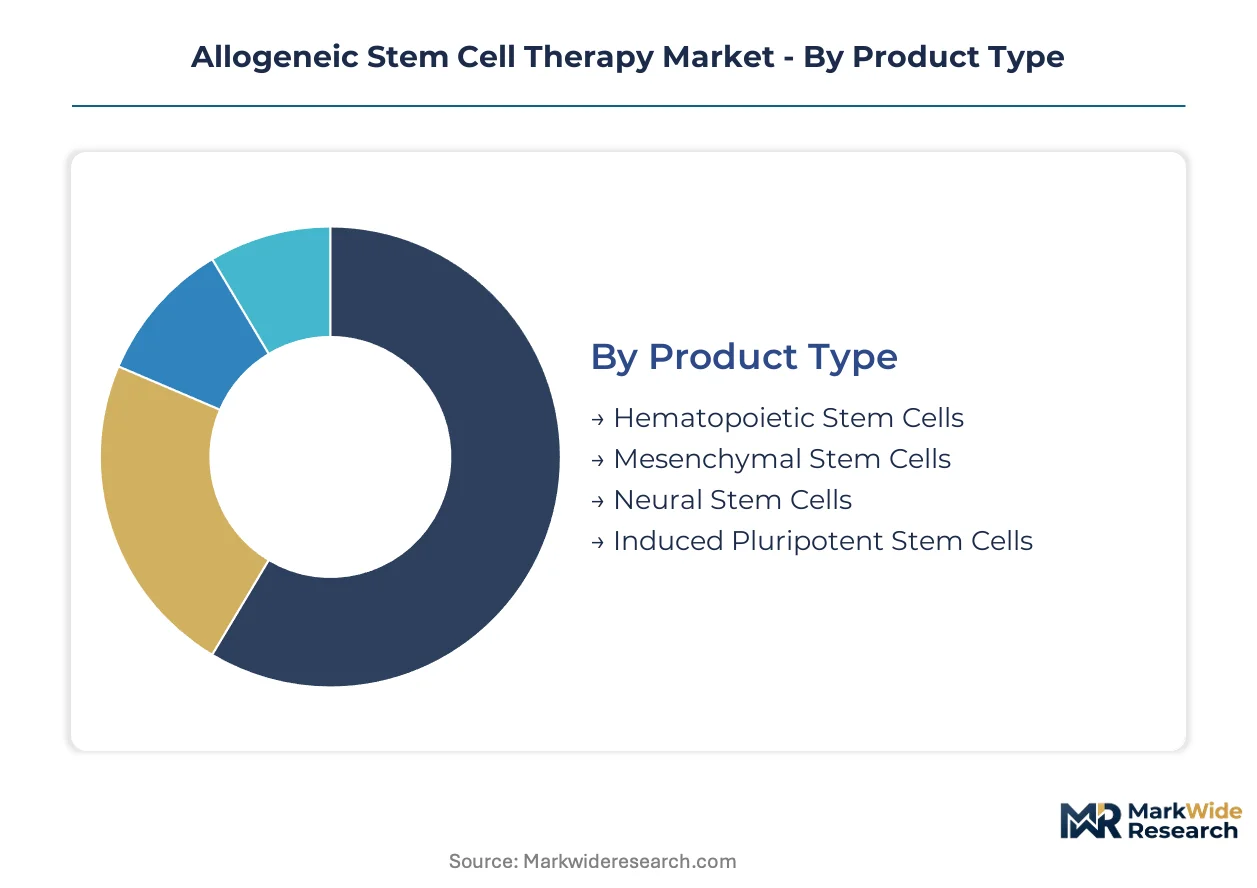
Segmentation in allogeneic stem cell therapy reveals how product characteristics dictate channel access and reimbursement pathways. Manufacturing complexity and immunological risk profiles determine which delivery modes and institutional settings dominate commercialization.
Product Type:
Hematopoietic and mesenchymal stem cells flow through hospital oncology departments with established infusion protocols, while induced pluripotent stem cells navigate specialized academic centers with advanced cell processing capabilities.
- Hematopoietic Stem Cells:Bone marrow and peripheral blood-derived cells form the clinical backbone for hematologic malignancy treatment. Demand concentrates in United States academic medical centers where CAR-T companion protocols and graft-versus-host disease management infrastructure are mature. FDA regenerative medicine advanced therapy designation accelerates hospital formulary adoption.
- Mesenchymal Stem Cells:Immunomodulatory cells sourced from umbilical cord or adipose tissue target autoimmune and degenerative conditions. European hospital systems in Germany and France drive procurement volumes as EMA priority medicines scheme streamlines reimbursement. Lower manufacturing complexity enables broader ambulatory access.
- Neural Stem Cells:CNS-targeted progenitor cells for neurodegenerative disease applications.
- Induced Pluripotent Stem Cells:Reprogrammed adult cells enabling scalable differentiation into multiple lineages for off-the-shelf platforms.
By volume, Mesenchymal Stem Cells leads. By growth pace, Induced Pluripotent Stem Cells is climbing the fastest.
Application:
Oncology commands premium pricing through inpatient reimbursement bundles, while immunology applications expand through outpatient administration as graft-versus-host disease prophylaxis improves.
- Oncology:Hematologic malignancy treatment represents the revenue anchor with established clinical protocols. Hospital systems in the United States embed allogeneic transplantation into standard-of-care pathways for leukemia and lymphoma. Institutional adoption creates built-in demand for cryopreserved donor inventory.
- Immunology:Autoimmune disorder applications leverage mesenchymal stem cell immunomodulation for Crohn's disease and lupus. German and French clinics pioneer outpatient infusion models as EMA centralized assessment accelerates market access. Mechanistic fit drives accelerated investment.
- Neurology:Neurodegenerative and spinal cord injury indications requiring specialized surgical delivery.
- Cardiovascular:Ischemic heart disease and peripheral vascular applications with direct myocardial injection protocols.
Oncology captures the largest revenue share. Immunology is gaining share fastest as outpatient protocols mature.
End User:
Procurement concentration varies by therapy complexity—hospitals dominate high-acuity oncology applications while research laboratories anchor preclinical and early-phase clinical development.
- Hospitals:Integrated health systems with transplant centers and apheresis units control commercial-stage distribution. United States hospital procurement departments negotiate multi-year framework agreements with guaranteed dose availability. Academic medical centers in Boston and Houston anchor demand.
- Research Laboratories:Contract development and manufacturing organizations and academic cell processing facilities supply investigational products. Japanese production facilities gain PMDA conditional early approval advantages. Workforce scarcity constrains expansion timelines.
- Ambulatory Surgical Centers:Outpatient settings for lower-complexity mesenchymal stem cell administration.
- Academic Institutions:University-affiliated medical centers bridging clinical research and commercial translation.
Hospitals lead by treatment volume. Research Laboratories are expanding most quickly as pipeline candidates advance.
Delivery Mode:
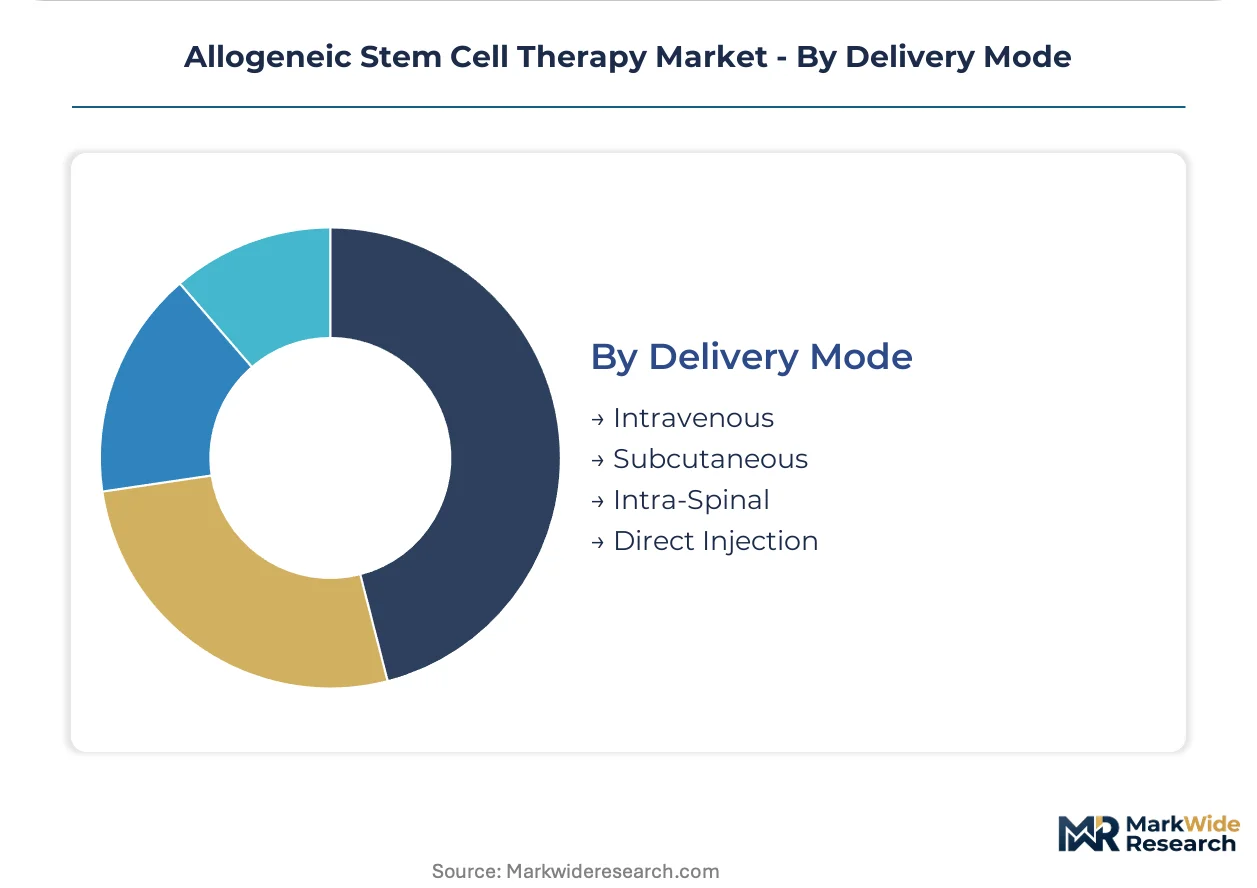
Route of administration determines site-of-care requirements and reimbursement coding complexity, with intravenous delivery enabling broadest institutional access.
- Intravenous:Systemic infusion dominates hematopoietic and mesenchymal stem cell administration with established nursing protocols. Hospital outpatient departments in the United States and Germany standardize cryopreserved product thawing and infusion workflows. Reimbursement infrastructure is most mature.
- Direct Injection:Targeted delivery to myocardial or articular tissue requires interventional specialists and imaging guidance. Japanese cardiac centers pioneer catheter-based delivery as PMDA rewards domestic manufacturing scale-up. Technical complexity limits site expansion.
- Subcutaneous:Dermal and localized administration for select immunomodulatory applications.
- Intra-Spinal:Intrathecal delivery for neurological indications requiring neurosurgical collaboration.
Intravenous leads by procedure volume. Direct Injection shows the steepest expansion trajectory as interventional cardiology adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while manufacturing scale advantages emerge in Japan. German hospital systems anchor European procurement volumes through centralized tendering. Chinese biotech clusters are accelerating iPSC platform development despite reimbursement lag.
United States
Academic medical centers in Boston and Houston drive demand for hematopoietic stem cell protocols. FDA regenerative medicine advanced therapy designation compresses commercial timelines for off-the-shelf candidates. The National Marrow Donor Program maintains donor inventory networks that supply transplant centers across the country.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia standardize mesenchymal stem cell infusion workflows. EMA priority medicines scheme accelerates centralized assessment for oncology applications. Heidelberg and Berlin anchor clinical research clusters where graft-versus-host disease protocols mature.
Japan
Domestic manufacturing investment unlocks PMDA conditional early approval advantages. METI funding programs support scalable bioreactor infrastructure for iPSC-derived products. Osaka and Tokyo house production facilities that supply regional transplant centers with cryopreserved inventory.
United Kingdom
NHS England's specialized commissioning framework bundles allogeneic infusion reimbursement. MHRA operates a rolling review pathway for regenerative medicine candidates. London and Cambridge concentrate cell therapy development alongside contract manufacturing organizations.
China
NMPA's breakthrough therapy designation attracts domestic biotech investment in CAR-T platforms. Yangtze River Delta biotech parks host iPSC differentiation facilities. Shanghai and Suzhou clusters focus on scalable manufacturing despite limited commercial reimbursement.
Allogeneic Stem Cell Therapy Market Vendor Landscape
Concentration sits with platform-scale manufacturers commanding commercial bioreactor infrastructure. The vendor base spans three tiers: integrated pharmaceutical conglomerates with cell therapy divisions, mid-cap specialists focused on single platform technologies, and emerging biotechs advancing preclinical pipelines. Boutique developers face margin compression as hospital procurement departments consolidate sourcing through multi-year framework agreements. Capacity expansion and gene editing technology licensing represent the dominant competitive moves reshaping positioning.
Within the platform-scale tier, Fate Therapeutics and Mesoblast Ltd exemplify divergent manufacturing strategies. Fate Therapeutics occupies a position centered on induced pluripotent stem cell engineering for natural killer cell candidates. Mesoblast Ltd anchors commercial-scale mesenchymal lineage cell production with established hospital supply relationships. CRISPR Therapeutics sits within the gene-edited allogeneic segment, representing convergence between programmable nuclease technology and off-the-shelf cell therapy development.
| Leading Market Players |
|---|
| Fate Therapeutics |
| Allogene Therapeutics |
| Artiva Biotherapeutics |
| Atara Biotherapeutics |
| Adicet Bio |
| CRISPR Therapeutics |
| Mesoblast Ltd |
| Vertex Pharmaceuticals Incorporated |
| Gamida Cell |
| Others |
Supply Flow & Price Mechanics
Dimethyl sulfoxide substitution for novel cryoprotectant formulations is redrawing manufacturing geography toward Japanese and German chemical clusters while compressing per-dose preservation economics. This input transition simultaneously elevates quality premiums for GMP-grade supply and erodes margins for developers locked into legacy DMSO contracts.
Pricing Analysis
The customization-premium spread between patient-matched HLA configurations and universal donor banks reaches three-to-one multiples. Three-tier pricing structure across premium, standard, and economy levels tracks manufacturing scale and immunological engineering intensity. Cost compression in standard-tier mesenchymal products is intensifying because Chinese bioreactor capacity is flooding mid-market supply. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement, while ambulatory clinics face acute margin pressure.
Supply Chain Analysis
Viral vector manufacturing capacity in the United States, United Kingdom, and South Korea constitutes the dominant chokepoint constraining IND advancement timelines. GMP-grade plasmid DNA, lentiviral packaging lines, and qualified cell substrates draw from concentrated contract manufacturer networks. Single-source vulnerability pervades vector supply, with 24-36 month booking windows locking out smaller developers. Distribution runs through cryogenic logistics specialists maintaining liquid nitrogen cold chains from production facilities to hospital apheresis units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA regenerative medicine advanced therapy designation and EMA priority medicines scheme creates formidable defensive moats for established platform developers. Switching costs between allogeneic and autologous protocols lock hospital systems into incumbent supply relationships.
For Market Incumbents: Secure exclusive multi-year framework agreements with United States academic medical centers before Japanese manufacturers exploit PMDA conditional early approval advantages. Expand captive bioreactor capacity in Boston and Houston clusters to preempt vector manufacturing bottlenecks from constraining pipeline advancement. Gene-edited allogeneic programs from emerging biotechs threaten cost-of-goods positioning.
For New Entrants and Emerging Players: Lead with autoimmune indication expansion in German outpatient clinics where EMA centralized assessment accelerates market access and mesenchymal stem cell protocols face limited incumbent saturation. Crohn's disease and lupus represent the most penetrable therapeutic areas. Partner with contract development and manufacturing organizations possessing established Japanese production footprints to unlock PMDA pathway benefits.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors integrated manufacturers with commercial-scale bioreactor infrastructure and gene editing technology licensing. Five-to-ten year viability hinges on successful navigation from clinical-stage to commercial reimbursement. Acquisition targets should display iPSC differentiation capabilities or CRISPR-mediated HLA knockout programs. Watch FDA regenerative medicine advanced therapy designation grants as inflection indicators for valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA regenerative medicine advanced therapy designation compresses Phase III-to-approval timelines for allogeneic candidates. |
| Manufacturing Scale-Up | Japanese METI funding programs support scalable bioreactor infrastructure for iPSC-derived natural killer cell platforms. |
| Regulatory Approval Pathway | EMA priority medicines scheme accelerates centralized assessment timelines for pediatric leukemia applications. |
| Licensing Agreement | Gene editing technology licensing from CRISPR platform holders enables universal donor cell bank development. |
| Hospital System Partnership | Multi-year framework agreements with United States academic medical centers guarantee cryopreserved dose availability. |
Methodological Framework
Operator-level perspectives from cell therapy process development scientists, regulatory affairs specialists, hospital procurement managers, and payer access directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up manufacturing cost modeling and top-down epidemiological demand estimation provided triangulation across the analysis window.
Sensitivity analysis tested forecast robustness against vector manufacturing capacity constraints, reimbursement policy shifts, and competitive entry timing. Segmentation dimensions spanned stem cell lineage, therapeutic application, end-user institution type, and regional regulatory cluster. CAGRs derived from patient population projections, pricing trajectory assumptions, and adoption curve modeling. Cryopreservation input cost inflation and workforce scarcity served as key forecast inputs.
Underlying assumptions cover sustained FDA and EMA expedited pathway availability, with deviation risk concentrated in graft-versus-host disease protocol failures and autologous CAR-T reimbursement entrenchment. Practitioners should keep alternative scenarios live as Japanese PMDA conditional approval criteria and Chinese NMPA breakthrough therapy designations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Thalassemia Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Alpha Thalassemia Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Anemia Drugs Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Rare Hematology Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Neutropenia Treatment Market