
 Chronic Immune Thrombocytopenia Treatment Market | 2026-2036
Chronic Immune Thrombocytopenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Immune Thrombocytopenia Treatment Market Outlook
Buyer concentration among integrated hospital networks and specialty pharmacy benefit managers is repositioning how chronic ITP therapies reach patients. AbbVie leverages its immunology infrastructure to sustain access across academic medical centers. Amgen competes through manufacturing scale in biologic supply chains. Pfizer anchors its position via channel control through specialty distribution partnerships.
Chronic immune thrombocytopenia treatment encompasses pharmacologic interventions that modulate platelet destruction and production pathways, including thrombopoietin receptor agonists that stimulate megakaryopoiesis in the bone marrow and immunosuppressive agents that attenuate autoantibody-mediated platelet clearance. These therapies serve to reduce bleeding risk and maintain hemostatic thresholds in patients with persistent platelet counts below safe levels. Thrombopoietin receptor agonists occupy the highest-margin segment due to chronic dosing requirements and limited biosimilar penetration. Oral administration routes are gaining share against intravenous alternatives as patients and payers prioritize convenience and site-of-care cost reduction.
The FDA's accelerated approval and orphan drug frameworks shape development economics for novel ITP mechanisms, while the EMA's PRIME designation creates parallel European access pathways. The EU MDR imposes escalating clinical evidence requirements on legacy devices used in platelet monitoring, indirectly affecting treatment algorithms. Stakeholders must monitor evolving CMS reimbursement policies for physician-administered versus self-administered biologics, as site-of-care differentials increasingly determine prescribing patterns and manufacturer channel investments.
Market Dynamics
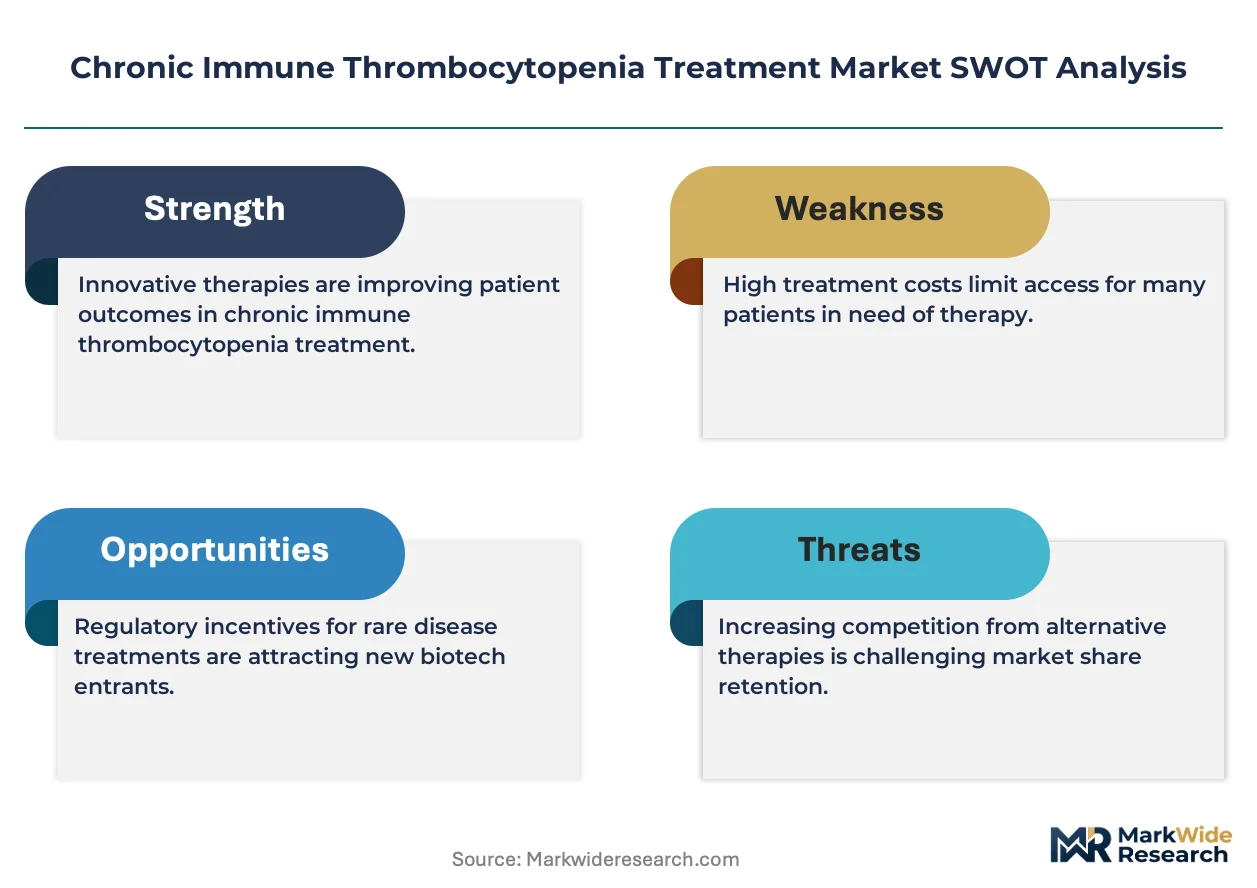
Hospital network consolidation and specialty pharmacy benefit manager vertical integration are compressing channel access for chronic ITP therapies, forcing manufacturers to restructure distribution partnerships around site-of-care economics rather than traditional physician detailing.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's orphan drug and accelerated approval frameworks compress development timelines for novel thrombopoietin receptor agonists, reducing capital requirements for mechanism-first biologics entering hematology indications.
- Oral Route Preference:Patient and payer demand for oral administration over intravenous alternatives is expanding addressable populations and reducing site-of-care costs across academic medical centers and community hematology practices.
- Chronic Dosing Economics:Persistent treatment requirements for platelet maintenance create recurring revenue structures that attract development investment despite limited prevalence of diagnosed ITP cases.
Market Restraints
- Biologic Manufacturing Concentration:Thrombopoietin receptor agonist production relies on concentrated mammalian cell culture capacity, creating supply vulnerability at contract manufacturing organizations in the United States and Western Europe.
- Prior Authorization Friction:Specialty pharmacy benefit managers impose step-therapy protocols and platelet count documentation requirements that delay therapy initiation and increase administrative burden on hematology practices.
- Biosimilar Delay:Complex glycosylation patterns and immunogenicity concerns have stalled biosimilar entry for reference thrombopoietin receptor agonists, preserving originator pricing but limiting payer leverage.
Strategic Opportunities
- Pediatric Label Expansion:The FDA's pediatric study requirements under PREA create exclusivity incentives for developers completing juvenile ITP trials, opening a chronically underserved age segment.
- Home Administration Models:Self-injection training programs and remote monitoring platforms enable therapy delivery outside infusion centers, capturing site-of-care cost savings for integrated delivery networks.
- Combination Mechanism Development:Pairing thrombopoietin receptor agonists with FcRn inhibitors or B-cell depleting agents offers potential for steroid-sparing regimens in refractory patient populations.
Industry Challenges
- Hematology Specialist Workforce Constraints:Fellowship program output has not kept pace with chronic ITP patient volume, stretching diagnostic and monitoring capacity at academic referral centers.
- Real-World Evidence Collection:Long-term platelet response durability and thrombotic risk data requirements under the FDA's accelerated approval confirmatory study obligations demand extended post-marketing infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Immune Thrombocytopenia Treatment Market |
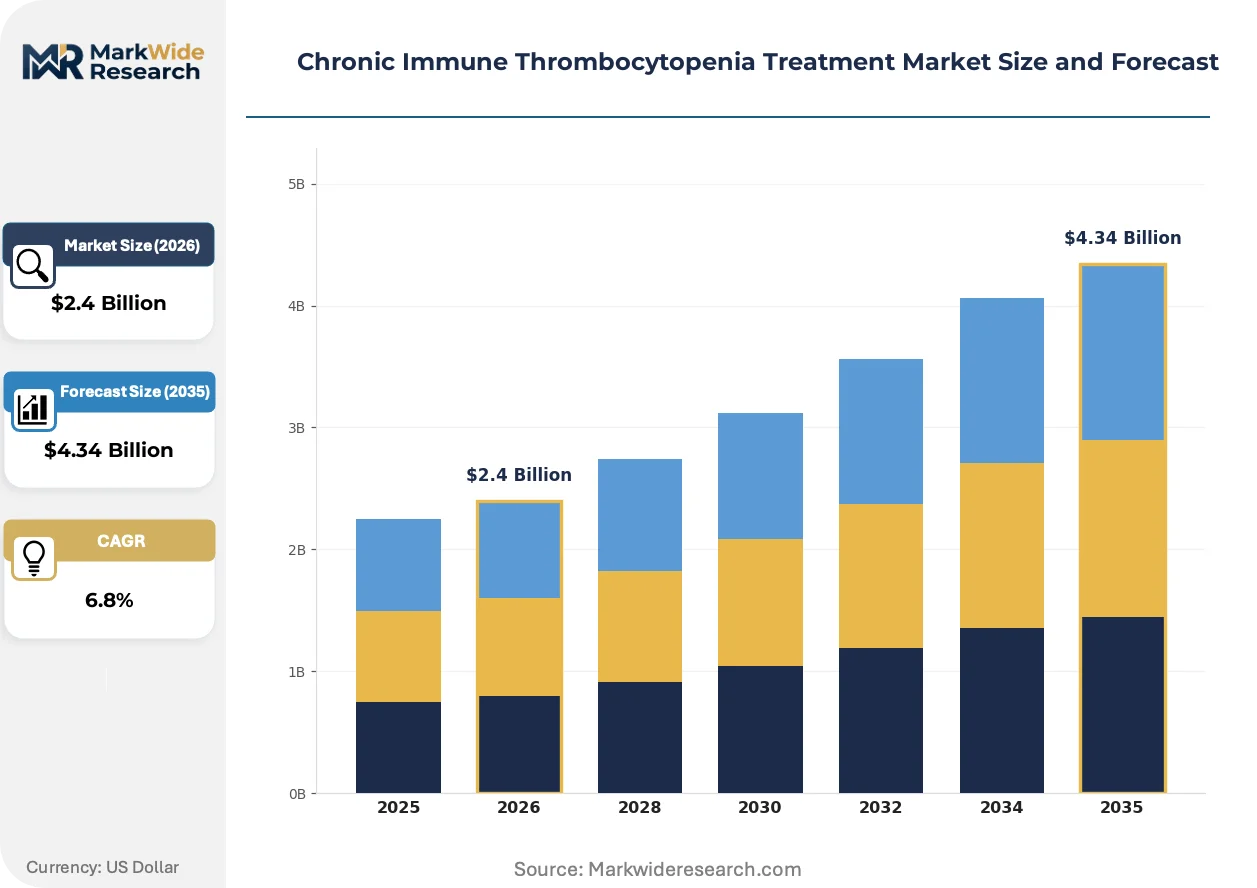
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunoglobulins, Thrombopoietin Receptor Agonists, Others End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular Delivery Mode: Self-Administered, Physician-Administered, Infusion Centers, Others |
| Companies Covered | AbbVie Inc, Amgen Inc, Pfizer Inc, Sanofi, Novartis AG, Johnson & Johnson Services Inc, Merck & Co Inc, Bristol Myers Squibb Inc, Rigel Pharmaceuticals Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Immune Thrombocytopenia Treatment Market Strategic Shifts
Digital biomarker integration and patient-reported outcome capture are reshaping how treatment response gets measured in chronic ITP, moving beyond platelet counts toward bleeding event prevention as the primary efficacy endpoint.
Subcutaneous auto-injector devices for thrombopoietin receptor agonists are integrating into home-care protocols, enabling weekly or biweekly self-administration that reduces infusion center dependency. Community hematology practices in the United States are adopting these devices fastest, driven by prior authorization incentives that favor lower site-of-care cost structures. The technology is integrating patient adherence monitoring with pharmacy refill data, creating closed-loop systems that flag discontinuation risk before platelet destabilization.
The EU MDR's escalating clinical evidence requirements for legacy platelet monitoring devices are forcing hematology laboratories to validate new automated counter technologies or absorb recertification costs. Manufacturers serving European hospital networks face compressed timelines for technical documentation updates. Academic medical centers in Germany and France are responding by consolidating hematology diagnostics into centralized reference laboratories that can amortize compliance investments across larger test volumes.
Specialty pharmacy distribution is consolidating around three national platforms that control prior authorization adjudication for thrombopoietin receptor agonists. Independent community hematology practices are losing direct purchasing leverage as these platforms mandate exclusive distribution agreements. The concentration is most visible in the United States, where integrated delivery networks in Texas and Florida have surrendered formulary autonomy to pharmacy benefit manager administered networks in exchange for administrative cost reduction.
Chronic Immune Thrombocytopenia Treatment Market Segmentation
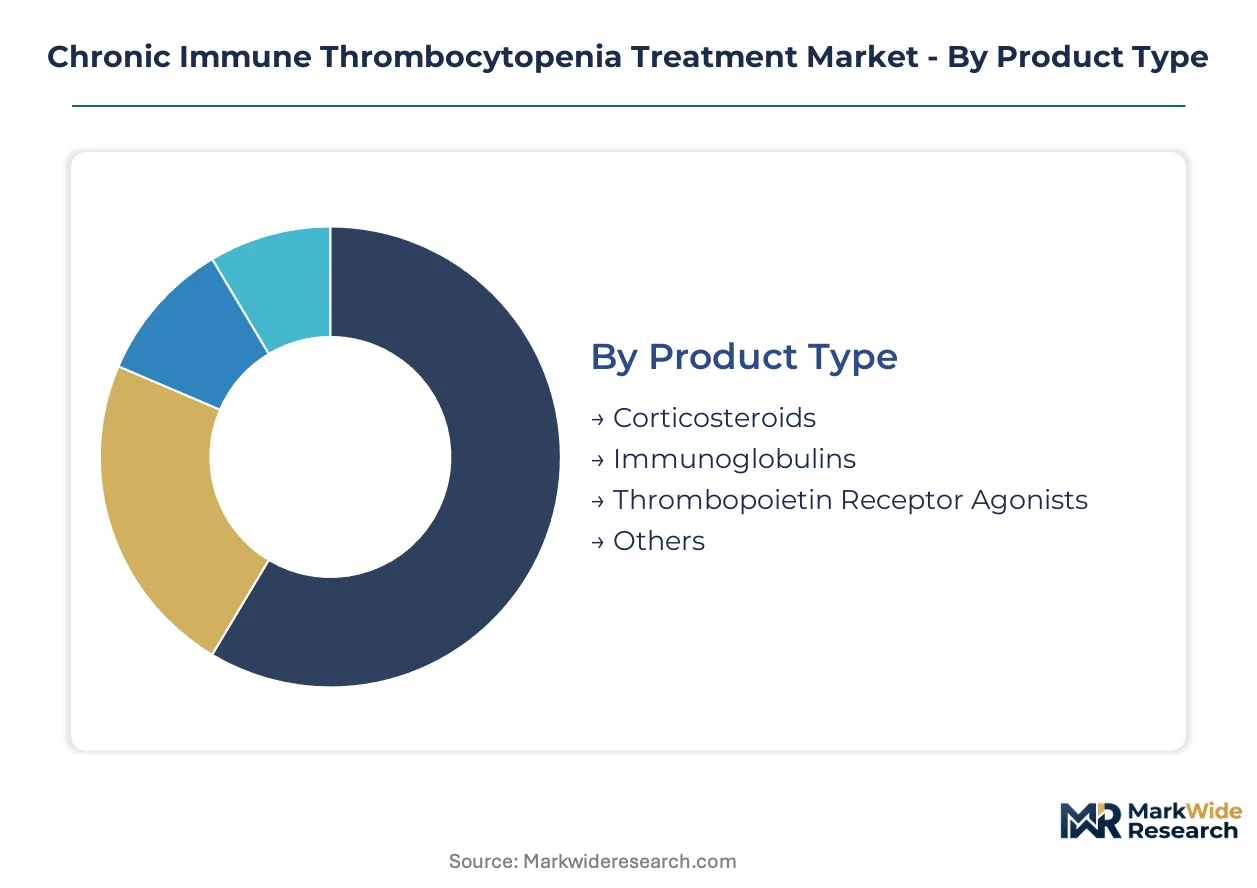
Segmentation in chronic ITP treatment reveals how capital deployment, regulatory pathways, and site-of-care economics fragment commercial opportunity. Manufacturers must align portfolio investments with the specific infrastructure and reimbursement requirements of each segment cluster.
Product Type:
Thrombopoietin receptor agonists demand the heaviest upfront capital commitment due to mammalian cell culture manufacturing and glycosylation control requirements.
- Thrombopoietin Receptor Agonists:Peptide-based biologics that stimulate megakaryocyte maturation through c-Mpl receptor signaling. Demand concentrates in United States academic medical centers where prior authorization infrastructure supports chronic reimbursement. Manufacturing scale constraints at contract development organizations limit supply elasticity.
- Immunoglobulins:Polyclonal antibody preparations derived from pooled plasma that provide rapid platelet count recovery through Fc receptor blockade. United States infusion centers absorb the highest volume due to emergency ITP management protocols. Plasma fractionation capacity and donor pool access determine regional availability.
- Corticosteroids:First-line immunosuppressants that suppress autoantibody production through lymphocyte modulation. Generic pricing and oral bioavailability sustain broad accessibility across community hematology practices.
- Others:Includes splenectomy alternatives and investigational FcRn inhibitors. Clinical trial recruitment at European referral centers drives development-stage demand.
Thrombopoietin receptor agonists absorb the bulk of installed capacity; FcRn inhibitor development is expanding most quickly.
End User:
Customer concentration patterns reveal how integrated delivery networks and pharmacy benefit managers are redrawing procurement boundaries.
- Hospitals:Academic medical centers and tertiary referral hospitals manage refractory cases requiring combination therapy and surgical backup. United States hospital network consolidation is compressing formulary autonomy into centralized pharmacy committees.
- Specialty Pharmacies:National distribution platforms control prior authorization adjudication and patient adherence monitoring. Three dominant United States platforms now mandate exclusive distribution agreements for thrombopoietin receptor agonists.
- Clinics:Community hematology practices in Florida and Texas are adopting subcutaneous auto-injector protocols to retain patients outside hospital networks.
- Homecare Settings:Self-injection training programs and remote monitoring platforms enable platelet management outside traditional sites of care. Reimbursement differentials between physician-administered and self-administered biologics are accelerating migration.
Hospitals retain the highest patient acuity mix; homecare settings are climbing the fastest as site-of-care economics shift.
Administration Route:
Route selection directly determines manufacturing investment requirements, cold chain infrastructure, and patient training protocols.
- Oral:Small-molecule formulations eliminate infusion center dependency and enable patient-directed titration. Payer preference for reduced site-of-care costs is expanding oral share against intravenous alternatives.
- Subcutaneous:Weekly or biweekly auto-injector delivery reduces healthcare utilization while maintaining therapeutic exposure. German and French academic centers are validating home administration protocols fastest.
- Intravenous:Required for immunoglobulin loading doses and some thrombopoietin receptor agonist formulations. United States infusion center capacity constraints are creating access bottlenecks during acute bleeding episodes.
- Intramuscular:Limited to specific corticosteroid preparations and emergency interventions. Bioavailability variability restricts use in platelet-critical situations.
Intravenous routes retain the largest installed base; oral administration is gaining share fastest on convenience and cost metrics.
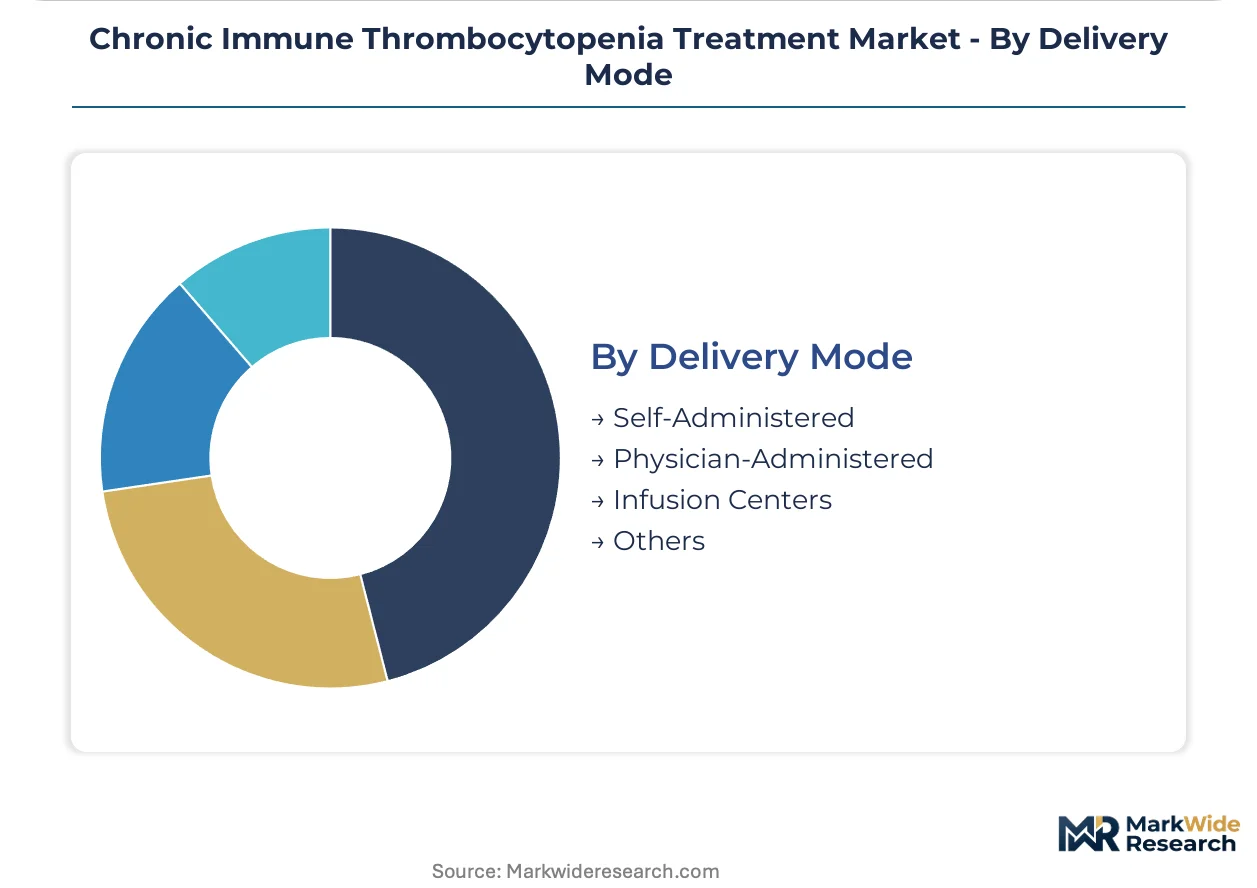
Delivery Mode:
Mode stratification reflects the tension between clinical oversight requirements and cost containment pressures across reimbursement systems.
- Physician-Administered:Hospital-based or office-based infusion with direct clinician supervision. United States Medicare reimbursement differentials favor this mode for high-cost biologics.
- Self-Administered:Patient or caregiver injection after training certification. Pharmacy benefit manager incentives in Texas and Florida are accelerating adoption.
- Infusion Centers:Dedicated ambulatory facilities for complex biologic delivery. Capacity constraints and nursing shortages are limiting expansion.
- Others:Includes emergency department administration and transitional care settings. Unpredictable utilization complicates inventory planning.
Physician-administered delivery absorbs the bulk of current biologic volume; self-administered modes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks concentrate the highest patient volume for chronic ITP therapies, with specialty pharmacy benefit managers controlling access pathways for thrombopoietin receptor agonists.
United States
Academic medical centers in Texas and Florida drive demand for subcutaneous auto-injector protocols that reduce infusion center dependency. FDA accelerated approval pathways for orphan hematology indications compress development timelines for novel mechanisms. The Mayo Clinic in Rochester anchors a referral network managing refractory cases requiring combination therapy.
Germany
University hospitals in Berlin and Heidelberg validate home administration models for thrombopoietin receptor agonists through structured self-injection training programs. EMA PRIME designation creates parallel European access pathways for developers targeting pediatric label expansion. The Charité network consolidates hematology diagnostics into centralized reference laboratories to amortize EU MDR compliance costs.
France
Public hospital networks in Paris and Lyon absorb the bulk of chronic ITP patient management through the AP-HP system. ANSM oversight of platelet monitoring device recertification under EU MDR imposes escalating clinical evidence requirements on legacy equipment. The Gustave Roussy institute specializes in refractory pediatric cases requiring surgical backup.
United Kingdom
NHS England's specialized commissioning framework centralizes access to high-cost biologics through designated treatment centers in London and Manchester. NICE technology appraisals determine reimbursement eligibility for thrombopoietin receptor agonists based on platelet response durability metrics. The Royal Free Hospital hosts a national referral service for splenectomy alternatives.
Japan
Designated cancer hospitals in Tokyo and Osaka manage chronic ITP alongside oncology portfolios through shared hematology infrastructure. PMDA's Sakigake designation accelerates review timelines for novel FcRn inhibitors entering development. The National Center for Global Health and Medicine coordinates real-world evidence collection for post-marketing confirmatory studies.
Chronic Immune Thrombocytopenia Treatment Market Competitive Environment
United States-based biopharmaceutical conglomerates anchor the top tier through immunology infrastructure and specialty pharmacy channel control; European specialists hold position via orphan drug incentives and academic center relationships. The market structure consolidates around three archetypes: diversified pharmaceutical conglomerates with hematology franchises, mid-cap biotechs with mechanism-first platforms, and plasma fractionation specialists supplying immunoglobulin volume. Competitive moves center on pediatric label expansion to capture PREA exclusivity and home administration training program deployment to capture site-of-care savings.
Within the diversified pharmaceutical tier, AbbVie Inc and Pfizer Inc exemplify channel-centric positioning through specialty distribution partnerships and integrated delivery network contracting. Amgen Inc occupies a distinct archetype as a manufacturing-scale biologic producer with concentrated mammalian cell culture capacity. These three entities represent the dominant competitive anchors shaping procurement dynamics across United States hospital networks and European academic centers.
| Leading Market Players |
|---|
| AbbVie Inc |
| Amgen Inc |
| Pfizer Inc |
| Sanofi |
| Novartis AG |
| Johnson & Johnson Services Inc |
| Merck & Co Inc |
| Bristol Myers Squibb Inc |
| Rigel Pharmaceuticals Inc |
| Others |
Value Chain & Pricing Dynamics
A stark bifurcation between originator thrombopoietin receptor agonists and generic corticosteroid alternatives governs both margin structures and procurement pathways across United States hospital networks. This divergence concentrates pricing power with mammalian cell culture manufacturers while compressing reimbursement floors for oral immunosuppressants distributed through community hematology channels.
Pricing Analysis
Volume concentrates in generic corticosteroids while margins accrue to biologic maintenance therapies. Pricing stratifies across originator biologics, authorized generics, and commodity immunosuppressants based on glycosylation complexity and FDA exclusivity status. Cost compression in the corticosteroid tier intensifies because of pharmacy benefit manager generic substitution mandates. Community hematology practices exhibit highest price sensitivity; academic medical centers prioritize platelet response durability over acquisition cost.
Supply Chain Analysis
ISO 13485 certification and FDA biologics license requirements gate entry for contract manufacturing organizations supplying active pharmaceutical ingredients. Production concentrates in the United States, Ireland, and Switzerland due to mammalian cell culture infrastructure density. Raw material dependencies include fetal bovine serum, recombinant DNA vectors, and specialized chromatography resins. Single-source vulnerability at plasma fractionation facilities creates supply interruption risk for immunoglobulin products. Distribution runs through specialty pharmacy benefit manager networks that control prior authorization adjudication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital network consolidation and pharmacy benefit manager vertical integration are forcing sub-scale manufacturers toward exit or acquisition, leaving only capitalized players with integrated delivery network contracts.
For Market Incumbents: Cement formulary position through exclusive distribution agreements with the three dominant United States specialty pharmacy platforms. Expand internal mammalian cell culture capacity to reduce contract manufacturing organization dependency. Prioritize pediatric label expansion under FDA PREA requirements to capture exclusivity extensions against FcRn inhibitor entrants.
For New Entrants and Emerging Players: Launch via home administration training programs targeting Texas and Florida community hematology practices outside consolidated hospital networks. Penetrate the refractory patient segment through combination mechanism trials pairing thrombopoietin receptor agonists with B-cell depleting agents. Exploit site-of-care reimbursement differentials favoring self-administered biologics over infusion center delivery.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap biotechs possessing mechanism-first platforms and accelerated approval designations given FDA orphan drug incentive structures. Five-to-ten year viability hinges on confirmatory study completion and real-world evidence infrastructure deployment. Watch for thrombotic risk signal emergence in post-marketing surveillance as the critical inflection indicator for thrombopoietin receptor agonist portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Label Expansion | FDA PREA compliance creates exclusivity incentives for juvenile ITP trial completion. |
| Home Administration Training | Self-injection programs capture site-of-care savings for integrated delivery networks in Texas. |
| Manufacturing Scale-Up | Captive mammalian cell culture capacity reduces contract manufacturing organization supply vulnerability. |
| Combination Mechanism Development | Steroid-sparing regimens pairing TPO-RAs with FcRn inhibitors address refractory populations. |
| Specialty Pharmacy Partnership | Exclusive distribution agreements with national platforms secure prior authorization adjudication control. |
Study Parameters
FDA filings, EMA submission documents, and ClinicalTrials.gov records formed the secondary backbone for mechanism and regulatory pathway mapping. Primary interviews with drug development executives, formulary directors at academic medical centers, payer access specialists, and hospital procurement managers validated commercial assumptions. Bottom-up patient volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Bottom-up modeling of patient prevalence, treatment rates, and therapy duration combined with top-down manufacturer revenue reconciliation. Segmentation dimensions included product type, administration route, delivery mode, and regional regulatory cluster. CAGRs were derived from patient volume trajectories and pricing elasticity assumptions. Key inputs incorporated prior authorization approval rates, site-of-care migration patterns, and biosimilar entry probability assessments.
Accelerated approval withdrawal, thrombotic safety signal emergence, and CMS reimbursement reclassification are the dominant revision risks to projection assumptions. A model refresh is warranted upon material change in FDA confirmatory study requirements or specialty pharmacy benefit manager formulary exclusion policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Sickle Cell Treatment Market
Hematology
Hemocytometer Market
Hematology
Sickle Cell Disease Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Multiple Myeloma Market
Hematology
Global Hematology Diagnostics Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Patient Blood Management Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Polycythemia Vera Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market