
 Platelet Function Test Market | 2026-2036
Platelet Function Test Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet Function Test Market Outlook
CE marking under the EU In Vitro Diagnostic Medical Devices Regulation is unwinding the competitive landscape for smaller reagent suppliers. F. Hoffmann-La Roche Ltd leverages its diagnostics platform breadth to sustain laboratory analyzer placements across European hospital networks. Siemens Healthineers anchors its position through integrated informatics that connect point-of-care devices to enterprise laboratory systems. Sysmex Corporation specializes in hematology automation and competes on workflow density in high-volume Asian diagnostic laboratories.
Platelet function tests measure platelet aggregation, secretion, and adhesion under shear or agonist-stimulated conditions using optical, electrical, or flow-based detection principles, primarily to guide antiplatelet therapy and diagnose bleeding disorders. Laboratory analyzers command the highest absolute revenue within product types due to capital placement cycles and recurring reagent contracts, while point-of-care devices capture the fastest expansion as cardiac surgery and emergency medicine applications demand intraoperative turnaround under ten minutes. Flow cytometry retains technology leadership in research and complex phenotyping, whereas electromechanical systems dominate routine clinical throughput in hospital coagulation laboratories.
FDA guidance on P2Y12 inhibitor monitoring shapes US product development pathways, while the EU IVDR and MDR impose conformity assessment burdens that filter market access for non-European manufacturers. Japan's PMDA maintains distinct clinical evidence requirements for hemostasis diagnostics that delay approval timelines relative to other device categories. Stakeholders must monitor evolving antithrombotic guidelines from cardiology societies and corresponding payer coverage determinations that will determine whether platelet function testing shifts from procedural adjunct to standard-of-care mandate.
Market Dynamics
The FDA's updated guidance on antiplatelet therapy management is compressing test turnaround requirements from hours to minutes, forcing device manufacturers to reengineer detection architectures while cardiac surgery units demand intraoperative monitoring capabilities that laboratory analyzers cannot deliver.
Growth Catalysts
- EU IVDR Conformity Pathways:The In Vitro Diagnostic Medical Devices Regulation is filtering market access for non-European reagent suppliers, creating placement opportunities for compliant manufacturers in German and French hospital networks.
- Cardiac Surgery Volumes:Tertiary hospitals in the United States and Japan are expanding catheterization lab throughput, generating procedural demand for point-of-care platelet function verification before emergency intervention.
- Optical Detection Miniaturization:Advances in LED-based aggregometry are enabling handheld device form factors that match laboratory precision without centrifugation steps.
Market Restraints
- Reagent Supply Concentration:Lyophilized agonist production clusters in Swiss and German chemical suppliers, exposing downstream device manufacturers to input cost volatility and batch consistency risks.
- PMDA Evidence Requirements:Japan's pharmaceutical and medical devices agency maintains distinct clinical validation standards for hemostasis diagnostics that extend approval timelines relative to other device categories.
- Flow Cytometry Throughput Limits:Complex phenotyping protocols require specialized operator training and capital-intensive infrastructure that constrains adoption outside research institutions.
Strategic Opportunities
- Emergency Medicine Penetration:Underdeveloped platelet function testing protocols in United States trauma centers present white-space expansion for ten-minute turnaround devices in bleeding disorder triage.
- Integrated Informatics Convergence:Bidirectional connectivity between point-of-care devices and laboratory information systems is enabling automated result routing that reduces manual transcription errors.
- IRA Diagnostic Reimbursement:The Inflation Reduction Act's coverage expansion pathways for preventive cardiovascular diagnostics may elevate platelet function testing from procedural adjunct to standard-of-care mandate.
Industry Challenges
- CE Marking Compliance Burden:Smaller reagent suppliers face technical documentation requirements and notified body backlogs that strain quality management system resources.
- Legacy Analyzer Integration:Hospital coagulation laboratories operate mixed-vendor instrument fleets that complicate middleware deployment and result standardization across platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet Function Test Market |
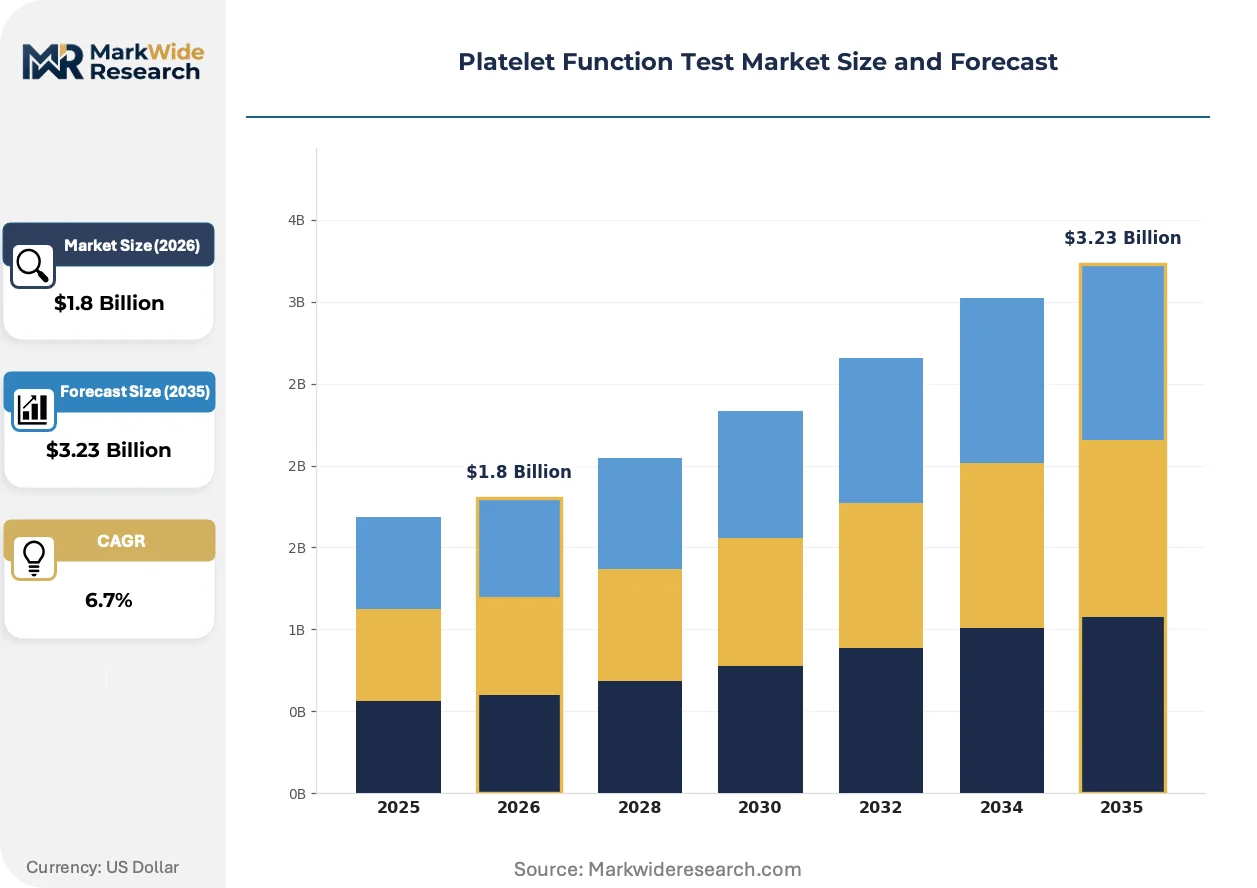
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Care Devices, Laboratory Analyzers, Reagents, Software Solutions Application: Cardiac Surgery, Hematological Disorders, Transplantation, Emergency Medicine End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Technology: Flow Cytometry, Electromechanical Systems, Optical Density Measurement, Ultrasound-Based Techniques |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers, Haemonetics Corporation, Sysmex Corporation, Helena Laboratories, Terumo Corporation, Fresenius SE & Co. KGaA, AggreDyne, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet Function Test Market Strategic Shifts
Electromechanical detection architectures are displacing optical systems in high-throughput clinical environments, while regulatory fragmentation across FDA, EMA, and PMDA jurisdictions forces parallel development tracks that compress product launch windows.
Microfluidic shear-based assays are displacing traditional aggregometry in research applications by enabling real-time platelet adhesion visualization under physiologic flow conditions. Academic medical centers in Germany and the Netherlands are adopting these platforms for antiplatelet drug development studies. The technology is displacing legacy optical methods by reducing sample volumes from milliliters to microliters while maintaining correlation with light transmission aggregometry.
The EU IVDR's classification of platelet function tests as Class C devices is imposing clinical evidence requirements that filter out reagent suppliers lacking quality management system maturity. Manufacturers must now submit performance evaluation reports demonstrating analytical and clinical validity across intended use populations. European hospital networks are responding by consolidating procurement around suppliers with established notified body relationships and IVDR technical documentation.
Cardiac surgery departments are unbundling device procurement from reagent supply contracts, creating direct purchasing relationships with point-of-care manufacturers that bypass laboratory distribution intermediaries. This disintermediation is most visible in United States health systems where value-based care contracts incentivize procedural cost transparency. Device vendors are responding with transparent per-test pricing models that separate capital placement from consumable recurring revenue.
Platelet Function Test Market Segmentation
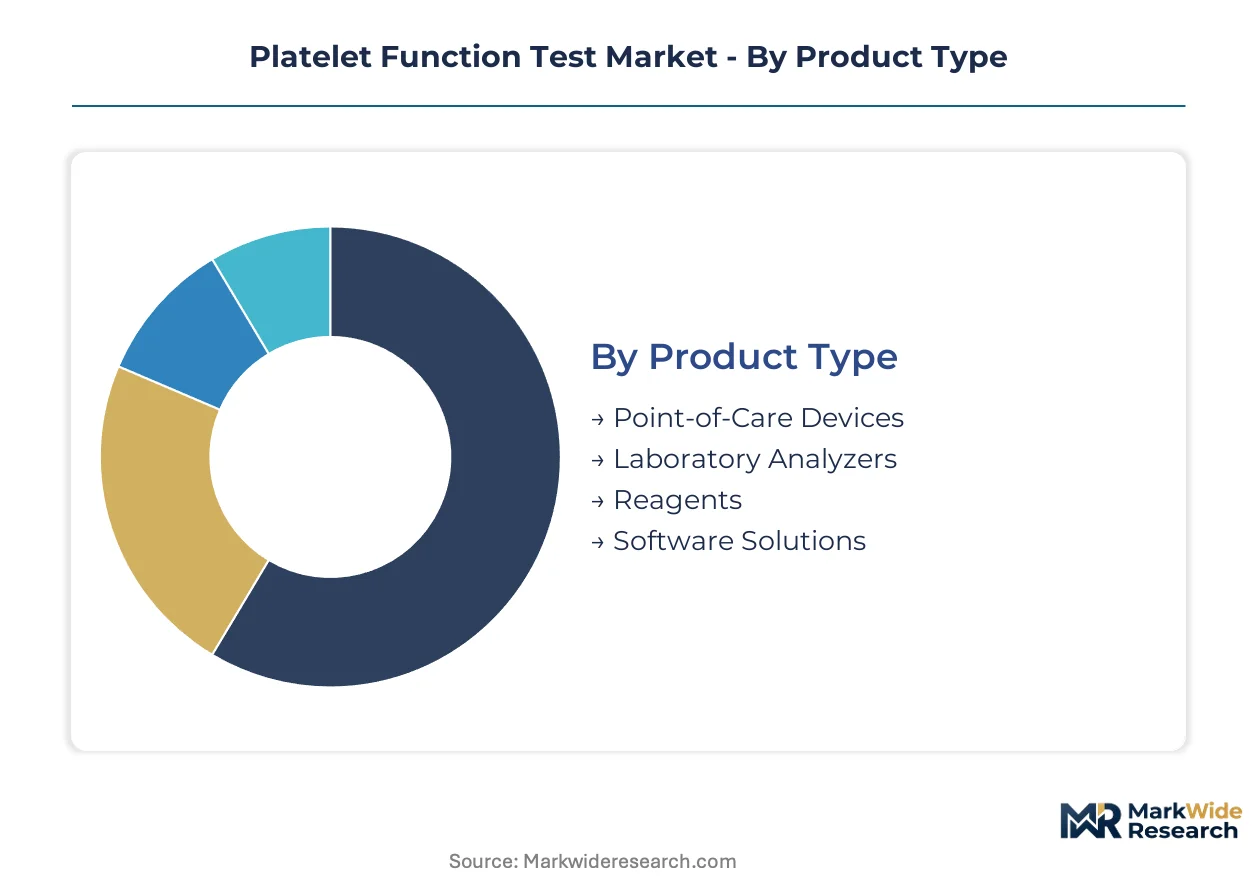
Platelet function testing spans capital-intensive laboratory infrastructure and disposable-intensive point-of-care deployment, creating divergent margin profiles and geographic demand patterns across product categories. Segmentation reveals how cardiac surgery volumes in tertiary hospitals pull technology choices toward intraoperative turnaround capabilities while hematology automation drives laboratory analyzer placements.
Product Type:
Domestic production clusters in Germany, Japan, and the United States supply laboratory analyzers and reagents, while point-of-care device manufacturing concentrates in Taiwanese and South Korean electronics corridors for optical miniaturization components.
- Point-of-Care Devices:Handheld and cartridge-based systems deliver platelet aggregation results within ten minutes without centrifugation. Demand concentrates in United States cardiac catheterization labs and Japanese emergency departments where procedural throughput mandates intraoperative decision support.
- Laboratory Analyzers:Floor-standing electromechanical and optical systems process high sample volumes with automated sample handling. German and French hospital networks anchor placements through multi-year reagent contracts tied to hematology automation lines.
- Reagents:Lyophilized agonists, buffers, and quality control materials enable test execution across device platforms.
- Software Solutions:Middleware and laboratory information system modules manage result routing, instrument interfacing, and regulatory compliance documentation.
Laboratory analyzers hold the largest share; momentum sits with point-of-care devices.
Application:
Cardiac surgery generates the highest per-procedure test density, while emergency medicine applications remain underdeveloped in trauma centers lacking established bleeding disorder triage protocols.
- Cardiac Surgery:Preoperative and intraoperative platelet function verification guides transfusion decisions and antiplatelet therapy management during coronary artery bypass and valve replacement procedures. United States tertiary hospitals and Japanese cardiovascular centers drive procedural volumes.
- Hematological Disorders:Diagnosis and monitoring of inherited platelet function defects, storage pool disorders, and acquired platelet dysfunction. Diagnostic laboratories in Germany and the Netherlands specialize in complex phenotyping referrals.
- Transplantation:Monitoring of platelet recovery and function following bone marrow and solid organ transplantation.
- Emergency Medicine:Rapid assessment of platelet function in trauma-induced coagulopathy and acute bleeding presentations.
Cardiac surgery commands the highest absolute revenue; emergency medicine is climbing the fastest.
End User:
Hospital procurement departments increasingly unbundle device capital from reagent supply, while diagnostic laboratories consolidate testing through multi-site automation contracts.
- Hospitals:Integrated health systems operate mixed-vendor instrument fleets across laboratory and point-of-care settings, complicating middleware standardization. United States value-based care contracts and Japanese diagnostic fee schedules shape capital allocation priorities.
- Diagnostic Laboratories:High-throughput reference laboratories and hospital-affiliated coagulation labs process routine platelet function panels. German and French networks emphasize workflow density and automated sample handling.
- Research Institutes:Academic medical centers conduct antiplatelet drug development and platelet biology studies.
- Outpatient Clinics:Cardiology and hematology clinics perform preoperative screening and therapy monitoring.
Hospitals hold the largest share; diagnostic laboratories are gaining share fastest.
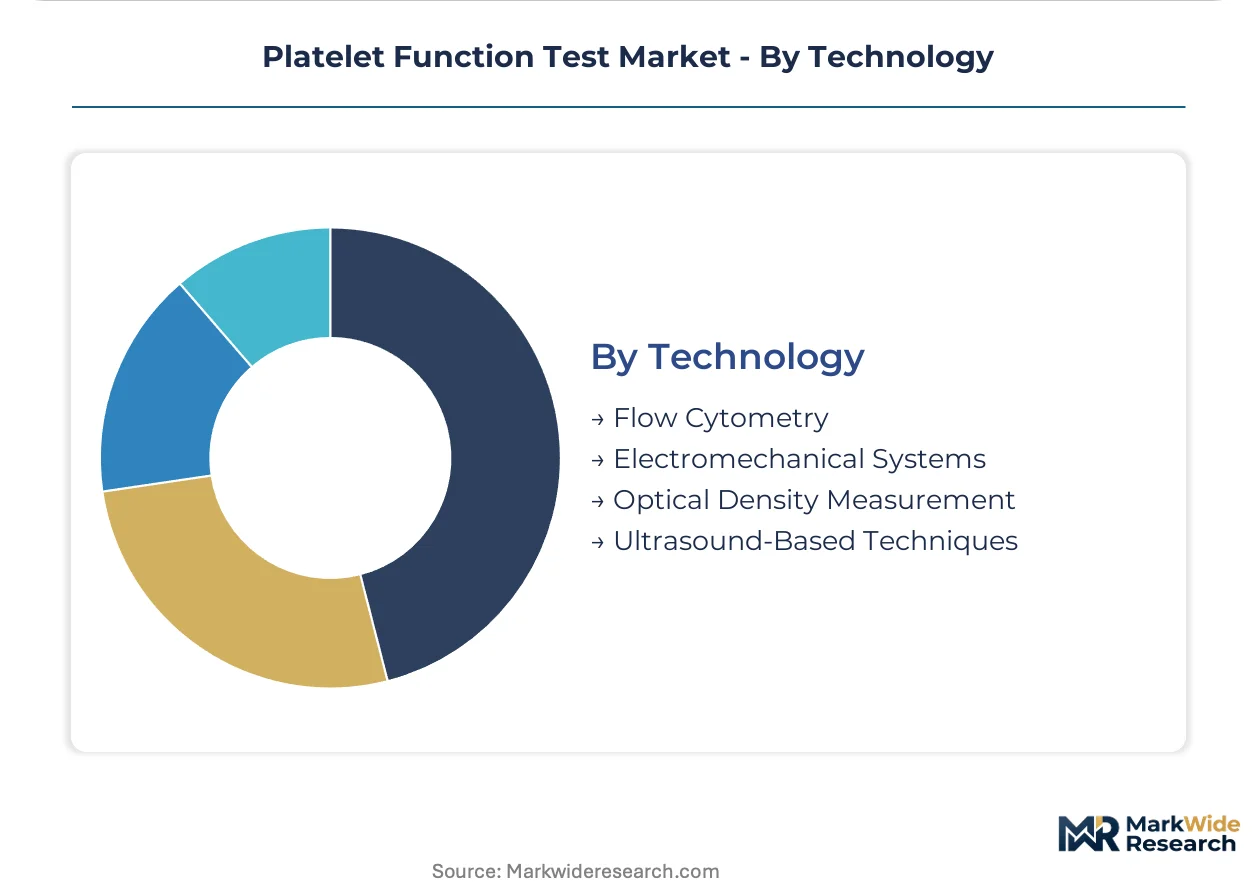
Technology:
Electromechanical detection dominates routine clinical throughput, while flow cytometry retains technology leadership in complex phenotyping applications requiring operator expertise.
- Flow Cytometry:Fluorescence-based single-cell analysis enables detailed platelet activation marker detection and granule release quantification. Research institutions in Germany and the Netherlands deploy these systems for drug development and rare disorder diagnosis.
- Electromechanical Systems:Impedance-based aggregometry measures electrical resistance changes during platelet aggregation without optical interference from lipemic or icteric samples. High-volume clinical laboratories in Japan and the United States favor this architecture for automated throughput.
- Optical Density Measurement:Light transmission aggregometry remains the reference method for platelet function assessment.
- Ultrasound-Based Techniques:Shear wave and acoustic detection methods enable label-free platelet adhesion monitoring.
Electromechanical systems hold the largest share; flow cytometry maintains the steepest expansion trajectory in research applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's diagnostic coverage expansion is reshaping cardiovascular testing infrastructure across the United States, while Japan's PMDA maintains distinct clinical evidence requirements that compress approval timelines for hemostasis diagnostics.
United States
Tertiary hospital cardiac surgery volumes drive point-of-care device procurement as catheterization labs mandate intraoperative turnaround under ten minutes. FDA guidance on P2Y12 inhibitor monitoring compresses test requirements from hours to minutes, forcing detection architecture reengineering. Boston and Cleveland medical centers anchor demand through value-based care contracts that incentivize procedural cost transparency.
Germany
EU IVDR conformity pathways filter market access for non-European reagent suppliers, creating placement opportunities for compliant manufacturers in hospital networks. CE marking under Class C device classification imposes clinical evidence requirements that consolidate procurement around established notified body relationships. The Rhine-Ruhr and Bavarian diagnostic laboratory clusters emphasize workflow density through multi-year hematology automation contracts.
Japan
Aging demographics expand cardiovascular procedure volumes in tertiary hospitals, generating procedural demand for platelet function verification before emergency intervention. PMDA maintains distinct validation standards for hemostasis diagnostics that extend approval timelines relative to other device categories. Tokyo and Osaka cardiovascular centers drive point-of-care adoption through diagnostic fee schedules that shape capital allocation priorities.
Switzerland
Lyophilized agonist production clusters expose downstream device manufacturers to input cost volatility and batch consistency risks. Swissmedic regulates hemostasis diagnostics with quality management system requirements that strain smaller supplier resources. Basel and Zurich chemical suppliers anchor the reagent supply chain through specialized agonist manufacturing capabilities.
Netherlands
Academic medical centers adopt microfluidic shear-based assays for antiplatelet drug development studies, displacing legacy optical methods. EMA-aligned regulatory frameworks facilitate cross-border diagnostic device circulation within European hospital networks. Rotterdam and Amsterdam research institutions specialize in complex platelet phenotyping referrals through flow cytometry platforms.
Platelet Function Test Market Competitive Environment
Listed leaders compete with private specialists across platform breadth versus workflow density dimensions. The market structures around three tiers: diversified diagnostics conglomerates with laboratory analyzer placements, point-of-care device specialists with cardiac surgery penetration, and reagent suppliers with lyophilized agonist production capabilities. Strategic moves concentrate on integrated informatics convergence and unbundled procurement models that separate capital placement from consumable recurring revenue.
Among diversified diagnostics conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthineers occupy positions that exemplify platform breadth and integrated informatics respectively. Sysmex Corporation represents the hematology automation archetype competing on workflow density in high-volume Asian diagnostic laboratories. These three anchors illustrate how competitive positioning diverges between laboratory analyzer scale and point-of-care turnaround specialization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Haemonetics Corporation |
| Sysmex Corporation |
| Helena Laboratories |
| Terumo Corporation |
| Fresenius SE & Co. KGaA |
| AggreDyne |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
EU IVDR Class C certification gates both supplier qualification and price stratification across the platelet function test market, forcing non-European manufacturers to absorb notified body costs that compliant rivals convert into tiered pricing power. German hospital networks exploit this asymmetry to extract transparent per-test terms while Swiss agonist suppliers capture upstream margin through lyophilized reagent premiums.
Pricing Analysis
Certification level (FDA 510(k)/CE IVDR/PMDA-grade) creates the primary spread between premium laboratory analyzers and handheld point-of-care units. Three-tier pricing structure across premium, standard, and economy levels tracks workflow density, with high-volume hematology automation contracts commanding per-test discounts below emergency medicine cartridge rates. Cost compression in point-of-care tiers is intensifying because cardiac surgery departments unbundle capital placement from consumable supply. Diagnostic laboratories in Japan exhibit the highest price sensitivity due to diagnostic fee schedule constraints, while United States value-based care systems prioritize total procedural cost transparency over unit economics.
Supply Chain Analysis
Lyophilized agonist inventories require six-to-nine-month stability validation cycles that extend lead times beyond standard diagnostic reagent procurement. Supply concentrates in Switzerland, Germany, and Japan for specialized agonist chemistry, while Taiwanese and South Korean electronics corridors feed optical miniaturization components. Raw material dependencies include porcine-derived reagents, high-purity buffers, and LED-based detection modules. Single-source vulnerability runs through Swiss chemical suppliers for P2Y12 receptor agonists. Distribution runs through laboratory distribution intermediaries in Europe, though United States health systems increasingly favor direct device procurement from point-of-care manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital procurement departments that unbundle device capital from reagent supply, fragmenting vendor relationships and compressing margin capture across the value chain.
For Market Incumbents: Consolidate reagent supply relationships with Swiss and German chemical suppliers to secure agonist batch consistency against emerging lyophilization specialists. Deepen backward integration into quality control material production to offset CE marking compliance burdens that strain smaller notified body partners. Defensive positioning requires preemptive IVDR technical documentation investment before 2027 procurement cycle renewals in French and German hospital networks. For New Entrants and Emerging Players: Anchor in United States trauma center emergency medicine protocols where ten-minute turnaround devices face minimal established competition from laboratory analyzer incumbents. Target underpenetrated bleeding disorder triage workflows ahead of cardiac surgery saturation. A focused go-to-market angle leverages transparent per-test pricing models that bypass laboratory distribution markups and align with value-based care contract structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostics conglomerates seeking to divest non-core hemostasis portfolios amid IVDR compliance cost concentration. Long-term viability hinges on point-of-care device manufacturers capturing standard-of-care designation through cardiology society guideline alignment. The signal to watch is Inflation Reduction Act preventive cardiovascular diagnostic coverage determinations that would elevate platelet function testing from procedural adjunct to reimbursed mandate.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR Class C technical documentation opens German hospital procurement to compliant manufacturers. |
| Hospital System Partnership | Direct purchasing relationships with United States cardiac surgery units bypass laboratory intermediaries. |
| Software Companion Development | Bidirectional LIS connectivity reduces manual transcription errors in mixed-vendor instrument fleets. |
| Reimbursement Strategy | IRA preventive cardiovascular coverage expansion may elevate testing to standard-of-care mandate. |
| Backward Integration | In-house lyophilized agonist production insulates against Swiss supplier cost volatility. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, hospital procurement directors, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, PMDA approval databases, EU IVDR notified body registries, and hospital procurement contract disclosures. Bottom-up segmentation modeling triangulated with top-down macroeconomic boundary checks across the analysis window.
Across the projection horizon, the analytical framework modeled demand by product type, application, technology, and end user, with geographic regulatory clusters as a cross-cutting dimension. CAGRs derived from procedure volume trajectories in cardiac surgery and antiplatelet therapy management protocols, calibrated against hematology automation placement cycles and point-of-care device adoption curves in emergency medicine.
Decision-makers should treat outputs as directional under assumptions of stable regulatory enforcement intensity and cardiac surgery volume continuity; material deviation in IVDR notified body capacity or PMDA validation timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Esoteric Testing Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Instrument Calibration Services Market
Testing Services
Mono Rapid Testing Market
Testing Services
Home Care Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Adiponectin Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Global Endocrine Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Blood Sugar Tester Market