
 Global Immunohematology Market | 2026-2036
Global Immunohematology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immunohematology Market Foresight
A shortage of certified immunohematology technologists is redrawing operational priorities across blood centers and hospital laboratories. Immucor leverages its automated instrument platforms to reduce manual testing dependency. Grifols sustains dominance in plasma-derived reagent supply through backward integration into donor collection networks. Bio-Rad Laboratories competes on molecular immunohematology assays that extend beyond serological methods.
Immunohematology encompasses the study of blood group antigens and antibodies, employing serological and molecular techniques to ensure compatibility between donor and recipient blood prior to transfusion or organ transplantation. Gel centrifugation technology occupies the largest installed base due to standardization advantages, while flow cytometry represents the fastest-expanding technology segment driven by complex antibody identification needs. Blood grouping reagents generate the steadiest revenue pool because hospitals replenish them at predictable intervals, whereas blood typing instruments command higher upfront margins with elongated replacement cycles.
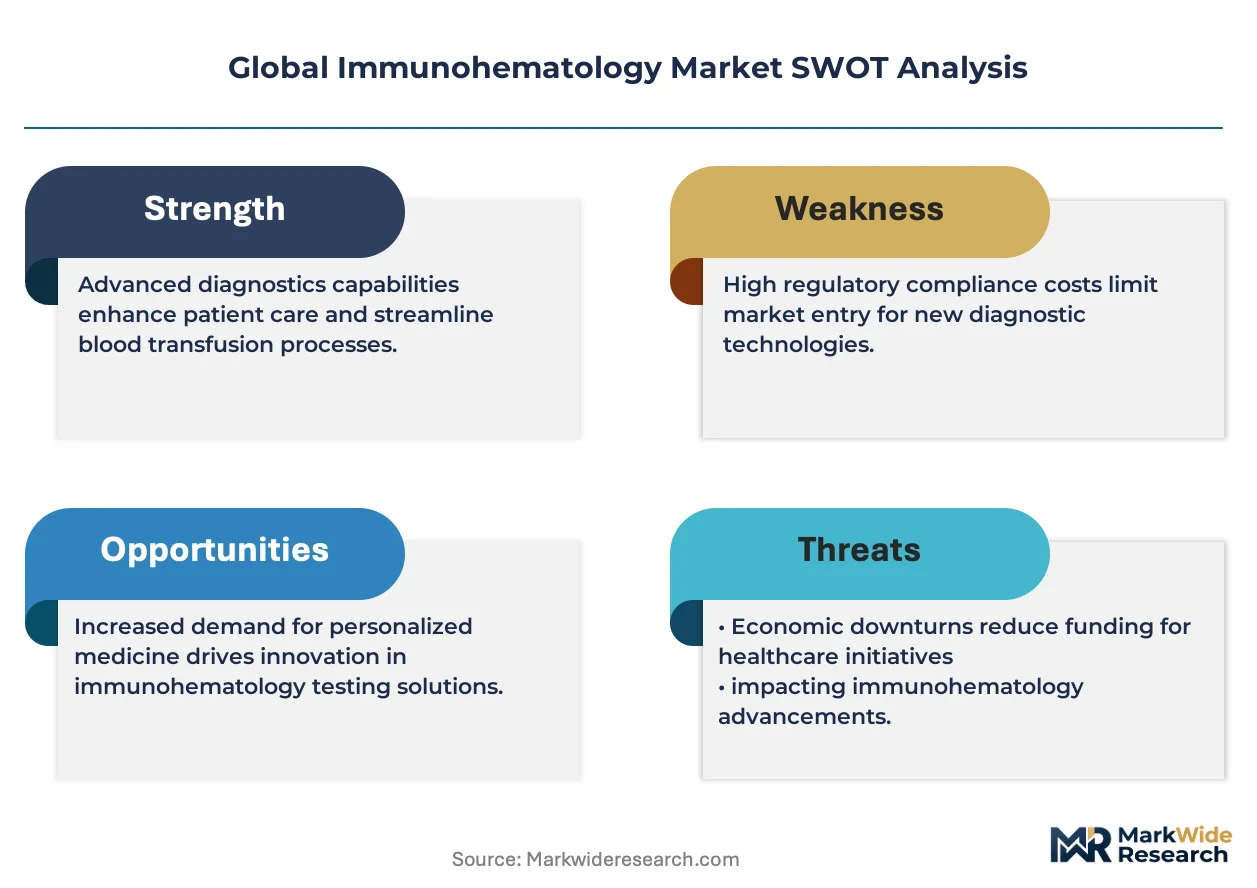
FDA blood establishment registration requirements and EMA CE marking under the In Vitro Diagnostic Regulation shape product development timelines and market access pathways for manufacturers. The EU AI Act introduces emerging compliance dimensions for automated immunohematology systems that incorporate machine learning algorithms for result interpretation. Stakeholders must weigh molecular assay adoption against infrastructure retrofit costs as reimbursement frameworks for extended antigen matching evolve across payer systems.
Market Dynamics
Automation platforms are compressing labor dependency across blood centers and hospital laboratories as certified technologist scarcity intensifies operational strain. Gel centrifugation retains dominance in routine testing while molecular assays capture complex antibody identification workflows.
Growth Catalysts
- FDA Blood Establishment Registration:Mandatory quality thresholds compel hospitals to upgrade reagent inventories and instrument platforms, sustaining replacement demand cycles.
- Oncology Transfusion Volumes:Chemotherapy-induced cytopenia drives sustained platelet and red cell demand across tertiary care centers in Germany, Japan, and the United States.
- Extended Antigen Matching:Molecular genotyping protocols reduce alloimmunization risk in sickle cell and thalassemia patient populations.
Market Restraints
- Reagent Input Concentration:Plasma-derived antibody supply depends on fractionator collection networks concentrated in the United States and Spain.
- EU IVDR Compliance Burden:CE marking transition under the In Vitro Diagnostic Regulation elongates product launch timelines and elevates documentation costs.
- Capital Intensity of Automation:Gel card and flow cytometry platforms require substantial upfront investment with seven-to-ten-year replacement cycles.
Strategic Opportunities
- Point-of-Care Blood Banking:Rural trauma centers in India and Brazil present underpenetrated demand for rapid bedside compatibility testing.
- EU AI Act Alignment:Automated result interpretation modules qualify for expedited conformity assessment when algorithm transparency documentation meets prescribed standards.
- NGS-Microarray Convergence:Next-generation sequencing platforms integrate with bead-based arrays to deliver high-throughput extended antigen profiles.
Industry Challenges
- Technologist Certification Pipeline:American Society for Clinical Pathology examination pass rates fail to match blood center vacancy rates.
- Legacy LIS Integration:Middleware compatibility gaps between automated instruments and hospital laboratory information systems prolong implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immunohematology Market |
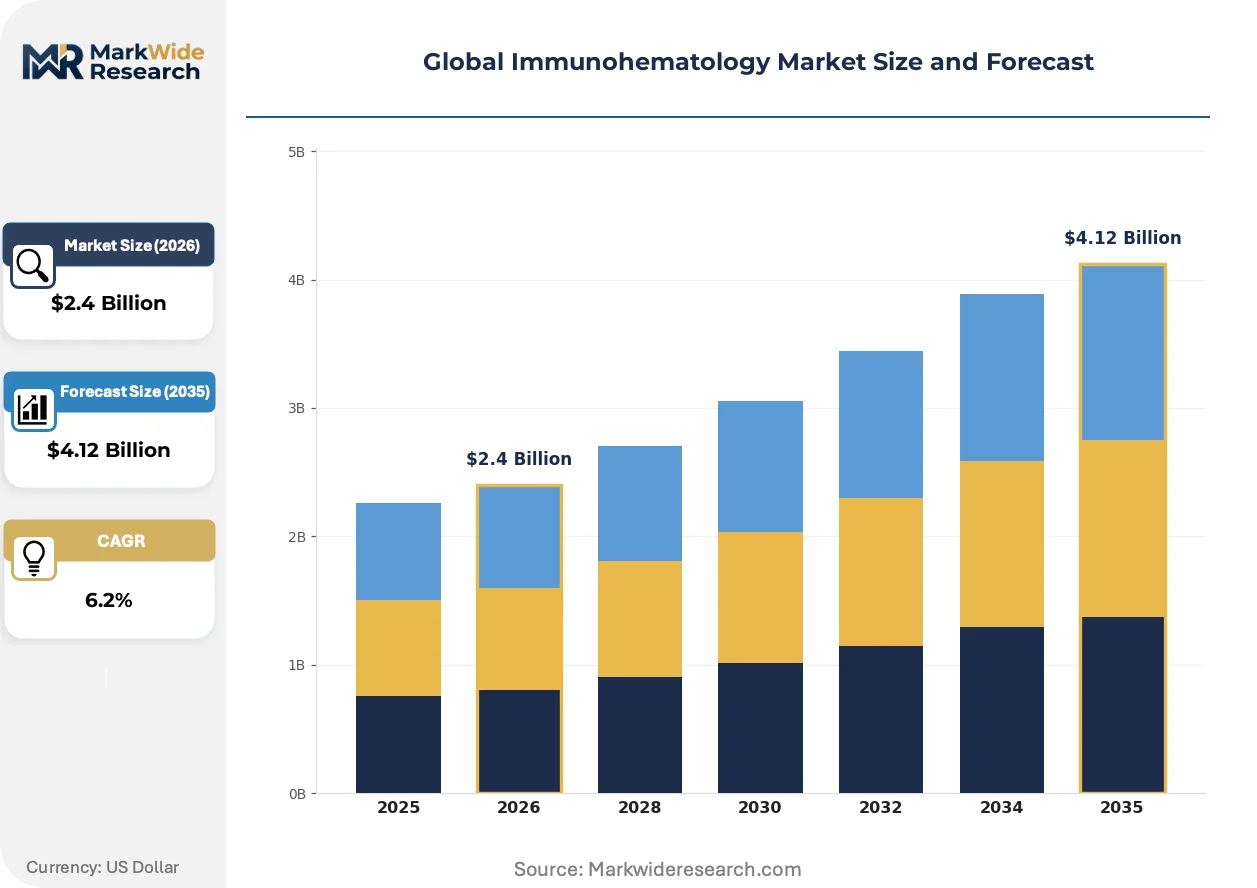
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Grouping Reagents, Cross-Matching Kits, Antibody Screening Test Kits, Blood Typing Instruments, Consumables Technology: Gel Centrifugation, Column Agglutination, Microplate, Solid Phase, Flow Cytometry Application: Blood Banks, Diagnostic Laboratories, Organ Transplant Centers, Forensic Laboratories, Academic & Research Institutes End User: Hospitals, Specialty Clinics, Blood Donation Centers, Research Laboratories |
| Companies Covered | Immucor, Grifols, Bio-Rad Laboratories, QuidelOrtho Corporation, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Beckman Coulter, Siemens Healthineers, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immunohematology Market Shifts & Advancements
Digital result interpretation and machine learning classification are redrawing competitive boundaries between instrument manufacturers and independent software developers. Regulatory frameworks are accelerating to address algorithmic decision-making in clinical diagnostics.
Molecular genotyping assays are supplanting serological methods for complex antibody identification and extended matching protocols. Reference laboratories in the United States and Germany are adopting these platforms at accelerated pace to address chronically transfused patient populations. The technology is compressing turnaround times for rare donor matching while elevating reagent margin structures.
EMA CE marking under the In Vitro Diagnostic Regulation imposes clinical evidence requirements that previously applied only to novel therapeutic devices. Manufacturers must now submit performance studies for Class C reagents, extending development timelines by twelve to eighteen months. Blood grouping reagent suppliers with legacy product portfolios face disproportionate compliance burdens.
Hospital procurement committees are consolidating vendor relationships to reduce validation overhead and service contract fragmentation. Integrated instrument-reagent contracts are displacing standalone reagent purchasing across multi-site health systems in the United States. This concentration is most visible in academic medical centers managing centralized transfusion services.
Global Immunohematology Market Segmentation
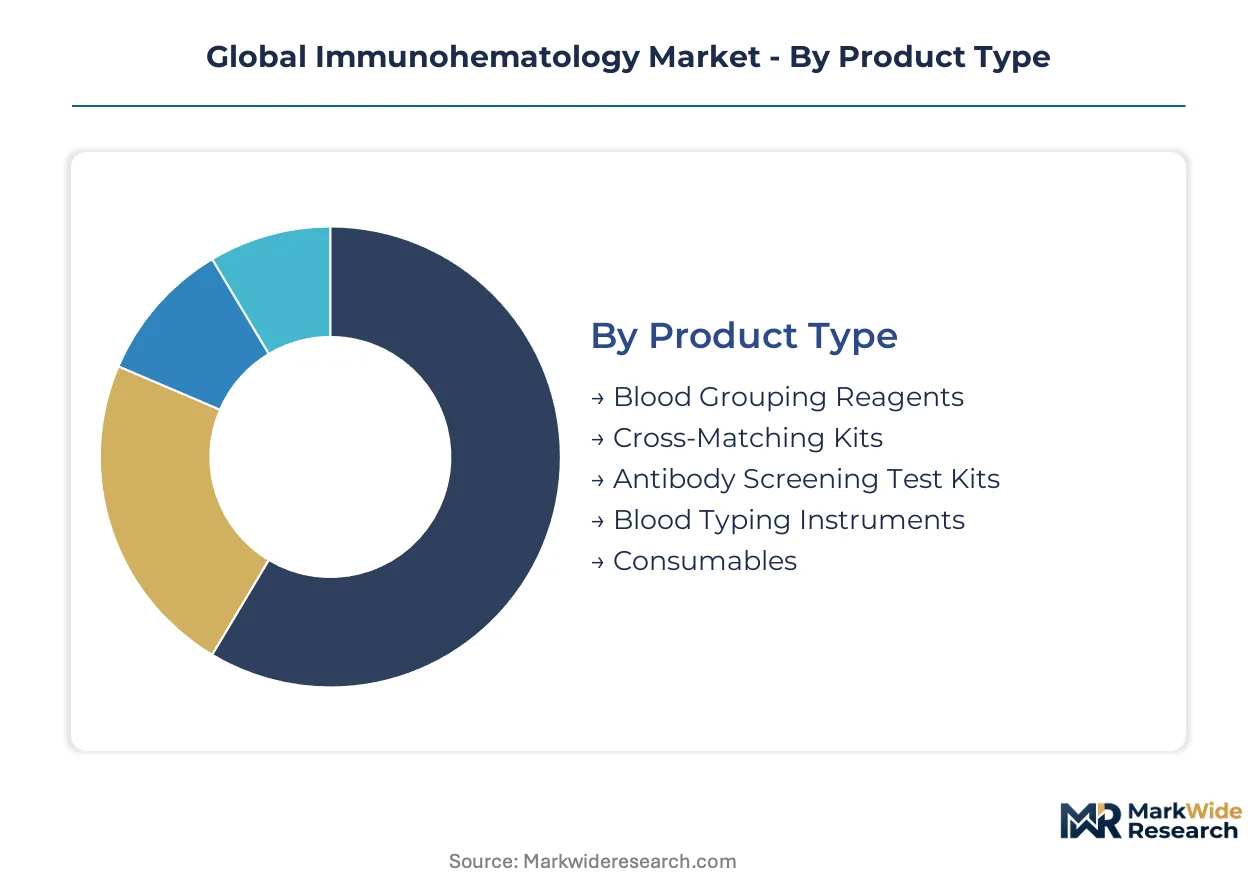
Segmentation in immunohematology reveals distinct competitive dynamics across product categories, with substitution pressure varying sharply between consumable reagents and capital-intensive instrumentation. Understanding these boundaries clarifies where manufacturers defend entrenched positions versus where insurgent technologies displace legacy methods.
Product Type:
Gel centrifugation platforms and molecular assays are exerting substitution pressure on conventional tube-based reagents, compressing margins in the most mature product categories.
- Blood Grouping Reagents:Antiserum-based solutions for ABO and Rh phenotyping constitute the highest-volume product line, with demand anchored in hospital transfusion services across the United States and Germany. Predictable replenishment cycles and FDA establishment registration requirements create substantial switching costs for institutional buyers.
- Cross-Matching Kits:Compatibility testing systems integrate donor and recipient samples through serological or gel-column methods, with trauma centers in Japan driving premium demand for rapid-turnaround formats. Extended antigen matching protocols in sickle cell treatment centers are elevating kit complexity and reagent consumption per test.
- Antibody Screening Test Kits:Panel cell arrays detect unexpected antibodies prior to transfusion, with reference laboratories representing the primary demand concentration.
- Blood Typing Instruments:Automated analyzers for gel card or microplate processing command substantial upfront investment, with seven-to-ten-year replacement cycles limiting near-term revenue volatility.
- Consumables:Pipette tips, reaction vessels, and quality control materials generate recurring revenue streams tied to instrument installed bases.
Blood grouping reagents anchor the volume base while blood typing instruments gain share at the steepest rate.
Technology:
Cost tier stratification separates high-throughput automation platforms from manual methods, with mid-range column agglutination systems capturing the broadest hospital laboratory footprint.
- Gel Centrifugation:Standardized card-based systems dominate routine ABO/Rh testing through objective endpoint interpretation and reduced technologist training requirements. German and Japanese blood centers have standardized on this format for donor screening workflows.
- Column Agglutination:Glass bead or gel matrix columns enable semi-automated processing with moderate capital investment, appealing to mid-volume hospital laboratories in the United States seeking workflow efficiency without full automation.
- Microplate:96-well formats support high-throughput screening in large-scale blood donor facilities, with EMA CE marking under IVDR imposing new performance study requirements.
- Solid Phase:Microwell coated with red cell membranes capture antibodies for automated detection, with adoption concentrated in reference laboratories handling complex serological investigations.
- Flow Cytometry:Laser-based detection of antigen-antibody binding enables extended phenotyping and rare donor matching, with academic medical centers in Germany pioneering clinical integration.
Gel centrifugation anchors the volume base while flow cytometry climbs the fastest.
Application:
Customer type fragmentation creates divergent purchasing patterns, with centralized blood banks consolidating vendor relationships while forensic laboratories prioritize specialized assay formats.
- Blood Banks:National and regional collection facilities process donor units through high-throughput screening lines, with the United States and Spain hosting the most concentrated infrastructure. FDA blood establishment registration mandates sustain quality investment cycles.
- Diagnostic Laboratories:Hospital-based and independent reference labs perform pre-transfusion testing, with oncology transfusion volumes in tertiary centers driving sustained demand.
- Organ Transplant Centers:Histocompatibility laboratories require extended antigen matching for solid organ and stem cell recipients, with molecular genotyping displacing serological methods in HLA-adjacent workflows.
- Forensic Laboratories:Bloodstain identification and parentage testing applications demand specialized antisera with documented chain-of-custody protocols.
- Academic & Research Institutes:Investigation of rare blood group systems and antibody mechanisms generates demand for research-grade reagents outside clinical regulatory pathways.
Diagnostic laboratories anchor the volume base while organ transplant centers gain share at the steepest rate.
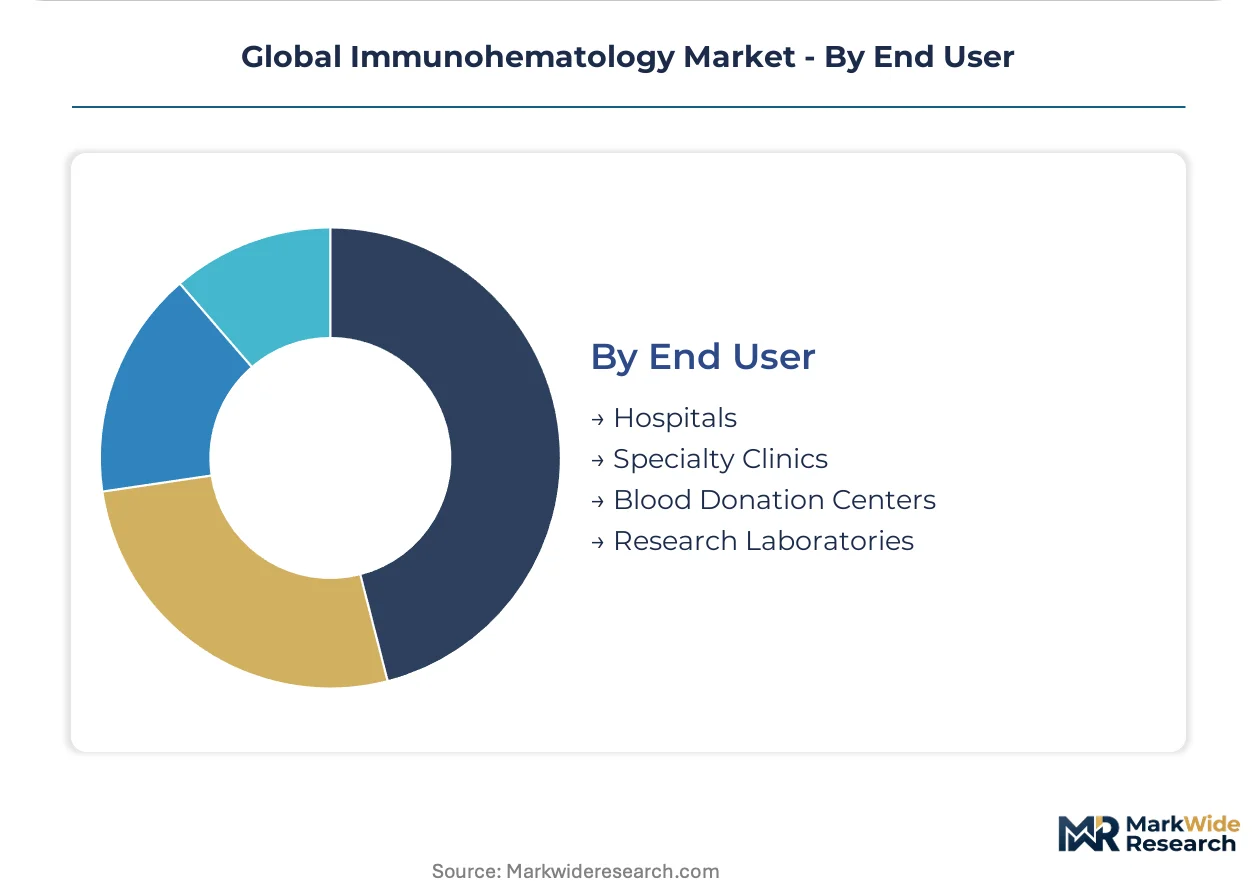
End User:
Procurement authority concentration varies sharply, with hospital system centralization displacing standalone laboratory purchasing autonomy.
- Hospitals:Transfusion services within acute care facilities represent the largest end-user category, with multi-site health systems in the United States consolidating vendor contracts to reduce validation overhead.
- Specialty Clinics:Hematology and oncology outpatient centers perform limited pre-transfusion testing, with chemotherapy-induced cytopenia sustaining platelet demand.
- Blood Donation Centers:Fixed and mobile collection sites screen donor units prior to component preparation, with backward integration into plasma collection networks securing reagent supply.
- Research Laboratories:Investigational studies of immunohematological mechanisms operate outside clinical reimbursement frameworks, with funding volatility constraining equipment refresh cycles.
Hospitals anchor the volume base while blood donation centers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA blood establishment registration requirements anchor the United States as the dominant geography, with EMA IVDR compliance and Japan's PMDA oversight shaping parallel development pathways across major markets.
United States
Oncology transfusion volumes and trauma center demand drive reagent consumption across tertiary care networks. FDA blood establishment registration mandates compel hospitals to upgrade instrument platforms and reagent inventories on predictable cycles. The Boston-Cambridge cluster houses reference laboratories pioneering molecular genotyping for extended antigen matching in sickle cell populations.
Germany
Aging demographics expand chronic disease burdens requiring sustained platelet and red cell support. EMA CE marking under the In Vitro Diagnostic Regulation imposes clinical evidence requirements that extend product launch timelines. The Rhine-Ruhr industrial corridor concentrates blood center automation infrastructure serving centralized transfusion services.
Japan
PMDA oversight maintains stringent quality thresholds for imported reagents and domestic manufacturing. METI industrial policy supports domestic production capacity for critical blood safety materials. The Kanto region around Tokyo hosts the densest concentration of hospital transfusion services with automated gel centrifugation platforms.
India
Rural trauma centers present underpenetrated demand for rapid bedside compatibility testing outside metropolitan hospital networks. CDSCO regulatory pathways for in vitro diagnostics are converging toward international standards. Maharashtra's Mumbai-Pune corridor anchors private hospital chain procurement of semi-automated column agglutination systems.
Brazil
ANVISA pharmaceutical and medical device oversight governs import licensing for blood grouping reagents and typing instruments. Public health system expansion drives demand for cost-efficient manual testing formats in regional blood centers. São Paulo state's hospital network concentrates advanced transfusion medicine capacity serving the southeastern population corridor.
Global Immunohematology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with plasma fractionators and diagnostic conglomerates occupying distinct competitive positions. The upper tier commands instrument-reagent bundled contracts across multi-site health systems. Three archetypes prevail: backward-integrated plasma suppliers, automated platform manufacturers, and molecular assay specialists. Consolidation through instrument-reagent integration and geographic licensing partnerships represents the dominant competitive vectors.
Among North American diagnostic specialists, Immucor, Bio-Rad Laboratories, and QuidelOrtho Corporation occupy positions across the automation-to-molecular spectrum. Immucor exemplifies the platform-integrated archetype with instrument-reagent bundling strategies. Bio-Rad Laboratories represents molecular assay specialization extending beyond serological methods. QuidelOrtho Corporation sits within the consolidated diagnostic conglomerate tier following recent corporate combinations.
| Leading Market Players |
|---|
| Immucor |
| Grifols |
| Bio-Rad Laboratories |
| QuidelOrtho Corporation |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Siemens Healthineers |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
FDA blood establishment registration and EMA CE marking under IVDR operate as simultaneous gating mechanisms for supply qualification and price stratification, with only certified manufacturers accessing premium hospital contracts while uncertified suppliers compete on cost in emerging markets.
Pricing Analysis
Long-term instrument-reagent bundled contracts dominate hospital procurement, locking multi-site health systems into predictable reagent replenishment cycles with embedded service premiums. Price differentiation separates FDA-registered premium tiers from standard CE-marked alternatives, with oncology transfusion centers showing lowest price sensitivity due to clinical risk aversion. Cost compression in manual testing formats intensifies as automated platforms displace labor-intensive workflows across mid-volume laboratories.
Supply Chain Analysis
Container availability constraints on trans-Atlantic and Asia-Pacific trade lanes elevate inbound logistics costs for temperature-sensitive reagent shipments, compressing margins for distributors serving decentralized hospital networks. Plasma fractionation capacity concentrates in the United States and Spain, with antibody supply drawing from donor collection networks subject to seasonal variability. Single-source vulnerability in rare antisera production elevates supply risk for extended antigen matching protocols. Distribution runs through specialized cold-chain logistics partners serving blood center and hospital laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including instrument maintenance contracts and software update subscriptions are expanding faster than hardware sales, creating defensible recurring revenue pools for platform-integrated vendors.
For Market Incumbents: Shield installed base positions through backward integration into plasma collection networks that secure captive antibody supply, while accelerating FDA submission timelines for molecular assay portfolios to preempt displacement by genotyping specialists. Certification investment in EU AI Act conformity assessment for automated result interpretation modules represents a critical defensive lever against software-centric entrants. For New Entrants and Emerging Players: Differentiate on point-of-care compatibility testing formats targeting rural trauma centers in India and Brazil, where underpenetrated demand exists outside metropolitan hospital procurement hierarchies. Partner with regional distributors possessing established cold-chain infrastructure to circumvent direct validation overhead with centralized health systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across molecular assay sub-segments as NGS-microarray convergence reduces platform development costs, improving entry economics for specialized genotyping firms. Acquisition targets with validated extended antigen matching protocols and reference laboratory relationships offer strongest long-term viability within a five-to-ten year window. Monitor EMA IVDR performance study submission volumes as inflection indicator for regulatory compliance burden trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Instrument-Reagent Bundling | Locks hospital procurement committees into multi-year contracts with predictable reagent replenishment revenue. |
| EU AI Act Conformity Assessment | Expedites market access for automated interpretation modules through algorithm transparency documentation. |
| NGS-Microarray Platform Integration | Delivers high-throughput extended antigen profiles for sickle cell and thalassemia patient populations. |
| Plasma Collection Network Expansion | Secures captive antibody supply for blood grouping reagent manufacturing against fractionator concentration. |
| Point-of-Care Rapid Testing Development | Captures rural trauma center demand outside metropolitan hospital laboratory procurement hierarchies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blood center technologists, hospital transfusion service directors, reagent manufacturing quality leads, and diagnostic instrument platform engineers. Secondary validation drew from FDA blood establishment registration databases, EMA IVDR submission trackers, hospital procurement contract disclosures, and GPO pricing benchmarks. Bottom-up instrument installed base estimates were triangulated against top-down reagent consumption models.
Across the analysis window, volume and value outputs reflect segmentation across product type, technology platform, application setting, and end-user procurement authority. CAGRs were derived from instrument replacement cycle analysis and reagent replenishment elasticity modeling. Forecast inputs incorporated oncology transfusion volume projections, technologist certification pipeline constraints, and molecular assay reimbursement evolution.
Material uncertainties — regulatory timeline delays, plasma collection network disruptions, and algorithmic diagnostic approval precedents — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EMA IVDR transition pacing and FDA quality threshold maintenance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Polycythemia Vera Treatment Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Multiple Myeloma Market
Hematology
Rare Hematology Market
Hematology
Sickle Cell Treatment Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Bone Marrow Transplant Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Pancytopenia Market
Hematology
Global Hematology Diagnostics Market
Hematology
Non-Hodgkin Lymphoma Treatment Market
Hematology
Hemostatic Spray Market
Hematology
Blood Screening Market
Hematology
Graft vs Host Disease Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market