
 Hematologic Malignancies Market | 2026-2036
Hematologic Malignancies Market Size, Share, and Industry Trends Forecast 2026-2036
Hematologic Malignancies Market Intelligence
Oncology-trained clinical trial investigators is reorganizing how quickly novel hematologic therapies reach pivotal study readouts. Bristol-Myers Squibb Company leverages its immuno-oncology manufacturing scale to sustain checkpoint inhibitor supply for lymphoma protocols. F. Hoffmann-La Roche Ltd anchors its position through companion diagnostic co-development with targeted agents. AbbVie Inc. specializes in B-cell pathway modulation, occupying a distinct niche in chronic lymphocytic leukemia.
Hematologic malignancies encompass cancers arising from blood-forming tissues and immune cells, including leukemias, lymphomas, and plasma cell neoplasms, characterized by clonal proliferation of hematopoietic cells with defined cytogenetic and molecular aberrations. These conditions require therapeutic intervention to restore normal hematopoiesis and prevent organ infiltration. Immunotherapy commands the highest margin pool as CAR-T cell therapies and bispecific antibodies attract premium pricing and dedicated manufacturing infrastructure. Leukemia represents the most mature therapy area with established chemotherapy backbones, while multiple myeloma is the fastest-expanding segment driven by proteasome inhibitor and anti-CD38 antibody uptake.
The FDA's accelerated approval and breakthrough therapy designation programs compress development timelines for hematologic cancer drugs, while the EMA's PRIME scheme and Japan's PMDA sakigake framework create parallel regulatory momentum in Europe and Asia. The EU's MDR and GDPR impose stringent clinical evidence and data governance requirements on diagnostic-therapeutic combinations. Stakeholders must monitor evolving biomarker qualification standards across FDA, EMA, and PMDA to align global development strategies with divergent evidentiary thresholds.
Market Dynamics
The FDA's accelerated approval pathway is compressing commercialization timelines for novel hematologic therapies while simultaneously fragmenting reimbursement negotiations across payers. This regulatory velocity is reshaping how manufacturers sequence clinical investments and prioritize biomarker-driven patient subsets.
Growth Catalysts
- CAR-T Manufacturing Scale-Up:Dedicated cell therapy facilities in the United States and Germany are expanding production slots for lymphoma protocols. Academic medical centers are securing long-term supply agreements with vector manufacturers.
- Breakthrough Therapy Designation:The FDA's expedited review framework is shortening time-to-market for bispecific antibodies in multiple myeloma. Developers are front-loading pivotal trials to capture priority review vouchers.
- Biomarker Infrastructure:Next-generation sequencing platforms in Japan and the United States are enabling real-time minimal residual disease monitoring. Community oncology networks are integrating these assays into standard care pathways.
Market Restraints
- Plasma-Derived Input Volatility:Apheresis collection capacity constraints in the United States are creating bottlenecks for immunoglobulin and albumin feedstocks used in cell culture media.
- EMA MDR Compliance Burden:The EU's Medical Device Regulation is extending validation timelines for companion diagnostic kits co-developed with targeted hematologic agents.
- Vein-to-Vein Logistics:Cryogenic cold chain dependencies for autologous cell therapies are concentrating treatment access around metropolitan infusion centers with validated logistics partnerships.
Strategic Opportunities
- Rural Infusion Network Expansion:Mobile cryogenic transport units are extending CAR-T access beyond academic hubs into secondary markets across the United States Midwest and Southern regions.
- Allogeneic Platform Convergence:Off-the-shelf cell therapy technologies are converging with gene-editing tools to reduce manufacturing turnaround from weeks to days.
- PMDA Sakigake Pathway:Japan's priority review scheme is attracting early-phase hematologic asset filings, creating first-mover advantages for developers willing to commit to Japanese pivotal trials.
Industry Challenges
- Cell Therapy Workforce Scarcity:Trained apheresis nurses and GMP manufacturing technicians are in acute shortage across the United States and Germany, constraining site activation for new protocols.
- Legacy EHR Integration:Electronic health record systems at community oncology practices require costly customization to support real-time biomarker ordering and results routing for precision hematology workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hematologic Malignancies Market |
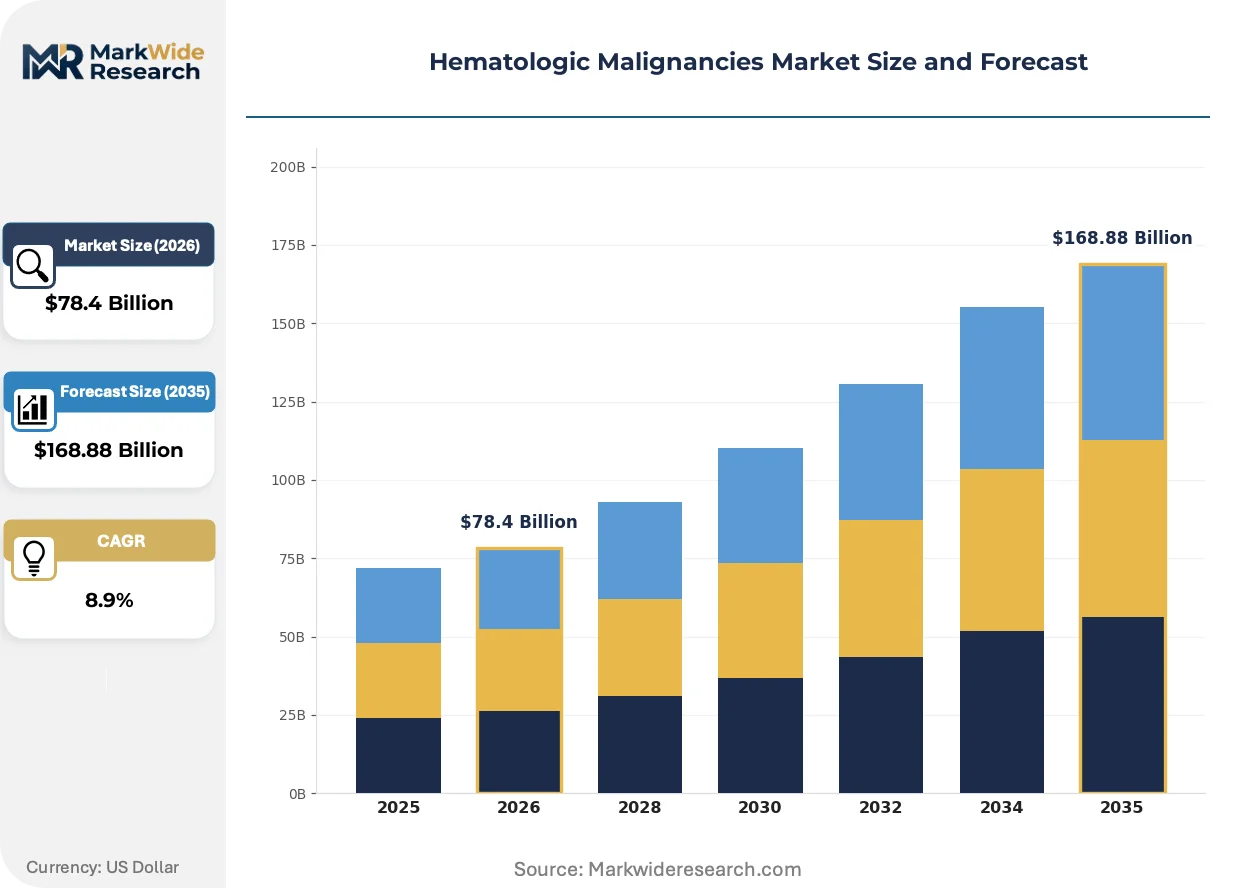
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $168.88 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Chemotherapy, Immunotherapy, Hematopoietic Stem Cell Transplant, Biosimilars Therapy Area: Leukemia, Lymphoma, Multiple Myeloma, Myelodysplastic Syndromes, Waldenström Macroglobulinemia End User: Oncology Centers, Hematology Clinics, Research Institutes, Diagnostic Laboratories, Specialty Hospitals Treatment Delivery Mode: Intravenous, Oral, Subcutaneous, Intrathecal, Combination Regimens |
| Companies Covered | Pfizer Inc., F. Hoffmann-La Roche Ltd, Sanofi SA, Bristol-Myers Squibb Company, AbbVie Inc., Novartis AG, Johnson & Johnson, Amgen Inc., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hematologic Malignancies Market Strategic Shifts & Innovations
Precision medicine infrastructure is fragmenting traditional chemotherapy paradigms across hematologic malignancies. Three convergent forces are restructuring how therapies are developed, reimbursed, and delivered to patients.
Bispecific T-cell engagers are fragmenting the relapsed/refractory lymphoma treatment algorithm by offering outpatient administration without the manufacturing complexity of autologous cell therapies. Community oncology practices in the United States are adopting these antibodies faster than academic centers had projected. The structural consequence is compressing hospital-based infusion revenue while expanding pharmacy benefit management control over oncology drug spend.
REACH regulation in Europe is tightening disclosure requirements for chemicals used in cell culture media and viral vector production processes. Manufacturers are reformulating reagent compositions to pre-register substances ahead of sunset dates. Hematologic cell therapy developers with EU commercialization plans are most affected, accelerating supplier qualification audits and dual-sourcing strategies for critical raw materials.
Site-of-care economics are driving consolidation in where complex hematologic therapies are administered. Payers in Germany and the United States are narrowing networks to centers meeting quality benchmarks for infection rates and turnaround times. Academic medical centers with integrated manufacturing capabilities are capturing disproportionate volume as commercial insurers steer patients away from lower-volume community sites lacking on-site apheresis and cryopreservation infrastructure.
Hematologic Malignancies Market Segmentation
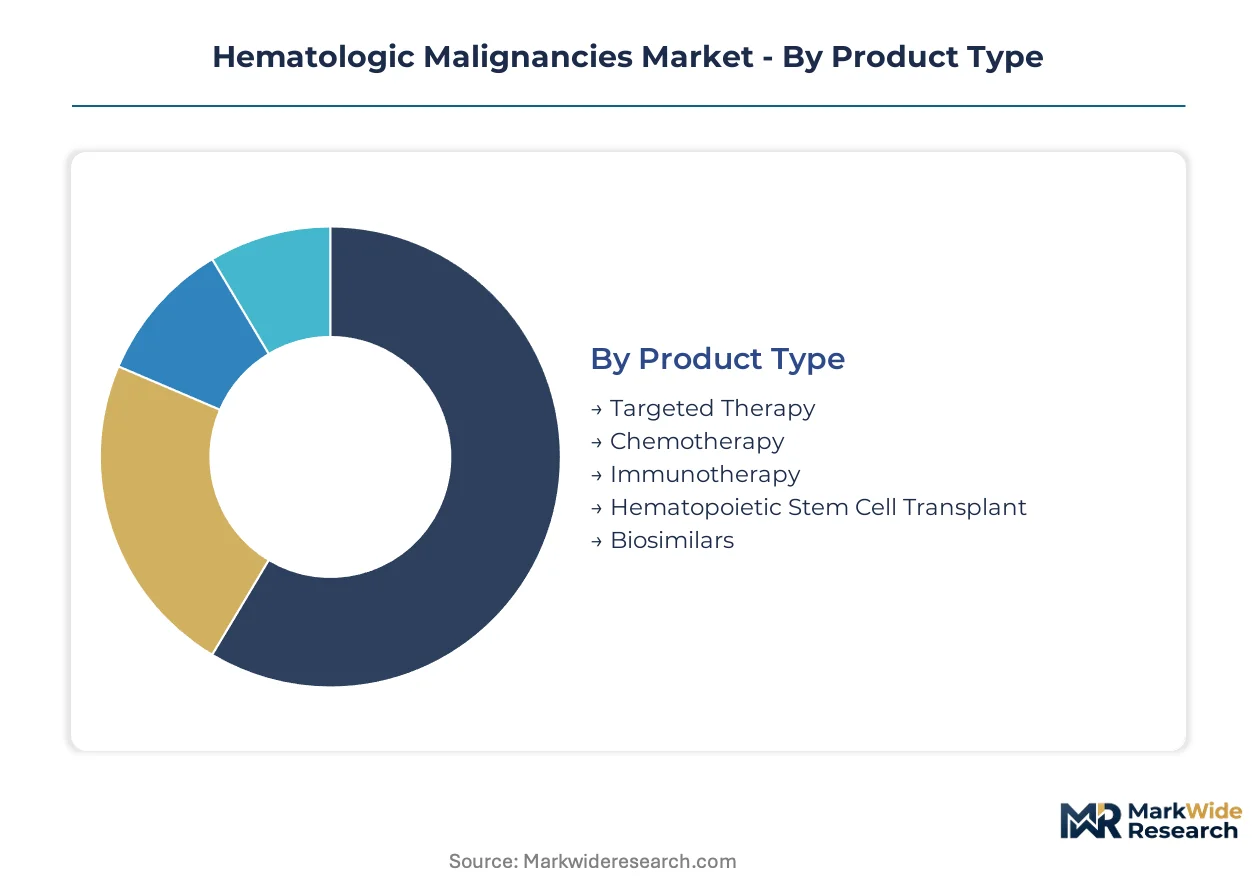
Segmentation in hematologic malignancies determines reimbursement pathways and site-of-care economics. Product type influences manufacturing investment priorities, while therapy area shapes clinical trial recruitment and regulatory strategy.
Product Type:
Channel mix varies sharply across modalities, with hospital outpatient departments capturing cell therapies and retail pharmacies handling oral targeted agents.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies directed at specific molecular aberrations. Demand concentrates in the United States and Germany where next-generation sequencing infrastructure enables biomarker-driven patient identification. Oral formulations expand community oncology access beyond infusion centers.
- Immunotherapy:CAR-T cell therapies, bispecific antibodies, and checkpoint inhibitors requiring specialized manufacturing or handling. Academic medical centers with apheresis capability and cryopreservation infrastructure dominate this channel. Payers in Japan and the United States are establishing distinct reimbursement mechanisms for these premium modalities.
- Chemotherapy:Established cytotoxic backbones including alkylating agents, antimetabolites, and anthracyclines. Generic competition has compressed margins, shifting volume toward cost-conscious health systems.
- Hematopoietic Stem Cell Transplant:Allogeneic and autologous transplantation services bundled at high-volume tertiary centers. Capacity constraints in Germany and the United States limit expansion.
- Biosimilars:Follow-on biologics referencing rituximab, trastuzumab, and other oncology monoclonals. European markets through EMA centralized approval have accelerated uptake faster than FDA-regulated channels.
By volume, chemotherapy leads. By growth pace, immunotherapy is expanding most quickly.
Therapy Area:
Cost tier stratification separates curative-intent protocols in acute leukemias from chronic management in indolent lymphomas.
- Leukemia:Acute myeloid and lymphoid malignancies requiring intensive induction regimens. Pediatric and young-adult protocols in Japan and the United States drive innovation in minimal residual disease monitoring.
- Lymphoma:Hodgkin and non-Hodgkin subtypes with divergent prognosis profiles. Diffuse large B-cell lymphoma commands the largest addressable population for CAR-T therapies.
- Multiple Myeloma:Plasma cell neoplasm with sequential relapse patterns driving continuous therapy models. Proteasome inhibitors and anti-CD38 antibodies anchor treatment sequences.
- Myelodysplastic Syndromes:Clonal stem cell disorders with risk-stratified management. Hypomethylating agents dominate higher-risk categories.
- Waldenström Macroglobulinemia:Rare lymphoplasmacytic lymphoma with BTK inhibitor sensitivity. Small patient pools concentrate expertise at designated centers of excellence.
Leukemia maintains the deepest clinical trial pipeline. Multiple myeloma shows the steepest expansion trajectory in novel agent approvals.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating procurement for community oncology practices.
- Specialty Hospitals:Dedicated cancer centers with embedded research infrastructure. These facilities capture complex protocols requiring inpatient capacity.
- Oncology Centers:Ambulatory infusion suites handling chemotherapy and supportive care. United States-based networks are consolidating under payer pressure.
- Hematology Clinics:Physician practices focused on benign and malignant blood disorders. Chronic lymphocytic leukemia monitoring generates recurring visit volume.
- Research Institutes:Academic medical centers conducting early-phase trials. FDA and EMA investigator-initiated study programs channel funding.
- Diagnostic Laboratories:Reference labs processing flow cytometry, cytogenetics, and molecular profiling. Companion diagnostic co-development partnerships with pharmaceutical sponsors are restructuring this segment.
Specialty hospitals lead by patient acuity. Oncology centers are gaining share fastest through site-of-care migration.
Treatment Delivery Mode:
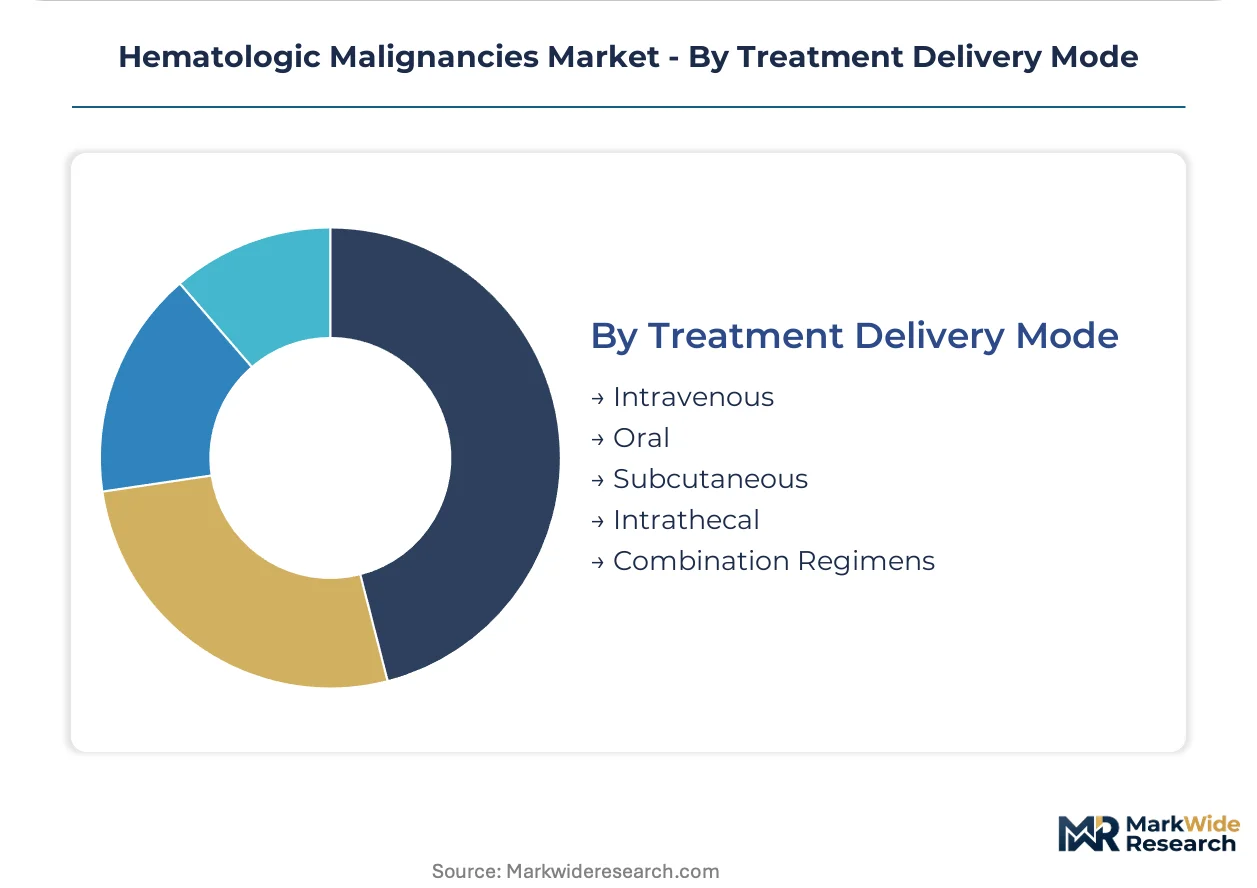
Volume distribution tracks administration complexity, with oral agents enabling home-based management and intravenous regimens anchoring facility revenue.
- Intravenous:Infusion-dependent monoclonal antibodies, chemotherapy, and cellular therapies. Hospital outpatient departments in Germany and the United States defend this volume through pharmacy benefit carve-outs.
- Oral:Tyrosine kinase inhibitors and immunomodulatory drugs with patient-administered dosing. Specialty pharmacy networks in the United States manage distribution and adherence monitoring.
- Subcutaneous:Self-injection formulations reducing clinic burden. Anti-CD38 antibodies and some bispecifics are migrating to this route.
- Intrathecal:Central nervous system prophylaxis and treatment for leukemic meningitis. Limited to specialized centers with neuro-oncology capability.
- Combination Regimens:Multi-agent protocols with sequential or concurrent administration. Clinical trial networks standardize these across sites.
Intravenous dominates current volume. Oral delivery is climbing the fastest as fixed-duration regimens expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision medicine infrastructure varies sharply across major markets, with the United States and Japan deploying CAR-T manufacturing at scale while Germany concentrates hematopoietic stem cell transplant capacity and India expands access to oral targeted agents through domestic production.
United States
FDA accelerated approval pathways compress commercialization timelines for bispecific antibodies and cell therapies. Academic medical centers in Boston, Houston, and Seattle anchor CAR-T manufacturing networks with validated apheresis partnerships. Payers are narrowing site-of-care networks to high-volume infusion centers meeting quality benchmarks.
Germany
EMA centralized marketing authorizations enable rapid uptake of novel hematologic agents across the federal system. The MDR compliance burden extends validation timelines for companion diagnostic kits co-developed with targeted therapies. Heidelberg and Munich clusters concentrate hematopoietic stem cell transplant expertise with integrated GMP cell processing facilities.
Japan
PMDA sakigake priority review attracts early-phase hematologic asset filings from developers committing to Japanese pivotal trials. Tokyo and Osaka academic centers deploy real-time minimal residual disease monitoring through next-generation sequencing platforms. METI funding supports domestic vector manufacturing to reduce import dependency for cell therapy supply chains.
United Kingdom
NICE technology appraisals create transparent reimbursement thresholds for premium hematologic immunotherapies. London and Manchester cancer centers participate in early access schemes for breakthrough-designated agents. The MHRA post-Brexit regulatory pathway diverges from EMA timelines for certain targeted therapy submissions.
India
CDSCO accelerated approval mechanisms expand access to biosimilar rituximab and generic imatinib formulations. Mumbai and Hyderabad manufacturing clusters produce active pharmaceutical ingredients for global hematologic therapy supply chains. Domestic clinical trial infrastructure scales investigator-initiated studies in acute leukemia protocols.
Hematologic Malignancies Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding cell therapy manufacturing scale and companion diagnostic co-development capabilities while mid-tier players concentrate on B-cell pathway modulation and targeted agent portfolios. Strategic archetypes include immuno-oncology platform builders, precision hematology specialists, and biosimilar challengers eroding legacy monoclonal margins. Competitive moves center on M&A to secure vector manufacturing capacity and strategic partnerships to embed diagnostics into therapy development.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd occupies a position exemplifying companion diagnostic integration with targeted hematologic agents. Bristol-Myers Squibb Company represents the immuno-oncology manufacturing archetype with checkpoint inhibitor supply scale for lymphoma protocols. AbbVie Inc. anchors the B-cell pathway specialization tier, occupying a distinct niche in chronic lymphocytic leukemia therapeutic development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Sanofi SA |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Novartis AG |
| Johnson & Johnson |
| Amgen Inc. |
| GlaxoSmithKline plc |
| Others |
Cost & Logistics Intelligence
FDA's GMP certification regime for cell therapy manufacturing gates both supplier qualification and price differentiation simultaneously, concentrating premium pricing power among academic medical centers with validated apheresis partnerships while compressing margins for community sites lacking cryopreservation infrastructure.
Pricing Analysis
Long-term offtake agreements between CAR-T developers and vector manufacturers anchor pricing for autologous cell therapies, while spot purchasing dominates chemotherapy backbones and supportive care agents. Price differentiation rests on GMP certification tier and manufacturing scale, with FDA-approved facilities commanding substantial premiums over non-certified alternatives. Cost compression in the chemotherapy tier is intensifying because of biosimilar rituximab entry and generic imatinib expansion. Community oncology practices exhibit the highest price sensitivity due to payer steerage toward narrow networks, while academic medical centers with integrated manufacturing show the least.
Supply Chain Analysis
Strategic stockpiling of cryogenic storage capacity and viral vector feedstocks dominates inventory strategy over just-in-time approaches, given the vein-to-vein logistics constraints and patient-matched manufacturing requirements. Supply concentrates in the United States, Germany, and Japan, where GMP cell processing infrastructure and apheresis networks are most developed. Raw material dependencies center on plasma-derived albumin, recombinant cytokines, and synthetic cell culture media. Single-source vulnerability in vector manufacturing creates structural risk, as qualified suppliers remain limited. Distribution runs through hospital outpatient departments with validated cold chain partnerships rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized manufacturing capabilities and trained clinical workforces are becoming the binding constraint on market expansion, with GMP technician scarcity and apheresis nurse shortages creating bottlenecks that determine which developers can execute at scale.
For Market Incumbents: Shield manufacturing margins by securing captive vector production capacity through backward integration into plasmid supply and viral vector suites. Consolidate site-of-care networks around high-volume infusion centers with on-site apheresis capability to defend against payer narrowing. Prioritize EMA MDR compliance investment for companion diagnostic co-development partnerships ahead of sunset dates. For New Entrants and Emerging Players: Anchor in allogeneic platform development to bypass the autologous manufacturing bottleneck and compress turnaround times from weeks to days. Target Waldenström macroglobulinemia and myelodysplastic syndromes as underpenetrated therapy areas with concentrated expertise requirements and less competitive intensity. Pursue PMDA sakigake pathway filings to establish first-mover positioning in Japan's priority review framework. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across CAR-T manufacturing infrastructure as dedicated cell therapy facilities require substantial upfront investment and long validation timelines. Long-term viability over the coming decade hinges on securing positions in bispecific antibody and allogeneic cell therapy platforms that reduce manufacturing complexity. Target acquisition archetypes include vector manufacturers with established GMP compliance and gene-editing technology specialists. Monitor FDA breakthrough therapy designation grants as an inflection signal for pipeline prioritization and valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | F. Hoffmann-La Roche Ltd's integrated approach with targeted agents accelerates biomarker-driven patient identification and reimbursement. |
| Allogeneic Platform Investment | Gene-editing convergence with off-the-shelf cell therapies reduces manufacturing turnaround from weeks to days. |
| Vector Manufacturing Scale-Up | Dedicated facilities in Boston and Houston secure supply chain control for lymphoma and leukemia protocols. |
| PMDA Sakigake Pathway Commitment | Early-phase asset filings in Japan create first-mover advantages through priority review frameworks. |
| Rural Infusion Network Expansion | Mobile cryogenic transport units extend CAR-T access beyond academic hubs into secondary United States markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases to establish baseline market sizing and growth trajectory assumptions. Primary interviews engaged drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across the United States, Germany, and Japan. Bottom-up patient-flow modeling and top-down revenue reconciliation triangulate volume and value estimates.
Segmentation dimensions modeled include product type, therapy area, end user, and treatment delivery mode across the projection horizon. Analytical framework incorporates administration route, patient population stratification, and regional regulatory cluster to capture precision medicine infrastructure variation. CAGRs derive from therapy-specific adoption curves and manufacturing capacity expansion schedules. Forecast inputs incorporate minimal residual disease monitoring penetration rates and biosimilar substitution assumptions.
Decision-makers should treat outputs as directional under stable regulatory approval timelines and payer reimbursement frameworks; material deviation would warrant model refresh. Revision becomes warranted when FDA accelerated approval revocation rates or EMA MDR compliance delays cross thresholds that alter commercialization velocity assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Apheresis Market
Hematology
Sickle Cell Disease Market
Hematology
Myelodysplastic Syndrome (MDS) Treatment Market
Hematology
Patient Blood Management Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Hematopoietic Agents Market
Hematology
Polycythemia Vera Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Haematocrit Centrifuge Market
Hematology
Single Blood Drop Analysis Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Non-Hodgkin Lymphoma Treatment Market