
 Hypereosinophilic Syndrome Market | 2026-2036
Hypereosinophilic Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Hypereosinophilic Syndrome Market Outlook
Market Dynamics
A capital-intensity divergence between large-cap biopharma and emerging biotech specialists is reorganizing competitive boundaries in hypereosinophilic syndrome therapeutics. GlaxoSmithKline plc leverages its respiratory and immunology infrastructure to sustain mepolizumab development across multiple eosinophilic indications. Bristol-Myers Squibb Company anchors its position through deep immunology expertise and existing biologic manufacturing networks. Knopp Biosciences LLC differentiates via targeted small-molecule discovery focused specifically on eosinophil biology.
Technical and Segment Landscape
Hypereosinophilic syndrome comprises a group of disorders characterized by persistent eosinophil counts exceeding 1.5 × 10⁹/L with associated organ damage, requiring therapies that deplete eosinophils or block interleukin-5 signaling pathways. The condition serves as a critical target for monoclonal antibody development and precision immunology platforms. Biologics command the dominant value share among product types due to their targeted mechanism and superior efficacy in steroid-refractory patients. Combination therapy approaches are expanding fastest within treatment modalities as clinicians seek to reduce corticosteroid burden. Hospitals retain the largest patient volume among end users, though specialty clinics are capturing higher-margin biologic administration as care shifts toward outpatient settings.
Regulatory Environment
FDA orphan drug incentives and EMA's Committee for Orphan Medicinal Products jointly accelerate clinical development timelines for hypereosinophilic syndrome therapies by granting protocol assistance and market exclusivity protections. The EU AI Act and FDA's evolving guidance on real-world evidence are reshaping how post-market efficacy data supports label expansion for biologics. Stakeholders must monitor how payer evidence requirements for rare disease biologics evolve alongside regulatory pathways, as reimbursement access increasingly determines commercial viability independent of approval status.
Market Dynamics
The hypereosinophilic syndrome market is being fundamentally restructured by the migration of biologic administration from inpatient infusion centers to outpatient specialty clinics, a shift that compresses reimbursement cycles and rewires distribution economics for eosinophil-targeted therapies.
Growth Catalysts
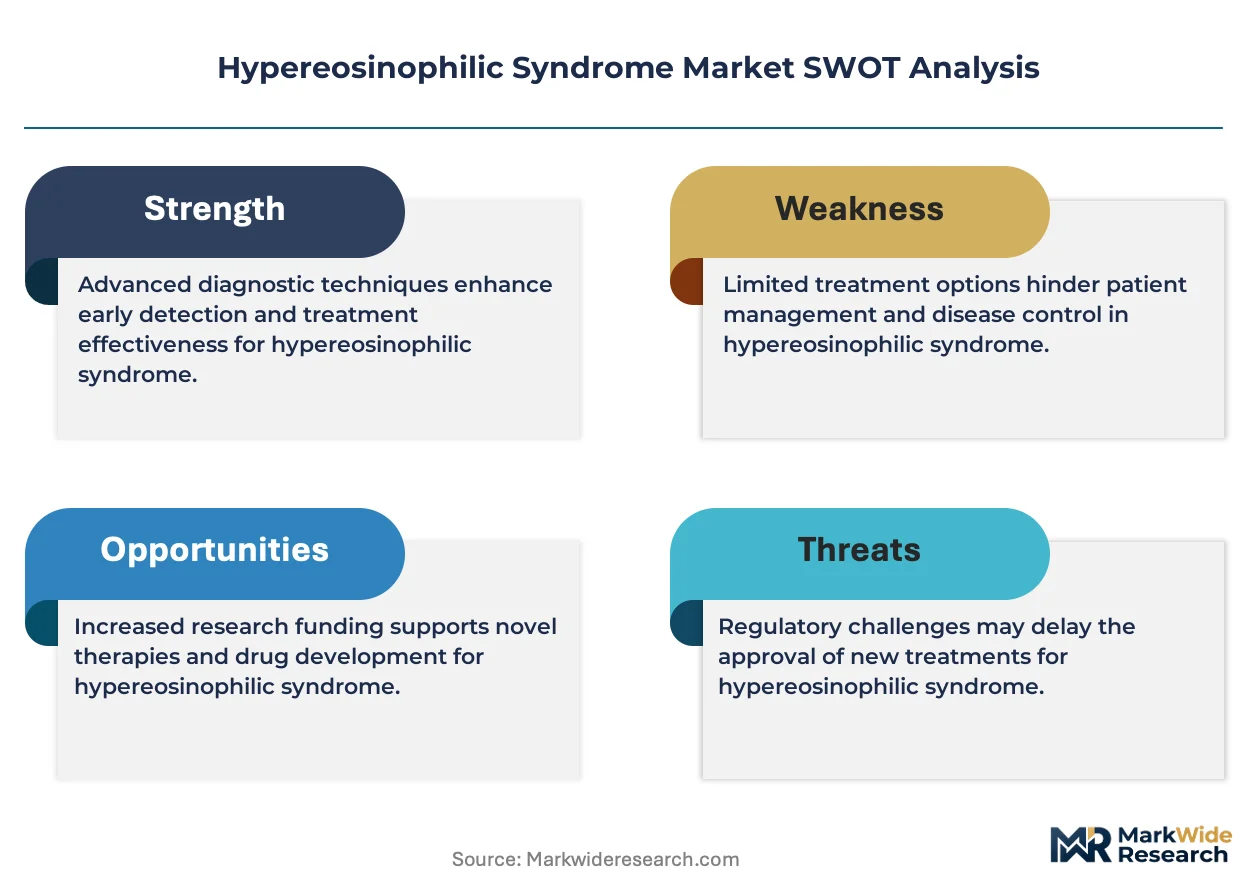
- FDA Orphan Drug Exclusivity:The seven-year market exclusivity provision accelerates clinical trial enrollment by de-risking development pipelines for sponsors targeting steroid-refractory patient populations.
- IL-5 pathway validation:Interleukin-5 signaling blockade has established durable clinical proof-of-concept, expanding prescriber confidence beyond corticosteroid-dependent protocols.
- Germany's AMNOG early benefit assessment:The structured HTA pathway for orphan diseases creates predictable reimbursement timelines that attract biologics manufacturers to prioritize European launch sequencing.
Market Restraints
- Cold-chain biologics distribution:Temperature-controlled logistics for monoclonal antibodies impose infrastructure requirements that exclude smaller hematology practices from biologic administration.
- Diagnostic coding fragmentation:The absence of a single ICD-10 code specific to hypereosinophilic syndrome complicates payer prior authorization and delays therapy initiation.
- Plasma-derived raw material concentration:Dependence on specialized bioreactor capacity in the United States and Ireland creates supply vulnerability for fusion protein manufacturing.
Strategic Opportunities
- Japan's Sakigake designation:The priority review pathway for regenerative medicines and biologics enables accelerated approval timelines for eosinophil-depleting therapies in Asia-Pacific's second-largest pharmaceutical market.
- Subcutaneous formulation development:Self-administration platforms for anti-IL-5 biologics open home-care channels that bypass hospital infusion center capacity constraints.
- Real-world evidence integration:FDA's guidance on RWE-supported label expansion creates post-market pathways to broaden indications beyond initial orphan approvals.
Industry Challenges
- Specialized immunology nursing shortage:Biologic administration requires trained infusion nursing that concentrates in major metropolitan academic medical centers, limiting geographic reach.
- Companion diagnostic co-development:The need for validated eosinophil biomarker assays synchronized with therapeutic trials extends regulatory timelines and increases capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypereosinophilic Syndrome Market |
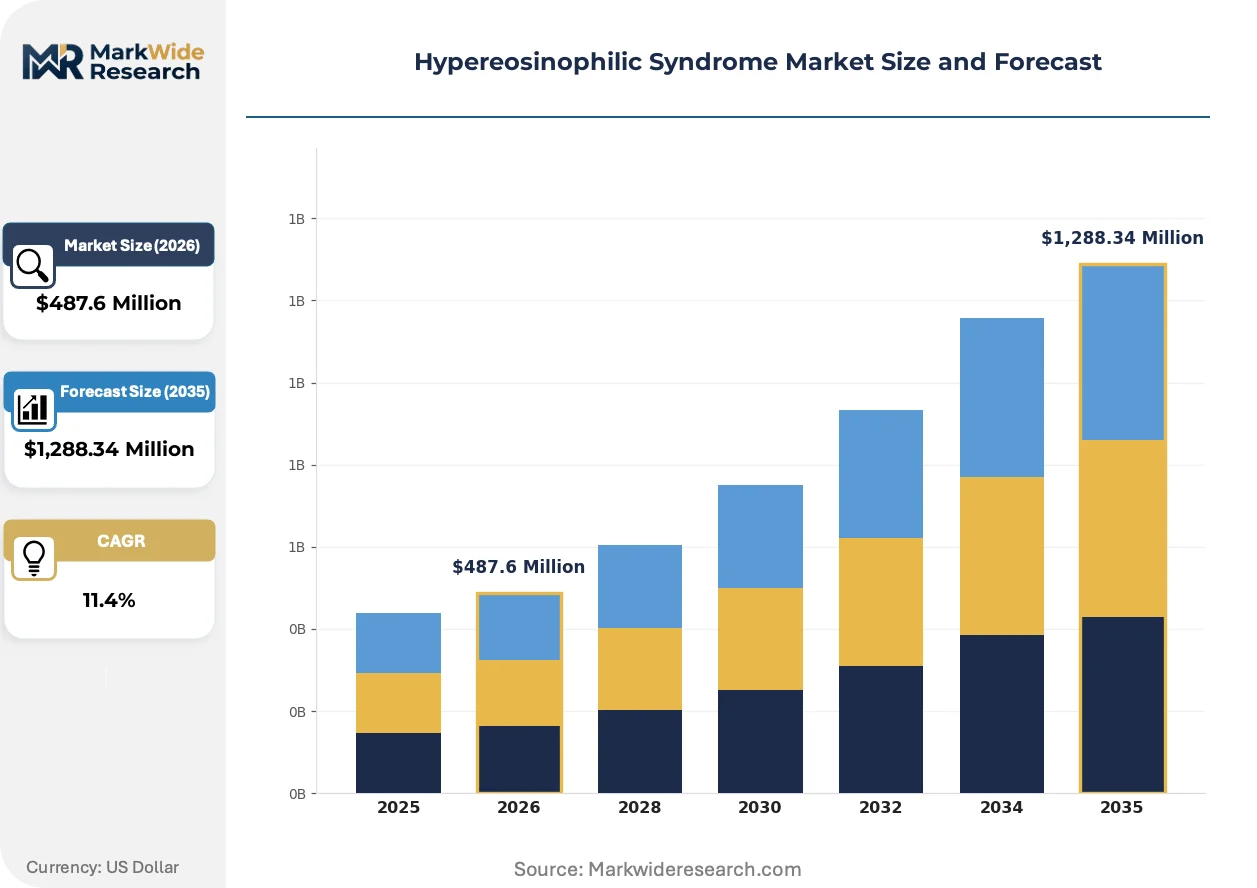
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Corticosteroids, Immunosuppressants, Targeted Therapies Treatment Approach: Monotherapy, Combination Therapy, Supportive Care, Maintenance Therapy End User: Hospitals, Specialty Clinics, Research Institutions, Home Care Administration Route: Oral, Subcutaneous, Intravenous, Inhalation |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Bristol-Myers Squibb Company, Novartis AG, Sanofi S.A., Teva Pharmaceutical Industries Ltd., Regeneron Pharmaceuticals Inc., F. Hoffmann-La Roche AG, Knopp Biosciences LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypereosinophilic Syndrome Market Strategic Shifts
Precision immunology platforms are actively fragmenting the treatment paradigm for eosinophil-driven disorders, creating parallel development tracks that compete for overlapping patient populations and prescriber mindshare.
Next-generation anti-IL-5 receptor antagonists are fragmenting the competitive landscape for steroid-sparing maintenance therapy. Hematology-oncology specialists at academic medical centers in Boston and Heidelberg are adopting these agents ahead of community-based rheumatologists. The technology is fragmenting prescriber hierarchies by enabling non-specialist physicians to manage previously complex eosinophil disorders without referral.
EMA's CSRD sustainability reporting requirements are mandating disclosure of clinical trial carbon footprints for orphan disease programs. Biopharma sponsors must now quantify and offset cold-chain logistics emissions across multi-center European studies. The regulation is compressing trial design choices, with sponsors consolidating site selection to reduce patient travel burden in Germany and the Netherlands.
Hospital procurement committees are unbundling biologic purchasing from bundled oncology contracts, creating standalone tender processes for eosinophil-targeted therapies. Specialty distributors are displacing traditional hospital pharmacy wholesalers in the United States as manufacturers seek direct relationships with infusion centers. The shift is most visible in Texas and Florida, where independent hematology clinics now account for the majority of new patient starts.
Hypereosinophilic Syndrome Market Segmentation
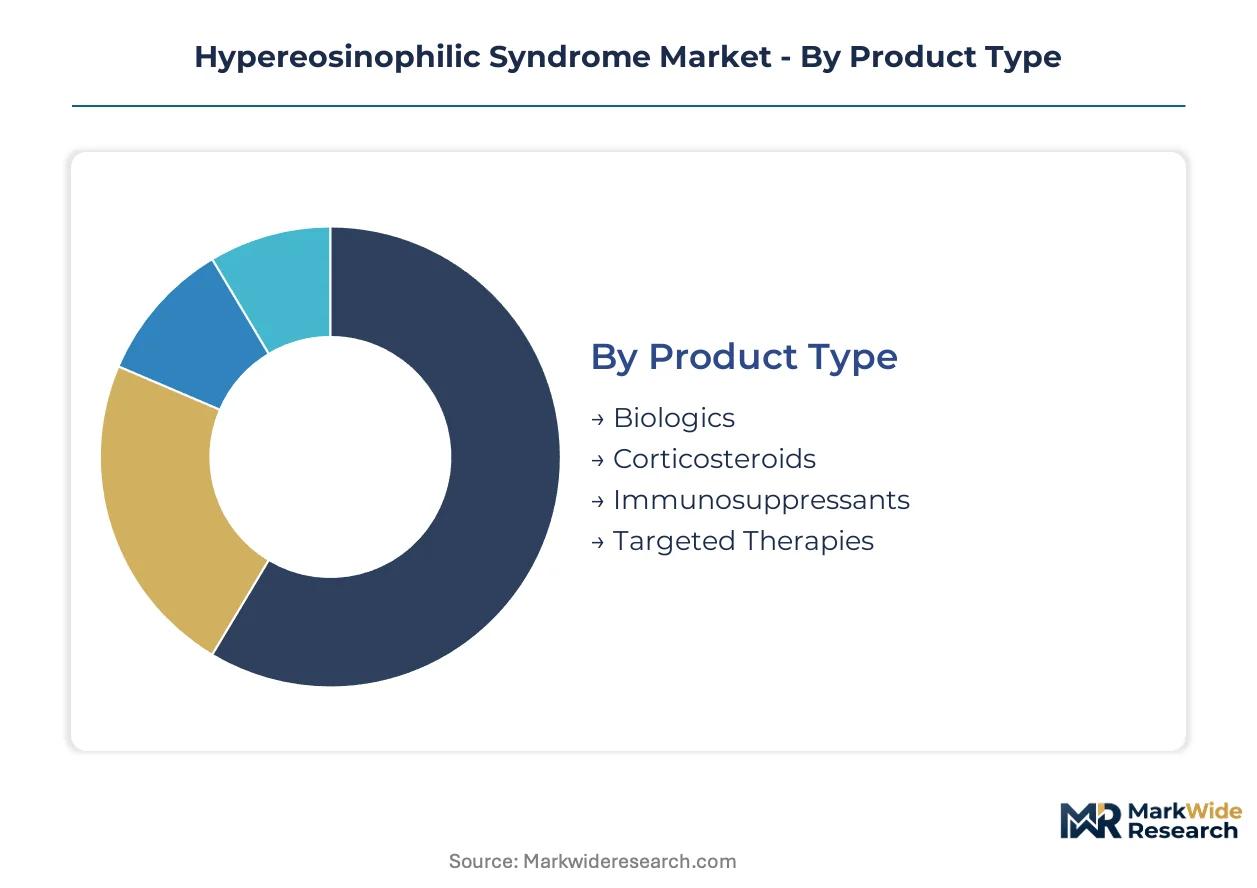
Segmentation in hypereosinophilic syndrome therapeutics reveals how regulatory pathways, reimbursement structures, and care delivery models reshape competitive positioning across product categories. Understanding these divides exposes where capital flows concentrate and which patient access channels offer sustainable margin profiles.
Product Type:
FDA orphan drug exclusivity and EMA's Committee for Orphan Medicinal Products create divergent commercialization timelines across molecular modalities, with biologics commanding premium pricing corridors unavailable to small-molecule alternatives.
- Biologics:Monoclonal antibodies and fusion proteins targeting IL-5 signaling dominate steroid-refractory patient management. Demand concentrates in United States academic medical centers and German university hospitals where hematology-oncology specialists administer intravenous formulations under REMS protocols.
- Corticosteroids:Systemic glucocorticoids remain first-line induction therapy despite toxicity limitations. Prescribing concentrates in community hospital emergency departments and Japanese general practice clinics where rapid eosinophil count reduction takes priority over long-term safety profiles.
- Immunosuppressants:Cyclosporine and hydroxyurea serve bridging therapy roles in resource-constrained settings.
- Targeted Therapies:Small-molecule kinase inhibitors address myeloproliferative variant subpopulations with specific molecular drivers.
Biologics handle the majority of throughput; targeted therapies are the fastest mover on share.
Treatment Approach:
Cost tier stratification separates acute intervention budgets from chronic maintenance contracts, with German sickness funds and US Medicare Advantage plans applying distinct prior authorization logic to each category.
- Monotherapy:Single-agent biologic protocols simplify reimbursement coding and reduce drug-drug interaction monitoring burdens. Adoption concentrates in United Kingdom NHS trusts and French hospital networks where formulary restriction policies favor streamlined prescribing pathways.
- Combination Therapy:Concurrent biologic-corticosteroid regimens enable steroid-sparing dose reduction. Demand clusters in Boston and Heidelberg academic centers where multidisciplinary eosinophil disorder clinics coordinate tapering protocols.
- Supportive Care:Symptom-directed interventions address organ-specific complications without modifying underlying eosinophilia.
- Maintenance Therapy:Long-term biologic administration prevents relapse in sustained remission patients.
Monotherapy handles the majority of throughput; combination therapy is expanding most quickly as clinicians seek corticosteroid burden reduction.
End User:
Volume distribution reflects site-of-care reimbursement differentials, with US hospital outpatient departments capturing facility fees unavailable to independent specialty clinics despite identical drug acquisition costs.
- Hospitals:Inpatient hematology services manage acute presentations with organ involvement and facilitate biologic infusions under supervision. Patient volume concentrates in Texas Medical Center and Mayo Clinic Rochester where dedicated eosinophil disorder programs attract complex referrals.
- Specialty Clinics:Outpatient immunology and allergy practices administer subcutaneous biologics with lower overhead structures. Growth concentrates in Florida independent hematology groups and Netherlands ambulatory care networks where infusion center capacity constraints drive site-of-care migration.
- Research Institutions:Academic medical centers with active clinical trial portfolios manage investigational therapy access.
- Home Care:Self-administration platforms for subcutaneous formulations bypass facility-based delivery entirely.
Hospitals handle the majority of throughput; specialty clinics are gaining share fastest as biologic administration migrates outpatient.
Administration Route:
Supply concentration in cold-chain logistics networks favors intravenous distribution through hospital-affiliated infusion centers, while subcutaneous formulation development enables channel bypass.
- Intravenous:Hospital-based infusion of monoclonal antibodies requires specialized nursing and adverse event monitoring infrastructure. Utilization concentrates in Dublin and Singapore tertiary centers where biologics manufacturing proximity reduces cold-chain failure risk.
- Subcutaneous:Prefilled syringe and autoinjector formats enable patient self-administration after initial supervised doses. Adoption accelerates in Japan community clinics and German physician practice associations where home-care reimbursement supports patient convenience.
- Oral:Corticosteroid and immunosuppressant tablets dominate induction therapy in primary care settings.
- Inhalation:Aerosolized corticosteroids address pulmonary eosinophilic manifestations without systemic exposure.
Intravenous handles the majority of throughput; subcutaneous is climbing the fastest as manufacturers prioritize patient-administered formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States prioritizes biologic maintenance therapy in outpatient settings, while Japan and Germany emphasize acute inpatient management with gradual steroid tapering protocols.
United States
Academic medical centers in Boston and Houston drive biologic adoption through dedicated eosinophil disorder programs. FDA orphan drug exclusivity accelerates clinical trial recruitment by de-risking development pipelines. Texas Medical Center and Mayo Clinic Rochester attract complex referrals from across North America.
Germany
University hospitals in Heidelberg and Munich anchor European demand for IL-5 pathway inhibitors through multidisciplinary eosinophil clinics. EMA's Committee for Orphan Medicinal Products grants protocol assistance that compresses regulatory timelines. Sickness funds in Bavaria and Baden-Württemberg apply structured HTA pathways that create predictable reimbursement for biologics.
Japan
Community hematology practices in Osaka and Nagoya favor corticosteroid induction followed by careful biologic transition. PMDA's Sakigake priority review pathway enables accelerated approval timelines for eosinophil-targeted therapies. Tokyo academic centers coordinate post-market surveillance for subcutaneous formulation safety.
United Kingdom
NHS trusts in London and Manchester restrict formulary access to streamlined monotherapy protocols. NICE technology appraisals apply cost-effectiveness thresholds that favor corticosteroid-sparing biologic regimens. Cambridge and Oxford research hospitals pioneer real-world evidence collection for label expansion.
Switzerland
University hospitals in Zurich and Geneva manage high-complexity cases with organ involvement through coordinated immunology-rheumatology services. Swissmedic grants expedited access pathways for rare disease biologics that lack full EU approval. Basel pharmaceutical clusters influence prescriber training across Alpine border regions.
Hypereosinophilic Syndrome Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in hypereosinophilic syndrome therapeutics. Large-cap biopharma commands biologic manufacturing infrastructure and respiratory-immunology sales networks that emerging developers cannot replicate. Three archetypes define competitive positioning: respiratory-diversified giants leveraging eosinophil biology expertise, immunology-focused mid-caps with biologic platforms, and targeted-discovery specialists concentrating on small-molecule eosinophil modulation. Consolidation pressures favor M&A activity around clinical-stage assets, while capacity expansion concentrates in United States and Irish bioreactor networks.
Among integrated biopharma leaders, GlaxoSmithKline plc and Bristol-Myers Squibb Company exemplify the respiratory-immunology diversified archetype, each occupying positions sustained by existing biologic manufacturing scale and specialty sales infrastructure. Knopp Biosciences LLC represents the targeted-discovery specialist tier, sitting within a narrower competitive space defined by focused small-molecule programs against eosinophil-specific pathways.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Regeneron Pharmaceuticals Inc. |
| F. Hoffmann-La Roche AG |
| Knopp Biosciences LLC |
| Others |
Value Chain & Pricing Dynamics
FDA orphan drug exclusivity and EMA's Committee for Orphan Medicinal Products jointly gate both supply qualification and price differentiation in hypereosinophilic syndrome therapeutics, creating dual-tier access where biologics manufacturers command premium corridors unavailable to small-molecule competitors while cold-chain logistics requirements exclude smaller hematology practices from participation.
Pricing Analysis
Long-term offtake contracts between biologics manufacturers and hospital systems dominate procurement, with subscription-based biologic administration agreements replacing transactional purchasing in United States academic medical centers. Price differentiation separates intravenous formulations requiring infusion center infrastructure from subcutaneous self-administration platforms, with German sickness funds and US Medicare Advantage plans applying distinct prior authorization logic to each tier. Cost compression in corticosteroid-dependent induction therapy is intensifying as clinicians seek steroid-sparing alternatives, though community hospital emergency departments remain most price-sensitive due to fixed reimbursement ceilings.
Supply Chain Analysis
The United States and Ireland anchor bioreactor capacity for monoclonal antibody production, with Singapore and Switzerland hosting secondary fill-finish operations for Asian and European distribution. Plasma-derived raw materials and specialized cell culture media feed from concentrated suppliers in North America and Western Europe, creating single-source vulnerability for fusion protein manufacturing. Tariff exposure on cold-chain logistics equipment runs through specialized distributors displacing traditional hospital pharmacy wholesalers, particularly in Texas and Florida where independent hematology clinics now capture majority patient starts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypereosinophilic syndrome therapeutics represents an early-cycle expansion story, with IL-5 pathway validation accelerating prescriber migration beyond corticosteroid-dependent protocols and creating multiple entry points for differentiated positioning.
For Market Incumbents: Compound manufacturing scale advantages through capacity expansion in Irish and Singaporean bioreactor networks to outpace emerging biotech specialists lacking comparable infrastructure. Defend against next-generation anti-IL-5 receptor antagonists by securing long-term offtake agreements with Texas Medical Center and Mayo Clinic Rochester referral hubs before non-specialist physicians gain confidence in independent management protocols. For New Entrants and Emerging Players: Differentiate on subcutaneous formulation development to bypass hospital infusion center capacity constraints and capture home-care reimbursement channels opening in Japan and Germany. Target Florida independent hematology groups and Netherlands ambulatory care networks as the most penetrable segments, leveraging direct relationships with specialty distributors to circumvent incumbent wholesaler lock-in. For Investors and Strategic Acquirers: Secondary-cycle assets sit with clinical-stage biotech specialists holding eosinophil-targeted small-molecule programs against myeloproliferative variant subpopulations. The five-to-ten year viability window favors acquisition targets with validated biomarker assays synchronized to therapeutic development, with the signal to watch being FDA guidance adoption on real-world evidence-supported label expansion pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administration platforms bypass hospital infusion capacity constraints in Texas and Florida. |
| Real-World Evidence Integration | FDA guidance adoption creates post-market pathways to broaden indications beyond initial orphan approvals. |
| Companion Diagnostic Co-Development | Validated eosinophil biomarker assays synchronize therapeutic trials and extend regulatory timelines. |
| Specialty Clinic Partnership Network | Direct relationships with independent hematology groups displace traditional hospital pharmacy wholesalers. |
| Cold-Chain Logistics Consolidation | Site consolidation in Germany and Netherlands reduces patient travel burden under EMA CSRD requirements. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure analysis triangulate market sizing across treatment modalities.
Sensitivity analysis on pricing assumptions and adoption curves shapes the analytical framework across the projection horizon, with segmentation dimensions covering product type, treatment approach, end user, and administration route. CAGRs derive from patient population epidemiology, biologic penetration rates in steroid-refractory cohorts, and regional regulatory cluster timelines.
The analysis sits within stated boundaries; outcomes outside sustained IL-5 pathway clinical validation or disrupted bioreactor supply would require recalibration. Recalibration cycles align with material shifts in FDA orphan drug incentive structures and EMA HTA pathway evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Neutropenia Treatment Market
Hematology
At-Home Hematology Testing Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Global Hematology Diagnostics Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Thrombocytopenia Treatment Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Patient Blood Management Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Graft vs Host Disease Market