
 Zonal Vehicle Control Unit Architectures Market | 2026-2036
Zonal Vehicle Control Unit Architectures Market Size, Share, and Industry Trends Forecast 2026-2036
Zonal Vehicle Control Unit Architectures Market Insights
A capital-intensity divergence between semiconductor-capable tier-1s and legacy wiring-harness suppliers is bifurcating competitive tiers in zonal architectures. Robert Bosch leverages in-house ASIC design and sensor portfolios to anchor full-domain controller offerings across European OEM programs. Continental competes through its server-based vehicle computer platforms, while NXP Semiconductors dominates automotive Ethernet switch silicon and S32 processing platforms that power zonal gateway consolidation.
Zonal vehicle control unit architectures partition vehicular electronic functions into geographically clustered domains—each managed by a local controller with deterministic Ethernet AVB backbones operating at 100Mbps to 10Gbps—reducing wiring weight and enabling over-the-air update granularity. The architecture type dimension shows hybrid configurations leading current OEM sourcing as transitional step-down from fully centralized compute, while distributed layouts retain share in commercial vehicle cost-optimized segments where retrofit compatibility dominates procurement criteria. Communication protocol selection increasingly concentrates on Ethernet AVB for backbone links, with CAN and LIN persisting as edge-node legacy interfaces where sensor-actuator cost sensitivity preserves incumbent bus technology.
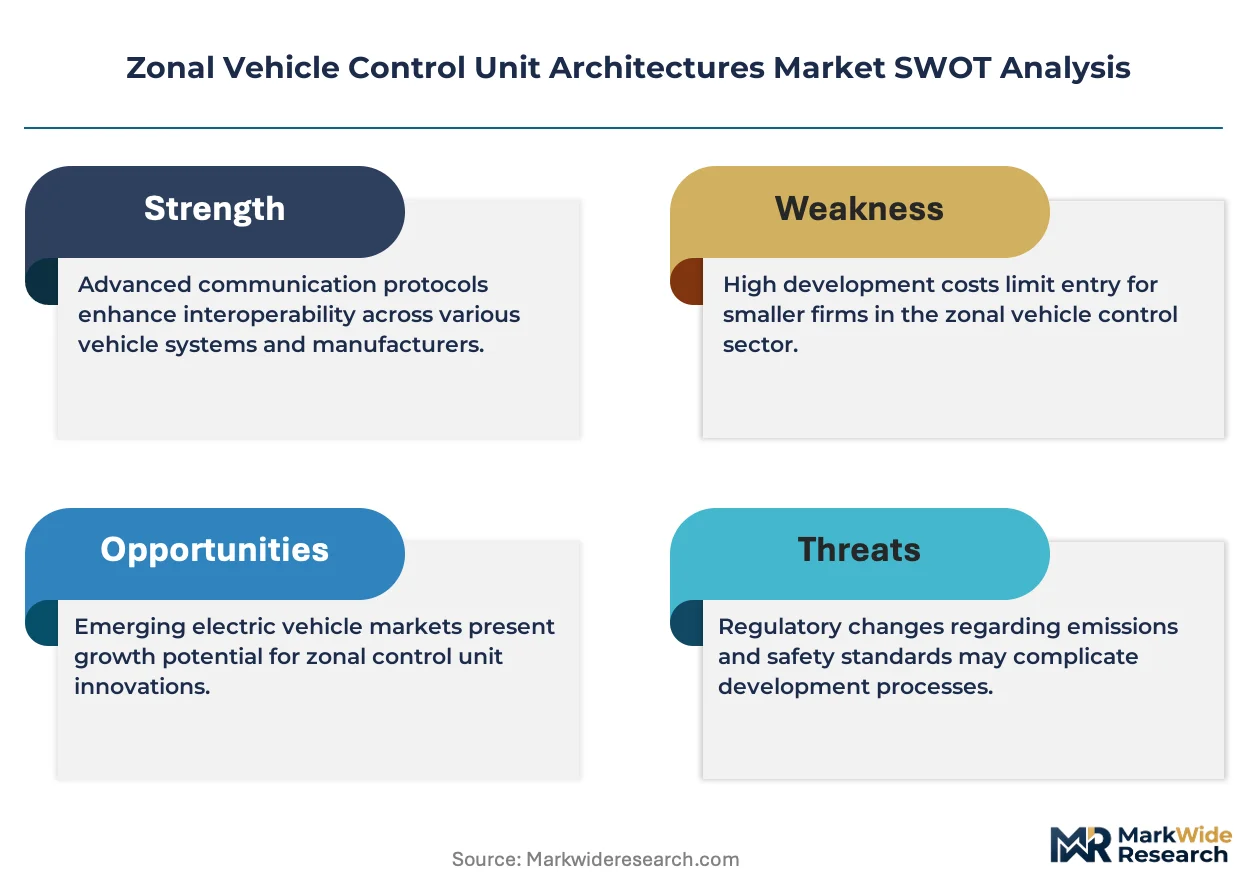
FDA vehicle cybersecurity guidance, EU Cybersecurity Act type-approval frameworks, and China's GB/T automotive network security standards collectively mandate encrypted zonal gateway authentication and intrusion detection as market-access preconditions. These regulatory architectures force OEMs to specify control units with hardware security modules and secure boot capabilities, eliminating non-compliant suppliers from platform bids. Stakeholders must monitor divergence between European UNECE WP.29 interpretation and China's SAMR enforcement timelines to align certification roadmaps with regional production commitments.
Market Dynamics
Centralized compute consolidation is compressing the traditional tiered supplier hierarchy in zonal architectures, as OEMs bypass legacy body electronics modules and source domain controllers directly from semiconductor-capable vendors.
Growth Catalysts
- EU Cybersecurity Act type-approval:Mandatory hardware security modules and encrypted gateway authentication create specification floors that eliminate non-compliant suppliers from European platform bids.
- Deterministic Ethernet AVB backbone:100Mbps to 10Gbps deterministic networking replaces legacy CAN/FlexRay for real-time control, reducing wiring harness weight while enabling granular over-the-air update partitioning.
- Premium battery-electric platforms:German and Chinese EV OEMs are mandating zonal layouts as base architecture for new dedicated BEV platforms, displacing distributed body electronics.
Market Restraints
- Automotive-grade silicon supply concentration:Foundry capacity for 16nm/7nm automotive SoCs concentrates among Taiwan-based contract manufacturers, exposing OEMs to geopolitical supply disruption.
- Legacy LIN/CAN sensor ecosystem lock-in:Cost-optimized edge nodes in commercial vehicle segments preserve incumbent bus technology, delaying full Ethernet migration.
- UNECE WP.29 certification timeline:Extended homologation cycles for cybersecurity management systems delay platform launches by 12-18 months versus conventional architectures.
Strategic Opportunities
- Commercial vehicle retrofit compatibility:Cost-optimized hybrid zonal configurations serve fleet operators requiring backward compatibility with existing trailer electronics and diagnostic tools.
- China GB/T network security standards:SAMR enforcement timelines for automotive intrusion detection create first-mover advantage for suppliers with pre-certified hardware security module designs.
- Sensor-actuator edge-node convergence:Integration of AI inference at zonal gateways enables predictive maintenance and occupancy detection without central compute dependency.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among German and Japanese tier-1s, constraining OEM internalization of zonal controller development.
- Legacy gateway software stack migration:Decades of proprietary CAN message databases and actuator calibration maps require costly re-architecture for Ethernet-native service-oriented communication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zonal Vehicle Control Unit Architectures Market |
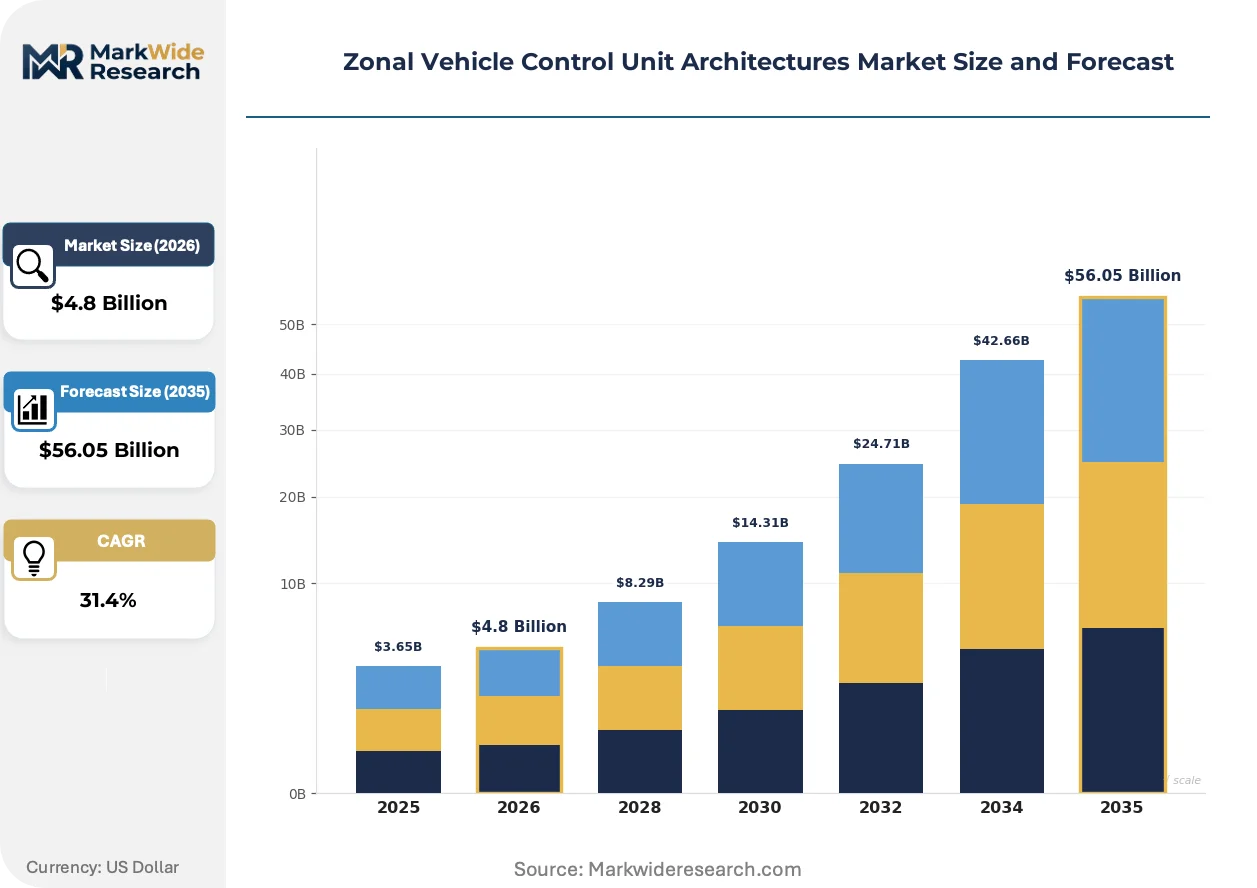
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $56.05 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Architecture Type: Centralized, Decentralized, Distributed, Hybrid Communication Protocol: CAN, FlexRay, Ethernet AVB, LIN, MOST Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles End User Segment: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Robert Bosch, Continental, Aptiv, Visteon, ZF Friedrichshafen, NXP Semiconductors, Valeo, Infineon Technologies, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zonal Vehicle Control Unit Architectures Market Trends and Innovations
Software-defined vehicle architectures are decoupling hardware refresh cycles from functional feature deployment, compressing traditional tier-1 development timelines and shifting value capture toward semiconductor and software vendors.
Domain controller consolidation is fragmenting the historical body electronics supply base. Tier-1s with captive ASIC design capability now capture zonal gateway and compute functions previously distributed across dozens of discrete ECUs. European premium OEMs are consolidating 70-100 body controllers into 4-6 zonal domains, eliminating intermediate tier-2 module suppliers from procurement chains.
REACH and RoHS material compliance mandates are constraining solder alloy and substrate material selection for high-density zonal controllers. Automotive Ethernet PHY silicon suppliers are accelerating halogen-free PCB qualification to maintain European market access. German OEMs are prioritizing suppliers with pre-certified green material stacks in platform sourcing decisions.
Buyer concentration among dedicated BEV platform teams is displacing traditional commodity purchasing. OEMs are forming direct engineering relationships with NXP, Renesas, and Infineon for S32 and R-Car processor roadmaps, bypassing historical tier-1 mediation for compute silicon selection. This pattern is most pronounced in China, where NIO, XPeng, and Li Auto maintain direct semiconductor vendor contracts for zonal gateway silicon.
Zonal Vehicle Control Unit Architectures Market Segmentation
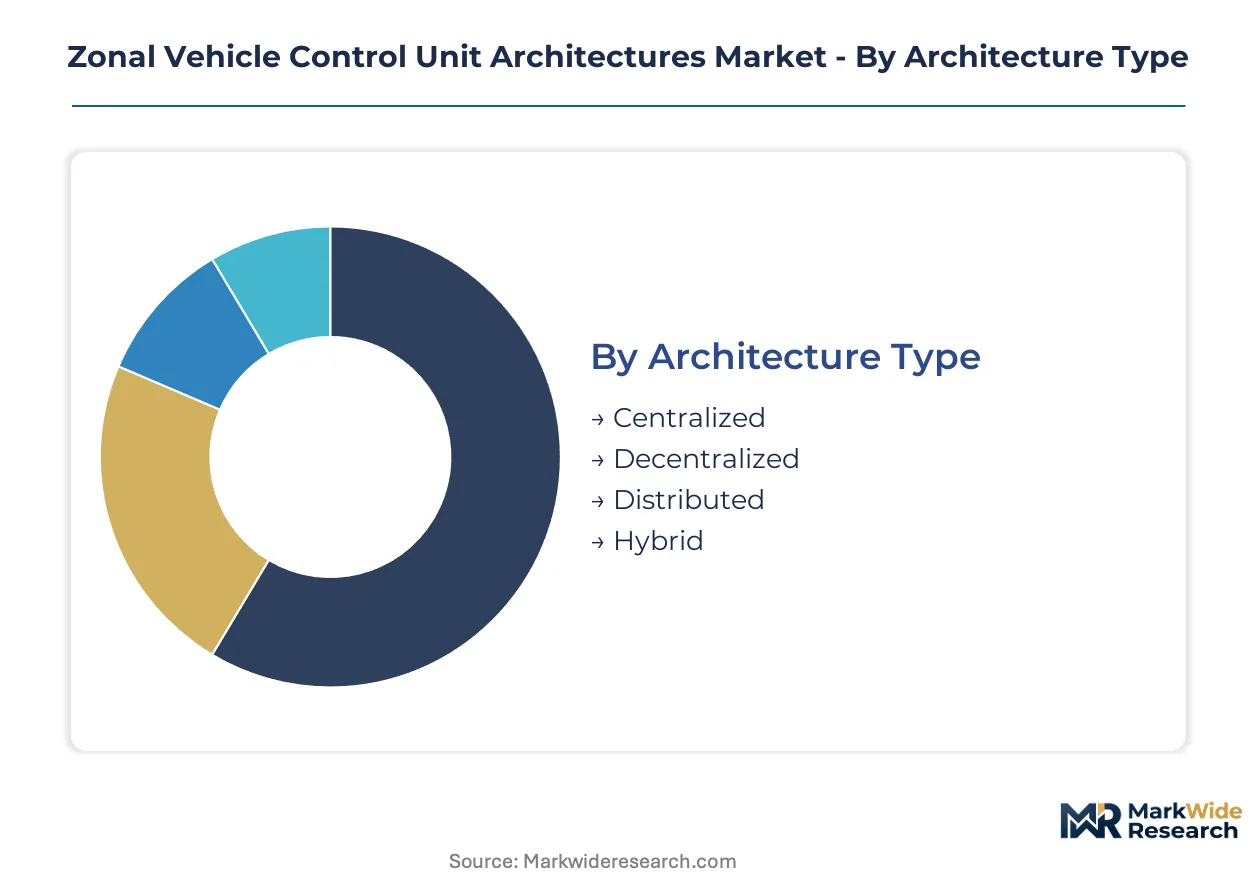
Zonal architectures fragment across multiple technical and commercial dimensions, each segment carrying distinct margin profiles and supplier qualification barriers. Procurement teams structure sourcing decisions around architecture maturity, protocol compatibility, and vehicle platform electrification roadmaps.
Architecture Type:
Margin pools concentrate in hybrid configurations where transitional engineering services command premium pricing during OEM platform migrations.
- Centralized:Consolidates all domain functions into high-performance vehicle computers with deterministic Ethernet backbones. German premium EV OEMs mandate this layout for dedicated BEV platforms, displacing legacy body electronics modules and capturing software-defined vehicle value upstream.
- Hybrid:Blends zonal gateways with retained distributed nodes for retrofit compatibility and cost-optimized commercial vehicle segments. Fleet operators in North America and Europe prioritize this architecture to preserve existing trailer electronics and diagnostic tool investments during platform transitions.
- Decentralized:Distributes compute across functional domains without full centralization. Japanese OEMs favor this approach for hybrid powertrain platforms requiring legacy system preservation.
- Distributed:Retains traditional ECU proliferation for cost-sensitive segments. Commercial vehicle manufacturers in India and Brazil specify this architecture where wiring harness weight reduction delivers insufficient total-cost-of-ownership benefit.
The dominant share belongs to hybrid configurations, while centralized architectures are closing the gap fastest as dedicated BEV platforms proliferate.
Communication Protocol:
Protocol selection directly determines semiconductor content value and supplier qualification complexity across OEM programs.
- Ethernet AVB:Enables 100Mbps to 10Gbps deterministic networking for real-time control and over-the-air update partitioning. European OEMs specify this for backbone links in premium platforms, with NXP and Broadcom silicon dominating gateway designs.
- CAN:Persists as edge-node interface where sensor-actuator cost sensitivity preserves incumbent bus technology. Commercial vehicle powertrain and chassis domains in Germany and China retain CAN for legacy actuator compatibility.
- LIN:Serves low-bandwidth body electronics such as door modules and climate controls. Cost-optimized passenger car segments in India and Southeast Asia specify LIN for seat and mirror actuators.
- FlexRay:Retains niche presence in chassis control systems requiring deterministic timing. German OEMs specify FlexRay for brake-by-wire and steer-by-wire domains pending Ethernet TSN maturation.
- MOST:Declining share in infotainment networking as Ethernet AVB displaces optical fiber for bandwidth and cost reasons. Japanese premium OEMs represent residual demand for existing platform continuity.
Ethernet AVB commands the dominant revenue position, with CAN maintaining volume leadership in unit shipments.
Vehicle Type:
Platform electrification mandates are restructuring procurement authority toward dedicated BEV engineering teams.
- Electric Vehicles:Dedicated BEV platforms in Germany and China mandate zonal architectures as base design, with centralized compute domains replacing distributed body electronics. NIO, XPeng, and Li Auto specify direct semiconductor vendor contracts for gateway silicon.
- Passenger Cars:Internal combustion and hybrid platforms drive hybrid zonal adoption as transitional step-down from full centralization. European premium OEMs consolidate 70-100 body controllers into 4-6 zonal domains.
- Commercial Vehicles:Cost-optimized segments preserve distributed layouts where retrofit compatibility dominates fleet procurement criteria. North American heavy-duty truck manufacturers prioritize backward compatibility with existing trailer electronics.
- Autonomous Vehicles:Redundant zonal gateways with ASIL-D functional safety certification support sensor fusion and fail-operational requirements. Robotaxi developers in California and Arizona specify deterministic Ethernet for lidar and camera data aggregation.
Electric vehicles hold the dominant share, while autonomous vehicle applications are expanding most quickly on safety-critical redundancy requirements.
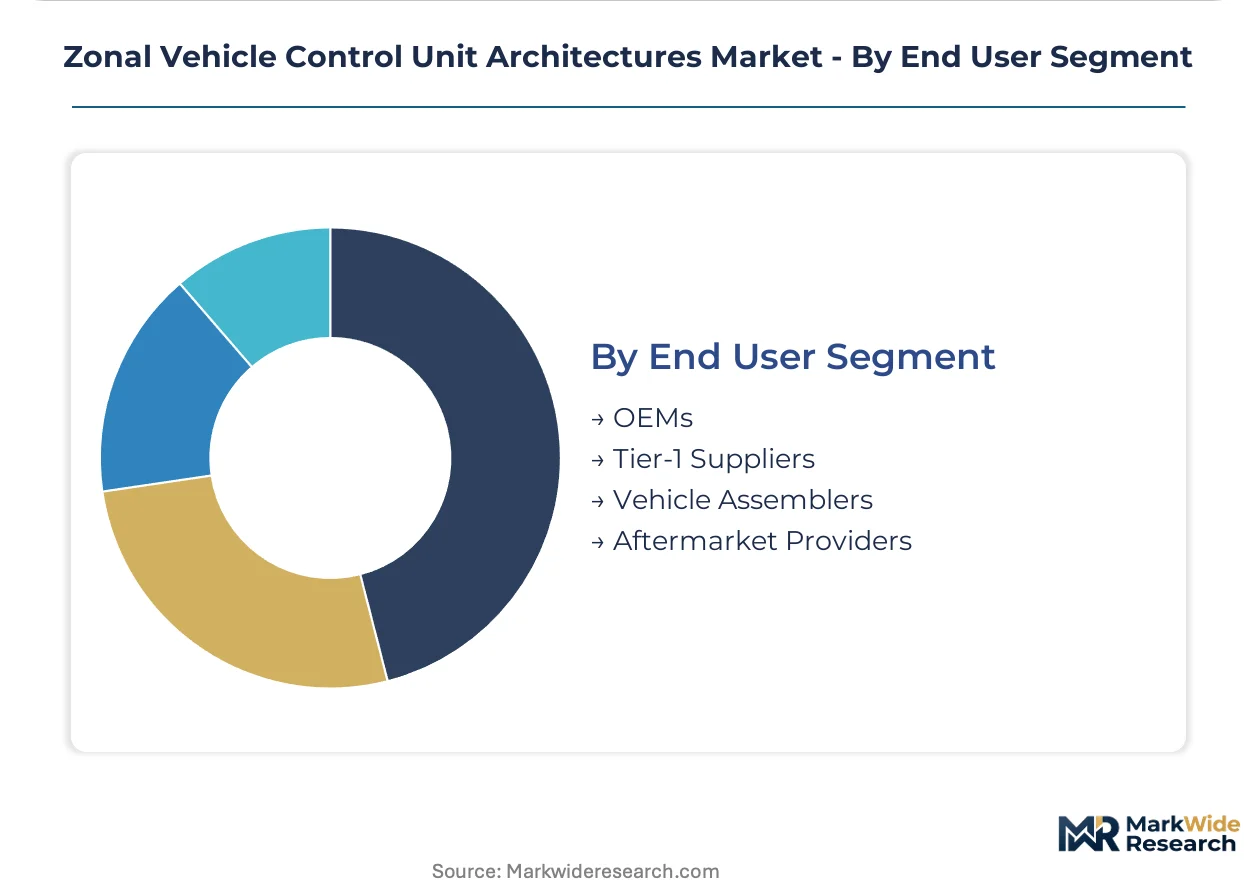
End User Segment:
Customer type determines contract structure, with OEM direct sourcing displacing traditional tier-1 mediation for compute-intensive domains.
- OEMs:German and Chinese EV manufacturers internalize zonal controller specification and source domain controllers directly from semiconductor-capable vendors. Direct engineering relationships with NXP, Renesas, and Infineon bypass historical tier-1 mediation.
- Tier-1 Suppliers:Robert Bosch and Continental anchor full-domain controller offerings through captive ASIC design and server-based vehicle computer platforms. Functional safety engineer scarcity concentrates ISO 26262 ASIL-D expertise among German and Japanese tier-1s.
- Vehicle Assemblers:Contract manufacturers in China and Mexico integrate pre-certified zonal modules from approved supplier lists. Procurement concentrates on module-level qualification rather than silicon selection.
- Aftermarket Providers:Diagnostic tool compatibility and legacy gateway software stack migration services address fleet retrofit requirements. European commercial vehicle operators demand backward compatibility with existing CAN message databases.
OEMs capture the dominant procurement volume, with tier-1 suppliers defending position fastest through captive semiconductor design capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German tier-1s commanding premium engineering rates, while Chinese OEMs extract cost advantages through direct semiconductor procurement. This asymmetry shapes regional sourcing patterns across zonal architecture deployment.
Germany
Premium EV platforms from BMW and Mercedes-Benz mandate centralized zonal layouts with ASIL-D functional safety certification. KBA enforcement of UNECE WP.29 cybersecurity regulations requires hardware security modules in all gateway controllers. Stuttgart and Munich engineering clusters host captive ASIC design centers for Robert Bosch and Continental.
China
NIO, XPeng, and Li Auto specify direct contracts with NXP and Renesas for S32 gateway silicon, bypassing traditional tier-1 mediation. SAMR's GB/T vehicle network security standards mandate encrypted intrusion detection systems by enforcement timelines. Shanghai and Shenzhen electronics corridors concentrate zonal controller manufacturing for domestic EV platforms.
United States
Robotaxi developers in California and Arizona specify redundant zonal gateways for lidar data aggregation with deterministic Ethernet backbones. NHTSA pending guidance on automated driving system cybersecurity influences OEM pre-certification strategies. Silicon Valley semiconductor design houses anchor partnerships with Detroit automakers on domain controller roadmaps.
Japan
Toyota and Honda favor decentralized architectures preserving legacy hybrid powertrain compatibility during platform transitions. METI standardization efforts for automotive Ethernet TSN target 2026 implementation for chassis-by-wire domains. Nagoya and Tokyo engineering centers concentrate ISO 26262 functional safety expertise among tier-1 suppliers.
South Korea
Hyundai and Kia integrate zonal gateways into dedicated E-GMP platforms with 800V electrical architectures. MFDS alignment with UNECE WP.29 timelines accelerates cybersecurity management system certification for export markets. Seoul Capital Area semiconductor packaging facilities supply automotive-grade Ethernet PHY modules.
Zonal Vehicle Control Unit Architectures Market Competitive Landscape
Concentration sits with diversified tier-1s possessing captive semiconductor design capability. The supplier base compresses into two tiers: integrated domain controller vendors capturing gateway and compute functions, and legacy wiring-harness specialists facing displacement. Three archetypes dominate—ASIC-capable tier-1s, automotive semiconductor pure-plays, and server-based vehicle computer platforms. Competitive moves center on backward integration into silicon design and strategic partnerships with foundry capacity holders.
Among diversified tier-1s, Robert Bosch and Continental exemplify the integrated domain controller archetype through server-based vehicle computer platforms and in-house design resources. NXP Semiconductors occupies a position as the automotive semiconductor pure-play anchoring S32 processing platforms and Ethernet switch silicon for gateway consolidation. These three represent the competitive core where value capture shifts from module assembly to semiconductor and software content.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| Aptiv |
| Visteon |
| ZF Friedrichshafen |
| NXP Semiconductors |
| Valeo |
| Infineon Technologies |
| Qualcomm |
| Others |
Pricing and Supply Chain Analysis
Ethernet AVB backbone substitution for legacy CAN/FlexRay wiring simultaneously shifts semiconductor sourcing toward Taiwan-based foundries and compresses tier-1 module margins as silicon content captures value upstream. German OEMs now specify gateway controllers with 10Gbps deterministic networking, forcing suppliers to absorb ASIC design costs or exit platform bids.
Pricing Analysis
The customization-premium spread between ASIL-D certified zonal gateways and standard body controllers now exceeds three-to-one, with functional safety certification and hardware security modules as primary price differentiation drivers. Pricing pressure stems from Chinese EV OEMs extracting volume discounts through direct semiconductor procurement contracts. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while German premium OEMs prioritize deterministic performance over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites 70 percent of automotive-grade Ethernet PHY silicon movement from Taiwan and South Korea to European assembly plants. The zonal controller supply chain draws from 16nm/7nm automotive SoC foundry capacity concentrated in Taiwan, AEC-Q100 qualified passive components from Japan, and halogen-free PCB substrates from South Korea. Single-source vulnerability in advanced node semiconductor fabrication exposes OEMs to geopolitical disruption. Distribution runs through approved tier-1 module suppliers with direct OEM engineering relationships bypassing traditional harness specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zonal architectures represent a platform-economics inflection where Ethernet-native service-oriented communication displaces decades of proprietary CAN message databases, with interoperability standards now determining supplier viability.
For Market Incumbents: Consolidate captive ASIC design capability and ISO 26262 ASIL-D certification expertise to defend against semiconductor pure-plays capturing gateway silicon margins. Prioritize backward integration into automotive Ethernet PHY design and secure multi-year foundry capacity reservations. Eliminate non-core body electronics module assembly to free engineering resources for domain controller development. For New Entrants and Emerging Players: Legacy gateway software stack migration services present a service-layer gap where incumbents under-serve fleet operators requiring CAN database backward compatibility. Target North American heavy-duty truck retrofit segments with hybrid zonal configurations preserving trailer electronics investments. Pursue direct engineering contracts with Chinese EV startups bypassing established tier-1 mediation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive semiconductor packaging specialists in South Korea and Malaysia possessing AEC-Q100 qualification infrastructure. Long-term viability hinges on 5-10 year foundry access agreements and pre-certification against evolving UNECE WP.29 cybersecurity mandates. Monitor SAMR enforcement timelines for GB/T intrusion detection standards as inflection indicator for hardware security module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Capability Acquisition | Captive silicon design secures NXP and Broadcom-independent gateway controller roadmaps for German OEM programs. |
| Automotive Ethernet TSN Pre-Certification | METI-aligned 2026 chassis-by-wire standards position suppliers for Toyota and Honda platform transitions. |
| Hardware Security Module Integration | EU Cybersecurity Act compliance eliminates non-encrypted gateway suppliers from European platform bids. |
| Foundry Capacity Reservation Agreements | Taiwan-based 7nm automotive node access insulates against supply disruption for centralized compute domains. |
| Legacy CAN Migration Services | Commercial vehicle fleet operators pay premium engineering rates for diagnostic tool backward compatibility preservation. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 domain controller procurement leads, automotive semiconductor application specialists, and commercial vehicle fleet maintenance directors anchored the qualitative base. Primary interview insights combined with secondary validation from UNECE WP.29 regulatory filings, SAMR GB/T standard drafts, SEC 10-K automotive segment disclosures, and IHS Markit vehicle production databases. Bottom-up zonal controller unit economics triangulated against top-down OEM platform electrification roadmaps.
Sensitivity analysis tested forecast outputs against variable adoption rates for centralized versus hybrid architectures across the projection horizon. Segmentation dimensions modeled include architecture type, communication protocol tier, vehicle electrification class, and regional regulatory cluster. CAGRs derived from unit shipment trajectories weighted by semiconductor content value per controller. Industry-specific inputs incorporated foundry capacity expansion schedules and cybersecurity certification timeline uncertainty.
Underlying assumptions cover sustained Taiwan-based foundry access, stable UNECE WP.29 interpretation across KBA and MFDS jurisdictions, and Chinese EV platform volume commitments, with deviation risk concentrated in geopolitical semiconductor supply disruption and extended ASIL-D homologation cycles. Practitioners should keep alternative scenarios live as SAMR enforcement timelines and EPA automotive cybersecurity guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Autonomous Taxi Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
North America Autonomous Navigation Market