
 Heavy-Truck Composite Component Market | 2026-2036
Heavy-Truck Composite Component Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Truck Composite Component Market Foresight
Multi-material design architecture is fragmenting traditional monocoque steel construction across heavy-truck platforms. KB Components leverages advanced compression molding capabilities to supply structural floor panels to European OEM assembly lines. Continental Structural Plastics anchors North American demand through integrated thermoplastic manufacturing for Class 8 sleeper cab applications. Wabash National Corporation differentiates its refrigerated trailer portfolio with proprietary composite panel systems that reduce tare weight.
Heavy-truck composite components integrate fiber-reinforced polymer matrices—typically E-glass or carbon fiber embedded in epoxy, vinyl ester, or thermoplastic resins—fabricated through resin infusion or compression molding to achieve strength-to-weight ratios exceeding steel by thirty to fifty percent. Floor panels dominate current volume throughput due to standardized dimensions across OEM platforms, while carbon fiber reinforcements command premium positioning in high-stress chassis nodes where fatigue resistance justifies material cost. Compression molding leads manufacturing stage adoption for high-volume body panel production, whereas prepreg layup sustains niche demand in low-rate aerodynamic fairing programs.
EPA greenhouse-gas emission standards for medium- and heavy-duty vehicles directly mandate mass reduction pathways that elevate composite component specification rates in US truck builds. EU CO2 emission performance standards for heavy-duty vehicles, enforced through the European Commission's regulatory framework, impose fleet-average penalties that accelerate OEM material substitution timelines. NHTSA safety regulations governing roof crush and underride protection simultaneously shape composite structural design parameters for cab and sleeper applications. Stakeholders must monitor evolving lifecycle assessment methodologies that may recalibrate the carbon-accounting advantage of glass fiber versus recycled steel in forthcoming regulatory revisions.
Market Dynamics
Multi-material chassis architectures are fragmenting monocoque steel construction across heavy-truck platforms as EPA and EU CO2 mandates harden fuel-efficiency requirements into procurement specifications.
Growth Catalysts
- EPA Greenhouse-Gas Standards:US medium- and heavy-duty vehicle emission rules mandate mass reduction pathways that elevate composite specification rates in domestic truck builds.
- Carbon Fiber Reinforcement:High-stress chassis nodes increasingly specify carbon fiber for fatigue resistance where material cost is justified by durability gains.
- German Fleet Procurement:Long-haul operators in Germany anchor European composite demand through integrated supply partnerships with major OEM assembly networks.
Market Restraints
- Resin Input Volatility:Epoxy and vinyl ester resin prices fluctuate with petrochemical feedstock costs, compressing margin predictability for compression molding suppliers.
- Carbon Fiber Supply Concentration:High-modulus fiber production concentrates among limited precursor manufacturers, creating bottleneck risk for premium chassis applications.
- Recycled Steel Substitution:Lifecycle assessment methodologies may recalibrate carbon-accounting advantages in favor of recycled steel for forthcoming regulatory revisions.
Strategic Opportunities
- Refrigerated Trailer Applications:Composite panel systems reduce tare weight in temperature-controlled freight, opening specification pathways beyond dry van segments.
- Thermoplastic Resin Convergence:Advanced thermoplastic matrices combined with automated fiber placement enable recyclable structural components with production cycle advantages.
- EU Green Deal Procurement Incentives:Fleet decarbonization subsidies accelerate material substitution timelines for operators meeting CO2 performance benchmarks.
Industry Challenges
- Compression Molding Talent Scarcity:Tool design and process engineering expertise for high-volume composite production lags OEM demand expansion.
- NHTSA Certification Timelines:Roof crush and underride protection testing protocols extend validation cycles for new cab and sleeper structural designs.
- Legacy Steel Integration:Mixed-material joining technologies require capital-intensive equipment upgrades at assembly plants transitioning from all-steel platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Truck Composite Component Market |
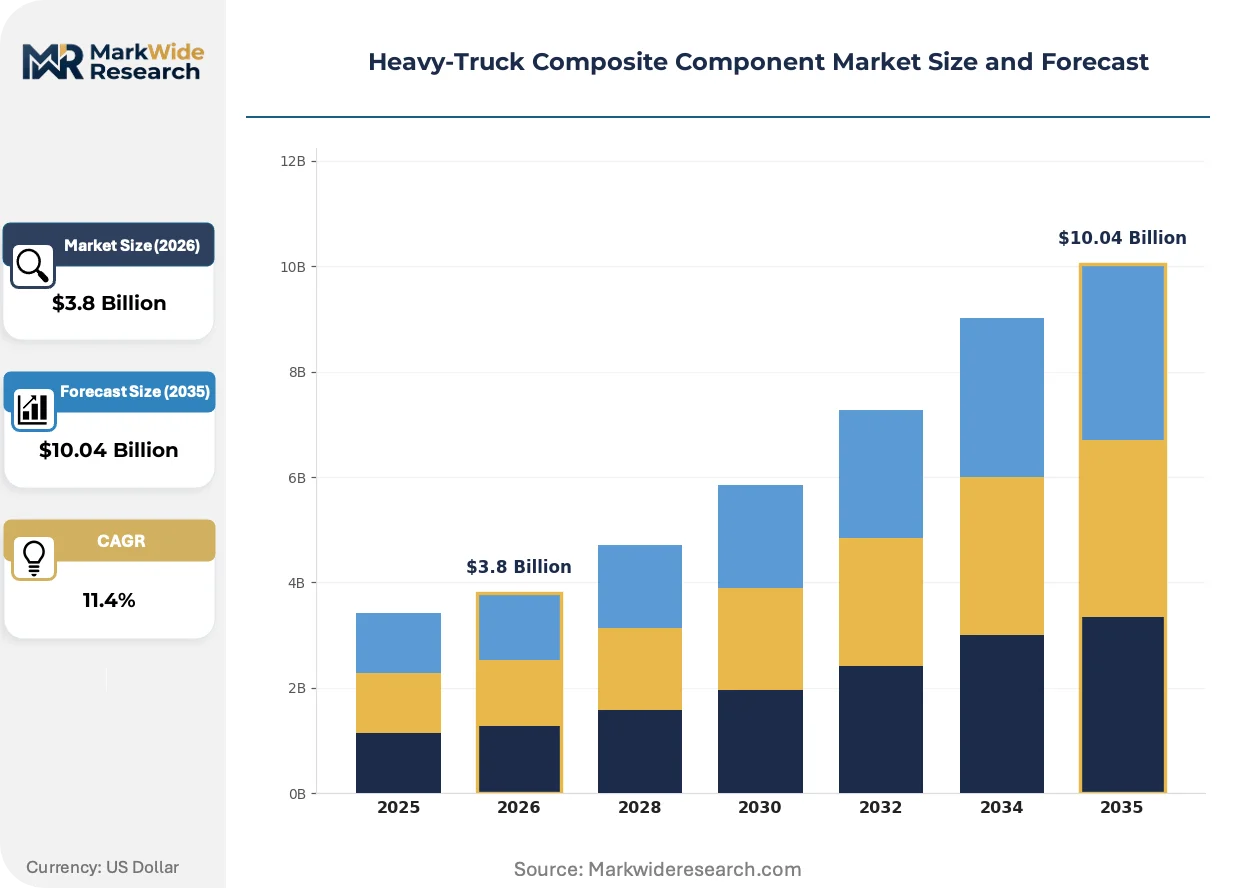
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Panels, Body Panels, Reinforcements, Doors Manufacturing Stage: Prepreg Layup, Resin Infusion, Vacuum Bagging, Compression Molding Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Thermoplastic End User: OEMs, Aftermarket Providers, Fleet Operators, Commercial Transport |
| Companies Covered | KB Components, Pagna Composites, Continental Structural Plastics, MW Industries, Bolwell Corporation, Creative Composites, Wabash National Corporation, Utility Trailer Manufacturing Company, MFG Composite Systems Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Truck Composite Component Market Shifts & Advancements
Process automation and material science advances are compressing production cycle times while regulatory tightening rewrites specification standards across OEM engineering departments.
Thermoplastic compression molding is collapsing the cost differential between composite and steel body panels for Class 8 sleeper cab applications. Fleet procurement teams at North American long-haul operators now specify thermoplastic floor panels as standard equipment rather than premium upgrades. This shift is collapsing traditional material selection hierarchies that previously reserved composites for aerodynamic fairings and non-structural components.
EU CO2 emission performance standards for heavy-duty vehicles impose fleet-average penalties that accelerate OEM material substitution timelines. The European Commission's regulatory framework directly ties compliance costs to vehicle mass, forcing engineering departments to redesign chassis nodes with fiber-reinforced alternatives. German OEMs face the steepest penalty structures and have responded with the most aggressive composite integration programs.
Buyer concentration among mega-fleet operators is consolidating procurement leverage and demanding outcome-based durability guarantees rather than material specifications. Large-scale logistics providers now contract directly with Tier-2 composite suppliers for sleeper cab retrofits, bypassing traditional OEM parts distribution. This pattern is most visible in US Midwest freight corridors where thousand-unit fleet operators negotiate multi-year panel supply agreements independent of vehicle purchase cycles.
Heavy-Truck Composite Component Market Segmentation
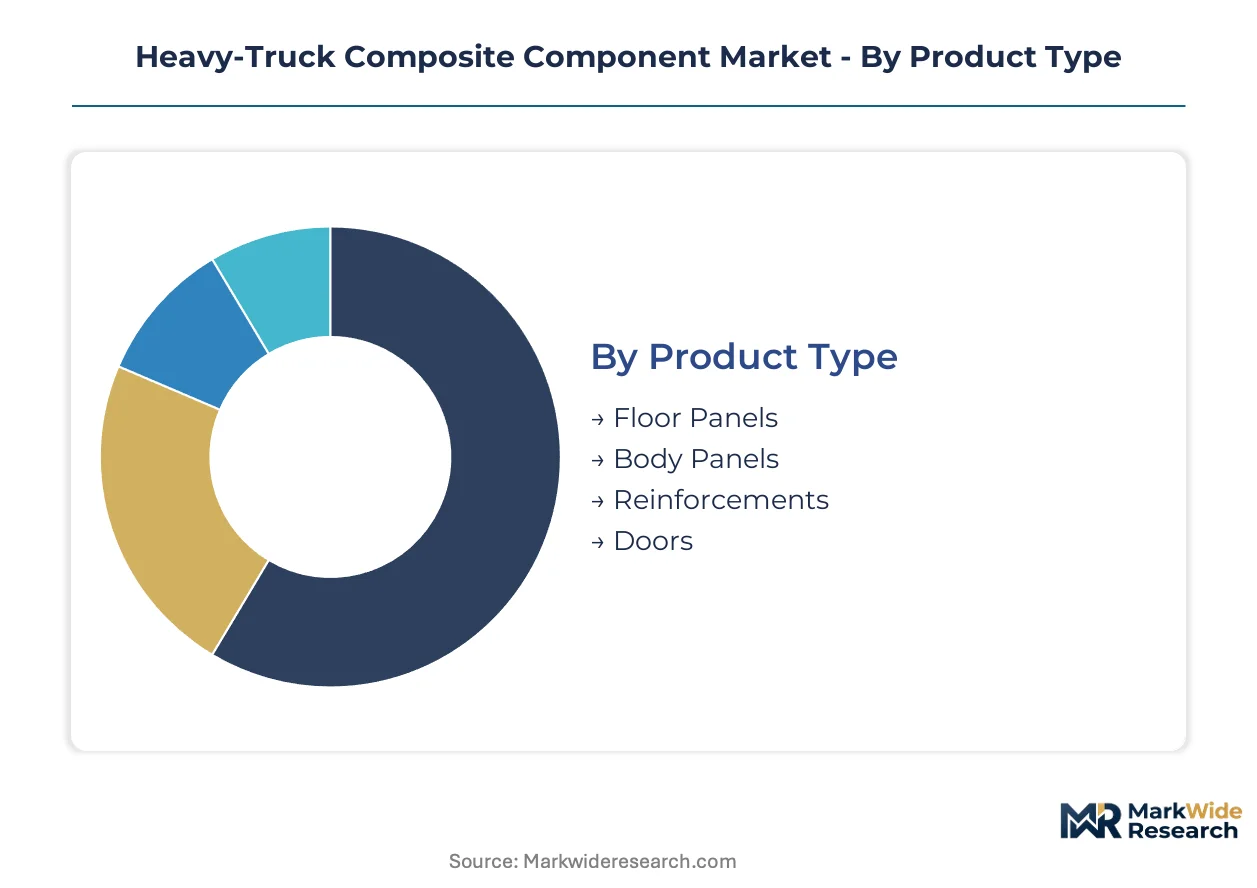
Heavy-truck composite component procurement fragments across four distinct classification axes. Product type and manufacturing stage hierarchies determine specification economics, while material selection and end-user channel dynamics reshape competitive positioning across OEM and aftermarket value chains.
Product Type:
Mature structural applications dominate current volume, with emerging aerodynamic and reinforcement segments capturing specification momentum in next-generation platform designs.
- Floor Panels:E-glass reinforced thermoplastic matrices achieve standardized load-bearing specifications across Class 8 sleeper cab architectures. Demand concentrates at Daimler Truck and MAN Truck & Bus assembly lines in Germany, where EPA and EU CO2 mandates compress material substitution timelines for fleet compliance.
- Body Panels:Compression-molded structural skins replace steel in hood, fender, and side fairing applications, achieving thirty to fifty percent weight reduction versus conventional metal stampings. North American long-haul fleet procurement now specifies these as standard equipment rather than premium upgrades, collapsing traditional material hierarchies.
- Reinforcements:Carbon fiber chassis nodes address high-stress fatigue zones in frame rail and suspension mounting points.
- Doors:Modular composite door assemblies integrate side-impact beams with thermoplastic outer skins for cab applications.
Floor Panels handles the majority of throughput; Reinforcements is expanding most quickly on specification share.
Manufacturing Stage:
Cost tier stratification separates high-volume automated processes from precision-intensive low-rate fabrication methods serving niche aerodynamic programs.
- Compression Molding:Automated thermoplastic processing enables sub-three-minute cycle times for body panel production at Continental Structural Plastics facilities. KB Components leverages this method for European OEM floor panel supply, where resin input volatility from petrochemical feedstock fluctuations compresses margin predictability.
- Resin Infusion:Vacuum-assisted resin transfer molding produces large-format structural components with void-free fiber wet-out for refrigerated trailer side walls. Wabash National Corporation specifies this process for proprietary panel systems that reduce tare weight in temperature-controlled freight segments.
- Prepreg Layup:Hand-laid carbon fiber prepregs serve low-rate aerodynamic fairing programs requiring complex curvature control.
- Vacuum Bagging:Atmospheric pressure consolidation of wet layup laminates sustains prototype and repair channel demand.
Compression Molding commands the production volume; Resin Infusion is gaining share fastest in trailer specification pathways.
Material:
Application-driven performance requirements fragment selection between structural stiffness, impact resistance, and recyclability mandates across OEM engineering departments.
- Glass Fiber:E-glass roving in vinyl ester or epoxy matrices dominates floor and body panel applications, delivering strength-to-weight ratios exceeding steel at commodity-grade pricing. German fleet procurement anchors European demand through integrated supply partnerships with major OEM assembly networks.
- Carbon Fiber:High-modulus PAN-based precursors command premium positioning in chassis nodes and structural reinforcements where fatigue resistance justifies material cost. Supply concentrates among limited precursor manufacturers, creating bottleneck risk for premium applications.
- Aramid Fiber:Kevlar and Twaron reinforcements address ballistic and abrasion-resistant components in military and severe-service truck variants.
- Thermoplastic:Polypropylene and polyamide matrices enable recyclable structural components with automated fiber placement compatibility.
Glass Fiber carries the volume base; Thermoplastic is climbing the fastest on sustainability-driven specification.
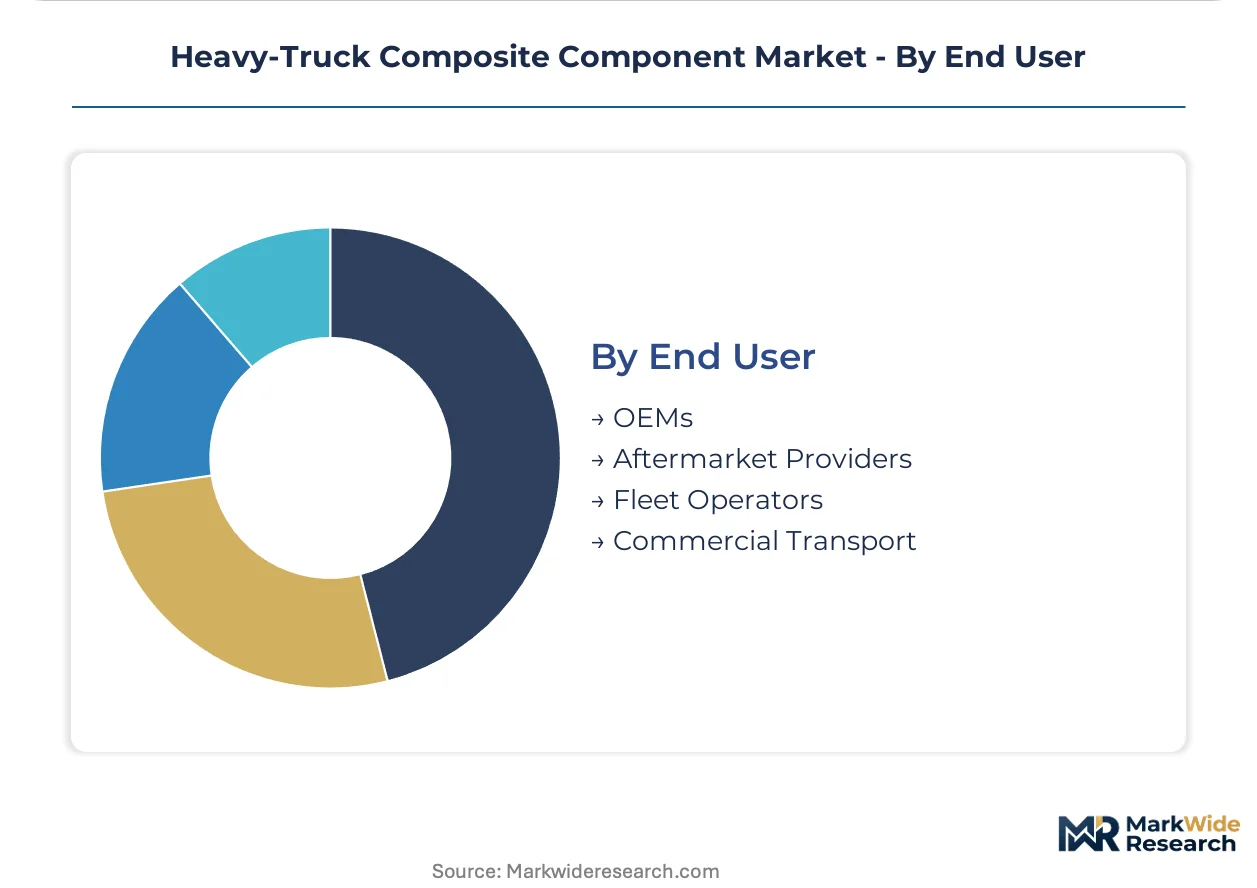
End User:
Customer type concentration consolidates procurement leverage among mega-fleet operators demanding outcome-based durability guarantees rather than material specifications.
- OEMs:Daimler Truck, MAN Truck & Bus, and Wabash National integrate composite components at original assembly, specifying multi-material chassis architectures that fragment monocoque steel construction. NHTSA roof crush and underride protection testing protocols extend validation cycles for new cab structural designs.
- Fleet Operators:Thousand-unit logistics providers in US Midwest freight corridors negotiate multi-year panel supply agreements independent of vehicle purchase cycles, bypassing traditional OEM parts distribution. Mega-fleet procurement leverage demands outcome-based durability guarantees.
- Aftermarket Providers:Sleeper cab retrofit specialists serve owner-operator segments with aerodynamic fairing upgrade kits.
- Commercial Transport:Refrigerated and dry van trailer lessors specify composite floor systems for weight-sensitive freight optimization.
OEMs retain the specification authority; Fleet Operators are capturing procurement autonomy fastest through direct Tier-2 contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German composite component exports flow primarily into North American long-haul fleet procurement channels, while Chinese material suppliers feed Asian OEM assembly networks expanding across Southeast Asian manufacturing corridors.
United States
Long-haul fleet operators in the Midwest freight corridor specify composite floor panels as standard equipment for fuel efficiency compliance. EPA greenhouse-gas standards for medium- and heavy-duty vehicles mandate mass reduction pathways that elevate composite specification rates. Detroit-Warren manufacturing cluster anchors North American thermoplastic compression molding capacity for Class 8 sleeper cab applications.
Germany
Daimler Truck and MAN Truck & Bus anchor European composite adoption through integrated supply partnerships with Tier-2 fabricators. EU CO2 emission performance standards impose fleet-average penalties that accelerate OEM material substitution timelines. Stuttgart manufacturing basin concentrates high-modulus carbon fiber chassis node production for premium heavy-duty platforms.
China
Domestic heavy-truck OEMs specify glass fiber reinforced thermoplastic matrices for cost-sensitive fleet procurement in long-distance logistics. MIIT fuel consumption regulations for heavy-duty commercial vehicles drive material lightweighting requirements. Yangtze River Delta industrial corridor hosts expanding compression molding capacity serving both domestic builds and export assembly networks.
Japan
Precision-oriented truck manufacturers specify carbon fiber reinforcements for high-stress chassis nodes requiring fatigue resistance. METI energy efficiency standards for commercial vehicles elevate composite specification in next-generation platform designs. Nagoya industrial zone sustains prepreg layup capabilities for low-rate aerodynamic fairing programs serving premium export markets.
Canada
Cross-border supply chains integrate Canadian resin compounders with US Midwest assembly operations for just-in-time panel delivery. Environment and Climate Change Canada emission regulations align with EPA mandates, creating harmonized procurement specifications. Ontario manufacturing corridor hosts thermoplastic matrix production facilities supplying Detroit-Warren OEM assembly lines.
Heavy-Truck Composite Component Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base organizes around three strategic archetypes: integrated Tier-1 suppliers commanding OEM direct relationships, specialized composite fabricators serving aftermarket retrofit channels, and material-agnostic distributors consolidating procurement leverage. Dominant competitive moves include backward integration into resin compounding operations and geographic expansion through licensing agreements with regional molders.
Among North American integrated suppliers, Continental Structural Plastics and Wabash National Corporation exemplify the channel-control archetype through captive OEM specification pathways. KB Components represents the European product-specialist model, anchoring regional supply partnerships with German OEM assembly networks. These three entities occupy distinct competitive positions without overlapping core market access strategies.
| Leading Market Players |
|---|
| KB Components |
| Pagna Composites |
| Continental Structural Plastics |
| MW Industries |
| Bolwell Corporation |
| Creative Composites |
| Wabash National Corporation |
| Utility Trailer Manufacturing Company |
| MFG Composite Systems Company |
| Others |
Supply & Pricing Matrix
German carbon fiber precursor manufacturers anchor upstream supply concentration, directing margin capture toward chassis node fabricators serving Daimler Truck and MAN assembly networks while compressing margin pools for commodity E-glass panel suppliers.
Pricing Analysis
Prior-generation thermoplastic floor panels, current-generation carbon fiber reinforcements, and next-generation recyclable thermoplastic matrices stratify across three performance tiers. Contract-based long-term offtake agreements dominate, with price differentiation driven by certification grade and volume scale. Cost compression in E-glass segments intensifies because petrochemical resin feedstock volatility erodes supplier margins. Fleet operators exhibit highest price sensitivity for standardized floor panels, while OEM engineering departments show lowest sensitivity for fatigue-critical chassis nodes.
Supply Chain Analysis
Extended payment terms from German OEMs to Tier-2 fabricators compress working capital cycles across European supplier networks. Manufacturing concentrates in Germany, China, and the United States, with raw material dependencies on PAN-based carbon fiber precursors, epoxy and vinyl ester resins, and E-glass roving. Single-source vulnerability in high-modulus carbon fiber production creates structural risk for premium chassis applications. Distribution runs through captive OEM supply agreements and direct mega-fleet contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-material chassis fragmentation creates white-space opportunities as procurement autonomy shifts from OEM specification departments toward direct fleet operator contracting with Tier-2 composite fabricators.
For Market Incumbents: Pre-empt margin erosion in standardized floor panels by securing backward integration into thermoplastic resin compounding operations. Anchor capacity expansion in the Detroit-Warren manufacturing cluster to capture North American long-haul fleet procurement. Defend against emerging Chinese compression molding suppliers by accelerating NHTSA certification timelines for next-generation cab structures. For New Entrants and Emerging Players: Establish a beachhead in refrigerated trailer composite panel systems, where Wabash National's proprietary position has not yet consolidated specification authority. Target direct contracting with thousand-unit fleet operators in US Midwest freight corridors, bypassing traditional OEM parts distribution. Lead with outcome-based durability guarantees rather than material specifications to differentiate from incumbent Tier-1 suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European automotive component suppliers holding captive relationships with German OEM assembly networks. Long-term viability hinges on exposure to EU CO2 compliance cost structures and the durability of direct fleet contracting relationships. Watch for inflection in lifecycle assessment methodologies that may recalibrate carbon-accounting advantages toward recycled steel alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of thermoplastic matrices insulates margin pools from petrochemical feedstock volatility. |
| Direct Fleet Operator Contracting | Bypassing OEM parts distribution captures procurement autonomy shifting toward mega-fleet logistics providers. |
| NHTSA Certification Acceleration | Compressed validation cycles for roof crush and underride protection testing defend against emerging Asian suppliers. |
| Refrigerated Trailer Panel Expansion | Temperature-controlled freight segments offer specification pathways beyond consolidated dry van markets. |
| Carbon Fiber Precursor Supply Agreements | Long-term offtake contracts with limited high-modulus fiber manufacturers mitigate single-source bottleneck risk. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-2 supplier production data anchors the qualitative findings. Primary interviews with composite fabrication plant managers, heavy-truck OEM procurement leads, fleet operator maintenance directors, and resin compounder technical R&D directors combined with secondary validation from EPA regulatory filings, EU Commission CO2 performance standard documentation, SEC 10-K disclosures from listed suppliers, and vehicle production databases. Bottom-up panel shipment data and top-down OEM build projections were triangulated to establish volume baselines.
Calibration against historical substitution rates for steel-to-composite material transitions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, manufacturing stage, fiber material, resin matrix, and end-user channel. CAGRs were derived from elasticity-adjusted demand curves incorporating fuel price sensitivity and regulatory penalty structures. Industry-specific forecast inputs include EPA greenhouse-gas standard phase-in schedules and EU fleet-average CO2 compliance cost trajectories.
Stress conditions across resin input cost volatility, carbon fiber supply disruption, and recycled steel lifecycle assessment recalibration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and OEM platform redesign cycles. Macroeconomic contraction, unilateral tariff imposition, or breakthrough steel recycling technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Poly Trucks Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market