
 Truck Diagnostic Market | 2026-2036
Truck Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Diagnostic Market Insights
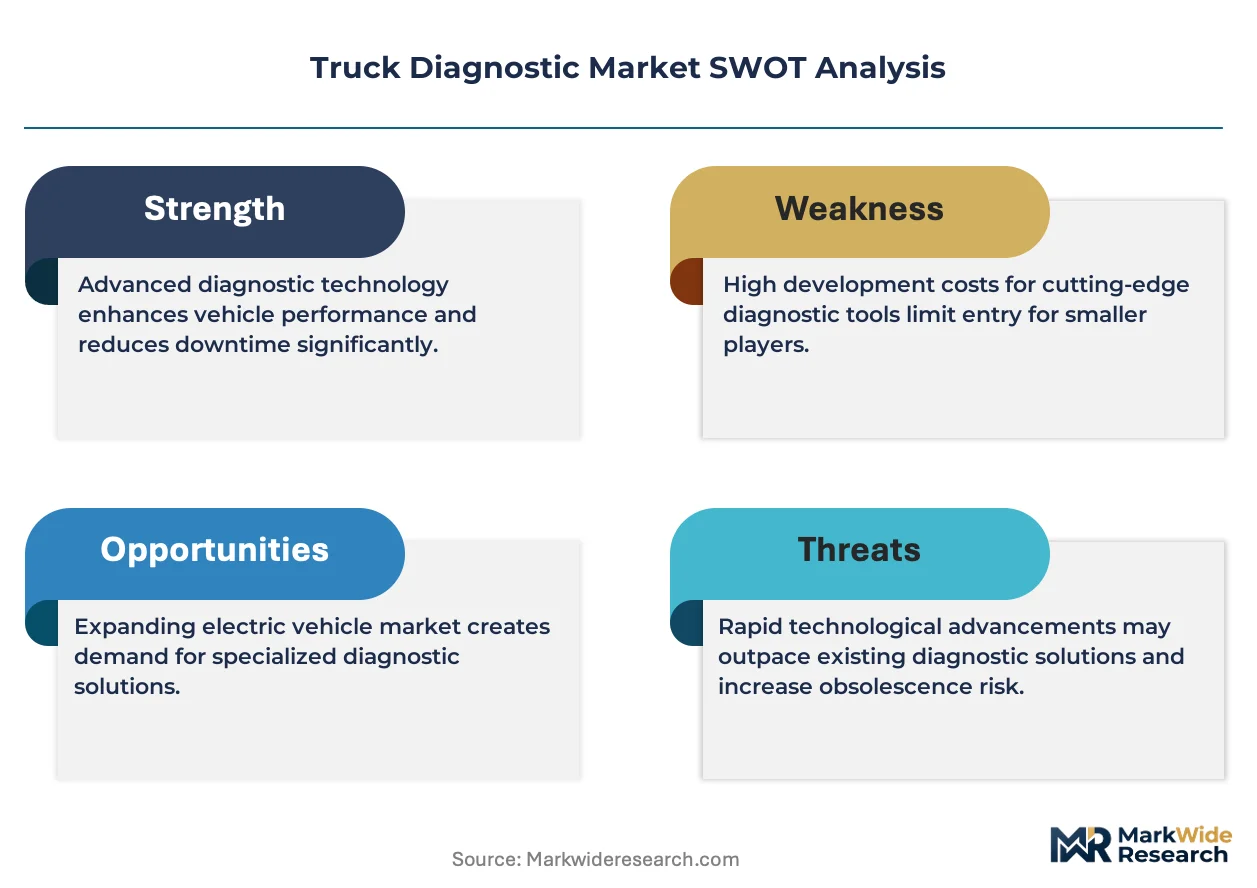
The truck diagnostic equipment landscape is rebalancing between premium OEM-integrated systems and commodity aftermarket scanners. Robert Bosch GmbH leverages its embedded control unit expertise to dominate factory-installed diagnostic architectures. Snap-on Incorporated sustains brand loyalty among independent repair shops through proprietary software ecosystems. Autel Intelligent Technology Corp., Ltd competes aggressively on price while extending feature parity in heavy-duty protocol coverage.
Truck diagnostic systems comprise electronic hardware interfaces, proprietary software platforms, and sensor networks that extract fault codes, monitor powertrain performance, and log emissions data from commercial vehicle electronic control modules. These systems typically operate across SAE J1939 and J1708 communication protocols to interface with engine, transmission, and aftertreatment controllers, serving the essential commercial purpose of minimizing unplanned downtime and ensuring regulatory compliance. Hardware segments anchor current revenue pools through recurring replacement cycles, while telematics and AI technology categories are capturing the fastest expansion as fleets shift from reactive to condition-based maintenance models. Cloud computing infrastructure within diagnostic platforms is concentrating margin pools among vendors controlling data aggregation and remote calibration capabilities.
The EPA enforces OBD-II and HD-OBD mandates that dictate minimum diagnostic capability for vehicles operating in the United States, directly shaping product development roadmaps and certification requirements. California's Air Resources Board imposes supplementary heavy-duty inspection and maintenance rules that exceed federal baselines, creating a bifurcated compliance environment. Stakeholders must monitor how emerging cybersecurity standards from NHTSA reshape remote diagnostic access protocols and data governance obligations.
Market Dynamics
Fleet operators are compressing maintenance cycles as EPA Phase 3 greenhouse gas standards force earlier adoption of predictive diagnostic systems. The collision between regulatory mandates and uptime requirements is restructuring procurement priorities across commercial vehicle operations.
Growth Catalysts
- Telematics Integration:Cloud-connected diagnostic platforms enable real-time fault monitoring across distributed fleets. Heavy-duty operators in the United States are prioritizing remote calibration capabilities to minimize roadside failures.
- EPA HD-OBD Mandates:Federal emissions enforcement requires standardized diagnostic reporting for heavy-duty vehicles. This compels retrofit investments among aging fleet assets to maintain operating authority.
- Condition-Based Maintenance:Sensor networks tracking powertrain degradation shift repair scheduling from mileage intervals to actual component health. Fleets report measurable reductions in unplanned downtime.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries control critical chip fabrication for diagnostic interface hardware. Geographic concentration creates procurement vulnerability during supply disruptions.
- Proprietary Protocol Lock-In:OEM-specific diagnostic architectures fragment aftermarket scanner compatibility. Independent repair shops face escalating software licensing costs to maintain coverage breadth.
- Skilled Technician Scarcity:Advanced diagnostic systems require expertise in SAE J1939 networking and aftertreatment electronics. Vocational training pipelines have not kept pace with system complexity.
Strategic Opportunities
- Electric Powertrain Diagnostics:Battery management system monitoring and thermal runaway detection represent unmet capability gaps. Early movers in high-voltage safety protocols capture fleet electrification budgets.
- California CARB Supremacy:State-level inspection rules exceeding federal baselines create premium product tiers. Vendors certifying to California Air Resources Board standards access price-insensitive compliance demand.
- AI-Augmented Fault Prediction:Machine learning models trained on aggregated telematics datasets identify failure patterns invisible to rule-based systems. Cloud infrastructure providers control margin-rich data aggregation layers.
Industry Challenges
- Multi-Protocol Integration Complexity:Fleets operate mixed-vintage assets communicating across J1708, J1939, and emerging CAN FD standards. Diagnostic platforms must maintain backward compatibility without performance degradation.
- Cybersecurity Certification Timelines:NHTSA emerging standards for remote diagnostic access impose encryption and authentication requirements. Product development cycles extend to accommodate third-party security validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Diagnostic Market |
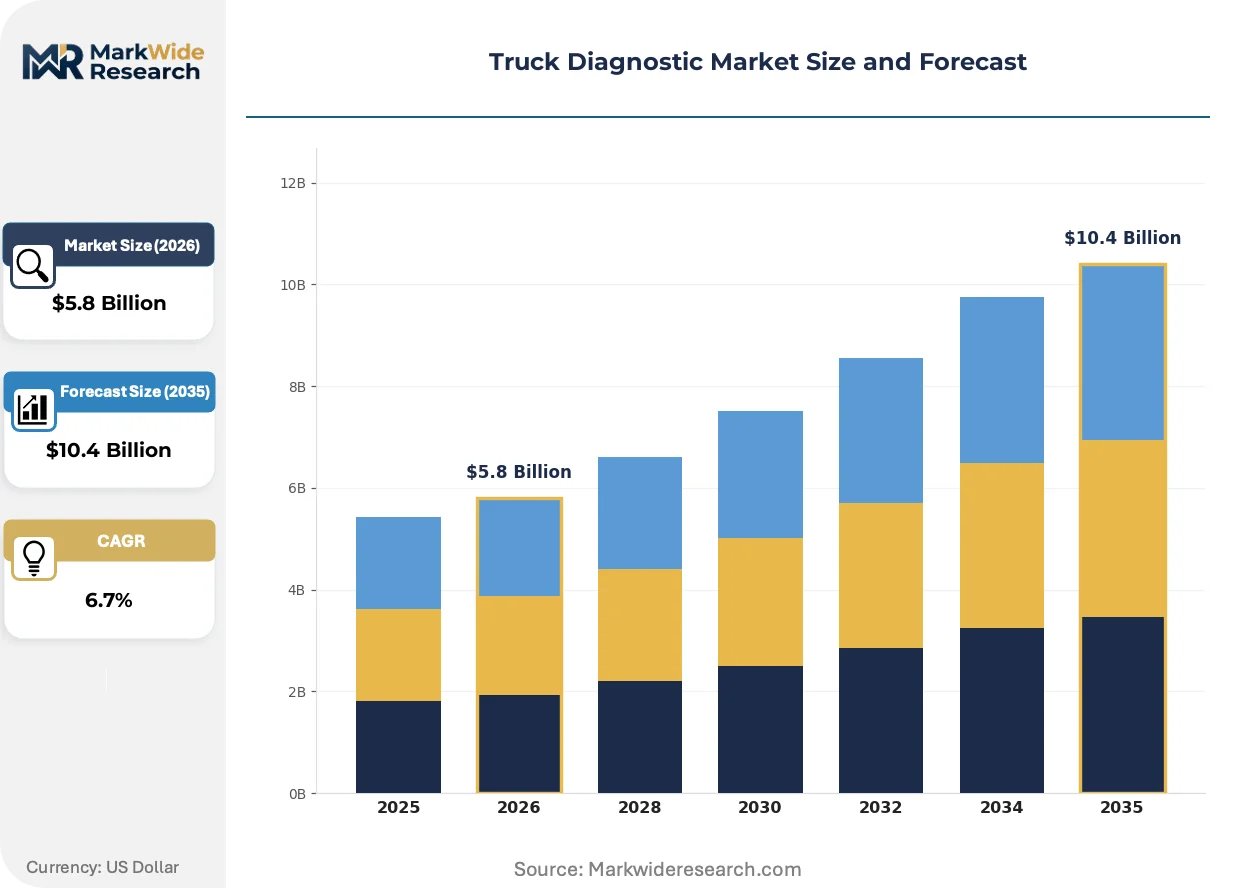
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Sensors, Diagnostic Tools End User: Fleet Operators, Repair Shops, OEMs, Independent Mechanics Service Type: Maintenance Services, Emergency Repairs, Installation, Calibration Technology: OBD-II, Telematics, Cloud Computing, AI |
| Companies Covered | Robert Bosch GmbH, Continental AG, Delphi Technologies, Snap-on Incorporated, ZF Friedrichshafen AG, Volvo Group, Cummins Inc., Autel Intelligent Technology Corp., Ltd, ACTIA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Diagnostic Market Trends and Innovations
Diagnostic technology is consolidating around unified data architectures that collapse the distinction between workshop tools and fleet management platforms. Three developments are compressing competitive timelines.
Edge computing modules embedded within vehicle electronic control units are unifying local fault processing with cloud analytics pipelines. Large fleet operators in the United States are deploying these systems at replacement cycle points to eliminate diagnostic hardware redundancy. The technology is unifying previously separate telematics and workshop diagnostic budgets into single procurement decisions.
California's Air Resources Board is expanding heavy-duty inspection and maintenance program requirements beyond federal EPA baselines. The regulation forces out-of-state operators serving California lanes to upgrade diagnostic capabilities or forfeit market access. Engine and aftertreatment manufacturers are accelerating integrated diagnostic software releases to preempt compliance gaps.
Fleet procurement departments are consolidating vendor relationships around full-lifecycle diagnostic service contracts. Independent repair shops and smaller fleet operators face exclusion as buying power concentrates among top-100 trucking enterprises. The pattern is most visible in long-haul freight corridors linking the Midwest industrial belt to West Coast port complexes.
Truck Diagnostic Market Segmentation
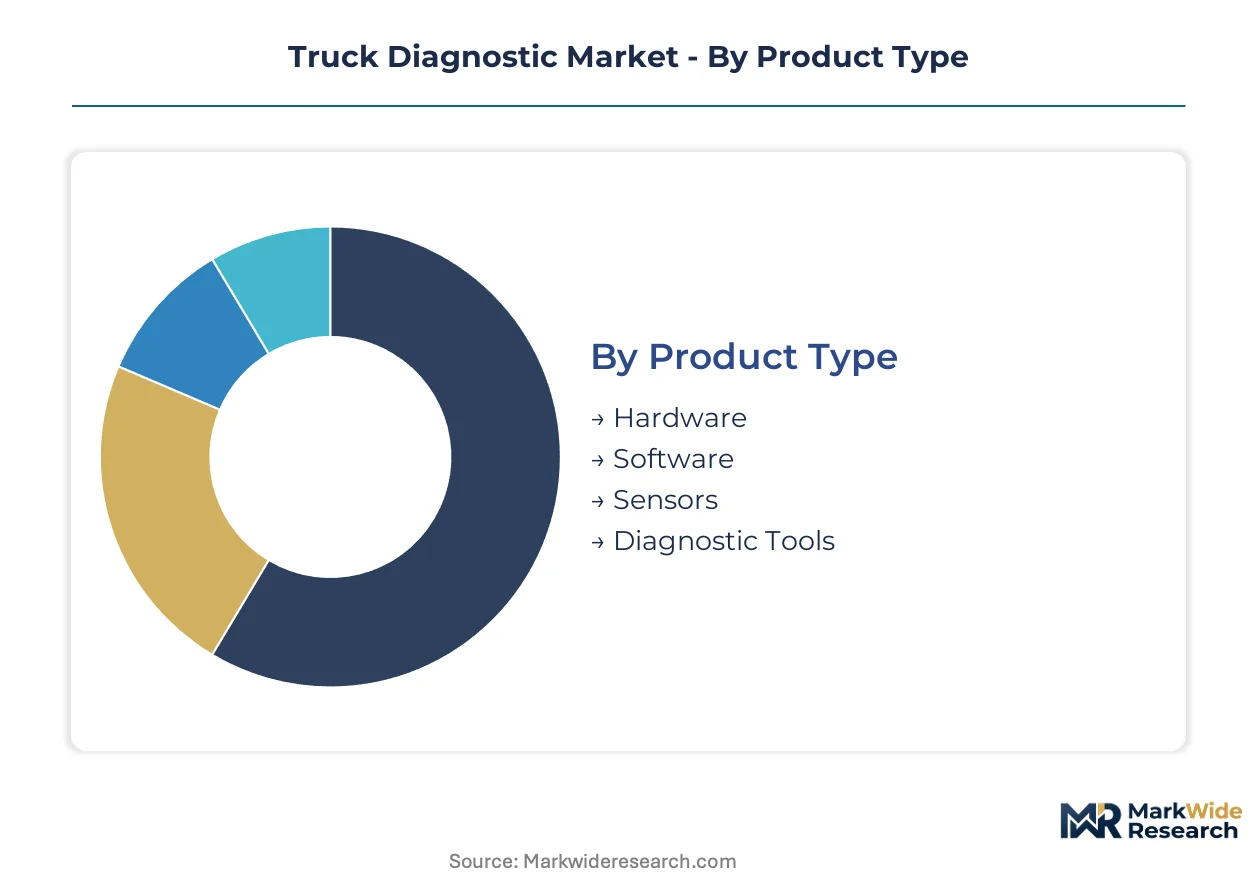
Truck diagnostic procurement splits sharply between capital-intensive hardware investments and recurring software subscriptions. Fleet operators weigh total cost of ownership against protocol coverage breadth when selecting across these dimensions.
Product Type:
Fleet capital allocation distinguishes between durable hardware assets and consumable software licenses.
- Hardware:Electronic control interfaces and diagnostic adapters constitute the foundational layer of workshop infrastructure. United States fleet operators prioritize J1939 and J1708 protocol compatibility to service mixed-vintage truck populations.
- Software:Proprietary diagnostic platforms license access to OEM-specific fault code libraries and calibration routines. Independent repair shops in California face escalating subscription costs to maintain CARB compliance coverage.
- Sensors:Aftertreatment and powertrain monitoring devices feed real-time data streams into predictive maintenance algorithms.
- Diagnostic Tools:Handheld scanners and PC-based interfaces serve intermittent-use scenarios with lower capital commitment.
Hardware leads on scale; software leads on momentum.
End User:
Buyer sophistication and compliance exposure determine technology tier selection.
- Fleet Operators:Large-scale trucking enterprises integrate diagnostic capabilities directly into telematics platforms. These buyers command volume pricing and demand API-accessible data aggregation.
- Repair Shops:Multi-bay service facilities balance coverage breadth against per-vehicle service economics. EPA HD-OBD mandates force continuous software refresh cycles to retain operating authority.
- OEMs:Vehicle manufacturers embed diagnostic architectures during production, controlling factory-installed calibration protocols.
- Independent Mechanics:Solo operators and small garages rely on aftermarket scanners with fragmented OEM coverage, accepting diagnostic limitations for lower entry costs.
Fleet operators concentrate procurement volume; repair shops expand fastest as compliance complexity deepens.
Service Type:
Revenue model preference separates scheduled maintenance contracts from transactional emergency response.
- Maintenance Services:Condition-based monitoring contracts replace mileage-interval scheduling with component-health triggers. Sensor networks track degradation patterns across powertrain and aftertreatment systems.
- Emergency Repairs:Roadside diagnostic response commands premium pricing for uptime-critical freight operations. Telematics-enabled remote fault assessment reduces unnecessary dispatch.
- Installation:Hardware deployment and system integration services accompany fleet technology refresh cycles.
- Calibration:Emissions control module programming and parameter updates ensure regulatory compliance post-repair.
Maintenance services anchor recurring revenue; emergency repairs capture peak margin per incident.
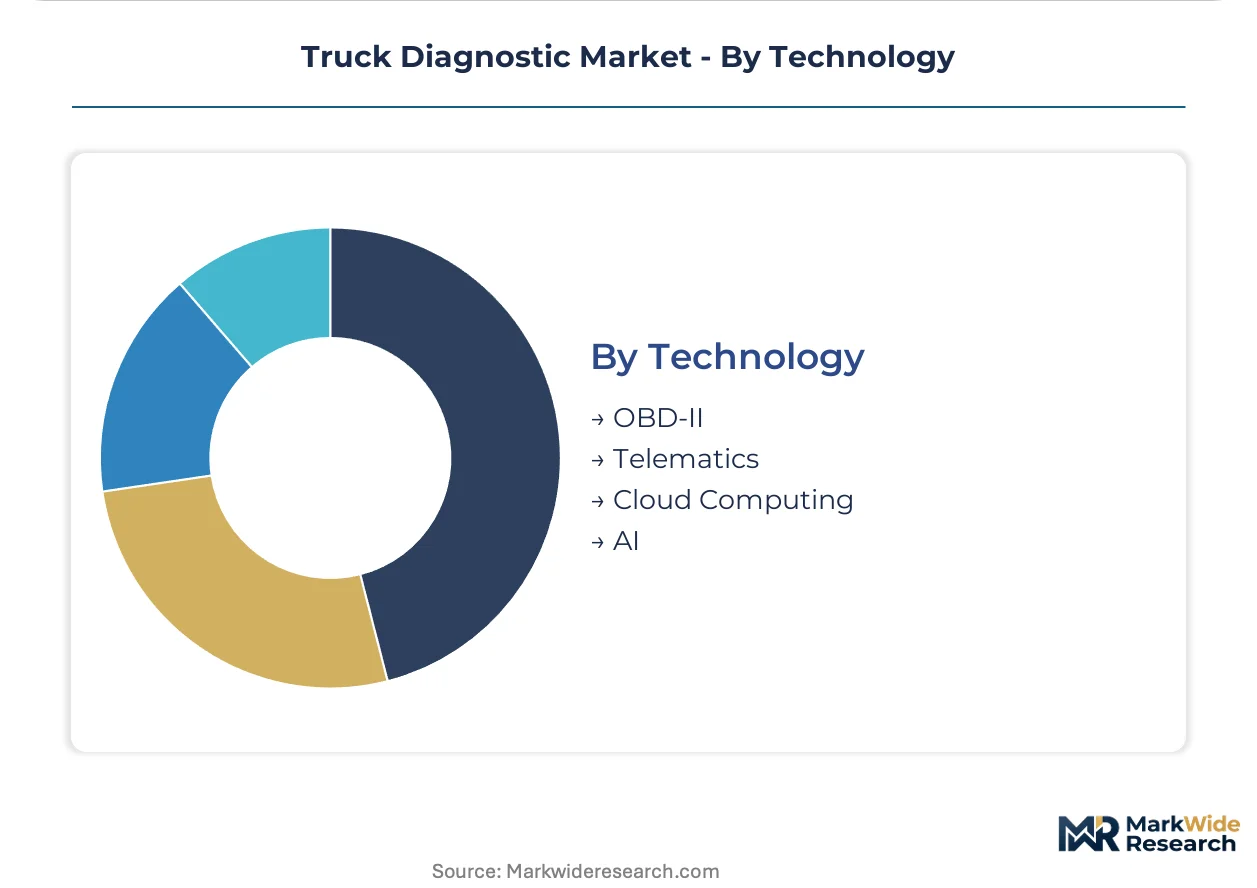
Technology:
Protocol standardization and data architecture choices lock buyers into vendor ecosystems.
- OBD-II:Federal emissions mandates standardize diagnostic connector formats and fault reporting structures across light and medium-duty vehicles. EPA enforcement ensures baseline interoperability.
- Telematics:Cellular-connected vehicle systems transmit fault codes and performance data to centralized fleet management platforms. Cloud infrastructure providers control margin-rich aggregation layers.
- Cloud Computing:Remote diagnostic access and over-the-air calibration capabilities eliminate workshop visit requirements for software updates.
- AI:Machine learning models trained on aggregated fleet datasets identify failure patterns invisible to rule-based diagnostic systems.
OBD-II dominates installed base; AI claims the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diesel technician density in the United States anchors diagnostic equipment procurement, while German engineering clusters and Chinese manufacturing hubs concentrate specialized production capacity across distinct value chain segments.
United States
Long-haul freight corridors between the Midwest industrial belt and West Coast ports generate concentrated demand for predictive maintenance systems. EPA Phase 3 greenhouse gas standards for heavy-duty vehicles compel fleet investments in advanced diagnostic architectures. The Dallas-Fort Worth metroplex hosts major fleet management headquarters driving telematics integration at scale.
Germany
Commercial vehicle engineering expertise in Stuttgart and Munich sustains premium diagnostic system development for OEM-integrated platforms. KBA enforcement of EU heavy-duty emissions regulations mandates standardized OBD protocols across member states. The Baden-Württemberg automotive cluster concentrates embedded control unit manufacturing for factory-installed diagnostic hardware.
China
Domestic truck production volumes in Shandong and Hubei provinces create aftermarket scanner demand across mixed-vintage fleets. MIIT regulations on commercial vehicle telematics data security reshape remote diagnostic access protocols. The Yangtze River Delta manufacturing corridor supplies diagnostic interface hardware components to global assembly operations.
Japan
Precision sensor manufacturing in Aichi and Kanagawa prefectures feeds global supply chains for powertrain monitoring devices. METI carbon neutrality roadmaps accelerate electrification diagnostics for battery management systems. The Nagoya industrial zone concentrates semiconductor fabrication for diagnostic control modules serving Asian export markets.
India
Commercial vehicle parc expansion in Maharashtra and Gujarat drives aftermarket diagnostic tool penetration among independent repair networks. BIS certification requirements for automotive electronics create compliance barriers for imported diagnostic equipment. The Delhi-Mumbai Industrial Corridor attracts fleet operator investments in condition-based maintenance infrastructure.
Truck Diagnostic Market Competitive Landscape
Top-tier vendors anchor factory-installed diagnostic architectures, while aftermarket specialists compete on protocol coverage breadth and subscription pricing flexibility. The market structure concentrates around three strategic archetypes: embedded control unit manufacturers, proprietary software platform developers, and price-competitive scanner producers. Dominant competitive moves include vertical integration into telematics data aggregation and geographic expansion through certification to California Air Resources Board standards exceeding federal baselines.
Within the OEM-integrated tier, Robert Bosch GmbH and Continental AG exemplify control over factory-installed diagnostic architectures. Among aftermarket platform developers, Snap-on Incorporated occupies a position representing proprietary software ecosystem strategies. Autel Intelligent Technology Corp., Ltd anchors the price-competitive scanner segment while extending feature coverage. These three archetypes capture distinct margin pools across hardware replacement cycles, recurring software subscriptions, and transactional equipment sales.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Delphi Technologies |
| Snap-on Incorporated |
| ZF Friedrichshafen AG |
| Volvo Group |
| Cummins Inc. |
| Autel Intelligent Technology Corp., Ltd |
| ACTIA Group |
| Others |
Pricing and Supply Chain Analysis
Premium-CARB certification tier divergence separates California-compliant diagnostic platforms from federal-baseline alternatives, with this bifurcation manifesting in both subscription pricing ladders and semiconductor sourcing strategies. OEM-integrated systems command hardware-plus-software bundled contracts, while aftermarket scanner vendors compete on unbundled transactional pricing for independent repair shops.
Pricing Analysis
Bundled service contracts dominate fleet operator procurement, unbundled per-scan licensing serves independent mechanics. Pricing stratifies across EPA HD-OBD certified, California CARB premium, and economy non-compliant tiers. Cost compression in economy scanner segments intensifies as Autel and comparable vendors extend J1939 protocol coverage. Fleet operators demonstrate lowest price sensitivity due to uptime monetization, while solo mechanics exhibit highest sensitivity to per-vehicle diagnostic economics.
Supply Chain Analysis
Skilled technician scarcity in Taiwan and Germany constrains diagnostic interface module production capacity. Semiconductor fabrication draws from Taiwan-based foundries, sensor components feed from Japanese precision manufacturers, and final assembly rests on Chinese Yangtze River Delta facilities. Single-source vulnerability in Taiwan chip supply creates procurement exposure during geopolitical disruptions. Distribution runs through OEM captive channels for factory-installed systems, independent distributor networks for aftermarket tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: California CARB supremacy creates 40-60% pricing premiums over federal-baseline systems, justifying certification investment for vendors targeting cross-border freight operators.
For Market Incumbents: Acquire cloud data aggregation capabilities to preempt telematics platform consolidation. Backward integration into semiconductor buffer stock programs mitigates Taiwan foundry concentration risk. Certification investment in California Air Resources Board standards captures price-insensitive compliance demand from out-of-state fleet operators serving West Coast corridors. For New Entrants and Emerging Players: AI-augmented fault prediction algorithms offer technology-first entry into fleet management platform partnerships. Electric powertrain diagnostics for battery management systems represents the most penetrable white space as electrification accelerates. Go-to-market through Midwest industrial belt fleet operators avoids incumbent-locked California repair shop networks. For Investors and Strategic Acquirers: Consolidation pressure builds where telematics data aggregation capabilities concentrate among cloud infrastructure providers. Long-term viability favors vendors controlling remote calibration and over-the-air update architectures. Target acquisition archetype: mid-cap diagnostic software platforms with EPA HD-OBD certification and API-accessible fleet integration. Signal to watch: NHTSA cybersecurity standard finalization timelines as inflection indicator for product development cycle extensions.| Strategic Initiative | Industry Significance |
|---|---|
| CARB Certification Investment | California Air Resources Board compliance unlocks premium pricing tiers for cross-border freight operators. |
| Telematics Platform Integration | API-accessible cloud aggregation consolidates previously separate diagnostic and fleet management budgets. |
| Electric Powertrain Diagnostic Development | Battery management system monitoring captures fleet electrification infrastructure spending. |
| Semiconductor Supply Diversification | Buffer stock programs mitigate Taiwan foundry concentration vulnerability in control module production. |
| AI-Augmented Fault Prediction | Machine learning models trained on aggregated telematics datasets differentiate from rule-based diagnostic systems. |
Research Methodology
Direct dialogue with fleet operations directors, independent repair shop owners, OEM calibration engineers, and EPA compliance officers grounded qualitative insights. Secondary validation drew from NHTSA regulatory filings, EPA emissions enforcement databases, SAE J1939 protocol documentation, and commercial vehicle registration data. Bottom-up unit economics triangulated against top-down fleet technology spending estimates.
Market sizing and growth projections emerged from segmented modeling across hardware, software, sensor, and diagnostic tool product categories; fleet operator, repair shop, OEM, and independent mechanic end users; and OBD-II, telematics, cloud computing, and AI technology tiers. CAGRs derived from regression analysis against commercial vehicle production volumes, EPA regulatory phase-in schedules, and fleet telematics adoption curves. Propulsion architecture electrification rates and cybersecurity certification timelines served as industry-specific forecast inputs.
The model holds under steady EPA Phase 3 enforcement and Taiwan semiconductor supply continuity; deviation in NHTSA cybersecurity rule acceleration or geopolitical chip supply disruption would shift hardware replacement cycle assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Heavy-Duty Truck Fleet Control Unit Architectures Market
Heavy-Duty Trucks
Heavy Duty Truck Wash Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Garbage Truck Bodies Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Egypt Trucks Market
Heavy-Duty Trucks
Turret Truck Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Global Vocational Truck Market