
 Heavy-Duty Truck Axle Locking Actuator Components Market | 2026-2036
Heavy-Duty Truck Axle Locking Actuator Components Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Truck Axle Locking Actuator Components Market Insights
Electrification of axle control systems is rewriting the architecture of heavy-duty drivetrain components, replacing purely mechanical linkages with sensor-integrated electromechanical modules. Bosch leverages its mechatronics portfolio to anchor positions in electrohydraulic actuator development for European OEM platforms. Dana Incorporated specializes in severe-duty axle systems and sustains manufacturing scale across North American commercial vehicle corridors. Eaton competes through integrated powertrain controls that extend from transmission to axle locking functions.
Heavy-duty truck axle locking actuator components are precision-engineered subassemblies that engage or disengage differential lock mechanisms through hydraulic, pneumatic, or electromechanical force transmission, typically operating at system pressures exceeding 150 bar and engineered for fatigue resistance exceeding one million duty cycles in mining and construction environments. Their primary purpose is to distribute torque across axle shafts when wheel slip conditions threaten traction, thereby protecting driveline hardware and maintaining vehicle mobility in low-friction terrain. The electromechanical technology segment is displacing legacy pneumatic systems in long-haul transport applications where response time and modularity command premium positioning. Gear mechanism components concentrate margin pools due to precision machining requirements and heat treatment protocols that limit supplier qualification. Off-road hauling and mining operations represent the most demanding application envelope, driving specification intensity for actuator bodies and control valves rated for shock load and contamination exposure.
Fleet operators and vehicle manufacturers face divergent compliance pressures from EPA, NHTSA, and EU Green Deal frameworks that tighten emissions boundaries while demanding durability validation under standardized test protocols. ISO 26262 functional safety requirements and CE marking obligations shape product development roadmaps and market access conditions for electrohydraulic actuator suppliers serving dual-region OEM programs. Stakeholders must monitor how software-defined axle control architectures alter procurement patterns for mechanical component suppliers and redefine warranty liability across the value chain.
Market Dynamics
Electrification of axle control architectures is compressing supplier margins while demanding simultaneous compliance with divergent EPA and EU Green Deal emissions frameworks across heavy-duty vehicle platforms.
Growth Catalysts
- EPA Phase 3 Standards:Stringent greenhouse gas mandates for heavy-duty trucks are forcing OEMs to specify lighter, more responsive electromechanical actuators that reduce parasitic losses compared to legacy pneumatic systems.
- Mining Operations:Severe-duty extraction sites in Australia and Canada require actuator assemblies rated for shock loads exceeding 150 bar and contamination exposure, driving specification intensity for fatigue-resistant gear mechanisms.
- Electromechanical Convergence:Sensor-integrated modules that combine position feedback with torque modulation are displacing purely mechanical linkages in long-haul corridors where traction control reliability commands premium positioning.
Market Restraints
- Heat Treatment Bottlenecks:Precision gear machining and specialized thermal processing protocols limit qualified supplier pools, concentrating margin capture among a narrow tier of certified forges.
- Raw Material Volatility:Specialty alloy steel and rare-earth magnet inputs for electromechanical actuators expose manufacturers to price swings that compress working capital cycles.
- ISO 26262 Certification Burden:Functional safety validation requirements for electrohydraulic systems extend product development timelines and raise barriers for component suppliers seeking dual-region OEM qualification.
Strategic Opportunities
- Software-Defined Architectures:Over-the-air updatable axle control systems create white space for suppliers offering embedded firmware alongside mechanical subassemblies, shifting procurement toward integrated module sourcing.
- Brazilian Mining Expansion:Iron ore and copper extraction growth in Minas Gerais state is generating demand for severe-duty actuator bodies rated for tropical humidity and abrasive particulate exposure.
- EU Battery-Electric Truck Mandates:The Green Deal's zero-emission freight corridors are accelerating development of compact electromechanical lockers compatible with e-axle packaging constraints.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-functional engineers capable of integrating mechanical fatigue analysis with embedded control systems command compensation premiums that inflate R&D overhead.
- Legacy System Integration:Electromechanical actuators must interface with existing pneumatic infrastructure in retrofit fleets, complicating warranty liability allocation between component and vehicle manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Truck Axle Locking Actuator Components Market |
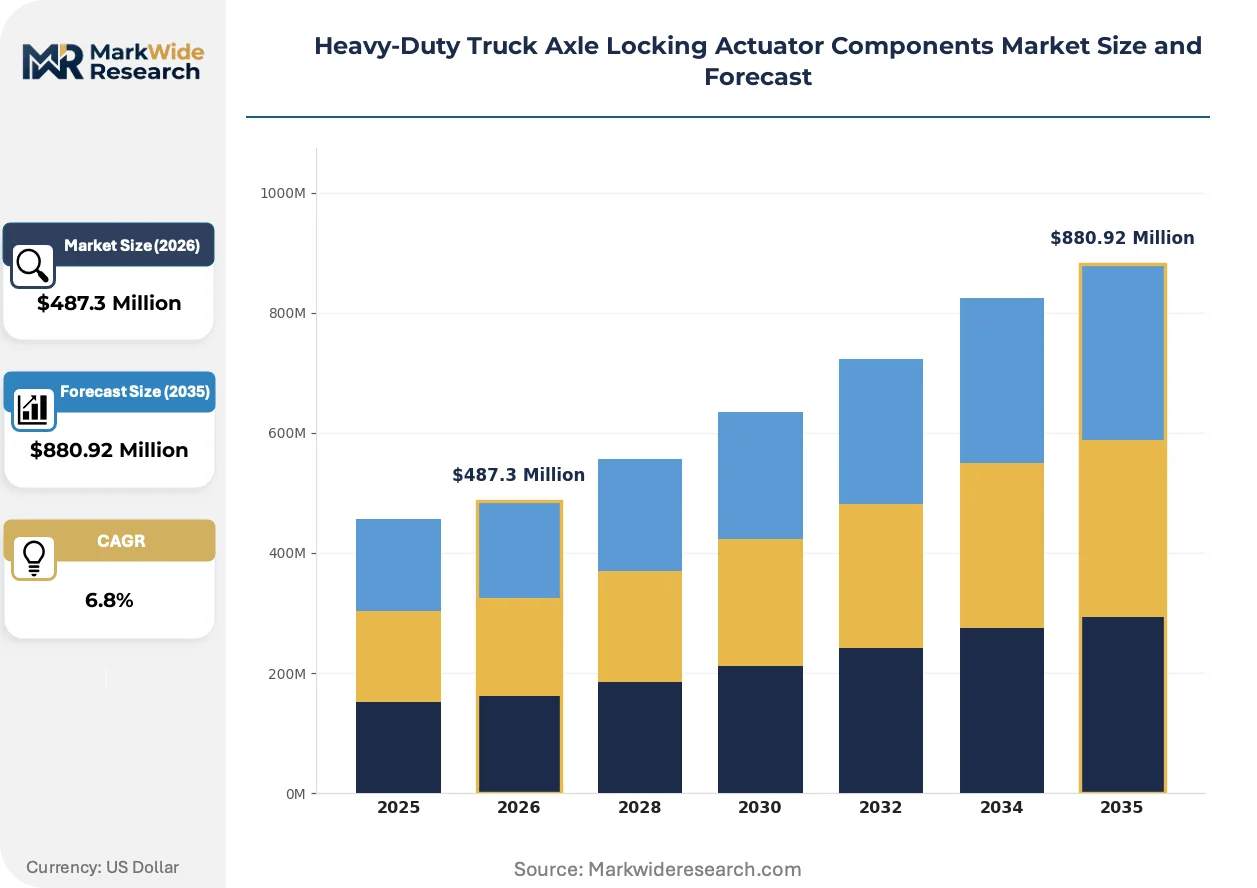
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Actuator Body, Gear Mechanism, Hydraulic Cylinder, Control Valve, Electrical Connector Technology: Hydraulic, Pneumatic, Electromechanical, Electrohydraulic, Mechanical Application: Off-Road Hauling, Long-Haul Transport, Construction Transport, Mining Operations, Heavy Logistics End User: Fleet Operators, Vehicle Manufacturers, Specialized Transport Services, Heavy Equipment Providers, Logistic Contractors |
| Companies Covered | ZF Friedrichshafen, Bosch, Cummins, Allison Transmission, BorgWarner, Dana Incorporated, Eaton, American Axle & Manufacturing, JTEKT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Truck Axle Locking Actuator Components Market Trends and Innovations
Axle control technology is undergoing forced convergence between mechanical durability requirements and digital responsiveness, compressing traditional supplier categories while elevating firmware capabilities to parity with machined components.
Electrohydraulic actuator designs are hybridizing pneumatic response speed with electromechanical precision by integrating proportional solenoid valves with high-pressure hydraulic accumulators. Mining fleet operators in Western Australia are specifying these hybrid systems for autonomous haul trucks where millisecond engagement timing prevents differential damage during wheel slip events. The technology is hybridizing procurement patterns as OEMs consolidate formerly separate pneumatic and electronic supplier bases into single-source module contracts.
REACH substance restrictions and F-Gas Regulation phase-down schedules in the European Union are eliminating certain hydraulic fluid formulations and pressurized gas systems from new axle actuator designs. Component suppliers serving Volvo and Scania platforms are reformulating seals and relocating manufacturing to avoid substances targeted for sunset. Severe-duty applications retain limited exemptions, creating a two-tier compliance environment between on-highway and off-road product lines.
Maintenance contracting for axle locking systems is unbundling from powertrain service agreements as fleet operators seek specialized drivetrain expertise separate from engine-overhaul providers. Independent service networks in the United States are capturing actuator calibration and firmware update revenue that OEM dealers previously monopolized. This disintermediation is most visible in the Great Lakes logistics corridor where regional specialists now warranty electromechanical locker performance separately from vehicle powertrain coverage.
Heavy-Duty Truck Axle Locking Actuator Components Market Segmentation
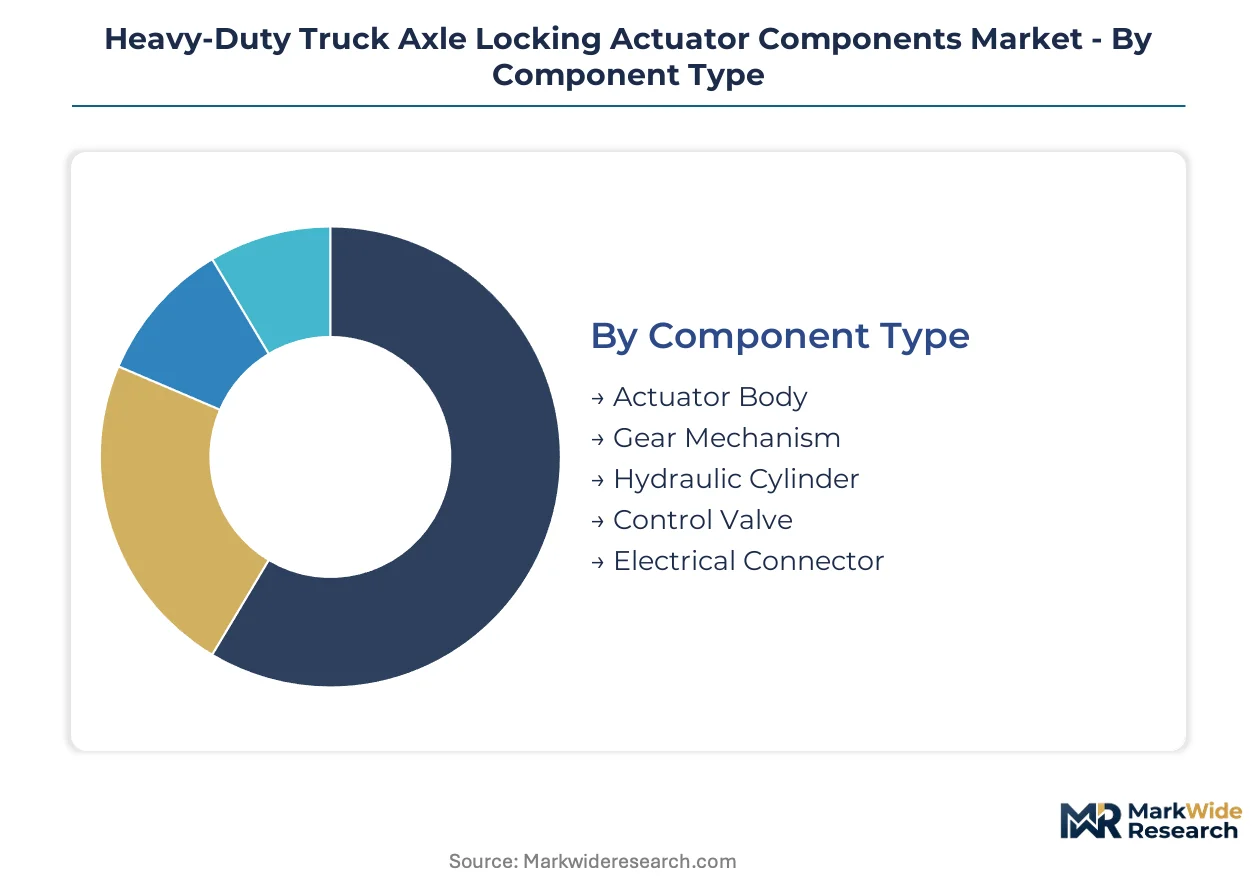
Component suppliers must navigate divergent specification intensities across actuator subsystems, where precision machining requirements and functional safety validation create tiered margin structures. Technology selection determines procurement patterns, with electromechanical convergence compressing legacy pneumatic supply chains while elevating firmware capabilities alongside mechanical hardware.
Component Type:
Mature forging and machining operations anchor established segments, while sensor-integrated subassemblies represent emerging value capture opportunities.
- Actuator Body:Cast and forged housings rated for system pressures exceeding 150 bar form the structural foundation of axle locking assemblies. Mining fleets in Australia specify fatigue-resistant ductile iron variants for autonomous haul trucks operating in Pilbara iron ore corridors, where shock load exposure demands contamination-sealed architectures.
- Gear Mechanism:Precision-machined planetary and spur gear sets transmit torque across differential lock engagements with position feedback integration. Heat treatment bottlenecks concentrate qualified supplier pools for carburized alloy steel components serving North American severe-duty platforms, limiting margin compression for certified forges.
- Hydraulic Cylinder:High-pressure piston assemblies convert fluid energy into mechanical lock engagement force.
- Control Valve:Proportional solenoid and directional flow regulators modulate pressure distribution timing.
- Electrical Connector:Sealed harness interfaces bridge actuator subassemblies with vehicle CAN bus architectures.
Gear mechanism components handle the majority of throughput; electrical connector integration is the fastest mover on share.
Technology:
Cost tier stratification separates legacy pneumatic infrastructure from premium electromechanical modules commanding firmware-inclusive pricing.
- Electromechanical:Sensor-integrated motor-driven actuators combine position feedback with millisecond engagement response. Long-haul transport corridors in Germany specify these modules for EPA Phase 3 compliance, where reduced parasitic losses improve fuel efficiency metrics against NHTSA mandates.
- Electrohydraulic:Hybrid architectures merge proportional solenoid precision with hydraulic accumulator power density. Western Australian mining operators deploy these systems for autonomous haul trucks requiring wheel slip prevention timing that pure pneumatic systems cannot achieve.
- Hydraulic:Fluid-power actuation remains prevalent in construction equipment retrofit markets.
- Pneumatic:Compressed air systems dominate legacy fleet maintenance cycles.
- Mechanical:Cable and linkage systems persist in cost-optimized emerging market specifications.
Electromechanical systems command premium positioning; electrohydraulic hybrids are expanding most quickly in severe-duty applications.
Application:
Volume concentration clusters in long-haul freight corridors, while specification intensity peaks in extractive industries demanding million-cycle durability validation.
- Mining Operations:Severe-duty actuator assemblies face contamination exposure and shock loads exceeding 150 bar in surface extraction environments. Canadian oil sands and Chilean copper pits specify sealed electrohydraulic modules with ISO 26262 functional safety certification for continuous drivetrain uptime.
- Off-Road Hauling:Articulated dump trucks and rigid haulers operating in Minas Gerais iron ore fields require tropical humidity-rated actuator bodies with abrasive particulate sealing.
- Long-Haul Transport:Highway freight tractors prioritize weight reduction and response time.
- Construction Transport:Mixer and dump configurations balance duty cycle severity with cost constraints.
- Heavy Logistics:Specialized lowboy and multi-axle trailers demand synchronized multi-axle locking coordination.
Long-haul transport generates baseline volume; mining operations drive steepest specification intensity and margin capture.
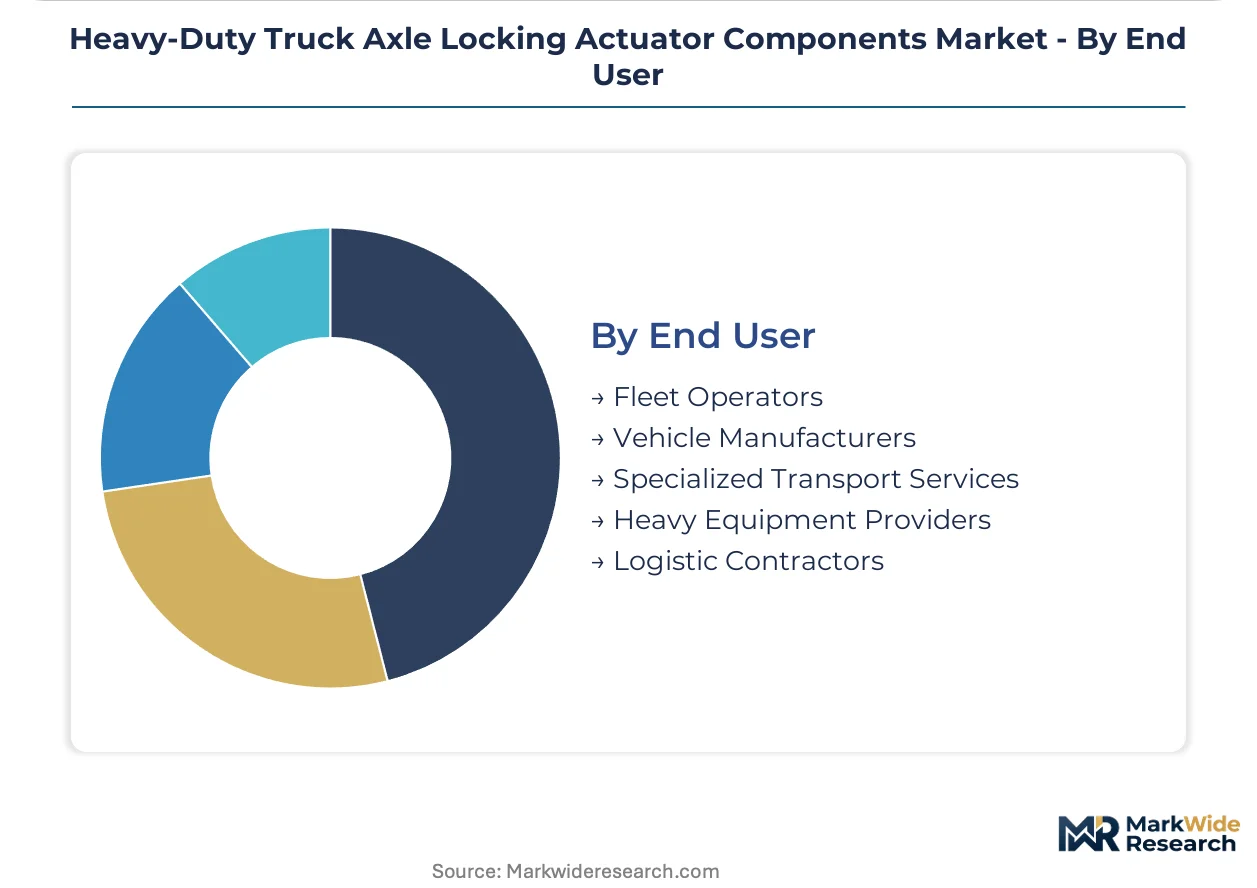
End User:
Customer type determines procurement sophistication, with fleet operators consolidating module sourcing while vehicle manufacturers enforce platform standardization.
- Fleet Operators:Large-scale logistics and extraction companies specify integrated actuator modules with embedded firmware and over-the-air update capability. United States-based regional specialists in the Great Lakes corridor now warranty electromechanical locker performance separately from OEM powertrain coverage, disintermediating traditional dealer service networks.
- Vehicle Manufacturers:OEM platform engineering teams enforce supplier consolidation across transmission-to-axle control integration, favoring single-source electrohydraulic module contracts over discrete component procurement.
- Specialized Transport Services:Heavy-haul and project cargo operators customize locking configurations for permit-specific axle loadings.
- Heavy Equipment Providers:Mining and construction fleet lessors prioritize residual value through standardized maintenance protocols.
- Logistic Contractors:Third-party fulfillment operators seek retrofit compatibility with existing pneumatic infrastructure.
Vehicle manufacturers dominate design-in decisions; fleet operators are gaining procurement leverage fastest through aftermarket specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a trade surplus concentrated in precision-machined actuator subassemblies, with Germany and the United States shipping finished electromechanical modules to mining corridors in Australia and Chile while sourcing forged housings from specialized foundries in China and India.
United States
Great Lakes logistics corridors drive fleet operator procurement of sensor-integrated locking modules with over-the-air firmware capability. EPA Phase 3 greenhouse gas standards and NHTSA fuel efficiency mandates compel OEMs to specify lighter electromechanical actuators that reduce parasitic losses. Detroit-Warren manufacturing clusters anchor Dana Incorporated and Eaton production facilities serving North American severe-duty platforms.
Germany
Long-haul freight operators along the Rhine-Alpine corridor specify millisecond-response electromechanical systems for traction control reliability. EU Green Deal zero-emission freight mandates and REACH substance restrictions accelerate reformulation of hydraulic seals and elimination of F-Gas regulated pressurized systems. Stuttgart engineering centers concentrate Bosch mechatronics development for electrohydraulic actuator integration into Volvo and Scania OEM platforms.
China
Domestic mining expansion in Inner Mongolia and Shanxi Province generates specification intensity for fatigue-resistant gear mechanisms rated beyond one million duty cycles. MIIT fuel consumption standards and dual carbon goals push commercial vehicle manufacturers toward electromechanical architectures compatible with e-axle packaging. Yangtze River Delta foundries supply ductile iron actuator housings to both domestic OEMs and export markets.
Australia
Pilbara iron ore autonomous haul truck fleets demand shock-load-rated electrohydraulic modules with ISO 26262 functional safety certification for continuous drivetrain uptime. National Heavy Vehicle Regulator performance-based standards shape durability validation protocols for contamination-sealed actuator assemblies. Perth engineering service networks specialize in actuator calibration revenue previously captured by OEM dealer channels.
Brazil
Minas Gerais iron ore and copper extraction growth drives demand for tropical humidity-rated actuator bodies with abrasive particulate sealing. ANVISA industrial equipment safety frameworks and IBAMA environmental licensing shape severe-duty component qualification timelines. São Paulo state manufacturing corridors host assembly operations integrating imported precision gear sets with locally forged structural housings.
Heavy-Duty Truck Axle Locking Actuator Components Market Competitive Landscape
On the supply side, the industry is consolidating around electromechanical module integration, compressing formerly discrete pneumatic and electronic supplier tiers into single-source contracts. Tiered competitive positioning separates mechatronics-integrated multinationals from specialized forging operations and regional firmware developers. Strategic archetypes include full-system integrators, precision machining specialists, and embedded control software providers. Dominant competitive moves encompass supplier consolidation across transmission-to-axle control chains and backward integration into captive heat treatment capacity.
Among Germany-based engineering conglomerates, ZF Friedrichshafen and Bosch exemplify the mechatronics-integrated archetype through their positions spanning electrohydraulic development for European OEM platforms. Dana Incorporated represents the severe-duty specialist tier with manufacturing scale concentrated across North American commercial vehicle corridors. Eaton occupies the powertrain integration vector, anchoring competitive positioning through control system architectures extending from transmission to axle locking functions. These three entities collectively illustrate how technology convergence is compressing traditional component supplier categories while elevating firmware capabilities to strategic parity with machined hardware.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Bosch |
| Cummins |
| Allison Transmission |
| BorgWarner |
| Dana Incorporated |
| Eaton |
| American Axle & Manufacturing |
| JTEKT |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine freight corridors concentrate electromechanical actuator demand where procurement cost dynamics hinge on heat treatment capacity scarcity and firmware-inclusive module differentiation. Fleet operators in Germany and Switzerland face divergent price points depending on whether suppliers command captive forging operations or rely on outsourced precision machining.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium electromechanical modules with ISO 26262 functional safety certification and embedded position feedback command substantial markups over pneumatic legacy systems. Cost compression in economy-tier mechanical linkages is intensifying because Brazilian and Indian foundries are expanding ductile iron casting capacity. Mining fleet operators exhibit lowest price sensitivity due to million-cycle durability requirements, while logistics contractors in retrofit markets resist firmware-inclusive pricing.
Supply Chain Analysis
Yangtze River Delta foundries and Stuttgart-area precision machining clusters hold dominant contract-manufacturing capacity for actuator housings and gear mechanisms. Supply draws from specialty alloy steel mills in Germany, rare-earth magnet processors in China, and hydraulic seal compounders serving REACH-compliant formulations. Single-source vulnerability concentrates in carburized gear suppliers certified for North American severe-duty platforms. Distribution runs through OEM captive channels for new vehicle platforms and independent service networks for aftermarket retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical substitution threatens pneumatic incumbent positions as fleet operators prioritize response time and modularity over legacy infrastructure compatibility.
For Market Incumbents: Insulate core positions through backward integration into captive heat treatment capacity for million-cycle gear certification. Dana Incorporated and Eaton demonstrate how transmission-to-axle control integration locks out modular competitors. Prioritize firmware development talent acquisition before mechatronics engineering compensation premiums inflate further. For New Entrants and Emerging Players: Build out specialized calibration and over-the-air update service capabilities targeting Great Lakes logistics corridor fleet operators disintermediating OEM dealer networks. Brazilian mining expansion in Minas Gerais offers the most penetrable geography for tropical humidity-rated actuator assemblies. Lead with aftermarket firmware subscription models rather than hardware-only positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized axle control divisions lacking software-defined architecture roadmaps. Long-term viability hinges on electromechanical module share expansion against pneumatic legacy decline. Monitor EPA Phase 3 compliance timeline acceleration as inflection signal for electromechanical procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive carburizing capacity locks in ISO 26262 certification for severe-duty gear mechanisms. |
| Firmware Development Center Establishment | Embedded control software capabilities elevate supplier positioning in software-defined axle architectures. |
| Brazilian Manufacturing Footprint Expansion | Local assembly operations capture Minas Gerais mining demand while navigating ANVISA qualification timelines. |
| Aftermarket Service Network Acquisition | Independent calibration specialists in Perth and Detroit capture actuator maintenance revenue from OEM dealers. |
| E-Axle Packaging Compatibility Investment | Compact electromechanical locker designs align with EU Green Deal zero-emission freight corridor mandates. |
Research Methodology
The analysis maps electromechanical, electrohydraulic, pneumatic, hydraulic, and mechanical technology segments, each validated through fleet maintenance directors, OEM platform engineers, aftermarket service network operators, and mining fleet procurement leads. Primary fieldwork combined with secondary validation from EPA regulatory filings, NHTSA fuel efficiency rulemakings, EU Green Deal documentation, and MIIT commercial vehicle standards anchored bottom-up and top-down triangulation.
Assumptions held fixed include EPA Phase 3 compliance timelines, EU REACH substance restriction schedules, and raw material alloy pricing bands; variables stress-tested encompass electrification adoption curves and autonomous haul truck deployment rates. The analytical framework modeled component type, technology, application, and end user dimensions across the projection horizon. CAGRs derived from installed base turnover analysis and specification intensity differentials between mining and long-haul duty cycles.
Stress conditions across rare-earth magnet supply disruption, heat treatment capacity expansion, and firmware talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge electromechanical substitution velocity or regulatory timeline delays as specific revision triggers. Quarterly review of OEM platform engineering staffing and Brazilian mining licensing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Heavy-Duty Truck Load and Axle Weight Sensor Systems Market
Heavy-Duty Trucks
US Vacuum Truck Market
Heavy-Duty Trucks
Automotive High Performance Trucks Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Dump Truck & Body Market
Heavy-Duty Trucks
Logging Trucks Market
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Flatbed Truck Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Mexico Refrigerated Truck Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Digger Derrick Truck Market