
 Dump Trucks and Mining Trucks Market | 2026-2036
Dump Trucks and Mining Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Dump Trucks and Mining Trucks Market Analysis
A capital-intensity divergence between integrated manufacturers and component assemblers is reorganizing competitive tiers in the dump truck and mining truck sector. Caterpillar Inc. leverages captive powertrain production to sustain margin control across ultra-class mining models. Komatsu Ltd. anchors its position through autonomous haulage system integration. BELAZ competes on payload extremes, dominating the 450-ton-plus category with in-house Belarusian fabrication.
Dump trucks and mining trucks are heavy-duty off-highway vehicles engineered for bulk material transport, typically featuring welded steel frames, hydro-pneumatic suspension systems, and power ratings exceeding 1,000 kW for mining-class units. Their primary purpose is moving overburden, ore, and aggregate in conditions where road-legal commercial vehicles cannot operate. Rigid dump trucks occupy the core revenue pool in surface mining, while electric fuel type variants represent the fastest-expanding segment as open-pit operators target Scope 1 emissions reductions. Articulated dump trucks sustain construction end-user demand through all-terrain chassis articulation that protects frame integrity on uneven grades.
EPA, EU Stage V regulations, and China's MEE emission standards are tightening particulate matter and NOx limits, forcing engine redesigns and aftertreatment additions that raise procurement costs but also filter out non-compliant suppliers. ISO 3450 braking performance standards and SAE J1511 stability criteria further constrain product architecture, particularly for above-60-ton capacity classes. Stakeholders must monitor battery energy density trajectories and charging infrastructure commitments at specific mine sites before committing to fleet electrification timelines.
Market Dynamics
Diesel-electric hybrid powertrains are decomposing the century-old mechanical drivetrain monopoly in heavy mining trucks, forcing incumbent suppliers to re-engineer torque delivery architectures around battery-buffered systems.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V emission mandates:North American and European open-pit operators face fleet replacement deadlines that favor compliant ultra-class models with integrated aftertreatment.
- Autonomous haulage integration:Mining companies in Australia's Pilbara region are retrofitting existing fleets with vendor-agnostic autonomy kits to reduce labor costs and shift-cycle variability.
- Rare earth extraction intensity:China's Inner Mongolia autonomous region is expanding surface mining capacity for neodymium and dysprosium, driving procurement of 300-ton-plus rigid dump trucks.
Market Restraints
- High-voltage battery supply concentration:Cell production for mining-class electric trucks clusters in East Asian suppliers, exposing fleet operators to geopolitical supply interruptions.
- Steel and copper input volatility:Welded frame fabrication and motor winding costs fluctuate with commodity exchange pricing, compressing OEM margin predictability on fixed-price contracts.
- Charging infrastructure capex requirements:Mine-site megawatt charging stations demand grid interconnection upgrades that extend project timelines beyond traditional diesel refueling deployment.
Strategic Opportunities
- Battery-swapping standardization:Interoperable swap protocols across Komatsu, Caterpillar, and BELAZ platforms would reduce operator lock-in and accelerate electric fleet adoption.
- Retrofit autonomy packages:Aftermarket sensor and control module integration for legacy mechanical trucks opens revenue in installed base renewal without full platform replacement.
- Indonesia nickel corridor expansion:Sulawesi and Halmahera island mining concessions are commissioning new haul roads suited for 240-ton electric rigid trucks with regenerative descent braking.
Industry Challenges
- High-voltage technician scarcity:Mine maintenance departments lack certified electricians for 1,000V+ battery systems, forcing OEMs to embed field service teams at customer sites.
- ISO 3450 braking recertification:Electric powertrain retrofits trigger full validation cycles for dynamic braking performance on downhill haul routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dump Trucks and Mining Trucks Market |
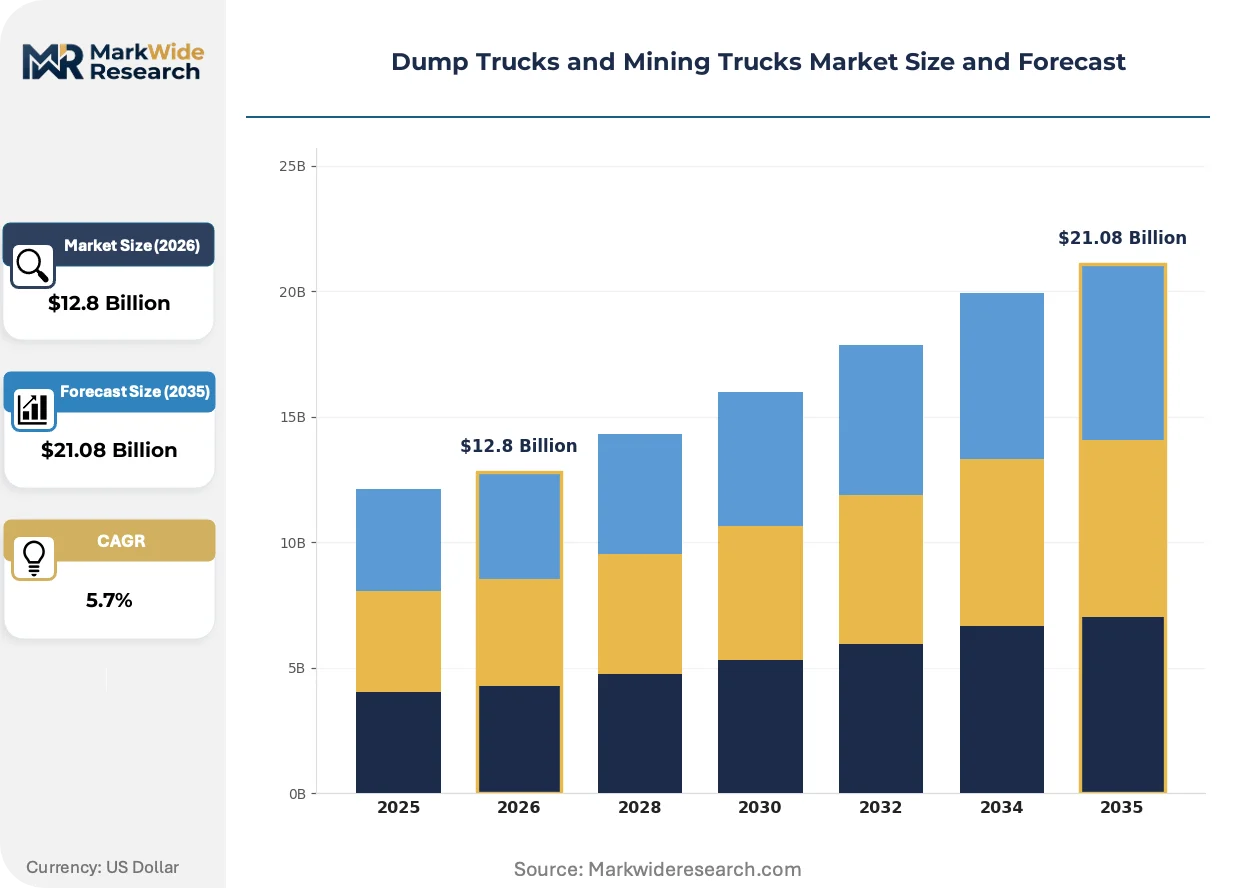
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Dump Trucks, Articulated Dump Trucks, Mining Trucks, Off-Highway Trucks End User: Construction, Mining, Agriculture, Oil & Gas Capacity: 10-25 Tons, 26-40 Tons, 41-60 Tons, Above 60 Tons Fuel Type: Diesel, Electric, Hybrid, Gasoline |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., BELAZ, Volvo Construction Equipment, Liebherr Group, Terex Trucks, Sany, XCMG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dump Trucks and Mining Trucks Market Emerging Trajectories
Powertrain electrification is fragmenting the engineering skill base that once concentrated in internal combustion expertise, redistributing competitive advantage toward battery thermal management and motor control software.
Solid-state battery cell chemistry is decomposing the energy density constraints that have limited electric mining truck payload-range parity. Tier 1 suppliers are piloting silicon-anode prototypes with mining OEMs in Chile's Atacama copper belt. The technology is decomposing the diesel-electric hybrid as a transitional stopgap, accelerating direct-to-battery-electric platform development.
China's MEE emission standards are tightening particulate matter enforcement for non-road mobile machinery, compelling domestic mining truck manufacturers to license European aftertreatment systems. The regulations are compressing product development cycles from 48 to 36 months. Inner Mongolia coal operators are responding by consolidating procurement around Stage V-compliant platforms from SANY and XCMG.
Lifecycle cost contracting is displacing upfront equipment sales in Australian iron ore operations. Major miners now negotiate total cost-per-ton haulage agreements that bundle maintenance, energy, and residual value risk with OEMs. This model is most advanced in Western Australia's Pilbara region, where Rio Tinto and BHP have shifted 60% of fleet additions to performance-based contracts.
Dump Trucks and Mining Trucks Market Segmentation
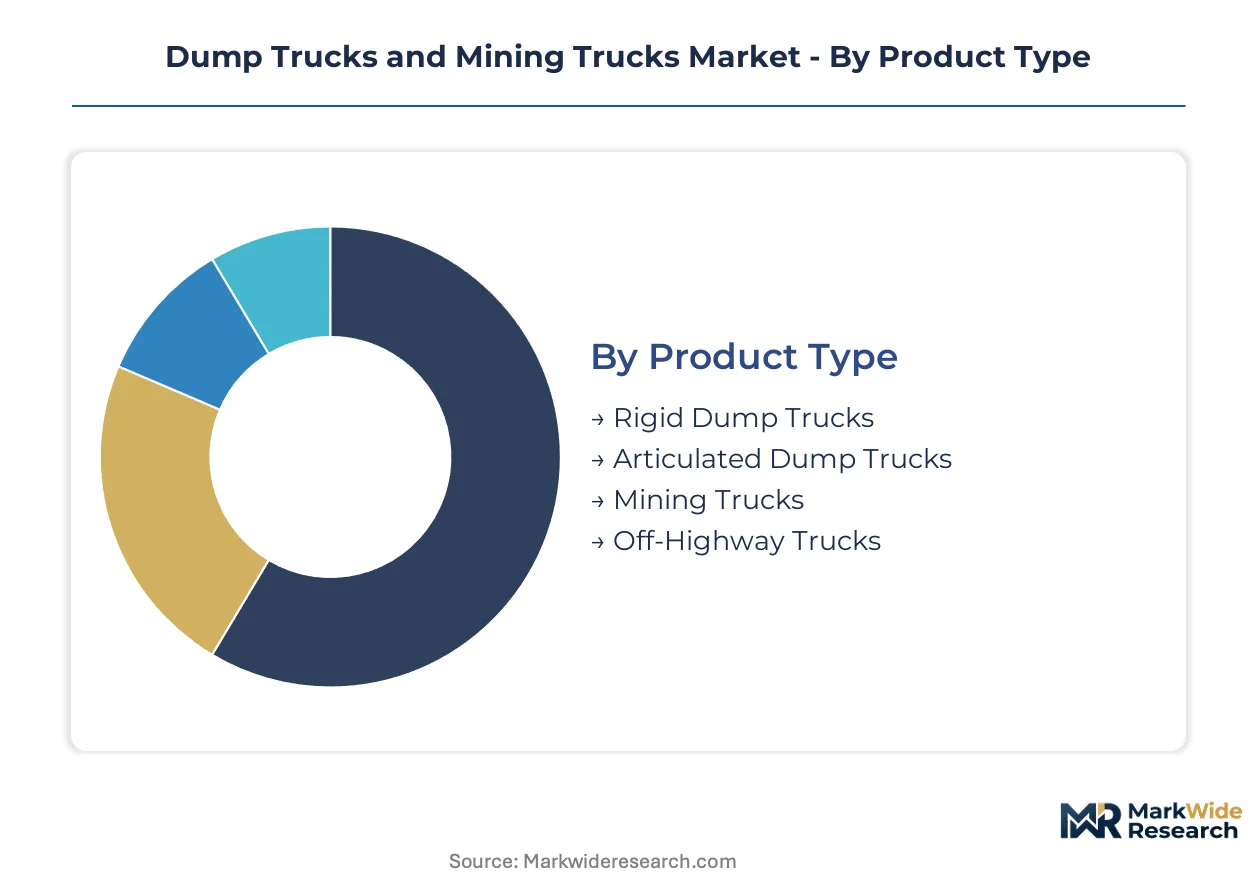
Segmentation in the dump truck and mining truck market reveals how equipment specifications align with distinct operational economics. Procurement patterns diverge sharply between surface mining operators seeking payload maximization and construction contractors prioritizing terrain adaptability. Channel strategies vary accordingly, with direct OEM relationships dominating ultra-class mining sales while dealer networks handle mid-capacity construction units.
Product Type:
Channel distribution for product types splits between captive OEM sales teams for mining-class units and independent dealer networks for construction-oriented models. Mining operators in Australia's Pilbara region source rigid dump trucks through direct procurement contracts with manufacturers. Construction contractors across Indonesia's nickel corridor acquire articulated units via regional equipment distributors.
- Rigid Dump Trucks:Welded steel frame construction with fixed rear axles delivers structural integrity for continuous high-load cycles. Demand clusters in Chile's Atacama copper belt where 240-ton-plus units move sulfide ore on dedicated haul roads. EPA Tier 4 Final compliance costs are accelerating fleet consolidation around newer platforms.
- Mining Trucks:Ultra-class specifications exceed 300-ton payload with diesel-electric powertrains and hydro-pneumatic suspension. China's Inner Mongolia autonomous region drives procurement for rare earth surface extraction, with operators specifying autonomous haulage compatibility. MEE emission standards are filtering non-compliant suppliers from tender shortlists.
- Articulated Dump Trucks:Pivot-steer chassis articulation protects frame integrity on uneven construction grades.
- Off-Highway Trucks:Intermediate payload class serves quarry and aggregate operations with simplified maintenance protocols.
Rigid Dump Trucks dominate installed base. Mining Trucks is where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive mining procurement from cyclical construction spending patterns. Mining end-users negotiate lifecycle cost contracts bundling maintenance and energy. Construction operators prioritize acquisition cost and residual value predictability.
- Mining:Open-pit and underground surface operations demand 1,000 kW-plus power ratings with 24/7 duty cycles. Western Australia's iron ore sector contracts total cost-per-ton haulage agreements covering 60% of fleet additions. Autonomous retrofit packages are extending existing fleet service life without full replacement.
- Construction:Road building and earthmoving applications require all-terrain mobility with rapid cycle times. Indonesian infrastructure projects are commissioning 40-ton articulated units for island terrain where road access remains limited. Rental fleet operators are expanding electric-hybrid allocations to meet municipal emission requirements.
- Agriculture:Bulk grain and feed transport in remote locations with seasonal utilization patterns.
- Oil & Gas:Remote site logistics and pad construction in frontier basins with extreme climate exposure.
Mining commands premium pricing tiers. Construction is expanding most quickly.
Capacity:
Volume concentration follows mineral deposit scale, with above-60-ton units anchoring iron ore and copper operations while 10-25 ton classes serve quarry and construction niches. Margin structures invert across capacity tiers, with smaller units facing price competition from used equipment imports.
- Above 60 Tons:Ultra-class payload ratings require specialized transport for site delivery and dedicated maintenance infrastructure. BELAZ dominates 450-ton-plus fabrication with in-house Belarusian production. ISO 3450 braking recertification requirements complicate electric powertrain retrofits on downhill haul routes.
- 41-60 Tons:Mid-mining class bridges construction and extraction applications with flexible deployment economics. India's limestone sector is standardizing procurement around 50-ton platforms with Stage V-compliant engines. Komatsu's autonomous haulage integration targets this capacity band for retrofit conversion.
- 26-40 Tons:Quarry and aggregate standard with balanced acquisition cost and productivity metrics.
- 10-25 Tons:Compact construction and agriculture segments with high used-equipment substitution risk.
Above 60 Tons dominates installed base. 41-60 Tons is gaining share fastest.
Fuel Type:
Customer type divergence separates early electric adopters with grid infrastructure access from diesel-dependent remote operations. Maturity curves vary by geography, with electrification advancing fastest where renewable generation supports mine-site charging.
- Electric:Battery-electric powertrains eliminate tailpipe emissions and enable regenerative braking on descent hauls. Indonesia's Sulawesi nickel corridor is commissioning 240-ton rigid trucks with megawatt charging stations. High-voltage technician scarcity forces OEM field service embedding at customer sites.
- Hybrid:Diesel-electric architectures buffer engine load with battery storage for fuel efficiency gains. Chilean copper operators are piloting silicon-anode solid-state prototypes to accelerate direct-electric platform development. Steel and copper input volatility compresses margin predictability on fixed-price contracts.
- Diesel:Remains dominant in frontier mining without grid interconnection, though aftertreatment costs are rising.
- Gasoline:Limited to compact construction and utility applications with minimal market presence.
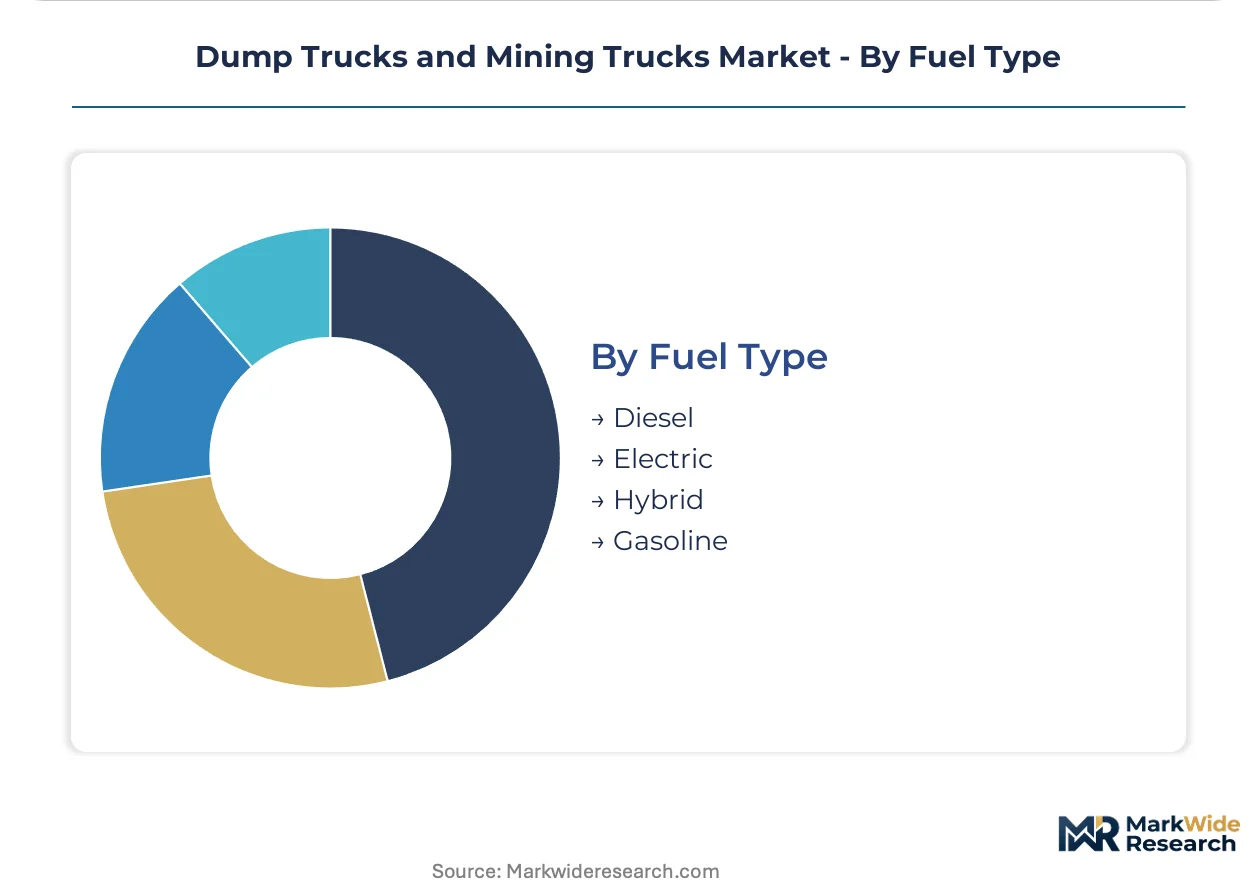
Diesel dominates installed base. Electric is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with Australian iron ore operators prioritizing autonomous fleet integration while Indonesian nickel miners emphasize electrification readiness on remote island concessions.
Australia
Western Australia's Pilbara region drives ultra-class rigid dump truck procurement for 24/7 iron ore haulage. The country's national mining safety regulator enforces autonomous haulage system certification standards that extend equipment validation timelines. Perth-based fleet operators negotiate total cost-per-ton contracts covering maintenance, energy, and residual value risk with OEMs.
China
Inner Mongolia's autonomous region concentrates demand for 300-ton-plus mining trucks serving rare earth surface extraction operations. The Ministry of Ecology and Environment tightens particulate matter enforcement for non-road mobile machinery, compelling domestic manufacturers to license European aftertreatment systems. Coal operators in Shanxi province consolidate procurement around compliant platforms from SANY and XCMG.
Chile
The Atacama copper belt anchors South American demand for diesel-electric hybrid powertrains with regenerative braking on high-altitude descent routes. The national mining regulator requires ISO 3450 braking performance recertification for electric powertrain retrofits. Antofagasta-based operators pilot silicon-anode solid-state battery prototypes with Tier 1 suppliers.
Indonesia
Sulawesi and Halmahera island mining concessions commission 240-ton electric rigid trucks with megawatt charging infrastructure for nickel corridor expansion. The country's energy ministry mandates renewable generation quotas for mine-site grid interconnection approvals. Morowali Industrial Park hosts integrated battery-to-truck supply chains serving export-oriented smelter operations.
United States
Nevada's gold-copper operations and Arizona's copper porphyry deposits sustain above-60-ton fleet renewals. EPA Tier 4 Final emission mandates accelerate replacement of pre-compliant mechanical drivetrain units. Elko County mining contractors source through direct OEM relationships rather than dealer networks for ultra-class specifications.
Dump Trucks and Mining Trucks Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive powertrain production and autonomous system integration separating premium positions from assembly-dependent competitors. The market structure rewards backward integration into engine manufacturing and control software development. Two dominant archetypes emerge: full-stack OEMs controlling powertrain-to-autonomy value chains, and payload-extreme fabricators specializing in 450-ton-plus categories. Competitive moves concentrate on strategic partnerships for battery cell supply and geographic expansion through lifecycle cost contracting.
Among integrated North American manufacturers, Caterpillar Inc. anchors the premium tier through captive powertrain production and autonomous haulage system integration. Komatsu Ltd. exemplifies the technology-forward archetype with vendor-agnostic autonomy kits for retrofit applications. BELAZ occupies a distinct position as a payload-extreme fabricator with in-house Belarusian production of 450-ton-plus mining trucks.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| BELAZ |
| Volvo Construction Equipment |
| Liebherr Group |
| Terex Trucks |
| Sany |
| XCMG Group |
| Others |
Supply Flow & Price Mechanics
Lifecycle cost-per-ton contracts in Western Australia's Pilbara region lock in multi-year supply access for ultra-class mining trucks while capping price volatility for operators. These performance-based agreements bundle maintenance, energy, and residual value risk with OEMs, compressing margin predictability for manufacturers while securing fleet renewal commitments from iron ore majors.
Pricing Analysis
Long-term offtake agreements dominate ultra-class procurement, with Rio Tinto and BHP negotiating total cost-per-ton haulage contracts covering sixty percent of fleet additions. Three-tier pricing structure across premium, standard, and economy levels separates autonomous-ready platforms from mechanical drivetrain units and used-equipment imports. Cost compression in the 10-25 ton articulated segment is intensifying because of high used-equipment substitution risk from Asian imports. Construction contractors exhibit highest price sensitivity, while mining operators prioritize lifecycle value over acquisition cost.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo trade lanes elevates inbound logistics costs for European aftertreatment systems licensed by Chinese manufacturers. Cell production for mining-class electric trucks clusters in China, South Korea, and Japan, drawing from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability in high-voltage battery supply exposes fleet operators to geopolitical supply interruptions. Distribution runs through direct OEM relationships for ultra-class units and independent dealer networks for construction-oriented models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dump trucks and mining trucks sit at a technology inflection where EPA Tier 4 Final and EU Stage V mandates are decomposing century-old mechanical drivetrain architectures around battery-buffered systems.
For Market Incumbents: Consolidate captive powertrain production and autonomous haulage system integration to defend margin control against emerging electric-only entrants. Backward integration into battery thermal management software and motor control systems anchors competitive position as solid-state chemistry accelerates direct-electric platform development.
For New Entrants and Emerging Players: Lead with battery-swapping standardization protocols and aftermarket retrofit autonomy packages for legacy mechanical trucks in Indonesia's nickel corridor. White-space concentrates in 240-ton electric rigid trucks for Sulawesi and Halmahera island concessions where grid interconnection mandates create electrification-ready demand.
For Investors and Strategic Acquirers: The market sits at a substitution phase that favors integrated OEMs with in-house powertrain production and control software development. Acquisition targets with captive battery supply agreements and mine-site charging infrastructure partnerships offer strongest five-to-ten year viability. Watch silicon-anode solid-state pilot results in Chile's Atacama copper belt as inflection signal for direct-electric platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cell capacity from East Asian suppliers for electric ultra-class platform launches. |
| Autonomous Haulage Integration | Reduces labor costs and shift-cycle variability for Pilbara iron ore operators. |
| Backward Integration | Captures margin control through in-house fabrication of welded steel frames and hydro-pneumatic suspension systems. |
| Long-term Service Contract | Bundles maintenance and residual value risk with OEMs under lifecycle cost-per-ton structures. |
| Geographic Manufacturing Footprint | Positions production near Indonesia's nickel corridor to serve battery-to-truck supply chains. |
Methodological Framework
Desk research of customs trade data, SEC filings, and national mining regulator disclosures preceded structured interviews with fleet procurement managers, OEM platform engineers, aftermarket service heads, and mine-site maintenance directors. Primary fieldwork across Australia's Pilbara region, Chile's Atacama copper belt, and Indonesia's Sulawesi nickel corridor combined with secondary validation from EPA certification databases and EU Stage V compliance registries. Bottom-up unit shipment estimates triangulated against top-down mineral extraction volume projections.
Variance decomposition across product type, capacity tier, fuel architecture, and regional regulatory cluster shaped analytical framework throughout the forecast period. CAGRs derived from slope-log regression on normalized shipment data with elasticity adjustments for commodity price cycles. Mine-site megawatt charging infrastructure deployment schedules and battery energy density trajectories served as key forecast inputs for electric segment penetration.
The analysis sits within stated boundaries; outcomes outside EPA Tier 4 Final compliance timelines or solid-state battery commercialization curves would require recalibration. Forecasts reflect assumptions on emission mandate enforcement intensity and grid interconnection approval velocities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Dump Trucks Market
Heavy-Duty Trucks
Hard Tonneau Cover Market
Heavy-Duty Trucks
Hydrogen Trucks Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
United States Refrigerated Trucking Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Medium and Heavy Duty Commercial Vehicles (MHCV) Market
Heavy-Duty Trucks
Heavy-Duty Vehicle Engine Brake Market
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Bucket Trucks Market