
 Heavy-Duty Trucks Market | 2026-2036
Heavy-Duty Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Trucks Market Analysis
EPA Phase 3 greenhouse-gas standards for heavy-duty vehicles is hardening the cost-of-entry calculus for manufacturers serving North America. Daimler Truck Holding AG leverages its integrated powertrain division to absorb compliance costs internally. Volvo Group anchors its position through sustained R&D intensity in battery-electric architectures. PACCAR Inc competes via specialized manufacturing scale concentrated in its U.S. and Mexican assembly plants.
Heavy-duty trucks denote commercial vehicles with gross vehicle weight ratings exceeding 33,000 pounds, typically employing ladder-frame chassis construction, multi-axle configurations, and diesel or alternative-fuel powertrains engineered for sustained high-torque operation over long-haul routes. Their primary purpose centers on moving bulk commodities, containerized freight, and specialized payloads across interstate and intraregional corridors. Diesel powertrain configurations still occupy the dominant revenue share, though electric powertrains are attracting fleet operator investment where charging infrastructure and total-cost-of-ownership thresholds align. Freight transportation applications generate the largest volume demand, while mining and construction segments sustain premium pricing for severe-duty specifications.
Federal EPA standards, California Air Resources Board mandates, and the EU Green Deal collectively shape product development timelines, emission certification costs, and market access conditions for manufacturers and fleet operators. The EU AI Act adds compliance layers for autonomous driving systems emerging in platooning and depot automation pilots. Stakeholders must monitor regulatory divergence between U.S. federal and state-level rules alongside European carbon-border adjustments that threaten to fragment supplier economics.
Market Dynamics
Zero-emission powertrain mandates are compressing diesel engine development cycles while forcing simultaneous investment in battery-electric and hydrogen fuel-cell architectures across all major manufacturing footprints.
Growth Catalysts
- EU Green Deal CO2 ceilings:Binding emission reduction mandates for heavy commercial fleets in Germany and France are accelerating fleet turnover timelines and expanding addressable market for alternative powertrains.
- Freight transportation electrification:Depot-based charging infrastructure deployment at major logistics hubs is enabling battery-electric truck deployment in predictable route applications.
- Battery energy density improvements:Solid-state and high-nickel chemistries are extending electric range capabilities into regional haul segments previously reserved for diesel.
Market Restraints
- Lithium and cobalt price volatility:Raw material cost swings for cathode active materials are compressing gross margins on battery-electric truck production.
- Semiconductor supply concentration:Power electronics and microcontroller sourcing remains concentrated in East Asian foundry capacity, creating single-point-of-failure exposure.
- EPA Phase 3 compliance costs:Certification and engineering expenses for meeting tightened greenhouse-gas standards are raising fixed cost thresholds for market entry.
Strategic Opportunities
- India commercial vehicle electrification:FAME-II subsidies and state-level EV policies are opening fleet electrification pathways in high-growth logistics corridors around Mumbai and Delhi.
- Autonomous depot automation:Convergence of lidar perception systems with vehicle-to-infrastructure communication is enabling yard truck automation at distribution centers.
- EU carbon border adjustment mechanism:Embedded carbon pricing on imported steel and aluminum is creating competitive advantage for European-based chassis and cab manufacturing.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks face acute shortages of electricians certified for 800V battery system servicing and thermal runaway containment.
- Multi-powertrain platform capex:Simultaneous engineering of diesel, battery-electric, and hydrogen fuel-cell variants is straining R&D allocation and tooling budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Trucks Market |
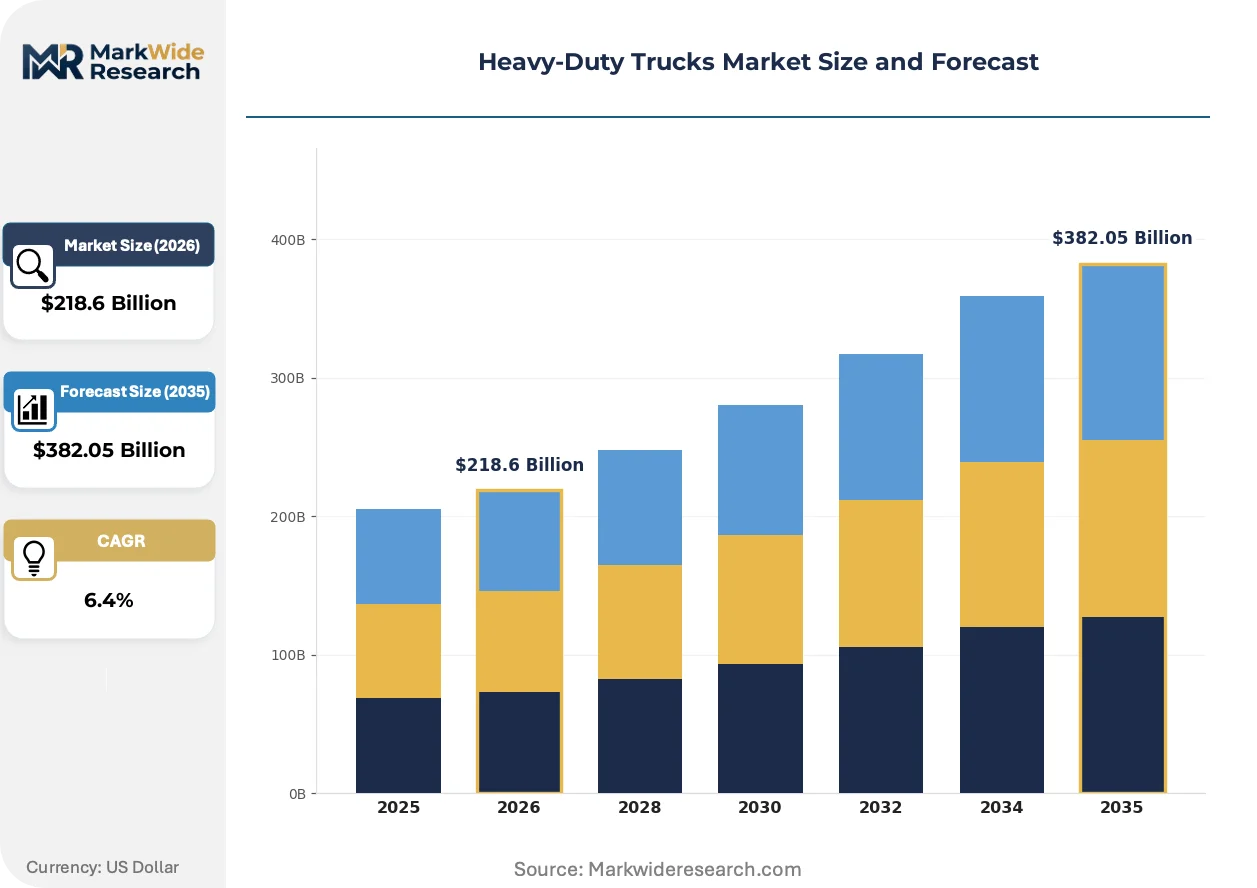
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $382.05 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Construction Trucks, Dump Trucks, Tow Trucks, Tank Trucks Powertrain: Diesel, Electric, Hybrid, Natural Gas Application: Freight Transportation, Construction, Mining, Agriculture End User: Logistics Companies, Construction Firms, Municipalities, Fleet Operators |
| Companies Covered | Daimler Truck Holding AG, Volvo Group, PACCAR Inc, Traton SE, Navistar International Corporation, Tata Motors Limited, China National Heavy Duty Truck, Hino Motors, Dongfeng Motor Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Trucks Market Emerging Trajectories
Powertrain diversification and digital freight matching are converging to reshape asset utilization models, while regulatory compliance automation is becoming a competitive differentiator in fleet procurement decisions.
Platooning coordination systems are automating highway convoy formation through vehicle-to-vehicle communication protocols that synchronize braking and acceleration across multiple trucks. Long-haul carriers in the southwestern United States are piloting these systems on interstate corridors with favorable regulatory frameworks. The technology is automating driver workload reduction and fuel consumption optimization in linehaul operations.
EPA Phase 3 greenhouse-gas standards are mandating substantial CO2 reductions from heavy-duty vehicles through model year 2032, with intermediate targets escalating compliance obligations. Engine manufacturers must certify powertrains across multiple duty cycles while maintaining thermal efficiency gains. Vocational truck segments face the steepest technology cost absorption challenges due to fragmented production volumes.
Fleet operators are consolidating supplier relationships around full-service lease providers who bundle vehicles, charging infrastructure, and energy management into single-contract arrangements. Large retail and e-commerce logistics buyers are displacing traditional equipment finance with usage-based models that transfer residual value risk. This consolidation is most visible in German and Dutch freight corridors where sustainability reporting requirements favor outsourced fleet management.
Heavy-Duty Trucks Market Segmentation
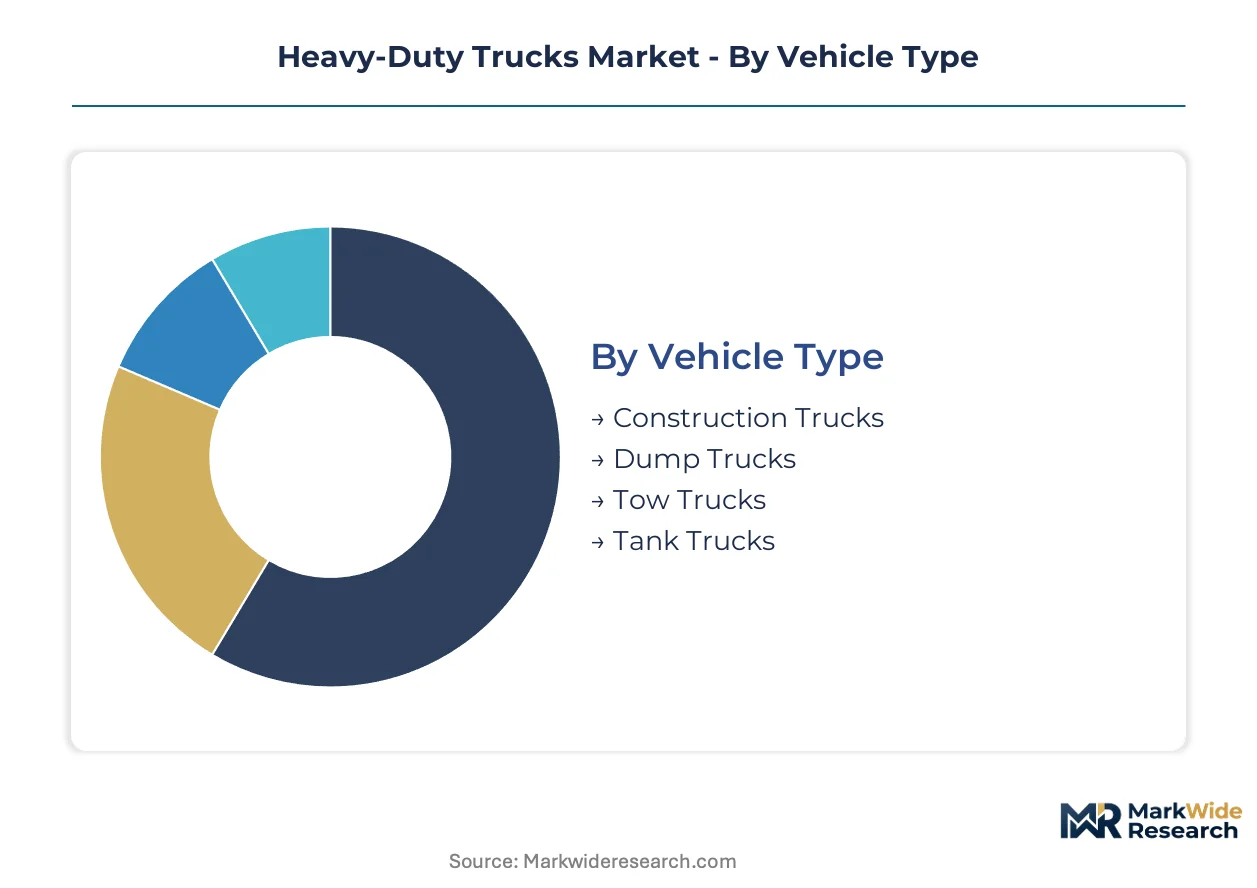
Heavy-duty truck segmentation reveals how distinct duty cycles, powertrain architectures, and ownership models create divergent performance requirements and procurement economics. Fleet operators prioritize specifications aligned with route predictability, payload density, and regulatory exposure in their respective operating geographies.
Vehicle Type:
Chassis architecture and body configuration determine gross vehicle weight ratings, axle load distributions, and specialized equipment integration capacity across vocational applications.
- Construction Trucks:Reinforced ladder-frame chassis with multi-leaf spring suspensions support concrete mixers, crane carriers, and concrete pump bodies. Demand concentrates in German urban renewal zones where EU Green Deal emission zones mandate Euro VI-e powertrains for inner-city work.
- Dump Trucks:High-strength steel bodies with hydraulic hoist mechanisms handle aggregates, demolition debris, and mining overburden. Severe-duty specifications dominate procurement in Australian iron ore corridors where payload-to-tare-weight ratios determine fleet economics.
- Tow Trucks:Integrated underlift and wheel-lift configurations service disabled commercial vehicles across interstate networks. Municipal contracts in California drive specification requirements through CARB-certified idle-reduction mandates.
- Tank Trucks:DOT 406/407 specification tank barrels transport refined fuels, chemicals, and food-grade liquids. Stainless steel barrel demand clusters around Rotterdam- Antwerp petrochemical hubs where ADR hazardous materials regulations govern cross-border movements.
Construction trucks lead on scale; dump trucks lead on momentum.
Powertrain:
Energy conversion architecture selection hinges on total-cost-of-ownership modeling across duty cycles, charging or fueling infrastructure availability, and residual value risk allocation between lessors and fleet operators.
- Diesel:Compression-ignition engines with selective catalytic reduction and diesel particulate filters remain dominant for irregular-route long-haul operations. EPA Phase 3 compliance costs are compressing engine development cycles while forcing thermal efficiency investments.
- Electric:Battery-electric architectures with 350-800V architectures and regenerative braking systems serve depot-based return-to-base routes. German logistics corridors around Duisburg and Munich show fastest fleet electrification where grid capacity supports megawatt charging.
- Hybrid:Parallel and series-hybrid configurations combining diesel prime movers with electric traction motors optimize stop-and-go vocational cycles. Refuse collection fleets in French metropolitan areas adopt these systems for brake wear reduction and noise compliance.
- Natural Gas:Spark-ignited or dual-fuel engines operating on compressed or liquefied natural gas serve regional haul corridors with established fueling infrastructure. Italian freight operators leverage existing methane pipeline networks for cost-advantaged fuel procurement.
Diesel retains volume dominance; electric gains share fastest.
Application:
Payload characteristics, operating terrain, and utilization intensity define suspension specifications, powertrain durability ratings, and cabin ergonomics requirements.
- Freight Transportation:Sleeper cab configurations with aerodynamic fairings and automated manual transmissions maximize fuel economy over interstate distances. E-commerce fulfillment networks in the Netherlands drive tractor-trailer specifications through sustainability-linked lease financing.
- Construction:All-wheel-drive chassis with locking differentials and high-ground-clearance suspensions navigate unimproved job sites. Indian infrastructure investment corridors around Mumbai-Nagpur expressway construction generate severe-duty demand.
- Mining:Extra-heavy-duty frames with reinforced crossmembers and cooling packages engineered for high-ambient-temperature operation haul overburden and ore concentrates. Western Australian Pilbara iron ore operations specify autonomous-ready chassis for future retrofit.
- Agriculture:Grain bodies and livestock trailers mounted on medium-heavy chassis serve seasonal harvest and livestock marketing cycles. Brazilian soy belt operators prioritize corrosion-resistant specifications for humid storage conditions.
Freight transportation leads on scale; construction leads on momentum.
End User:
Ownership structure and fleet scale determine procurement channel preferences, service contract terms, and technology adoption sequencing across customer segments.
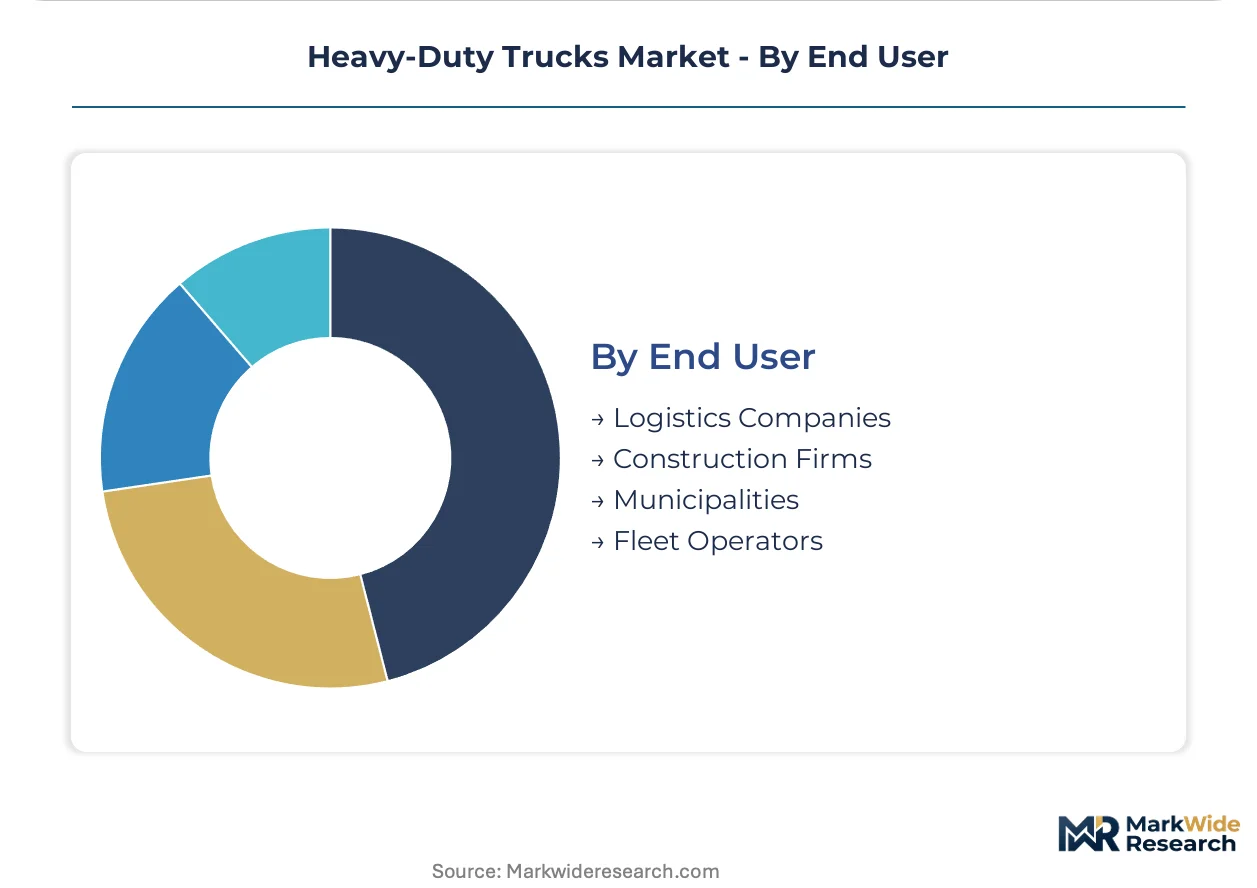
- Logistics Companies:Asset-heavy 3PL and dedicated contract carriage operators specify integrated telematics and fuel optimization systems. Deutsche Post DHL Group's fleet standardization programs influence European tractor specification trends.
- Construction Firms:Project-based contractors favor rental and lease arrangements with maintenance-inclusive terms to match equipment availability to contract duration. Bouygues Construction's equipment pooling models concentrate demand in French-speaking European markets.
- Municipalities:Public procurement regulations mandate lifecycle cost evaluation and local content requirements for sanitation, fire apparatus, and public works vehicles. Los Angeles Sanitation's zero-emission fleet mandates reshape North American refuse truck specifications.
- Fleet Operators:Full-service leasing providers bundle vehicles, maintenance, and energy management into single-contract arrangements. Penske Truck Leasing and Ryder System consolidation around sustainability reporting requirements drives standardized telematics deployment.
Logistics companies lead on scale; fleet operators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The heavy-duty truck industry traces its modern lineage to post-war German engineering clusters that pioneered ladder-frame chassis construction for long-haul freight. Manufacturing gravity subsequently dispersed across three continents as diesel engine technology matured and regional emission regimes proliferated.
Germany
Logistics operators in the Rhine-Ruhr corridor face binding CO2 reduction mandates under the EU Green Deal that compress fleet turnover timelines. The KBA enforces Euro VI-e certification requirements that disqualify older diesel powertrains from urban emission zones. Duisburg and Munich logistics hubs show fastest battery-electric truck deployment where grid capacity supports megawatt charging infrastructure.
United States
Long-haul carriers across southwestern interstate corridors pilot platooning coordination systems that synchronize braking through vehicle-to-vehicle protocols. EPA Phase 3 greenhouse-gas standards mandate substantial CO2 reductions through model year 2032, escalating compliance obligations for engine manufacturers. Los Angeles Sanitation's zero-emission fleet mandates reshape refuse truck specifications for municipal procurement nationwide.
China
Domestic freight volume expansion along the Beijing-Shanghai logistics corridor drives severe-duty chassis demand for containerized cargo movement. MIIT enforces dual carbon goals that accelerate battery-electric and hydrogen fuel-cell powertrain development timelines. Yangtze River Delta manufacturing clusters concentrate cab and chassis assembly capacity serving both domestic and export markets.
India
Infrastructure investment corridors around the Mumbai-Nagpur expressway generate construction truck demand for earthmoving and aggregate transport. FAME-II subsidies and state-level EV policies open fleet electrification pathways in high-growth logistics corridors. Maharashtra and Gujarat logistics operators consolidate procurement around full-service lease providers bundling vehicles with charging infrastructure.
Brazil
Soy belt agricultural operators prioritize corrosion-resistant chassis specifications for humid storage conditions during seasonal harvest cycles. ANVISA and environmental regulators impose emission standards that align with Mercosur trade bloc harmonization efforts. São Paulo and Paraná freight corridors concentrate tank truck demand for biofuel distribution and petrochemical feedstock movement.
Heavy-Duty Trucks Market Vendor Landscape
The competitive structure tilts toward diversified powertrain conglomerates with captive engine manufacturing capacity. Consolidated manufacturing footprints in Germany, Sweden, and the United States concentrate high-volume production while specialized regional assemblers serve protected domestic markets. Two strategic archetypes dominate: integrated powertrain manufacturers absorbing compliance costs internally, and scale-focused fabricators concentrating assembly in low-cost manufacturing zones. Competitive moves center on multi-powertrain platform engineering and strategic partnerships for battery cell sourcing.
Among European-based manufacturers, Daimler Truck Holding AG and Volvo Group exemplify the integrated powertrain archetype through captive engine and axle production. Traton SE occupies a position within the Volkswagen Group industrial portfolio that leverages shared component architectures across multiple truck brands. PACCAR Inc represents North American manufacturing concentration with assembly plant networks spanning the United States and Mexico.
| Leading Market Players |
|---|
| Daimler Truck Holding AG |
| Volvo Group |
| PACCAR Inc |
| Traton SE |
| Navistar International Corporation |
| Tata Motors Limited |
| China National Heavy Duty Truck |
| Hino Motors |
| Dongfeng Motor Group |
| Others |
Supply Flow & Price Mechanics
High-voltage technician scarcity in the Rhine-Ruhr corridor widens labor-cost differentials between premium certified-service tiers and economy maintenance channels, compressing margins on mid-market fleet contracts while elevating pricing power for integrated full-service lease providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified service bundles from independent workshop arrangements and unbranded component sourcing. Price differentiation hinges on EPA Phase 3 certification grade and after-sales service bundling intensity. Pricing pressure stems from lithium and cobalt cost volatility feeding into battery-electric truck production economics. Fleet operators exhibit highest price sensitivity in vocational segments with fragmented production volumes, while logistics companies leasing through full-service contracts show lowest sensitivity due to residual value risk transfer.
Supply Chain Analysis
Remanufacturing flows for diesel powertrain components create secondary supply channels that compete with new-part pricing in aftermarket service networks. Manufacturing concentration centers on Germany, Sweden, and the United States for cab and chassis assembly, with China dominating battery cell and power electronics production. Raw material dependencies rest on lithium carbonate from South American salares, cobalt from Central African mines, and high-grade steel from European integrated mills. Single-source vulnerability in East Asian semiconductor foundries threatens power electronics availability. Distribution runs through captive dealer networks for OEM parts alongside independent distributors serving price-sensitive fleet maintenance operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy-duty trucks market reads as a late-cycle quality story as fleet procurement shifts toward premium zero-emission specifications with integrated telematics and energy management bundling.
For Market Incumbents: Deepen backward integration into battery cell supply through joint ventures with Korean and Chinese manufacturers to secure cathode active material access against price volatility. Expand captive remanufacturing capacity in Mexico to offset EPA Phase 3 compliance cost absorption in North American diesel powertrain service networks. Prioritize certification investment for 800V high-voltage technician training programs to defend service revenue streams against independent workshop competition. For New Entrants and Emerging Players: Enter via India FAME-II subsidy corridors around Mumbai and Delhi logistics hubs where incumbent service networks remain underdeveloped and full-service lease penetration lags European benchmarks. Target municipal sanitation procurement in California CARB-compliant segments where zero-emission mandates displace incumbent diesel relationships. Pursue depot automation partnerships with lidar perception system providers as a go-to-market angle for yard truck electrification pilots. For Investors and Strategic Acquirers: Full-service leasing providers are the most active acquirer in this space as sustainability reporting requirements consolidate fleet management relationships around bundled vehicle-energy-telematics contracts. Long-term viability favors targets with captive charging infrastructure deployment capabilities and established high-voltage technician certification programs. Monitor EU carbon border adjustment mechanism implementation progress as an inflection indicator for European-based chassis manufacturing cost competitiveness against Asian import alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Powertrain Platform Standardization | Daimler Truck and Volvo Group reduce engineering duplication across diesel, electric, and hydrogen variants. |
| Battery Supply Agreement | Long-term cathode material offtakes insulate production margins against lithium price volatility. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities enable EPA compliance calibration without physical service visits. |
| Geographic Manufacturing Footprint | PACCAR's Mexico assembly concentration captures cost advantages for North American vocational segments. |
| Charging Infrastructure Partnership | Megawatt charging deployment at Duisburg and Munich logistics hubs accelerates fleet electrification timelines. |
Methodological Framework
Bottom-up freight transportation fleet modeling reconciled against top-down powertrain production tracking forms the analytical core. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet maintenance directors, and full-service lease operations managers combined with secondary validation from EPA certification databases, EU type-approval records, vehicle production registries, and customs trade data. Triangulation across stakeholder inputs and documentary sources established segmentation baselines for diesel, electric, hybrid, and natural gas powertrain categories.
Input-output matrices map powertrain architecture adoption to route predictability profiles, charging infrastructure availability, and regulatory compliance cost thresholds across the projection horizon. Segmentation dimensions span vehicle type, powertrain configuration, application duty cycle, and end-user ownership structure. CAGRs derive from fleet turnover rate modeling under binding CO2 mandate scenarios. Industry-specific forecast inputs include battery energy density improvement curves and grid capacity expansion timelines at major logistics corridors.
Inputs from OEM production disclosures and fleet operator procurement surveys were available through the study window; gaps in hydrogen fuel-cell infrastructure deployment data introduce uncertainty bands for long-haul zero-emission adoption trajectories. Forecasts reflect assumptions regarding EU Green Deal implementation consistency and EPA Phase 3 enforcement intensity. Practitioners should monitor lithium contract price settlements and megawatt charging standardization progress for early signals of electric powertrain total-cost-of-ownership inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Van Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Mining Truck Market