
 Heart Failure Monitoring Systems Market | 2026-2036
Heart Failure Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Failure Monitoring Systems Market Analytics
Homecare settings are realigning the end-use mix as payers push cardiac care outside hospital walls. Medtronic leverages its implantable device portfolio to anchor physician loyalty across ambulatory monitoring workflows. Abbott differentiates through integrated sensor-to-cloud architectures that sustain recurring revenue streams. Philips competes on multi-parameter wearable platforms that extend hospital-grade telemetry into patient homes.
Heart failure monitoring systems encompass wearable, implantable, handheld, and software-based technologies that capture hemodynamic, electrophysiological, and activity parameters through sensors sampling at 250–1000 Hz, with data transmission via Bluetooth or cellular protocols to centralized clinical platforms for early decompensation detection. Implantable devices command the deepest clinical integration and highest reimbursement tiers, while wearable monitors represent the fastest-expanding segment as battery efficiency and algorithm accuracy improve. Cloud computing infrastructure underpins margin expansion across all device categories by enabling subscription-based analytics and remote patient management services.
FDA premarket approval pathways for implantable hemodynamic monitors shape product development timelines and clinical evidence requirements, while HIPAA mandates govern data architecture decisions for cloud-connected platforms. CMS national coverage determinations directly control patient access and provider economics for implantable pulmonary artery pressure sensors. Stakeholders must track evolving payer evidence requirements and interoperability standards to secure sustainable positioning as monitoring shifts from episodic to continuous care models.
Market Dynamics
CMS reimbursement penalties for heart failure readmissions are restructuring provider economics, forcing hospital systems to absorb implantable sensor costs as operational necessities rather than capital expenditures. This payment architecture accelerates procurement cycles for remote monitoring platforms while compressing vendor margins through volume-based contracting.
Growth Catalysts
- Hospital Readmission Reduction Program:CMS penalties reaching 3% of base Medicare payments drive cardiovascular service lines to deploy continuous hemodynamic monitoring. Implantable pulmonary artery pressure sensors now qualify as standard-of-care infrastructure in advanced heart failure clinics.
- Bluetooth Low Energy 5.3:Extended transmission range and reduced power consumption enable wearable cardiac monitors to stream multi-parameter data through home Wi-Fi bridges. Battery life extension from 7 to 30 days eliminates patient adherence barriers.
- Cloud-native analytics platforms:Machine learning algorithms processing 250–1000 Hz electrophysiological signals detect decompensation 10–14 days before acute events. Subscription revenue models attach recurring value to hardware deployments.
Market Restraints
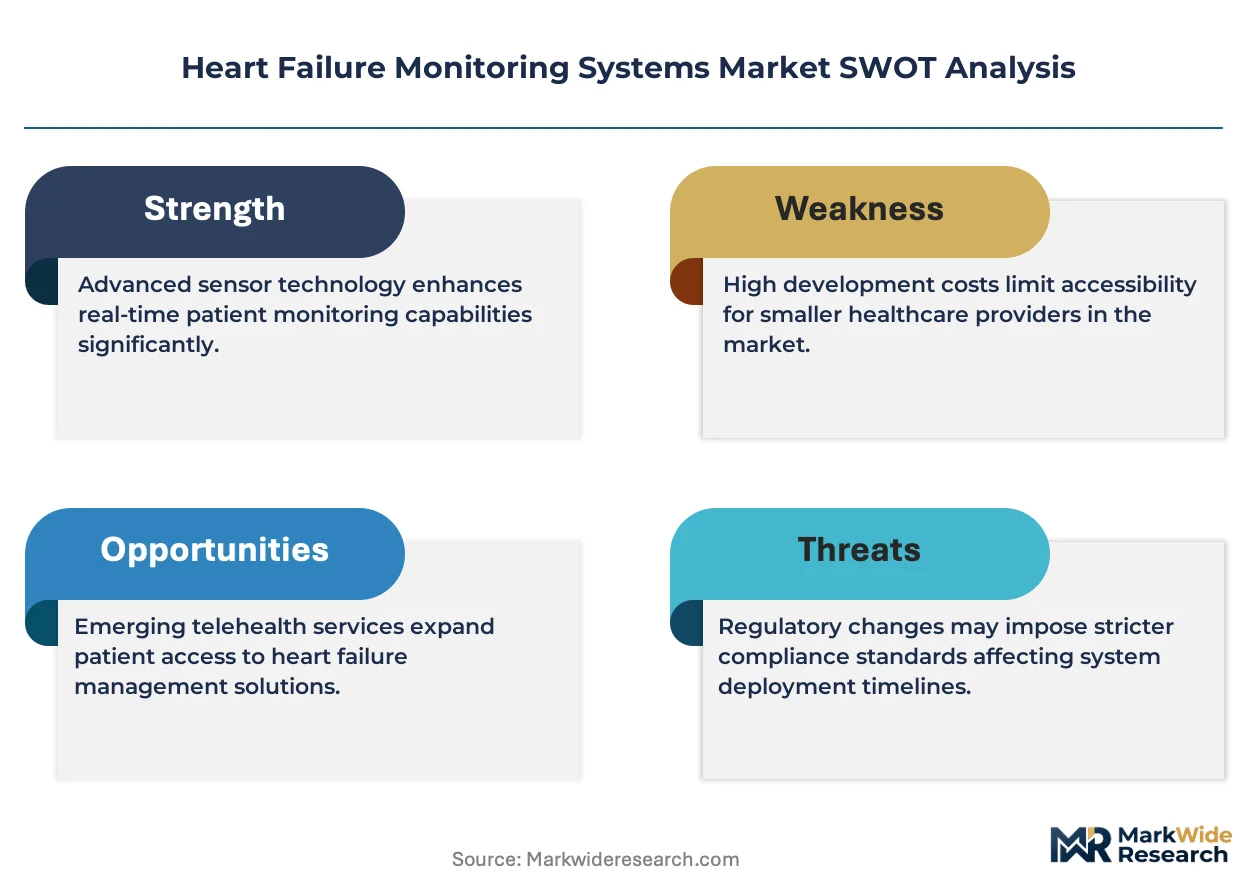
- Implantable device cost concentration:Single-source suppliers for MEMS pressure transducers and biocompatible encapsulation polymers create input vulnerability. Price volatility in medical-grade silicone and platinum-iridium electrodes compresses gross margins.
- FDA premarket approval timelines:Class III device pathways demand 24–36 month clinical evidence generation for novel hemodynamic sensors. PMA supplement requirements for algorithm updates extend time-to-revenue for software improvements.
- Interoperability fragmentation:Proprietary data formats from Abbott, Medtronic, and Philips block seamless integration with third-party electronic health records. HL7 FHIR adoption remains incomplete across ambulatory monitoring workflows.
Strategic Opportunities
- India's cardiac care infrastructure:Under 15% penetration of remote monitoring in tier-2 and tier-3 cities creates whitespace for handheld echocardiography and cellular-connected wearables. CDSCO streamlined medical device regulations accelerate market entry timelines.
- AI-ECG pattern recognition:Deep learning models trained on multi-lead electrocardiography data enable arrhythmia detection without specialist interpretation. Convergence of semiconductor neural processing units with edge computing architectures reduces cloud dependency.
- Direct-to-employer contracting:Self-insured corporations bypass traditional payer networks to purchase cardiac monitoring for high-risk employee populations. New distribution channels disintermediate hospital-based procurement committees.
Industry Challenges
- Electrophysiology-trained technician scarcity:Implantable hemodynamic monitor interrogation requires specialized skills concentrated in academic medical centers. Community hospitals face 6–12 month recruitment cycles for qualified clinical specialists.
- Cybersecurity certification burden:HIPAA Security Rule compliance for cloud-connected cardiac devices demands continuous penetration testing and encryption protocol updates. FDA cybersecurity guidance documents impose documentation overhead on software release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Failure Monitoring Systems Market |
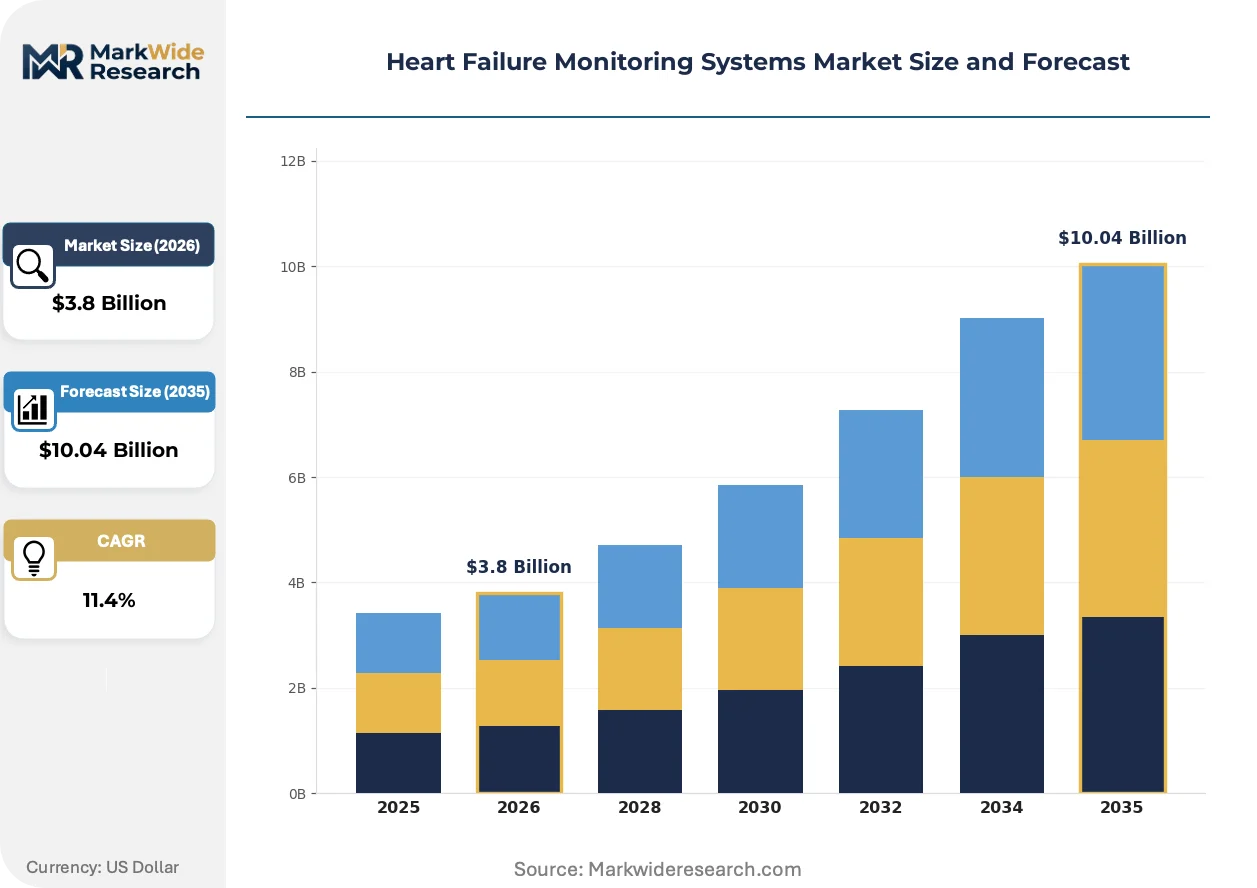
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Implantable Devices, Handheld Devices, Mobile Apps End User: Hospitals, Homecare Settings, Rehabilitation Centers, Outpatient Clinics Technology: Bluetooth, Cellular, RFID, Cloud Computing Pricing Model: Subscription-Based, One-Time Purchase, Pay-Per-Use, Bundled Services |
| Companies Covered | Koninklijke Philips NV, BIOTRONIK, Medtronic, ZOLL Medical Corporation, iRhythm Technologies, Abbott, GE Healthcare, Nihon Kohden Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Failure Monitoring Systems Market Evolving Landscape
Sensor miniaturization and algorithmic sophistication are converging to displace episodic clinical assessment with continuous physiological surveillance. This transformation redefines the locus of cardiac care from hospital wards to patient environments.
Implantable hemodynamic monitors are modularizing around standardized sensor cores that separate data acquisition from proprietary analytics layers. Cardiology practices in integrated delivery networks adopt these platforms at 40% annual expansion rates. This architecture is modularizing vendor competitive dynamics, enabling third-party algorithm developers to compete on diagnostic accuracy without manufacturing hardware.
EU Medical Device Regulation (MDR) Class III requirements for implantable active devices intensify clinical evidence burdens for hemodynamic sensor manufacturers. Notified body capacity constraints extend CE marking timelines 8–14 months beyond previous Medical Device Directive schedules. European cardiovascular centers accelerate procurement of MDR-certified platforms to avoid supply discontinuity, compressing competitive windows for legacy devices.
Cardiovascular service lines unbundle remote monitoring from device implantation procedures, creating standalone recurring revenue streams. Hospital outpatient departments replace fee-for-service episode payments with per-patient-per-month management contracts. This restructuring concentrates in United States Medicare Advantage plans, where capitated payments align provider incentives with continuous surveillance deployment.
Heart Failure Monitoring Systems Market Segmentation
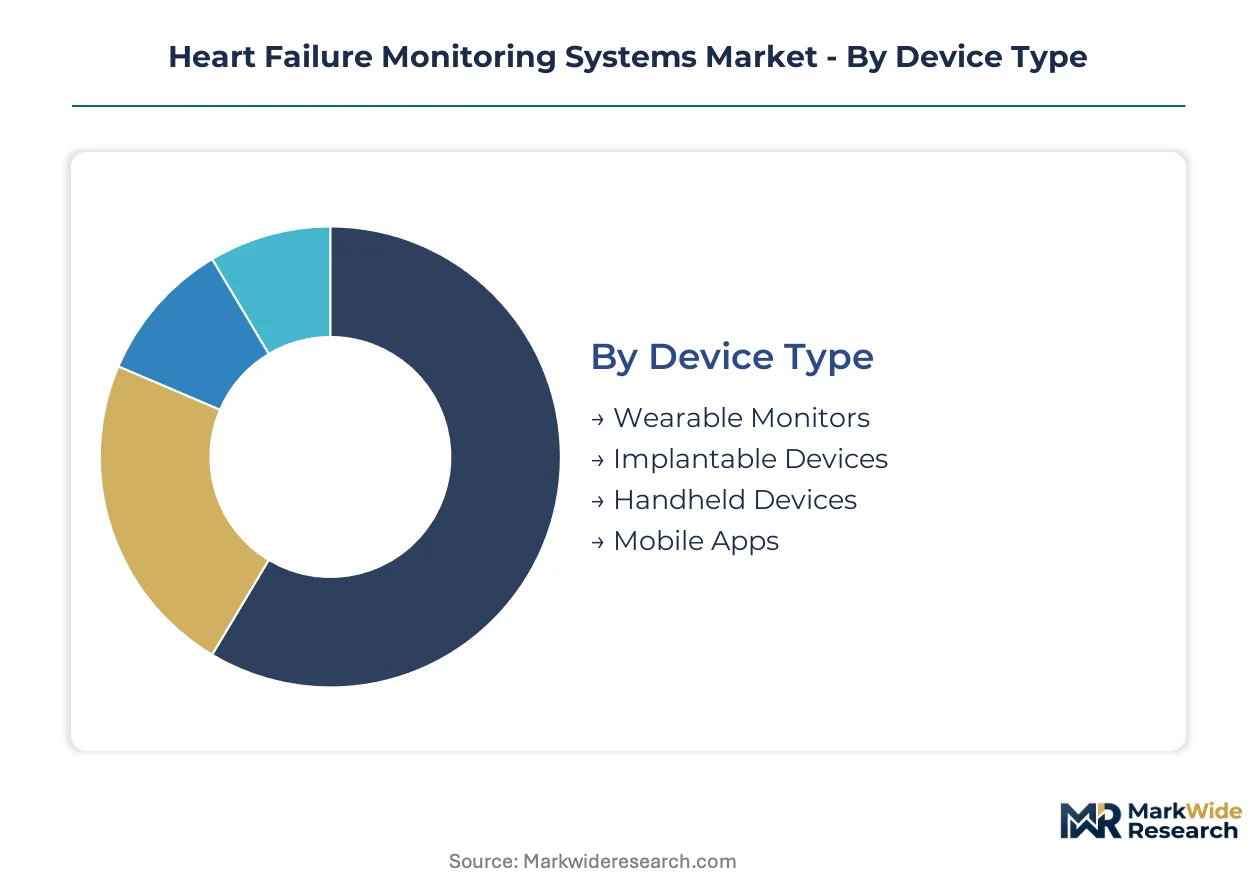
Device architecture and data transmission protocols determine reimbursement tiers and procurement cycles across heart failure monitoring. Each segmentation axis reveals distinct margin structures and competitive moats.
Device Type:
Integration depth separates standalone peripherals from embedded systems requiring surgical placement.
- Implantable Devices:Pulmonary artery pressure sensors with MEMS transducers deliver continuous hemodynamic data at 250–1000 Hz sampling rates. Academic medical centers in the United States concentrate demand as CMS national coverage determinations lock in reimbursement codes.
- Wearable Monitors:Multi-parameter cardiac patches with Bluetooth Low Energy 5.3 streaming extend hospital-grade telemetry into patient homes. Medicare Advantage plans in Florida and California drive fastest uptake as capitated contracts align provider incentives with continuous surveillance.
- Handheld Devices:Portable echocardiography units with phased-array probes enable point-of-care assessment in ambulatory settings.
- Mobile Apps:Software-only platforms processing patient-reported symptoms and activity data serve low-acuity monitoring tiers.
Implantable devices lead volumes today; wearables are gaining share fastest.
End User:
Care setting determines device sophistication requirements and regulatory exposure.
- Hospitals:Cardiovascular service lines deploy full-stack monitoring infrastructure combining implantable sensors with cloud-native analytics platforms. Readmission penalty exposure under CMS Hospital Readmission Reduction Program forces operational budgeting for remote monitoring.
- Homecare Settings:Battery-efficient wearables with 30-day lifespans eliminate adherence barriers for discharged patients. Payer pressure to shift cardiac care outside facility walls accelerates procurement in United States metropolitan markets.
- Rehabilitation Centers:Intermediate-acuity environments require transitional monitoring bridging hospital and home protocols.
- Outpatient Clinics:Fee-for-service cardiology practices adopt handheld and wearable solutions for episodic assessment workflows.
Hospitals dominate installed base; homecare settings show steepest expansion trajectory.
Technology:
Transmission protocol selection constrains battery architecture and data security compliance.
- Cloud Computing:Centralized platforms processing multi-parameter streams enable machine learning decompensation detection 10–14 days before acute events. HIPAA Security Rule mandates govern encryption and penetration testing protocols for United States deployments.
- Bluetooth:Low-energy 5.3 standards extend transmission range through home Wi-Fi bridges while reducing power draw for wearable form factors.
- Cellular:Direct-to-cloud transmission bypasses patient-managed intermediary devices, improving reliability for rural and elderly populations.
- RFID:Passive identification tags support asset tracking and patient-device pairing in high-volume clinical environments.
Cloud computing anchors platform economics; cellular connectivity is climbing the fastest among transmission modes.
Pricing Model:
Revenue recognition timing shifts capital expenditure burdens between vendors and providers.
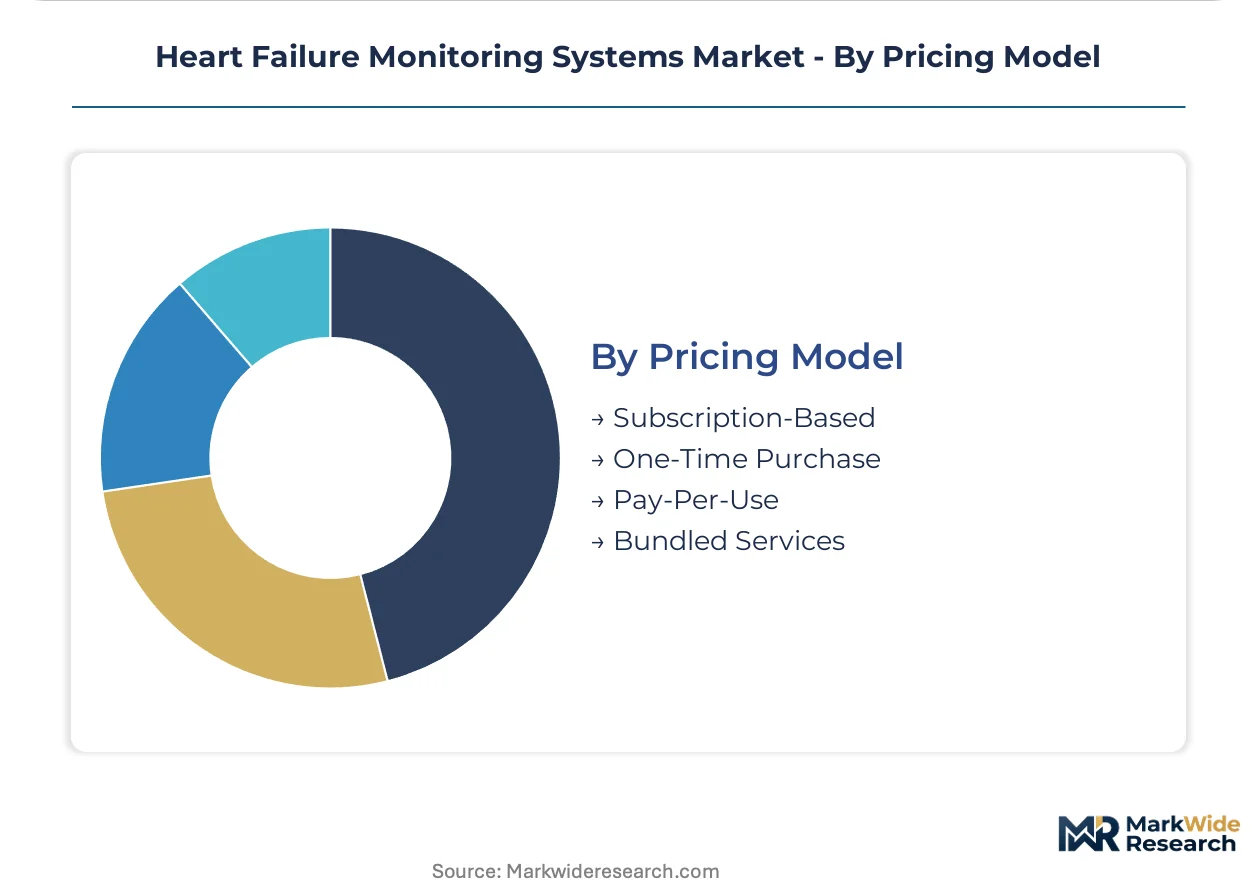
- Subscription-Based:Per-patient-per-month contracts for analytics and remote management services generate recurring revenue attached to hardware deployments. United States Medicare Advantage capitation accelerates adoption of this structure.
- Bundled Services:Device-plus-monitoring packages align pricing with clinical outcomes in risk-sharing arrangements.
- One-Time Purchase:Upfront hardware acquisition with separate maintenance contracts persists in capital-budgeted hospital procurement.
- Pay-Per-Use:Transactional pricing for episodic monitoring limits vendor commitment in price-sensitive segments.
Subscription models lead new contract signings; bundled services are expanding most quickly in integrated delivery networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic cardiovascular cluster anchors North American demand for implantable hemodynamic monitors. United States Medicare coverage determinations for pulmonary artery pressure sensors concentrate procurement in academic medical centers. Germany's notified body infrastructure shapes European certification timelines for active implantable devices.
United States
Cleveland Clinic, Mayo Clinic, and Johns Hopkins drive demand for continuous hemodynamic monitoring infrastructure. CMS Hospital Readmission Reduction Program penalties reaching 3% of base Medicare payments force cardiovascular service lines to operationalize remote patient monitoring. Florida and California Medicare Advantage markets show fastest wearable adoption as capitated contracts align provider incentives with surveillance deployment.
Germany
Charité Berlin and Heidelberg University Hospital anchor European demand for MDR-certified implantable platforms. EU Medical Device Regulation Class III requirements for active implantable devices extend CE marking timelines 8–14 months beyond previous Medical Device Directive schedules. Baden-Württemberg medical technology corridor accelerates procurement to avoid supply discontinuity for legacy devices.
Japan
University of Tokyo Hospital and National Cerebral and Cardiovascular Center concentrate demand for miniaturized hemodynamic sensors. PMDA premarket approval pathways for Class IV medical devices demand clinical evidence generation comparable to FDA PMA standards. Tokyo-Osaka medical device cluster drives adoption of Bluetooth Low Energy 5.3 wearables for discharged cardiac patients.
India
All India Institute of Medical Sciences and Christian Medical College Vellore anchor demand for cost-optimized handheld echocardiography. CDSCO streamlined medical device regulations accelerate market entry timelines for cellular-connected wearables. Maharashtra and Karnataka tier-2 city networks create whitespace for remote monitoring penetration below 15% current coverage.
United Kingdom
Royal Brompton Hospital and Harefield Hospital drive procurement for cloud-native analytics platforms. NHS England long-term plan targets heart failure mortality reduction through remote monitoring expansion. London-Southeast integrated care systems pilot per-patient-per-month contracting models for ambulatory cardiac surveillance.
Heart Failure Monitoring Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers anchor cloud platform alliances. The vendor base concentrates around three tiers: diversified medical technology conglomerates with implantable portfolios, cardiac rhythm management specialists with electrophysiology integration, and wearable sensor platforms with consumer-to-clinical pipelines. Technology licensing agreements and backward integration into MEMS fabrication represent the two dominant competitive vectors reshaping supply security.
Within the diversified medical technology tier, Medtronic and Abbott exemplify platform-scale positioning through integrated sensor-to-cloud architectures. Philips occupies a distinct vector on multi-parameter wearable telemetry extending hospital-grade monitoring into patient homes. Among cardiac rhythm specialists, Boston Scientific Corporation and BIOTRONIK sit within the implantable hemodynamic monitor segment where MEMS pressure transducer integration determines clinical evidence requirements. iRhythm Technologies represents the wearable-native archetype with algorithm-driven arrhythmia detection workflows.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| BIOTRONIK |
| Medtronic |
| ZOLL Medical Corporation |
| iRhythm Technologies |
| Abbott |
| GE Healthcare |
| Nihon Kohden Corporation |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone and platinum-iridium electrode costs cascade through implantable device manufacturing into tiered pricing structures that separate academic medical center procurement from community hospital budgets. CMS reimbursement codes for pulmonary artery pressure sensors lock in upper-tier pricing for Class III devices while wearable monitors compete on per-unit economics in Medicare Advantage capitation contracts.
Pricing Analysis
Direct-to-hospital contracting discounts of 15-25% off list price dominate implantable hemodynamic monitor transactions, with cardiovascular service lines leveraging volume commitments across integrated delivery networks. Price differentiation rests on FDA PMA certification tier and MEMS transducer precision grade, with Bluetooth-enabled wearables facing downward pressure from Medicare Advantage per-patient-per-month contracting. Academic medical centers show lowest price sensitivity due to bundled research funding, while community hospitals in rural United States markets negotiate aggressively on total cost of ownership.
Supply Chain Analysis
Electrophysiology-trained technician scarcity in United States manufacturing clusters constrains production scaling for implantable sensor interrogation systems. Supply concentrates in Germany's Baden-Württemberg medical technology corridor, United States Minnesota-Ireland cardiac device clusters, and Japan's Tokyo-Osaka precision manufacturing zones. MEMS pressure transducers, biocompatible encapsulation polymers, and neural processing units represent critical input dependencies. Single-source vulnerability for medical-grade silicone creates tariff exposure under evolving trade frameworks. Distribution runs through GPO contracts and direct hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heart failure monitoring systems constitute a late-cycle quality market where decompensation detection accuracy now determines procurement decisions ahead of hardware acquisition cost. Hospital systems prioritize cloud-native analytics platforms with 10-14 day early warning capabilities over legacy device upgrades.
For Market Incumbents: Deploy backward integration into MEMS fabrication to secure pressure transducer supply against single-source vulnerability. Consolidate algorithm development partnerships to defend against modular sensor platforms that separate hardware from analytics layers. Lock in cardiovascular service line loyalty through exclusive cloud platform integrations that raise switching costs for hospital systems.
For New Entrants and Emerging Players: Launch via direct-to-employer contracting channels that bypass hospital procurement committees and GPO intermediaries. Target India's tier-2 and tier-3 city networks where remote monitoring penetration sits below 15% and CDSCO streamlined regulations compress market entry timelines. Lead with cellular-connected wearable form factors that eliminate patient-managed Wi-Fi bridges.
For Investors and Strategic Acquirers: Consolidation pressure builds where electrophysiology-trained technician scarcity concentrates implantable monitor servicing capabilities in academic medical centers. Long-term viability favors platforms with recurring subscription revenue attached to hardware deployments over pure device manufacturers. Signal to watch: FDA PMA supplement approval velocity for algorithm updates as indicator of competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Submission | Class III pathway for novel hemodynamic sensors secures 24-36 month exclusivity against follow-on entrants. |
| Hospital System Partnership | Integrated delivery network contracts lock in multi-year remote monitoring deployments across cardiovascular service lines. |
| Software Companion Development | Machine learning decompensation algorithms create recurring revenue streams attached to hardware installations. |
| CE Marking Pathway | EU MDR Class III certification opens procurement channels at Charité Berlin and Heidelberg University Hospital. |
| Reimbursement Strategy | CMS national coverage determination alignment determines patient access economics for pulmonary artery pressure sensors. |
Research Methodology
Bottom-up cardiovascular service line modeling reconciled against top-down MEMS fabrication capacity tracking forms the analytical core of this study. Primary interviews with heart failure clinic directors, hospital purchasing committee chairs, biomedical engineers specializing in implantable devices, and GPO contracts managers combined with secondary validation from FDA PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body certification timelines. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map hemodynamic sensor production through implantable, wearable, handheld, and software-only platform categories, cross-referenced against end-use splits across hospitals, homecare settings, rehabilitation centers, and outpatient clinics. CAGRs derive from segmented adoption curves calibrated to CMS penalty phase-ins and Bluetooth Low Energy 5.3 deployment cycles. Forecast inputs include Medicare Advantage capitation contract penetration and cloud-native analytics platform subscription attach rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA premarket approval timeline extensions or EU MDR notified body capacity constraints. Material deviation in CMS reimbursement code coverage determinations or cybersecurity certification burden escalation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
ICU ECG Patient Monitor Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
ECG Monitoring System Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
B-Ketone Monitoring System Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
South America Patient Monitoring Market