
 Global Minimal Residual Disease Market | 2026-2036
Global Minimal Residual Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Global Minimal Residual Disease Market Foresight
Platform licensing revenue is fragmenting across specialized assay developers and broader diagnostic conglomerates. Adaptive Biotechnologies leverages its immune repertoire sequencing platform to anchor clinical partnerships with major cancer centers. Guardant Health competes through liquid biopsy infrastructure that extends from oncology screening into minimal residual disease surveillance. QIAGEN sustains its position by controlling sample-to-insight workflows that integrate PCR and NGS chemistries.
Minimal residual disease denotes the persistence of malignant cells below conventional morphologic detection thresholds, typically quantified at sensitivities of one tumor cell per 100,000 to 1,000,000 normal cells using molecular or immunophenotypic methods. The technology serves primarily to stratify relapse risk, guide therapy escalation or de-escalation, and validate complete remission in hematologic malignancies. Next-generation sequencing applications capture expanding margin pools as clinicians demand clone-specific tracking capabilities beyond bulk population assessment. Flow cytometry retains dominance in acute leukemia monitoring where rapid turnaround and established standardization protocols sustain clinical trust. Digital PCR segments show accelerating uptake in solid tumor MRD applications where ultra-low allele fraction detection drives technical specifications.
The FDA regulates MRD assays as in vitro diagnostics under premarket notification or approval pathways, while the EMA's IVDR transition imposes new clinical evidence requirements on European market access. ISO 15189 accreditation standards govern diagnostic laboratory quality management systems that underpin test result reliability for clinical decision-making. Stakeholders must monitor evolving payer coverage policies that increasingly predicate reimbursement on demonstrated impact on patient management decisions rather than analytical validity alone.
Market Dynamics
The FDA's breakthrough device designation pathway compresses commercialization timelines for novel MRD assays, while academic medical centers simultaneously expand testing protocols across hematology-oncology departments. This regulatory acceleration intersects with clinical demand for clone-specific tracking capabilities, creating structural pressure on laboratories to upgrade from bulk population assessment to next-generation sequencing workflows.
Growth Catalysts
- IRDAI Coverage Expansion:India's insurance regulator is mandating broader reimbursement for molecular diagnostics in hematologic malignancies, opening access to private hospital networks previously constrained by out-of-pocket payment requirements.
- ISO 15189 Accreditation Mandates:Diagnostic laboratories across Germany, Japan, and Australia face intensifying pressure to achieve quality management certification, driving standardization investments that validate test reliability for clinical decision-making.
- Digital PCR Sensitivity Thresholds:Solid tumor surveillance applications now demand ultra-low allele fraction detection below 0.01%, pulling assay developers toward droplet-based partitioning technologies that exceed flow cytometry resolution limits.
Market Restraints
- Reagent Supply Concentration:Polymerase enzymes and fluorophore-conjugated antibodies concentrate among three specialized biochemical suppliers in Switzerland and the United States, exposing assay manufacturers to input cost volatility and allocation rationing during demand surges.
- EMA IVDR Clinical Evidence Burden:Europe's in vitro diagnostic regulation imposes prospective performance studies on Class C devices, extending market access timelines and consuming capital that otherwise funds product pipeline expansion.
- Flow Cytometry Standardization Lock-in:Acute leukemia monitoring protocols rely on decade-old gating strategies and antibody panels, creating technical friction against molecular method adoption despite superior analytical sensitivity.
Strategic Opportunities
- Brazil's ANVISA Fast-Track Pathway:The national health surveillance agency offers priority review for oncology companion diagnostics, enabling first-mover positioning in a market where private oncology networks are consolidating under hospital group ownership.
- NGS-Flow Cytometry Convergence:Combined immunophenotypic and clonal sequence analysis on single platforms addresses the unmet need for standardized MRD quantification across B-cell malignancies where antigen drift complicates traditional monitoring.
- Direct-to-Oncologist Distribution:Specialized assay developers are bypassing reference laboratory intermediaries to place instruments and consumables directly within cancer center pathology departments, capturing margin previously allocated to third-party logistics.
Industry Challenges
- Bioinformatics Pipeline Validation:Clinical laboratories struggle to recruit computational biologists capable of implementing ISO 13485-compliant variant calling workflows, creating bottlenecks in assay deployment timelines.
- Multi-Platform Integration Complexity:Academic medical centers operate heterogeneous instrument fleets spanning PCR, flow cytometry, and sequencing chemistries, forcing expensive middleware development to harmonize data formats for longitudinal patient tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Minimal Residual Disease Market |
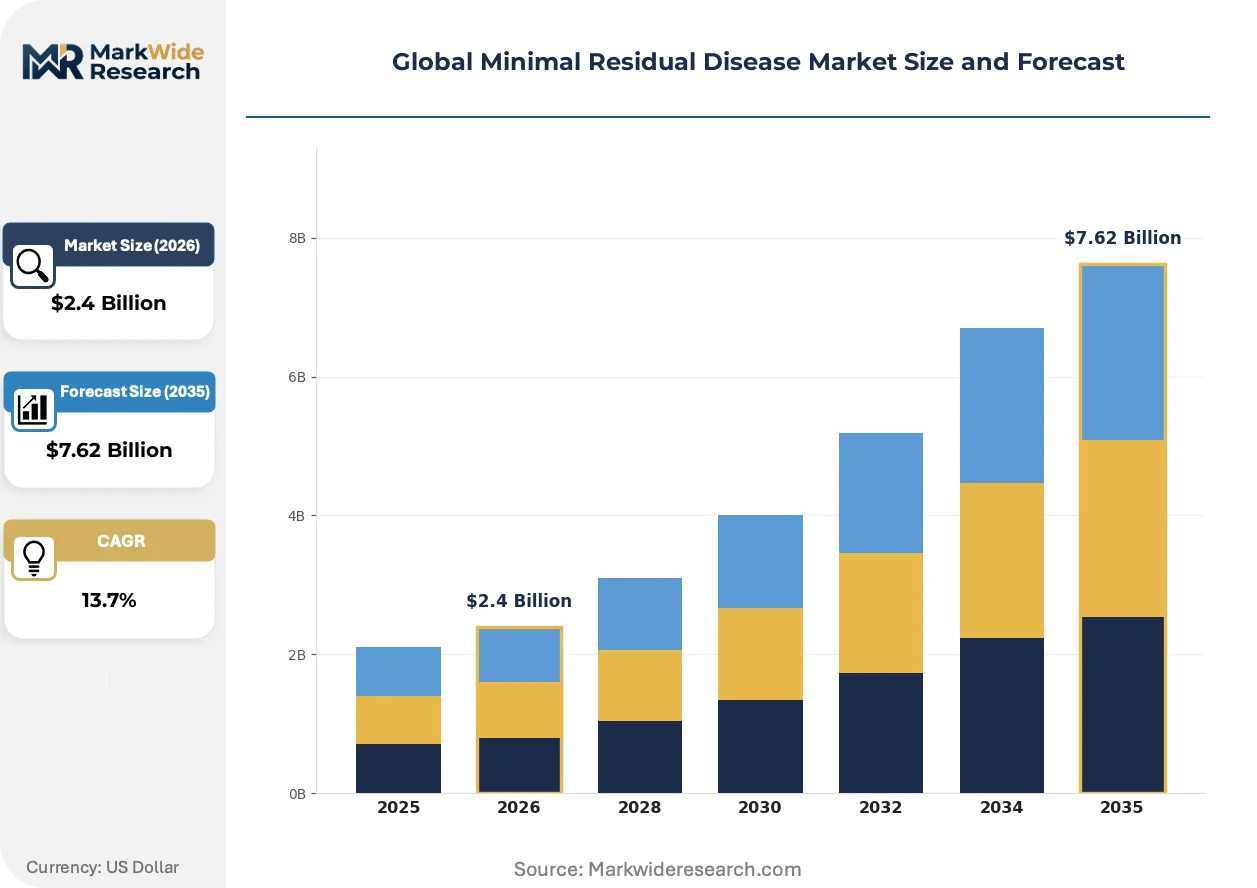
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Detection Technology: Next-Generation Sequencing, Flow Cytometry, Polymerase Chain Reaction, Digital PCR Application: Hematologic Malignancies, Solid Tumors, Recurrent Cancer, Post-Therapy Monitoring End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Academic Centers Sample Type: Bone Marrow, Peripheral Blood, Cerebrospinal Fluid, Tissue Biopsy |
| Companies Covered | Adaptive Biotechnologies, Guardant Health, Natera, NeoGenomics, Quest Diagnostics, QIAGEN, Bio-Rad Laboratories, Sysmex Corporation, Exact Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Minimal Residual Disease Market Shifts & Advancements
Assay developers are converging on integrated sample-to-insight workflows that compress turnaround times from blood draw to clinical report. This operational compression demands simultaneous advances in automation hardware, cloud-based variant interpretation, and regulatory science alignment across multiple jurisdictions.
ClonoSEQ and similar immune repertoire sequencing platforms are migrating from research-only deployment into routine clinical surveillance for multiple myeloma and acute lymphoblastic leukemia. Major cancer centers in the United States and Germany are adopting these assays at twelve-to-eighteen-month implementation cycles. The technology is migrating from bulk population assessment toward patient-specific clonal tracking, compressing the competitive window for laboratories that remain dependent on non-quantitative methods.
The European Union's Medical Device Regulation imposes notified body oversight on software-as-a-medical-device components within MRD analysis pipelines. Industrial consequence includes mandatory clinical performance studies for algorithms that classify sequence variants as malignant or benign. Hematologic oncology segments face the steepest compliance burden, with manufacturers responding through prospective validation cohorts that document impact on patient management decisions.
Oncology procurement departments are unbundling after-sales service contracts from instrument purchase agreements, forcing diagnostic suppliers to compete on per-test reagent pricing rather than capital equipment lock-in. Hospital networks in the Netherlands and Nordic countries lead this transition, replacing ten-year service bundles with competitive tendering for annual maintenance and software updates. Solid tumor MRD applications exhibit the most aggressive unbundling, as laboratories pilot multiple platforms before committing to standardized workflows.
Global Minimal Residual Disease Market Segmentation
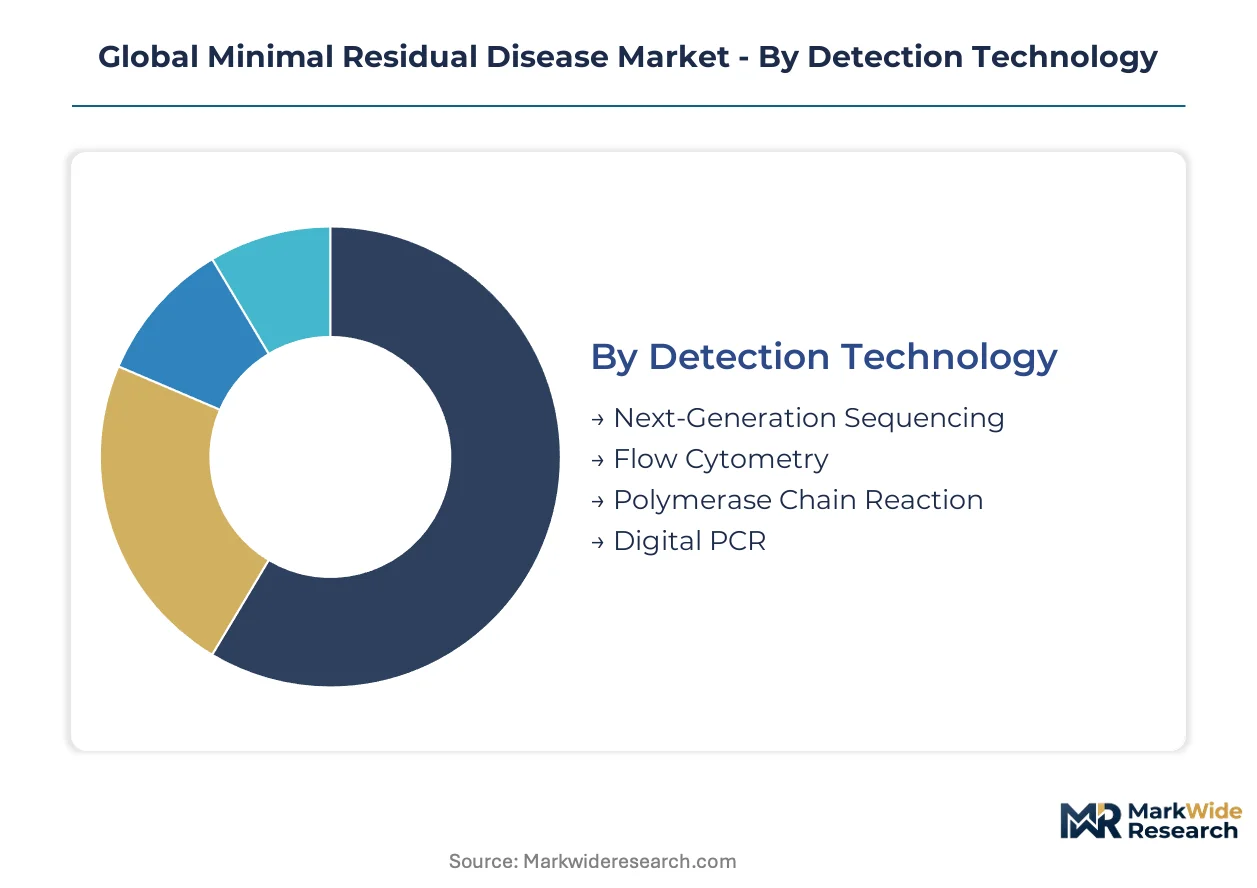
Segmentation in the minimal residual disease market reveals how technology maturity, clinical application, and institutional purchasing power intersect to determine competitive positioning. Understanding these divisions exposes where assay developers must concentrate R&D investment versus where operational efficiency drives margin capture.
Detection Technology:
The maturity spectrum spans decades-old methods to emerging platforms still validating clinical utility at scale.
- Next-Generation Sequencing:Immune repertoire sequencing enables clone-specific tracking at single-cell resolution, with academic medical centers in the United States and Germany adopting twelve-to-eighteen-month implementation cycles for routine surveillance in multiple myeloma and acute lymphoblastic leukemia. Demand concentrates where clinicians require antigen drift monitoring beyond flow cytometry capabilities.
- Flow Cytometry:Multi-parameter immunophenotyping maintains dominance in acute leukemia protocols where rapid turnaround and established gating strategies sustain clinical trust despite inferior analytical sensitivity to molecular methods. Hospital networks in the Netherlands prioritize this technology for its operational reliability and lower capital burden.
- Polymerase Chain Reaction:Allele-specific amplification remains cost-effective for targeted mutation monitoring in resource-constrained settings.
- Digital PCR:Droplet-based partitioning achieves ultra-low allele fraction detection below 0.01% for solid tumor surveillance applications.
Flow cytometry handles the majority of throughput; next-generation sequencing is expanding most quickly on share.
Application:
Application segmentation follows the progression from established hematologic protocols to emerging solid tumor opportunities.
- Hematologic Malignancies:Standardized MRD quantification in acute lymphoblastic leukemia, multiple myeloma, and acute myeloid leukemia drives the bulk of current testing volume, with Medicare coverage determinations in the United States broadening reimbursement access for circulating tumor DNA approaches.
- Solid Tumors:Colorectal, breast, and lung cancer surveillance represents the steepest expansion trajectory as ultra-low allele fraction detection requirements pull assay developers toward digital PCR and NGS workflows. Private oncology networks in Brazil are consolidating under hospital group ownership, creating concentrated demand for companion diagnostic integration.
- Recurrent Cancer:Early relapse detection protocols are gaining traction in Japan and Australia where ISO 15189 accreditation mandates validate test reliability.
- Post-Therapy Monitoring:Therapy de-escalation decisions increasingly depend on MRD negativity confirmation, particularly in pediatric oncology programs.
Hematologic malignancies anchor current revenue; solid tumors are gaining share fastest.
End User:
End user segmentation reflects divergent purchasing authority and technical sophistication across institutional types.
- Diagnostic Laboratories:High-throughput reference labs in Germany, Japan, and Australia face intensifying ISO 15189 accreditation pressure, driving middleware investments to harmonize heterogeneous instrument fleets spanning PCR, flow cytometry, and sequencing chemistries.
- Academic Centers:Major cancer centers are expanding testing protocols across hematology-oncology departments while simultaneously piloting direct-to-pathology distribution models that bypass reference laboratory intermediaries.
- Research Institutes:Prospective validation cohorts for algorithm classification consume significant capital as the EU Medical Device Regulation imposes notified body oversight on software-as-a-medical-device components.
- Pharmaceutical Companies:Clinical trial endpoints increasingly incorporate MRD negativity as a surrogate for survival, creating demand for standardized cross-platform comparability.
Diagnostic laboratories process the highest test volumes; academic centers are climbing the fastest on instrument placement.
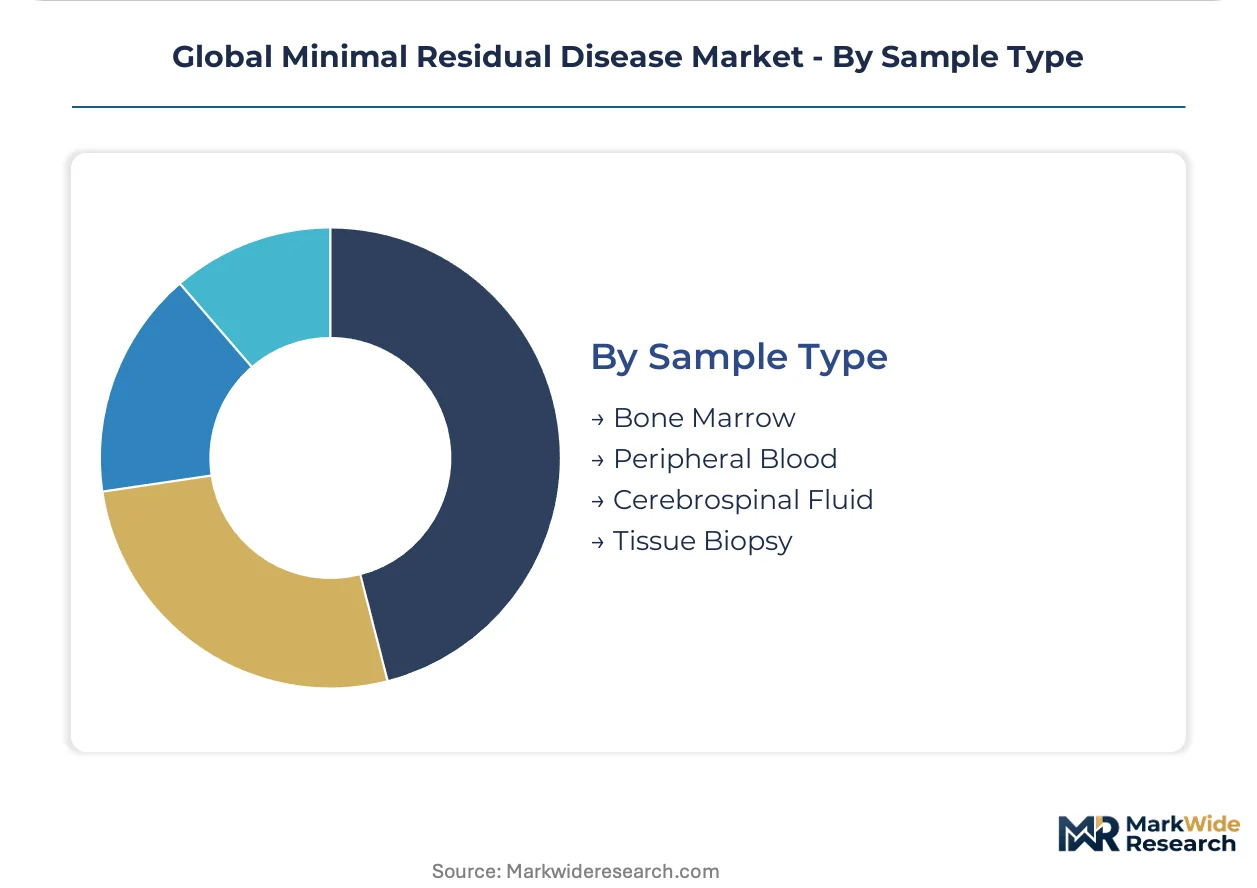
Sample Type:
Sample type segmentation tracks the migration from invasive tissue collection toward liquid biopsy alternatives.
- Peripheral Blood:Circulating tumor DNA extraction from plasma enables serial monitoring without repeated bone marrow aspiration, with India's IRDAI mandating broader reimbursement for molecular diagnostics in private hospital networks previously constrained by out-of-pocket requirements.
- Bone Marrow:Aspirate collection remains the reference standard for acute leukemia MRD assessment where cellular concentration exceeds peripheral blood sensitivity thresholds.
- Cerebrospinal Fluid:Central nervous system involvement detection in lymphoid malignancies requires specialized collection protocols and rapid processing.
- Tissue Biopsy:Solid tumor MRD applications increasingly favor archival tissue for clonal sequence identification rather than fresh collection.
Bone marrow dominates current protocol requirements; peripheral blood is advancing most rapidly on utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Private hospital networks in India face out-of-pocket payment constraints, while academic medical centers in Germany absorb premium pricing for ISO 15189-accredited workflows. Medicare coverage expansion in the United States eliminates cost barriers for circulating tumor DNA testing.
United States
Academic medical centers in Boston and Houston are expanding MRD testing protocols across hematology-oncology departments. The FDA's breakthrough device designation pathway accelerates commercialization timelines for novel assays. Major cancer centers in California are adopting twelve-to-eighteen-month implementation cycles for immune repertoire sequencing platforms.
Germany
Diagnostic laboratories in Munich and Heidelberg face intensifying pressure to achieve ISO 15189 quality management certification. The EMA's IVDR transition imposes new clinical evidence requirements on European market access. Hospital networks in North Rhine-Westphalia prioritize flow cytometry for its operational reliability and lower capital burden.
Japan
Early relapse detection protocols are gaining traction in Tokyo and Osaka where ISO 15189 accreditation mandates validate test reliability. METI standards govern diagnostic laboratory quality management systems. Research institutes in Kobe are conducting prospective validation cohorts for algorithm classification under tightened regulatory oversight.
India
IRDAI coverage expansion is mandating broader reimbursement for molecular diagnostics in hematologic malignancies. Private hospital networks in Mumbai and Bangalore previously constrained by out-of-pocket payment requirements are opening access to MRD testing. The country's national pharmaceutical regulator is streamlining approval pathways for oncology companion diagnostics.
Brazil
Private oncology networks in São Paulo and Rio de Janeiro are consolidating under hospital group ownership. ANVISA offers priority review for oncology companion diagnostics, enabling first-mover positioning. Laboratory clusters in Minas Gerais are piloting direct-to-pathology distribution models that bypass reference laboratory intermediaries.
Global Minimal Residual Disease Market Competitive Landscape
Specialized assay developers and broader diagnostic conglomerates split the market into competing capability clusters. Platform licensing revenue fragments across immune repertoire sequencing specialists and liquid biopsy infrastructure providers. Three archetypes dominate: immune repertoire sequencing platforms, liquid biopsy workflow integrators, and sample-to-insight workflow controllers. Strategic partnerships and direct-to-oncologist distribution represent the dominant competitive moves as laboratories bypass reference intermediaries.
Within the immune repertoire sequencing tier, Adaptive Biotechnologies exemplifies the clinical partnership anchor model. Guardant Health and QIAGEN occupy positions spanning liquid biopsy infrastructure and integrated workflow control respectively. These three companies represent the strategic archetypes reshaping competitive positioning: immune repertoire sequencing platforms that anchor cancer center partnerships, liquid biopsy specialists extending from screening into surveillance, and workflow controllers integrating PCR and NGS chemistries.
| Leading Market Players |
|---|
| Adaptive Biotechnologies |
| Guardant Health |
| Natera |
| NeoGenomics |
| Quest Diagnostics |
| QIAGEN |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| Exact Sciences |
| Others |
Supply & Pricing Matrix
Switzerland's specialized biochemical corridor around Basel concentrates polymerase enzyme production and fluorophore-conjugated antibody manufacturing, granting incumbent suppliers substantial leverage over assay developers who face allocation rationing during demand surges. This upstream concentration transmits directly into reagent pricing volatility and forces diagnostic manufacturers to absorb input cost shocks or pass them through to hospital laboratory customers.
Pricing Analysis
After-sales service contracts and extended maintenance agreements generate the majority of lifetime value for instrument manufacturers, though oncology procurement departments in the Netherlands and Nordic countries are aggressively unbundling these from capital purchases. Three-tier pricing structure across premium ISO 15189-accredited, standard certified, and economy non-accredited tiers separates academic medical centers from private hospital networks. Cost compression in the economy tier is intensifying because India's IRDAI-mandated reimbursement expansion exposes manufacturers to price-sensitive private hospital networks previously constrained by out-of-pocket payment requirements. Diagnostic laboratories exhibit the highest price sensitivity, while major cancer centers in Boston and Houston absorb premium pricing for clone-specific tracking capabilities.
Supply Chain Analysis
Contract manufacturing for diagnostic instruments concentrates among specialized EMS providers in Germany, Japan, and the United States who maintain cleanroom assembly capacity for PCR and sequencing platforms. Reagent production draws from Swiss biochemical suppliers for polymerase enzymes, United States specialty chemical manufacturers for fluorophore-conjugated antibodies, and German precision optics firms for flow cytometry components. Single-source vulnerability pervades the polymerase enzyme tier where three suppliers control global capacity. Distribution runs through reference laboratory intermediaries in most markets, though direct-to-pathology placement is displacing this model in Brazil's consolidating private oncology networks and select United States academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as solid tumor MRD applications migrate from research validation into routine clinical surveillance, with digital PCR and NGS workflows capturing share from established hematologic protocols.
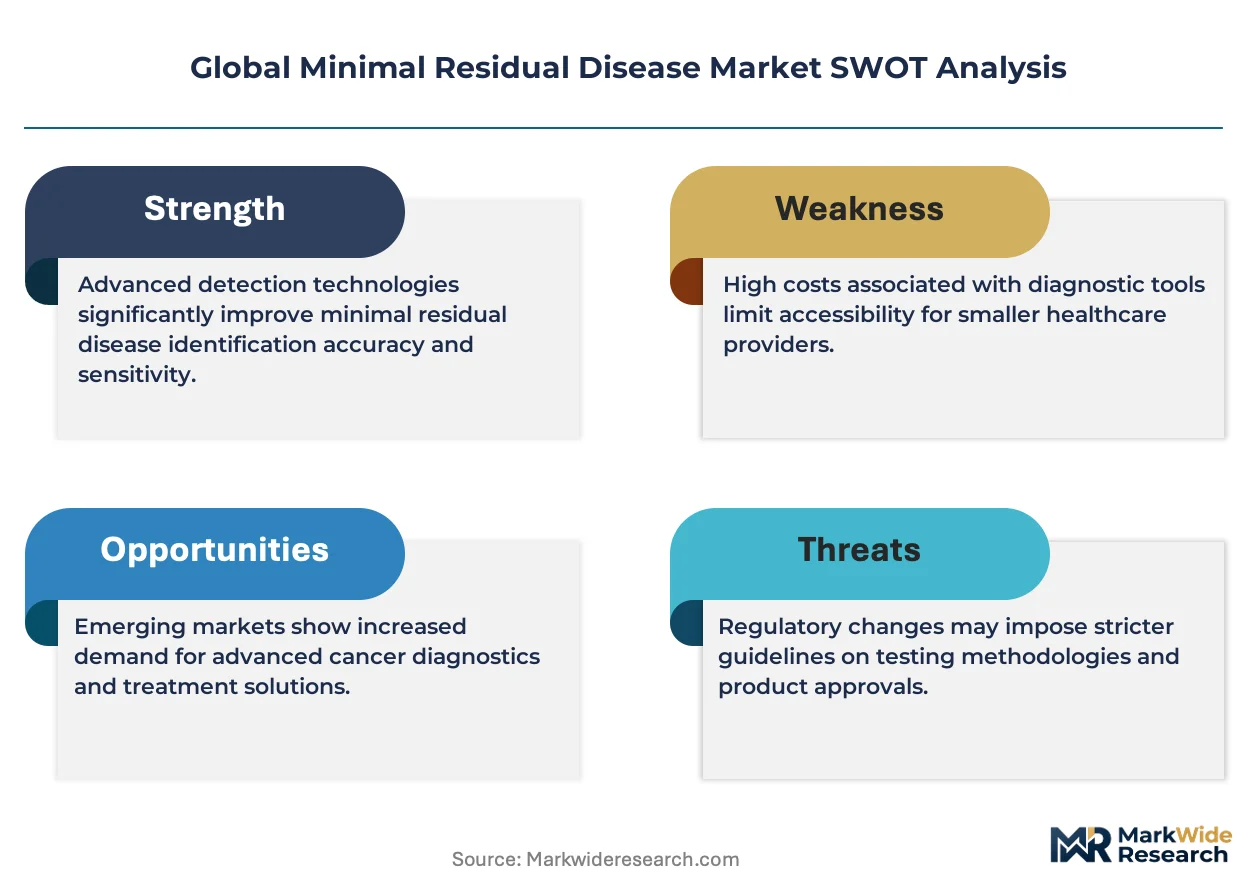
For Market Incumbents: Build regulatory data moats through prospective clinical performance studies that satisfy EMA IVDR requirements for Class C devices and FDA breakthrough device designation pathways. Deepen backward integration into polymerase enzyme supply through captive production or long-term offtake agreements with Swiss biochemical suppliers to defend against allocation rationing. Anchor cancer center partnerships with immune repertoire sequencing platforms before clone-specific tracking becomes commoditized. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA fast-track pathway where private oncology network consolidation creates concentrated demand for companion diagnostic integration. Target solid tumor surveillance applications in colorectal and lung cancer where ultra-low allele fraction detection requirements favor droplet-based digital PCR platforms over incumbent flow cytometry. Pursue direct-to-oncologist distribution models that bypass reference laboratory intermediaries and capture margin previously allocated to third-party logistics. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because assay developers with integrated sample-to-insight workflows will absorb point-solution specialists lacking cloud-based variant interpretation or automation hardware capabilities. Acquisition targets should display ISO 13485-compliant bioinformatics pipelines and established clinical utility evidence in hematologic malignancies. Watch for inflection when major cancer centers complete their twelve-to-eighteen-month NGS implementation cycles and shift procurement focus toward solid tumor applications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates commercialization timelines for novel MRD assays seeking Medicare coverage. |
| ISO 15189 Accreditation Investment | Validates test reliability for clinical decision-making in German and Japanese laboratories. |
| Direct-to-Pathology Distribution | Bypasses reference laboratory intermediaries to capture margin in Brazil's consolidating networks. |
| NGS-Flow Cytometry Platform Convergence | Addresses antigen drift monitoring needs in B-cell malignancies through combined analysis. |
| EMA IVDR Clinical Performance Studies | Satisfies notified body oversight requirements for software-as-a-medical-device components. |
Research Methodology
The analysis maps detection technology sub-sectors including immune repertoire sequencing, flow cytometry, digital PCR, and allele-specific amplification, each validated through hematologist-oncologists, diagnostic laboratory directors, and payer access specialists across academic medical centers and private hospital networks. Primary interviews with biomedical engineers, GPO contracts managers, and regulatory affairs leads at assay developers were cross-referenced against FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov MRD endpoint records, and CMS Medicare coverage determination databases. Bottom-up instrument placement and reagent consumption estimates were triangulated against top-down market size validation.
Assumptions held fixed include continued Medicare reimbursement expansion for circulating tumor DNA testing, EMA IVDR implementation timelines, and ISO 15189 accreditation mandates across Germany, Japan, and Australia. The analytical framework models segmentation across detection technology, application type, end-user institution, and sample source, with CAGRs derived from instrument placement velocity and per-test pricing trajectories across the projection horizon. Key inputs include academic medical center adoption cycle duration for NGS platforms and private oncology network consolidation rates in Brazil and India.
Sensitivities concentrate around EMA IVDR clinical evidence requirements extending market access timelines, polymerase enzyme supply disruptions from Swiss manufacturers, and payer policy shifts predicating reimbursement on patient management impact rather than analytical validity alone. Quarterly review of FDA breakthrough device designations, ANVISA approval pathways, and IRDAI coverage expansion implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market