
 Preimplantation Genetic Testing Market | 2026-2036
Preimplantation Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Preimplantation Genetic Testing Market Intelligence
The divergence between premium and commodity tiers is hardening in preimplantation genetic testing. High-complexity laboratories offering full chromosomal screening with rapid turnaround times command premium pricing, while basic aneuploidy screening becomes a table-stakes offering. Illumina, Inc. leverages its dominance in next-generation sequencing instrumentation to anchor laboratory workflows across major fertility networks. Thermo Fisher Scientific Inc. competes through integrated reagent and platform ecosystems that sustain recurring revenue streams.
Preimplantation genetic testing encompasses the biopsy and genetic analysis of embryos prior to uterine transfer, employing techniques such as trophectoderm biopsy at the blastocyst stage followed by whole-genome amplification and sequencing to detect chromosomal abnormalities or monogenic disorders. Its primary purpose centers on improving in vitro fertilization outcomes by selecting viable embryos and preventing heritable disease transmission. PGT-A commands the largest volume share as clinics standardize aneuploidy screening, while PGT-M captures concentrated margin pools due to complex probe design requirements for single-gene disorders. Next-generation sequencing displaces fluorescence in situ hybridization across technology adoption curves, though polymerase chain reaction retains utility in rapid-turnaround scenarios.
FDA oversight of laboratory-developed tests and CLIA certification requirements shape operational compliance burdens for clinical laboratories offering PGT services. State-level insurance mandates for infertility coverage, notably in Massachusetts and Illinois, directly influence patient access and demand patterns. EMA regulation of in vitro diagnostic medical devices under the EU MDR creates parallel compliance frameworks for European laboratories. Stakeholders must monitor evolving reimbursement codes and regulatory reclassification risks that could reshape laboratory economics and patient cost-sharing structures.
Market Dynamics
Next-generation sequencing is compressing turnaround times and expanding chromosomal resolution, forcing laboratories to retool workflows and retrain embryologists around massively parallel platforms.
Growth Catalysts
- State insurance mandates:Massachusetts and Illinois require infertility coverage, expanding patient access to PGT-A as a standard IVF protocol. Fertility networks in these states report higher screening penetration.
- Blastocyst-stage trophectoderm biopsy:This technique preserves embryo viability compared to earlier cleavage-stage methods, driving adoption across high-complexity laboratories seeking improved implantation rates.
- EU MDR harmonization:The European Medical Device Regulation creates unified compliance pathways for IVD manufacturers, reducing fragmentation across national markets and streamlining cross-border laboratory service expansion.
Market Restraints
- Sequencing reagent concentration:Three suppliers dominate library preparation chemistries, exposing laboratories to input cost volatility and supply allocation risk during manufacturing disruptions.
- FDA LDT oversight uncertainty:Pending reclassification of laboratory-developed tests threatens compliance cost escalation and potential validation requirements for existing PGT workflows.
- Fluorescence in situ hybridization legacy infrastructure:Capital equipment depreciation schedules and trained technician pools slow displacement timelines in mid-tier fertility clinics.
Strategic Opportunities
- Polygenic risk scoring integration:Convergence of polygenic score algorithms with PGT-A workflows enables complex trait screening, opening margin pools beyond aneuploidy detection in premium-tier laboratories.
- Direct-to-consumer genetic counseling:Telehealth platforms bypass traditional clinic-mediated referral chains, capturing patients earlier in fertility decision journeys.
- India's draft Assisted Reproductive Technology Regulation:Pending national standards for PGT service quality create first-mover positioning for accredited laboratories entering this underpenetrated market.
Industry Challenges
- Embryologist training pipeline:Trophectoderm biopsy competence requires 100+ supervised procedures, creating certification bottlenecks that constrain laboratory expansion velocity.
- CLIA high-complexity director scarcity:Qualified laboratory directors with reproductive genetics specialization command premium compensation, elevating fixed cost structures for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preimplantation Genetic Testing Market |
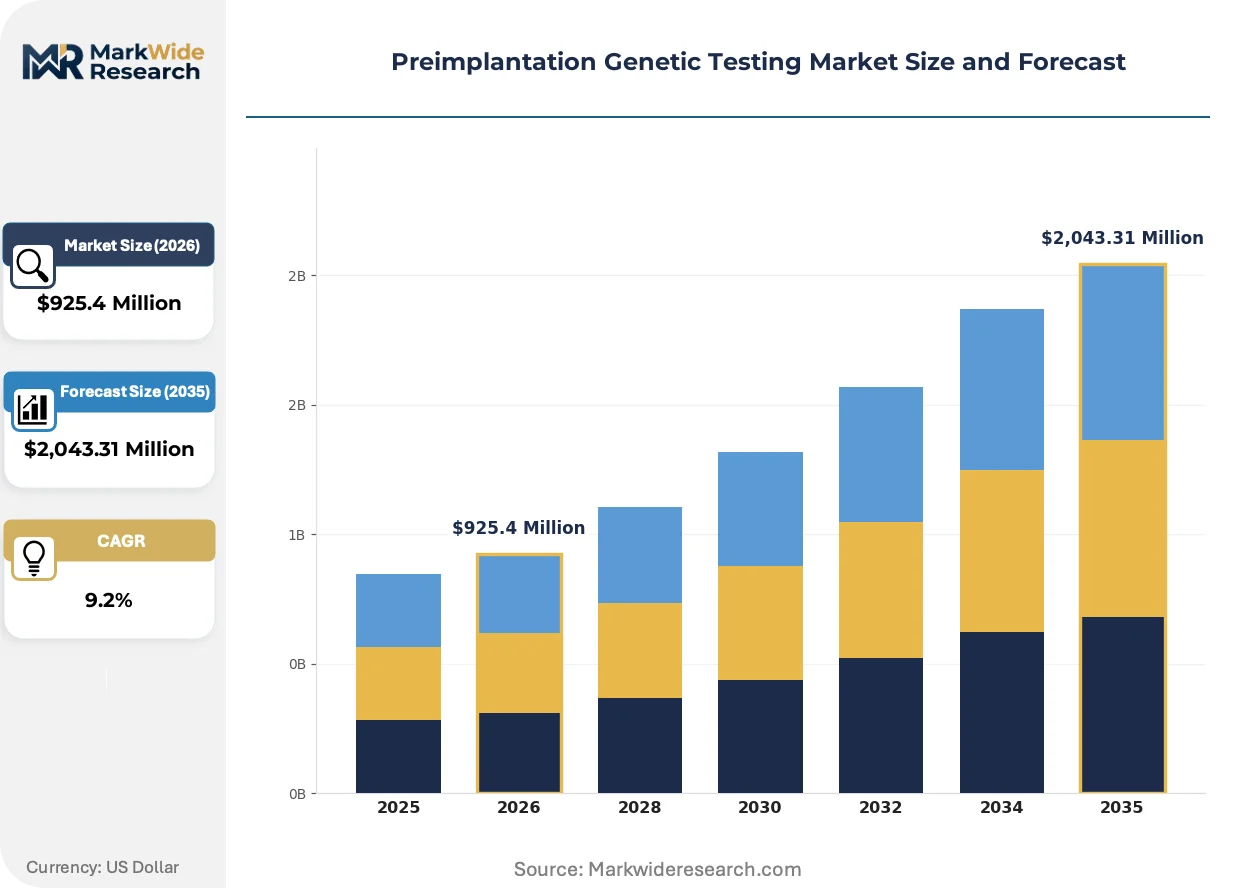
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $2,043.31 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PGT-A, PGT-M, PGT-SR, Comprehensive Chromosomal Screening Technology: Next-Generation Sequencing, Microarray Analysis, Polymerase Chain Reaction, Fluorescence In Situ Hybridization Application: Fertility Treatment, Genetic Disorder Prevention, Research & Development, Embryo Selection End User: Fertility Clinics, Hospitals, Research Laboratories, Diagnostic Centers |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., Natera, Inc., CooperSurgical, Inc., Agilent Technologies, Inc., Quest Diagnostics Incorporated, Igenomix, Laboratory Corporation of America Holdings, Revvity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preimplantation Genetic Testing Market Strategic Shifts & Innovations
Workflow automation and artificial intelligence classification tools are compressing embryologist labor intensity while raising diagnostic consistency thresholds across laboratory networks.
Next-generation sequencing is rewriting laboratory economics by collapsing per-sample reagent costs and enabling simultaneous chromosomal and monogenic analysis. High-volume fertility networks in the United States are completing platform transitions within eighteen-month windows. This technology is compressing the price premium between PGT-A and PGT-M service tiers.
EU MDR Article 10 clinical evidence requirements are forcing IVD manufacturers to generate prospective performance data for PGT platforms. Smaller reagent suppliers face documentation burdens that favor integrated platform vendors with regulatory affairs infrastructure. European laboratories are consolidating supplier relationships to reduce audit complexity.
Patients are initiating PGT discussions before clinic selection, reversing traditional physician-driven referral patterns. Digital health platforms and genetic counseling apps capture these upstream decisions, redirecting patient flow toward laboratories with direct consumer interfaces. This behavior shift concentrates volume in the United States among networks with integrated telehealth capabilities.
Preimplantation Genetic Testing Market Segmentation
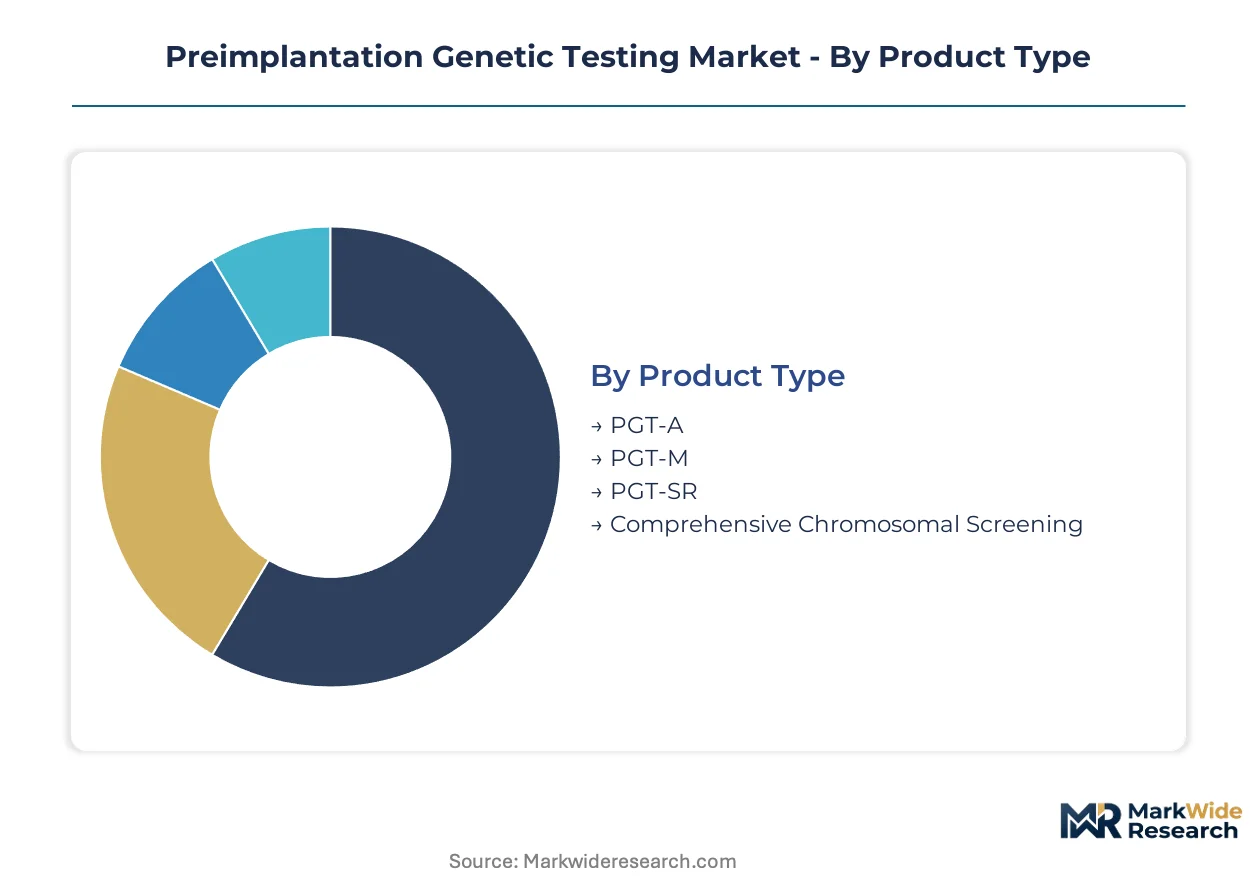
Preimplantation genetic testing segments along four dimensions that shape procurement decisions and laboratory investment priorities. Product type determines reimbursement codes and clinical utility, while technology selection locks laboratories into multi-year platform commitments with distinct workflow architectures.
Product Type:
Supply concentration in sequencing instrumentation favors laboratories offering expanded screening panels over single-purpose assays.
- PGT-A:Aneuploidy screening detects chromosomal abnormalities across all 23 chromosome pairs using whole-genome amplification protocols. United States fertility networks in Massachusetts and Illinois standardize this as baseline IVF protocol under state insurance mandates.
- PGT-M:Monogenic disorder testing requires custom probe design for single-gene mutations, concentrating demand in academic medical centers with reproductive genetics specialization. Complex validation workflows sustain premium pricing tiers.
- PGT-SR:Structural rearrangement screening identifies balanced translocations and inversions in parental karyotypes.
- Comprehensive Chromosomal Screening:Full chromosomal profiling combines aneuploidy detection with subchromosomal copy-number analysis.
PGT-A absorbs the bulk of installed capacity; Comprehensive Chromosomal Screening is expanding most quickly.
Technology:
Cost tier differentiation separates high-throughput sequencing platforms from legacy cytogenetic methods.
- Next-Generation Sequencing:Massively parallel platforms collapse per-sample reagent costs while enabling simultaneous chromosomal and monogenic analysis. High-volume United States fertility networks complete platform transitions within compressed eighteen-month windows.
- Microarray Analysis:Comparative genomic hybridization arrays deliver intermediate resolution for copy-number variation detection. Mid-tier laboratories deploy this technology where sequencing infrastructure investment exceeds patient volume thresholds.
- Polymerase Chain Reaction:Rapid-turnaround amplification retains utility in time-sensitive embryo transfer decisions.
- Fluorescence In Situ Hybridization:Legacy capital equipment and trained technician pools slow displacement timelines in smaller fertility clinics.
Next-Generation Sequencing commands dominant capital allocation; Polymerase Chain Reaction maintains niche utility in rapid-turnaround scenarios.
Application:
Volume concentration tracks fertility clinic expansion and research funding flows.
- Fertility Treatment:IVF protocol integration drives routine PGT-A utilization in United States commercial fertility networks. Standardized workflows and state-level insurance coverage expand addressable patient populations.
- Genetic Disorder Prevention:Carrier screening cascade identifies at-risk couples prior to conception, concentrating demand in preconception counseling programs.
- Research & Development:Academic laboratories generate prospective performance data for EU MDR clinical evidence requirements.
- Embryo Selection:Morphokinetic analysis integration with genetic screening optimizes single-embryo transfer outcomes.
Fertility Treatment absorbs the bulk of procedure volume; Genetic Disorder Prevention is climbing the fastest as carrier screening expands upstream.
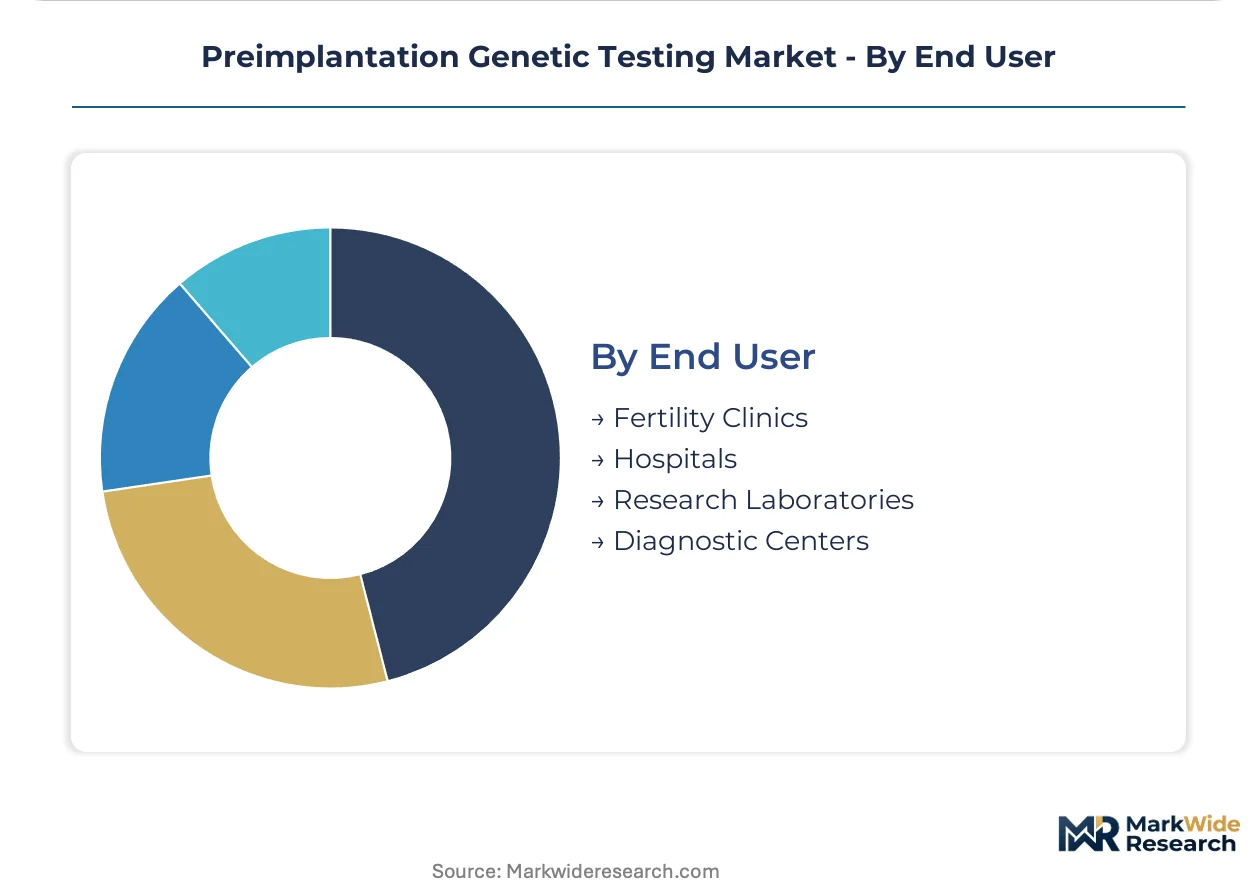
End User:
Customer type determines service complexity and reimbursement pathway.
- Fertility Clinics:Specialized reproductive medicine centers integrate biopsy and genetic analysis within single-site workflows. United States networks with multi-state presence capture economies of scale in sequencing batch processing.
- Hospitals:Academic medical centers combine PGT-M capabilities with pediatric genetics and prenatal diagnostic services.
- Research Laboratories:Institutional investigators generate clinical evidence for regulatory submissions and algorithm development.
- Diagnostic Centers:Independent reference laboratories offer outsourced PGT analysis to smaller fertility practices lacking in-house sequencing infrastructure.
Fertility Clinics absorb the bulk of testing volume; Diagnostic Centers are gaining share fastest as outsourced models penetrate mid-tier markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors preimplantation genetic testing demand through its concentration of academic medical centers and fertility networks. State-level insurance mandates in Massachusetts and Illinois expand patient access. Laboratories across these clusters complete sequencing platform transitions within compressed timelines.
United States
Fertility networks in Massachusetts and Illinois standardize PGT-A under state insurance mandates. FDA oversight of laboratory-developed tests shapes compliance frameworks for clinical laboratories. Boston and New York Metro host high-complexity laboratories completing next-generation sequencing transitions.
Germany
Academic medical centers in Baden-Württemberg and Bavaria concentrate PGT-M capabilities for monogenic disorder testing. EMA regulation under EU MDR creates unified compliance pathways for IVD manufacturers. Heidelberg and Munich laboratories generate prospective clinical evidence for regulatory submissions.
United Kingdom
London fertility networks integrate PGT-A within standard IVF protocols for private patient segments. Human Fertilisation and Embryology Authority licensing requirements govern laboratory accreditation. Cambridge research clusters develop polygenic risk scoring algorithms for embryo selection.
Spain
Barcelona and Madrid fertility clinics attract cross-border reproductive tourism through competitive pricing tiers. National health system reimbursement varies by autonomous community, creating regional access disparities. Catalan laboratories specialize in trophectoderm biopsy training programs for European embryologists.
Japan
Tokyo academic medical centers combine PGT-M with pediatric genetics services. PMDA oversight of reproductive technologies limits commercial expansion compared to Western markets. Osaka laboratories retain polymerase chain reaction capabilities for rapid-turnaround embryo transfer decisions.
Preimplantation Genetic Testing Market Key Industry Players
Capital-heavy sequencing platform producers compete with asset-light laboratory service providers across tiered market positions. The vendor base separates into integrated instrumentation suppliers, specialized reagent manufacturers, and fertility network laboratories with captive testing capacity. Three strategic archetypes dominate: platform-anchored conglomerates sustaining recurring revenue through consumable lock-in; independent reference laboratories capturing outsourced volume from mid-tier clinics; and academic medical centers retaining complex PGT-M capabilities. Competitive moves concentrate on sequencing platform transitions and regulatory compliance infrastructure investments.
Among platform-anchored instrumentation suppliers, Illumina, Inc. and Thermo Fisher Scientific Inc. exemplify the capital-intensive archetype sustaining laboratory workflow dependencies. Natera, Inc. occupies a position within the independent reference laboratory tier. These named entities anchor industry-level commentary without specific factual claims about individual strategic actions or market positions.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| Natera, Inc. |
| CooperSurgical, Inc. |
| Agilent Technologies, Inc. |
| Quest Diagnostics Incorporated |
| Igenomix |
| Laboratory Corporation of America Holdings |
| Revvity |
| Others |
Cost & Logistics Intelligence
State insurance mandates in Massachusetts and Illinois are compressing patient out-of-pocket exposure while expanding screening volumes, forcing laboratories to absorb cost efficiencies through sequencing platform consolidation and reagent contract restructuring.
Pricing Analysis
Turnaround-time guarantees anchor value-based pricing tiers across fertility network laboratories. Three-tier pricing structure across premium, standard, and economy levels separates rapid-result PGT-M from batch-processed PGT-A and basic aneuploidy screening. Cost compression in standard-tier screening is intensifying because next-generation sequencing per-sample economics collapse with volume scale. Price-sensitive mid-tier fertility clinics in non-mandated states drive commoditization pressure, while academic medical centers with CLIA high-complexity directors sustain premium capture.
Supply Chain Analysis
Domestic-content requirements for CLIA-certified laboratory operations in the United States are reshaping sourcing toward FDA-registered reagent manufacturers. Library preparation chemistries concentrate supply among vendors in the United States, Germany, and Japan. Sequencing instrumentation draws from captive consumable ecosystems. Single-source vulnerability runs through Illumina's dominance in next-generation sequencing flow cells. Distribution runs through direct laboratory sales forces and fertility network procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence requirements and FDA LDT reclassification uncertainty are accelerating consolidation, eliminating laboratories lacking regulatory affairs infrastructure and prospective data generation capabilities.
For Market Incumbents: Anchor market position through backward integration into trophectoderm biopsy training programs, creating certification bottlenecks that constrain competitor laboratory expansion. Lock fertility networks into multi-year sequencing platform leases with embedded reagent minimums, defending against independent reference laboratory encroachment. For New Entrants and Emerging Players: Launch via telehealth-integrated genetic counseling platforms that capture patients upstream of clinic selection, bypassing established referral chains. Target India's pending ART regulatory framework for first-mover laboratory accreditation, exploiting underpenetrated demand among urban fertility centers. For Investors and Strategic Acquirers: Re-rating potential sits with independent reference laboratories possessing EU MDR technical documentation and CLIA high-complexity director bench strength given pending regulatory compliance cost escalation. Long-term viability favors assets with multi-state fertility network contracts and integrated sequencing infrastructure. Watch FDA LDT reclassification timing as volume inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Sequencing Platform Transition | Next-generation sequencing displacement of FISH collapses per-sample costs while expanding chromosomal resolution for fertility networks. |
| EU MDR Technical Documentation Investment | Prospective clinical evidence generation for PGT platforms satisfies EMA Article 10 requirements and streamlines cross-border service expansion. |
| Telehealth Genetic Counseling Integration | Direct-to-consumer patient capture upstream of clinic selection reverses traditional physician-driven referral patterns toward laboratories with digital interfaces. |
| Trophectoderm Biopsy Training Program Development | Embryologist certification bottlenecks constrain competitor expansion velocity while creating captive demand for accredited laboratory services. |
| Multi-State Fertility Network Consolidation | Economies of scale in sequencing batch processing concentrate volume among laboratories with geographic footprint spanning insurance-mandated states. |
Research Approach
Independent corroboration across laboratory directors, fertility network procurement officers, regulatory affairs specialists, and reproductive geneticists underwrites the qualitative findings. Primary interviews with CLIA high-complexity directors, embryology training program administrators, and IVD manufacturer product managers combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, state insurance mandate legislative records, and fertility clinic accreditation databases. Bottom-up procedure volume estimates and top-down sequencing reagent consumption patterns were triangulated to anchor market sizing.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and insurance coverage expansion patterns structured the analytical framework. Segmentation dimensions modeled include product type, technology platform, application setting, and end-user category across the projection horizon. CAGRs were derived from fitted adoption curves weighted by state-level mandate implementation schedules and sequencing platform transition velocities. Forecast inputs incorporated embryologist training pipeline constraints and CLIA director availability by metropolitan statistical area.
FDA LDT reclassification timing, EU MDR notified body capacity constraints, and sequencing reagent supply disruptions are the dominant revision risks. Forecasts reflect assumptions regarding regulatory stability and laboratory accreditation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market