
 Cell-Free Fetal DNA Testing Market | 2026-2036
Cell-Free Fetal DNA Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cell-Free Fetal DNA Testing Market Outlook
Software-defined assay interpretation and cloud-based variant reporting is realigning what laboratories purchase, shifting value from standalone instruments to recurring informatics subscriptions. Natera, Inc. leverages proprietary algorithms to anchor its Panorama platform in physician-ordered workflows. Illumina, Inc. sustains dominance in sequencing hardware while extending into secondary analysis software. Laboratory Corporation of America Holdings competes through national logistics networks that control specimen collection and turnaround times.
Cell-free fetal DNA testing isolates and analyzes fragments of placental DNA circulating in maternal blood, typically requiring a minimum fetal fraction threshold of four percent for reliable aneuploidy detection via massively parallel sequencing. The technology enables non-invasive screening for chromosomal abnormalities without amniocentesis risk. Non-Invasive Prenatal Testing occupies the largest revenue pool due to universal screening recommendations from professional obstetric societies. Massively Parallel Sequencing leads technology adoption as laboratories phase out microarray-based approaches for higher sensitivity. Physician-Ordered delivery mode captures the dominant share, though telehealth-integrated ordering is gaining traction among fertility clinics seeking remote patient management.
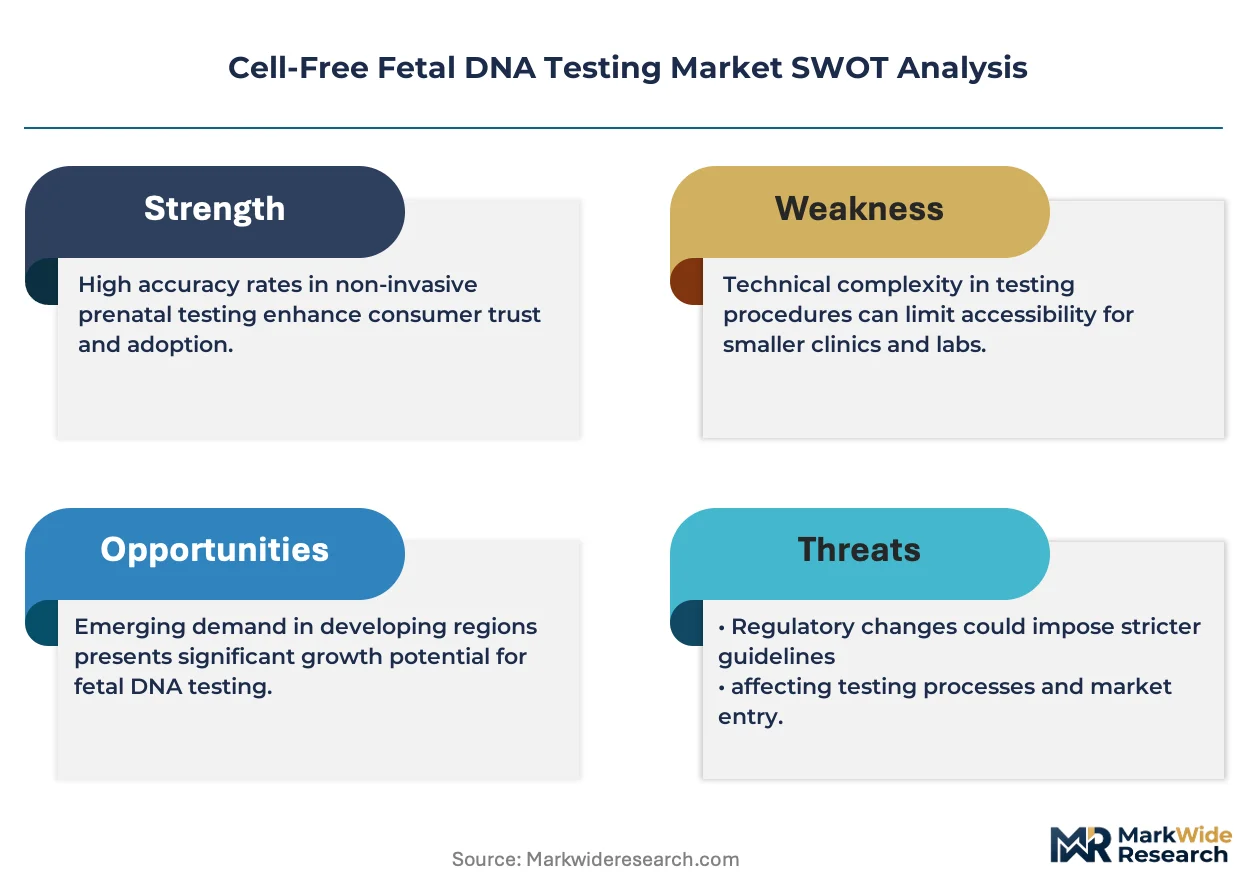
The FDA regulates cfDNA testing as high-complexity laboratory-developed tests under CLIA oversight, while the EU In Vitro Diagnostic Regulation mandates CE marking and performance documentation for European market access. Germany's national screening committee evaluates evidence thresholds for public reimbursement, directly shaping commercial viability across European prenatal care systems. Japan's PMDA oversees clinical validation requirements that determine which platforms enter its concentrated hospital market. Stakeholders must monitor evolving reimbursement decisions from CMS and parallel national bodies, as coverage determinations will dictate whether cfDNA screening expands from high-risk to average-risk pregnancies or contracts to targeted indications.
Market Dynamics
The transition from microarray-based screening to massively parallel sequencing is compressing laboratory capital cycles and forcing mid-sized diagnostic facilities into platform consolidation decisions.
Growth Catalysts
- Professional guideline expansion:Obstetric societies in the United States and Germany now recommend universal cfDNA screening for average-risk pregnancies, eliminating prior risk-stratification barriers that limited addressable volume.
- Sequencing cost deflation:Reagent and flow-cell economics from next-generation sequencing platforms have reduced per-test manufacturing costs below microarray parity thresholds.
- Integrated health system bundling:Hospital networks in California and Texas are embedding cfDNA testing into standardized prenatal care pathways, capturing patients at first-trimester intake.
Market Restraints
- Reimbursement fragmentation:CMS coverage determinations for average-risk indications remain inconsistent across Medicare Administrative Contractors, creating payment uncertainty for outpatient laboratories.
- Sequencing instrument concentration:Two manufacturers control over 80% of installed next-generation sequencing base positions, exposing laboratories to supply vulnerability and service pricing power.
- Fetal fraction failure rates:Samples below four percent fetal fraction require redraws or invasive procedures, generating clinical workflow friction and patient dissatisfaction.
Strategic Opportunities
- Telehealth-integrated ordering:Fertility clinics in Florida and Arizona are deploying remote blood-draw coordination, extending cfDNA access to patients without proximity to academic medical centers.
- Expanded aneuploidy panels:Detection of microdeletions and sex chromosome abnormalities is absorbing incremental sequencing capacity while commanding premium pricing from high-risk cohorts.
- Japan PMDA pathway acceleration:Streamlined clinical validation requirements for sequencing-based assays are compressing time-to-market for platforms seeking entry into the concentrated Japanese hospital market.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation and algorithm development functions require hybrid molecular biology-computational expertise that exceeds current laboratory staffing models.
- CLIA complexity escalation:FDA oversight of laboratory-developed tests is intensifying validation documentation requirements, extending compliance timelines for assay modifications.
- Cloud infrastructure integration:Secondary analysis pipelines demand HIPAA-compliant data architectures that many regional laboratories lack capital to deploy internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell-Free Fetal DNA Testing Market |
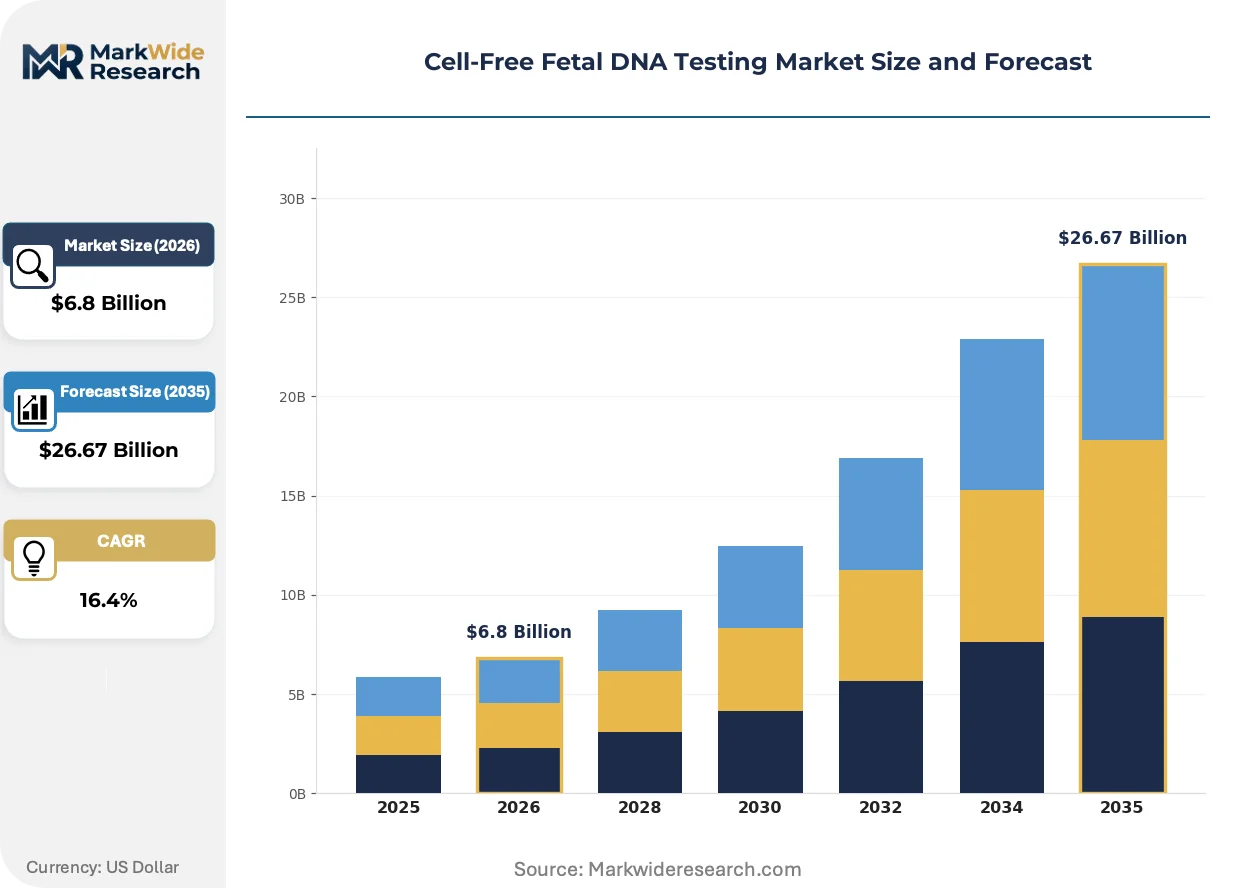
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Invasive Prenatal Testing, Carrier Screening, Paternity Testing, Third Trimester Testing Technology: Sequencing, PCR, Massively Parallel Sequencing, Microarray End User: Hospitals, Diagnostic Laboratories, Fertility Clinics, Genetic Counseling Centers Delivery Mode: Direct-to-Consumer, Physician-Ordered, Hybrid, Telehealth |
| Companies Covered | Illumina, Inc., Natera, Inc., F. Hoffmann-La Roche Ltd, Guardant Health, Sequenom Laboratories, Laboratory Corporation of America Holdings, Quest Diagnostics, Ariosa Diagnostics, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell-Free Fetal DNA Testing Market Strategic Shifts
Software-defined assay interpretation is realigning purchasing patterns across prenatal diagnostic laboratories, shifting procurement emphasis from capital equipment toward recurring informatics subscriptions and algorithm access.
Massively parallel sequencing is absorbing the analytical workload previously managed by chromosomal microarrays, delivering superior sensitivity for sub-chromosomal abnormalities while reducing DNA input requirements. Academic medical centers in Massachusetts and North Carolina are completing platform transitions within 18-month windows. The technology is absorbing market share at the expense of array-based workflows, compressing the installed base of legacy cytogenetic instruments.
The EU In Vitro Diagnostic Regulation is mandating CE marking with enhanced performance documentation for sequencing-based prenatal assays, elevating compliance costs for manufacturers seeking European market access. Germany's national screening committee evaluates evidence thresholds for statutory reimbursement, directly shaping commercial viability across European prenatal care systems. Smaller sequencing platforms are withdrawing from the European market rather than absorbing MDR compliance burdens.
Direct-to-consumer marketing restrictions are redirecting patient demand toward physician-mediated ordering channels, reinforcing obstetrician gatekeeper functions. Telehealth platforms are capturing fertility clinic referrals for remote prenatal counseling and specimen logistics. This behavioral pivot is most visible in Texas and Georgia, where integrated health systems have deployed patient navigation services to capture self-referred screening demand.
Cell-Free Fetal DNA Testing Market Segmentation
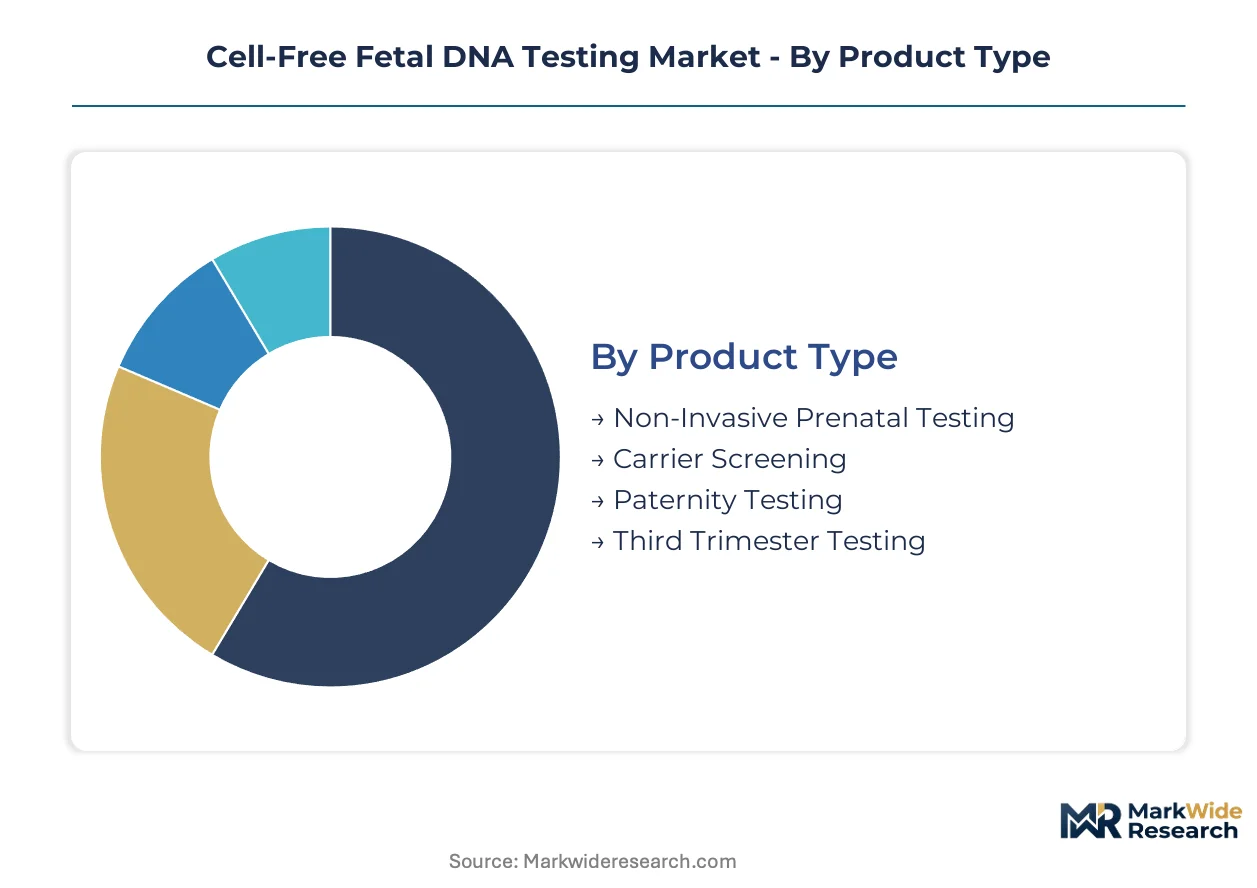
Segmentation in cfDNA testing reveals how clinical workflows, reimbursement pathways, and technology choices fragment purchasing decisions across prenatal care settings. Laboratories and health systems prioritize different performance attributes based on patient volume, regulatory environment, and integration with electronic health records.
Product Type:
Clinical indication intensity separates high-volume screening applications from specialized diagnostic niches.
- Non-Invasive Prenatal Testing:Screens fetal DNA for chromosomal aneuploidies including trisomies 21, 18, and 13 through maternal blood draw. Demand concentrates in United States integrated health systems where professional society guidelines mandate first-trimester universal screening; reimbursement certainty from CMS contractors determines laboratory participation rates.
- Carrier Screening:Identifies parental carrier status for autosomal recessive and X-linked conditions prior to conception or early pregnancy. Fertility clinics in California and Texas bundle expanded carrier panels with IVF workflows; pricing pressure from health plan medical necessity policies constrains panel breadth.
- Paternity Testing:Determines biological fatherhood through fetal DNA comparison with alleged paternal samples.
- Third Trimester Testing:Assesses late-pregnancy complications including fetal aneuploidy confirmation and zygosity determination in multiple gestations.
Volume sits with Non-Invasive Prenatal Testing; growth tilts toward Carrier Screening.
Technology:
Capital intensity and sensitivity requirements divide laboratories by sequencing platform generation and throughput capacity.
- Massively Parallel Sequencing:Simultaneously sequences millions of DNA fragments to detect chromosomal abnormalities with sensitivity exceeding microarray platforms. Academic medical centers in Massachusetts and North Carolina completed platform transitions within compressed 18-month windows; reagent cost deflation below microarray parity accelerates replacement cycles.
- Sequencing:Encompasses targeted next-generation sequencing approaches with lower throughput than massively parallel methods. Mid-sized regional laboratories in Germany deploy targeted panels for aneuploidy detection where CE marking under MDR constrains platform choices.
- PCR:Amplifies specific DNA sequences for rapid, low-cost detection of known variants.
- Microarray:Hybridizes DNA samples to fixed probe sets for chromosomal analysis.
Installed base concentrates with Massively Parallel Sequencing; laboratories retaining Microarray capacity face accelerated obsolescence timelines.
End User:
Specimen volume and integration depth determine whether buyers prioritize turnaround time, interpretive support, or cost per test.
- Hospitals:Embedded within maternal-fetal medicine departments with direct obstetrician ordering and same-day phlebotomy. Hospital networks in Texas and California standardize cfDNA testing into prenatal care pathways; EHR integration requirements favor vendors with HL7 FHIR connectivity.
- Diagnostic Laboratories:Independent reference facilities processing specimens from multiple ordering sites. National logistics networks control specimen collection windows and result delivery; CLIA complexity escalation extends compliance timelines for assay modifications.
- Fertility Clinics:Specialized reproductive endocrinology practices with pre-conception and early-pregnancy screening focus.
- Genetic Counseling Centers:Patient education and risk assessment facilities with interpretive service orientation.
Specimen volume aggregates at Diagnostic Laboratories; patient capture rates climb fastest at Fertility Clinics through telehealth-integrated ordering.
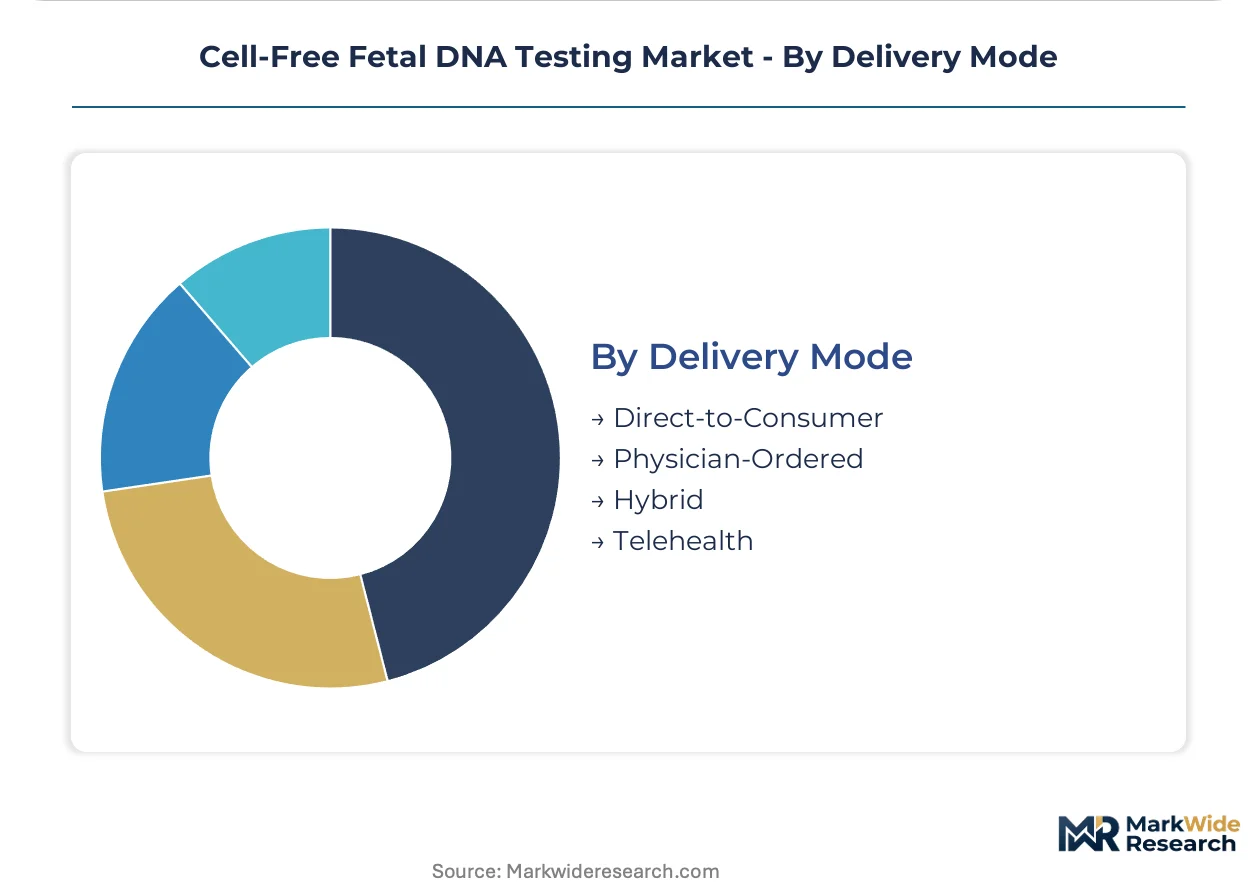
Delivery Mode:
Regulatory oversight intensity and patient access convenience shape channel selection for cfDNA test distribution.
- Physician-Ordered:Requires obstetrician or maternal-fetal medicine specialist authorization with insurance pre-authorization support. Dominates United States reimbursement landscape; integrated health systems deploy patient navigation services to capture self-referred demand and redirect toward physician-mediated channels.
- Telehealth:Remote blood-draw coordination with virtual genetic counseling and electronic result delivery. Fertility clinics in Florida and Arizona extend cfDNA access to patients lacking proximity to academic medical centers; HIPAA-compliant cloud infrastructure demands exceed regional laboratory capital capacity.
- Direct-to-Consumer:Patient-initiated testing without clinician intermediary.
- Hybrid:Combines digital patient engagement with mandatory physician review.
Reimbursement stability favors Physician-Ordered; access expansion is steepest through Telehealth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing instrument manufacturing concentrates in the United States and Germany, while clinical specimen volume and reimbursement-funded consumption disproportionately flow through American hospital networks and Japanese tertiary care centers.
United States
Integrated health systems in Texas and California embed cfDNA testing into standardized prenatal pathways at first-trimester intake. FDA oversight under CLIA high-complexity laboratory-developed test frameworks shapes validation timelines for assay modifications. Academic medical centers in Massachusetts completed platform transitions to massively parallel sequencing within compressed 18-month windows.
Germany
The national screening committee evaluates evidence thresholds for statutory reimbursement, directly determining which platforms achieve commercial viability across European prenatal systems. EU In Vitro Diagnostic Regulation mandates CE marking with enhanced performance documentation, elevating compliance costs for sequencing-based assays. Mid-sized regional laboratories deploy targeted panels where MDR constraints limit platform choices.
Japan
PMDA clinical validation requirements govern which sequencing platforms enter the concentrated hospital market, with streamlined pathways compressing time-to-market for compliant assays. Tertiary care centers in Tokyo and Osaka anchor specimen volume for non-invasive prenatal screening. Domestic reimbursement decisions determine whether cfDNA expands from high-risk to average-risk pregnancy indications.
United Kingdom
National Health Service commissioning frameworks govern access to cfDNA screening, with regional variation in coverage policies creating patchwork adoption across England, Scotland, and Wales. MHRA post-Brexit regulatory divergence from EU MDR introduces parallel compliance pathways for manufacturers. London-based hospital networks pilot telehealth-integrated ordering for fertility clinic referrals.
China
NMPA clinical trial requirements for sequencing-based diagnostics determine market entry timelines for prenatal screening platforms. Provincial health commission reimbursement catalogs in Guangdong and Jiangsu shape commercial viability beyond premium private-pay segments. Yangtze River Delta hospital clusters drive volume for non-invasive prenatal testing adoption.
Cell-Free Fetal DNA Testing Market Competitive Environment
Top-tier vendors anchor sequencing hardware and proprietary algorithm development, while mid-tier diagnostic laboratories compete through logistics networks and turnaround time compression. The vendor base stratifies across instrument manufacturers, assay developers, and reference laboratory operators. Three archetypes dominate: sequencing platform owners, bioinformatics-anchored test developers, and national logistics-integrated laboratories. Competitive moves concentrate on strategic partnerships between hardware and software layers, plus geographic expansion through CLIA laboratory acquisitions.
Among sequencing-anchored platform developers, Illumina, Inc. and Natera, Inc. occupy positions representing hardware dominance and algorithm-proprietary test development respectively. Laboratory Corporation of America Holdings exemplifies the logistics-integrated reference laboratory archetype. These three entities represent distinct competitive vectors: instrument installed base control, physician workflow software embedding, and specimen collection network density.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Natera, Inc. |
| F. Hoffmann-La Roche Ltd |
| Guardant Health |
| Sequenom Laboratories |
| Laboratory Corporation of America Holdings |
| Quest Diagnostics |
| Ariosa Diagnostics |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Bioinformatics specialists concentrated in Massachusetts and California command salary premiums that propagate through assay pricing tiers, widening spreads between premium algorithm-anchored platforms and economy-grade PCR alternatives.
Pricing Analysis
Cost-down pressure on standard NIPT panels accelerates because health plan medical necessity policies constrain reimbursement breadth. Three-tier pricing structure across premium, standard, and economy levels separates proprietary algorithm platforms from validated sequencing assays and legacy microarray alternatives. Price differentiation traces to FDA clearance tier and bioinformatics sophistication. Fertility clinics exhibit highest price sensitivity; academic medical centers prioritize sensitivity thresholds over per-test economics.
Supply Chain Analysis
Next-generation sequencing reagent supply rests on concentrated manufacturing in the United States, Germany, and Japan. Flow-cell chemistries, polymerase enzymes, and barcoded adapter libraries constitute critical input dependencies. Single-source vulnerability concentrates in Illumina's control of sequencing instrument installed base. Distribution runs through national reference laboratory networks that manage specimen logistics and CLIA-certified processing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU In Vitro Diagnostic Regulation erects compliance cost barriers that favor scaled incumbents with dedicated regulatory affairs infrastructure, compressing viable participation to CE-marked platform holders.
For Market Incumbents: Deepen algorithm-proprietary differentiation through expanded microdeletion detection panels that absorb incremental sequencing capacity. Acquire regional CLIA-certified laboratories in Texas and Florida to compress specimen turnaround times against emerging telehealth-integrated competitors. Threat substitution from cloud-native diagnostic platforms demands preemptive EHR integration investments. For New Entrants and Emerging Players: Capture telehealth-integrated ordering workflows in fertility clinic segments where physician-mediated channels remain underdeveloped. Target Arizona and Georgia markets where patient navigation services redirect self-referred demand toward compliant ordering pathways. Go-to-market leverage rests on HIPAA-compliant cloud infrastructure partnerships that exceed regional laboratory capital constraints. For Investors and Strategic Acquirers: Re-rating potential sits with bioinformatics-anchored test developers given professional guideline expansion toward average-risk pregnancy screening. Long-term viability favors platforms with demonstrated PMDA pathway success in Japan's concentrated hospital market. Watch CMS coverage determination uniformity across Medicare Administrative Contractors as inflection signal for outpatient laboratory participation rates.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance documentation elevates barriers for sequencing-based assay market entry in Germany. |
| Hospital System Partnership | Texas and California health network standardization embeds cfDNA testing into first-trimester intake workflows. |
| Software Companion Development | Proprietary variant interpretation algorithms anchor physician-ordered platform loyalty against hardware competitors. |
| Reimbursement Strategy | CMS contractor alignment on average-risk indications determines laboratory addressable volume expansion. |
| PMDA Submission | Streamlined Japanese clinical validation accelerates time-to-market for sequencing platforms in Tokyo-Osaka hospital clusters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maternal-fetal medicine specialists, CLIA laboratory directors, health plan medical policy leads, and genetic counseling center administrators validated demand-side assumptions. FDA 510(k) submissions, EMA MDR technical documentation, and PMDA approval records supplied regulatory trajectory inputs. Bottom-up test volume modeling and top-down healthcare expenditure triangulation converged on segment-level estimates.
Granularity-level modeling deployed product type, technology platform, end-user facility, and delivery mode dimensions across the projection horizon. Massively parallel sequencing adoption curves, fetal fraction failure rate assumptions, and reimbursement pathway probabilities informed analytical frameworks. CAGRs derived from logistic diffusion modeling of platform transition dynamics and professional guideline update schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS coverage expansion decisions and EU MDR enforcement consistency. Assumptions reflect documented regulatory trajectories and health system procurement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Cystatin C Testing Market