
 Automotive Adaptive Engine Mounts Market | 2026-2036
Automotive Adaptive Engine Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Adaptive Engine Mounts Market Outlook
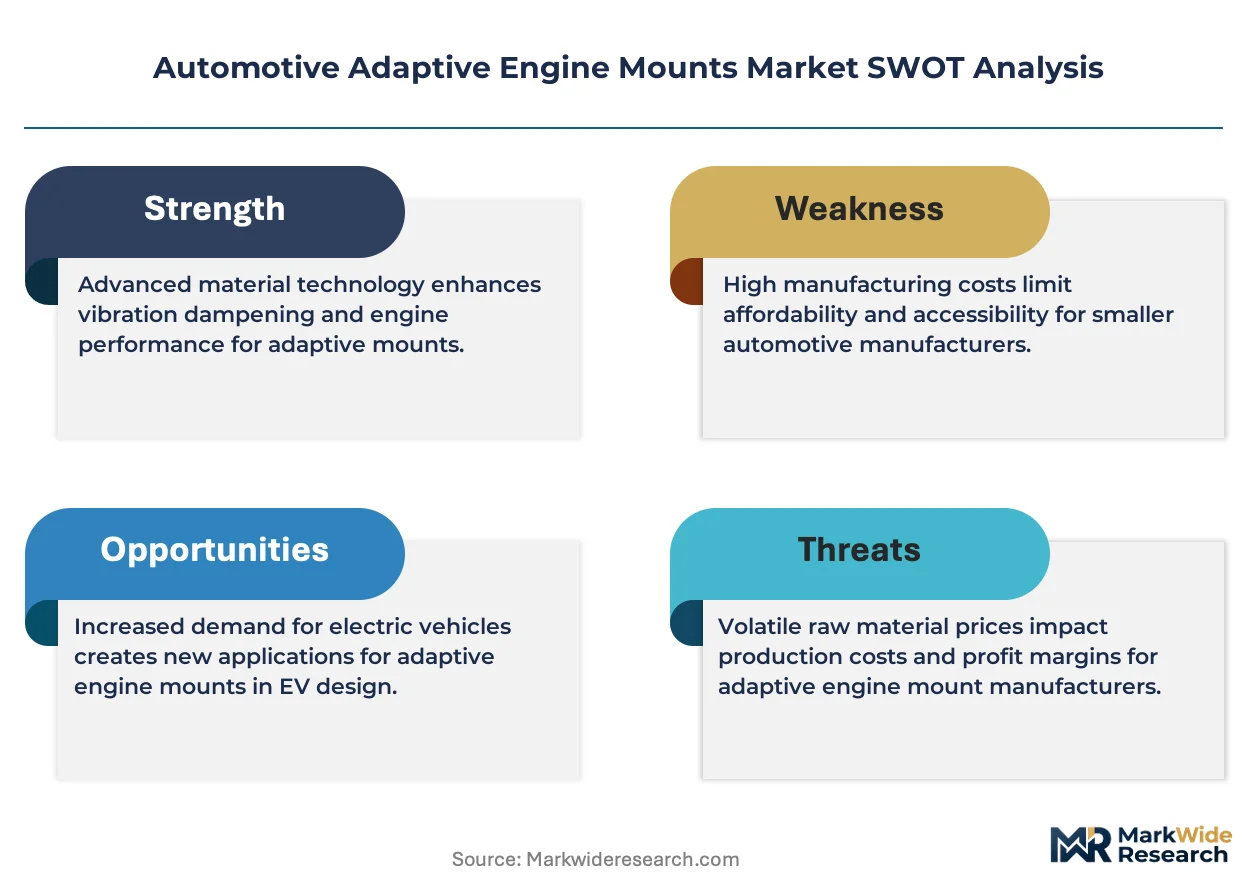
China's Jiangsu and Zhejiang province manufacturing corridor is reconfiguring regional supply dynamics for precision-engineered chassis components. Sumitomo Riko leverages its rubber-to-electronics integration heritage to dominate active mount architectures for hybrid platforms. Tenneco competes through backward integration into polyurethane formulation, sustaining margin control across the vibration control value chain. ContiTech anchors European OEM relationships with hydraulic adaptive systems calibrated to EU noise regulations.
Automotive adaptive engine mounts are vibration-isolation devices incorporating sensor-actuator loops that modulate stiffness in real time to cancel engine-induced oscillations, typically operating through magnetorheological fluids or piezoelectric stacks with response latencies under ten milliseconds. Their primary purpose is to decouple powertrain vibration from vehicle structure during idle and transient load conditions, preserving occupant comfort and component durability. Hydraulic mounts retain the largest installed base among passenger car applications, though electromechanical variants represent the fastest-expanding margin pool as EV architectures demand active cancellation of high-torque electric motor harmonics. OEM channel concentration concentrates procurement volume with vehicle assemblers and Tier-1 suppliers, while aftermarket providers occupy a fragmented, price-sensitive tier serving aging premium vehicle parc.
NHTSA's Federal Motor Vehicle Safety Standards govern structural integrity and durability testing for engine mounting systems sold in the United States, while ECE R14 and ECE R94 frameworks in Europe mandate crash-performance compatibility that shapes adaptive mount release specifications. China's MIIT enforces GB standards for NVH certification that OEMs must satisfy for domestic vehicle type approval, tightening product development cycles for suppliers. Stakeholders must monitor how dual carbon goals across Beijing, Brussels, and Washington reshape material selection criteria for mount substrates and actuation fluids.
Market Dynamics
Electromechanical mount architectures are compressing the addressable market for conventional hydraulic systems as EV powertrains demand active harmonic cancellation rather than passive isolation. This technology displacement is forcing incumbent suppliers to retool rubber-molding competencies toward sensor integration and real-time control firmware.
Growth Catalysts
- EU vehicle noise directives:Germany's KBA enforces progressively stricter NVH limits that mandate factory-fit adaptive mounts for luxury passenger car homologation.
- China's dual carbon goals:MIIT subsidies for electrified powertrains accelerate procurement of lightweight, energy-efficient mount systems in the Yangtze River Delta cluster.
- Piezoelectric stack actuation:Response latencies under ten milliseconds enable real-time stiffness modulation that satisfies Japan's tightened JIS vibration standards.
Market Restraints
- Magnetorheological fluid supply concentration:Specialty iron particle formulations depend on captive Chinese rare earth processing, exposing Tier-1 suppliers to input volatility.
- NHTSA durability testing timelines:Extended validation cycles for structural integrity certification delay product release schedules by 12-18 months.
- Passive elastomeric mounts:Mature rubber-to-metal bonding technology retains cost advantage in economy vehicle segments, capping premium system penetration.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic manufacturing incentives create white space for adaptive mount localization serving Maruti Suzuki and Hyundai Motor India.
- ISO 26262 functional safety convergence:Integration of ASIL-D rated control electronics with chassis systems opens premium pricing for safety-certified architectures.
- Battery-protected EV architectures:Active vibration cancellation for high-torque electric motor harmonics represents unmet need in China's NEV export programs.
Industry Challenges
- Embedded systems firmware development:Scarce talent pools for real-time control algorithms and sensor fusion engineering constrain Tier-1 R&D throughput.
- GB standards NVH certification:China's MIIT type approval requirements demand parallel testing protocols that fragment product development resources.
- Legacy vehicle platform integration:Retrofitting electromechanical mounts into internal combustion architectures requires custom bracketry and control module adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Adaptive Engine Mounts Market |
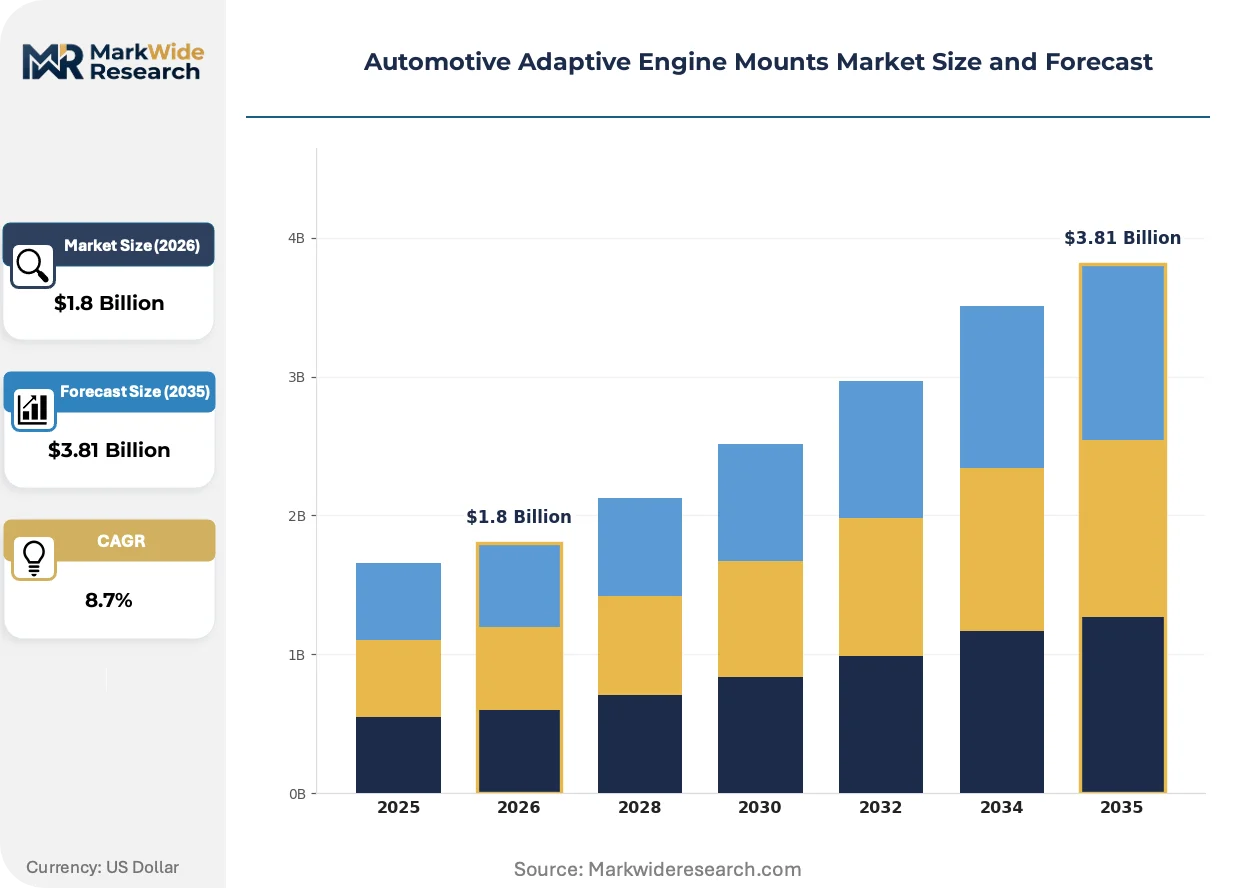
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydraulic, Rubber, Pneumatic, Electromechanical Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Vans Material: Polyurethane, Steel, Aluminum, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Sumitomo Riko, Tenneco, ContiTech, Yamashita Rubber, Magna International, Hutchinson, Trelleborg, Federal-Mogul, Vibracoustic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Adaptive Engine Mounts Market Strategic Shifts
Active damping technologies are converging with vehicle domain architectures, compressing the traditional separation between powertrain isolation and chassis control systems. This integration is redrawing supplier boundaries and qualification requirements.
Magnetorheological fluid systems are hybridizing with piezoelectric actuation stacks to create dual-mode mounts capable of switching between comfort-oriented and performance-calibrated damping profiles. EV manufacturers in China's NEV sector are adopting these architectures at accelerated pace to address high-torque motor harmonics. The technology is hybridizing what were previously distinct product categories into unified active suspension-integrated modules.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of hydraulic mount damping fluids across European supply chains. ECHA's 2023 candidate list updates have disqualified several legacy polymer additives used in elastomeric membranes. German OEMs are responding by accelerating electromechanical alternatives that eliminate fluid-based damping media entirely.
Vehicle assemblers are consolidating adaptive mount procurement through single-source chassis integration contracts rather than discrete component purchasing. This bundling displaces standalone Tier-1 negotiations in favor of system-level supplier relationships. The pattern is most visible in Japan, where Toyota and Honda have shifted to platform-level vibration control sourcing for new BEV architectures.
Automotive Adaptive Engine Mounts Market Segmentation
Adaptive engine mount procurement cycles vary dramatically by technology maturity and vehicle platform refresh rates. Electromechanical architectures turnover every 3-4 years as EV powertrains evolve, while hydraulic systems persist across 7-10 year vehicle lifecycles. Understanding these temporal patterns clarifies where suppliers must prioritize R&D versus manufacturing scale.
Type:
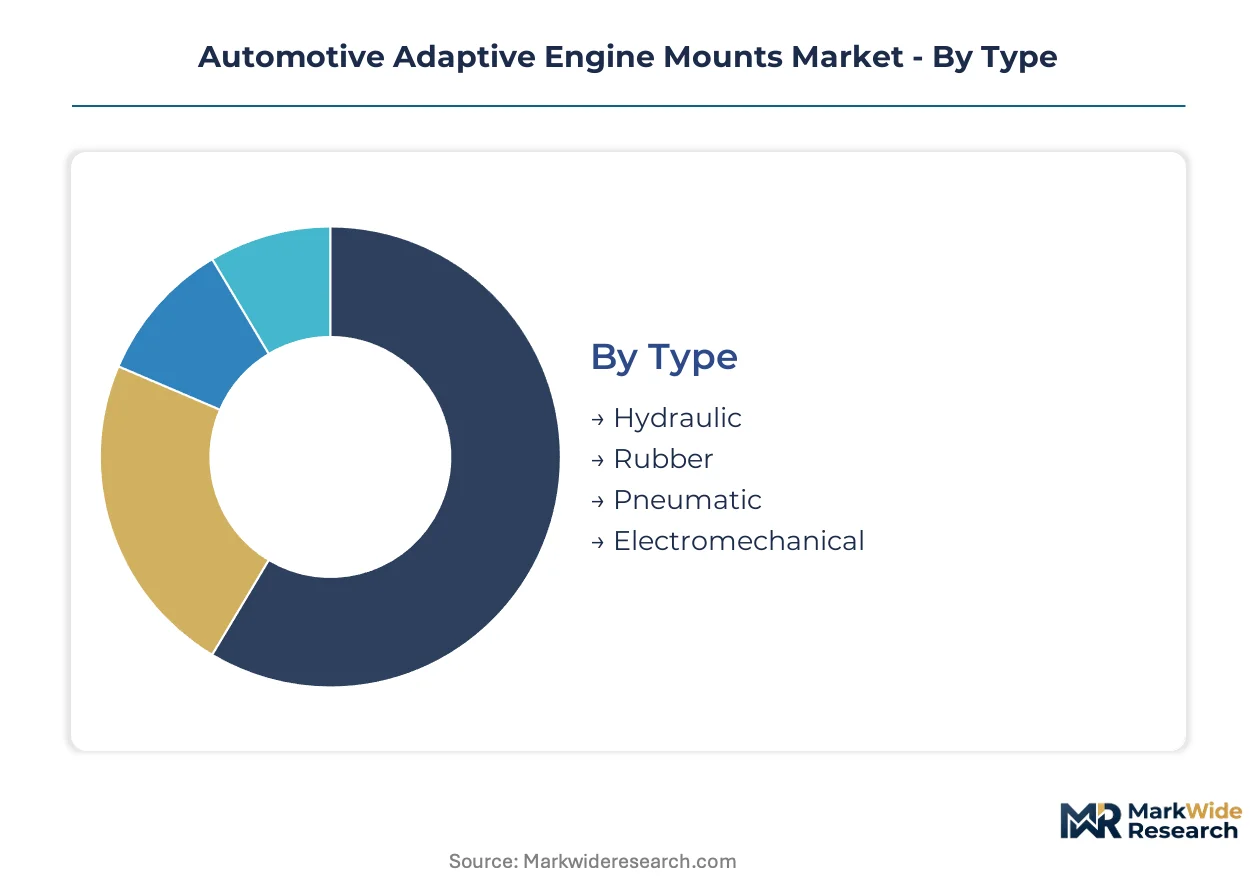
Hydraulic mounts command the longest production runs but face compressed development cycles as electromechanical alternatives prove feasibility. Rubber variants sustain steady replacement demand. Pneumatic systems occupy niche commercial applications with irregular procurement patterns.
- Hydraulic:Magnetorheological fluid chambers modulate damping through variable viscosity under magnetic field excitation. German OEMs in Stuttgart and Munich specify these for luxury sedan homologation under KBA noise directives, though rare earth supply exposure constrains margin stability.
- Electromechanical:Piezoelectric actuator stacks achieve sub-ten millisecond response latencies for active harmonic cancellation. China's NEV manufacturers in Shenzhen and Shanghai are standardizing these for high-torque electric motor isolation, driving the steepest supplier qualification activity.
- Rubber:Elastomeric-to-metal bonded assemblies provide passive isolation through tuned stiffness characteristics. Aftermarket channels sustain volume for aging vehicle parc maintenance.
- Pneumatic:Air-spring based systems deliver load-adaptive stiffness for heavy commercial platforms. Limited adoption outside European long-haul freight specifications.
Hydraulic architectures dominate installed base. Electromechanical variants are where expansion concentrates.
Application:
Passenger car platforms generate the highest absolute volume but fragment across powertrain configurations. Commercial vehicle demand clusters in fleet procurement cycles. Electric vehicle applications impose distinct technical requirements that reshape supplier capabilities.
- Passenger Cars:Multi-point mounting systems isolate inline-four and V6 configurations across unibody architectures. Japanese OEMs in Toyota City and Nagoya specify adaptive mounts for JIS NVH certification compliance.
- Electric Vehicles:High-torque motor harmonics at low RPM demand active cancellation rather than passive isolation. China's MIIT subsidies accelerate Yangtze River Delta procurement for NEV export programs.
- Commercial Vehicles:Frame-mounted systems endure higher static loads and vibration amplitudes. North American heavy-duty specifications prioritize durability over comfort calibration.
- Vans:Transverse powertrain configurations in compact delivery vehicles use simplified two-point mounting. European last-mile logistics fleets drive periodic replacement demand.
Passenger cars anchor current revenue. Electric vehicle applications are climbing the fastest.
Material:
Material selection tracks weight reduction imperatives and damping performance tradeoffs. Aluminum substitution accelerates in EV architectures. Steel retains cost advantage in high-volume segments.
- Polyurethane:Castable elastomer formulations enable complex geometries with tunable dynamic stiffness. Tenneco's backward integration into proprietary formulations sustains margin control across vibration control supply chains.
- Steel:Stamped and welded brackets provide structural anchorage with established welding protocols. Economy vehicle segments in India prioritize steel for cost containment.
- Aluminum:Die-cast housings reduce unsprung mass for battery-protected EV architectures. China's dual carbon goals accelerate aluminum adoption in Jiangsu province manufacturing.
- Composite:Glass-fiber reinforced polymers offer corrosion resistance and acoustic decoupling. Limited to premium applications pending recycling pathway validation.
Steel retains volume leadership. Aluminum is gaining share fastest.
End User:
Procurement authority is consolidating toward vehicle assemblers with platform-level integration mandates. Aftermarket channels fragment across price-sensitive distributors. Tier-1 suppliers face margin compression from direct OEM relationships.
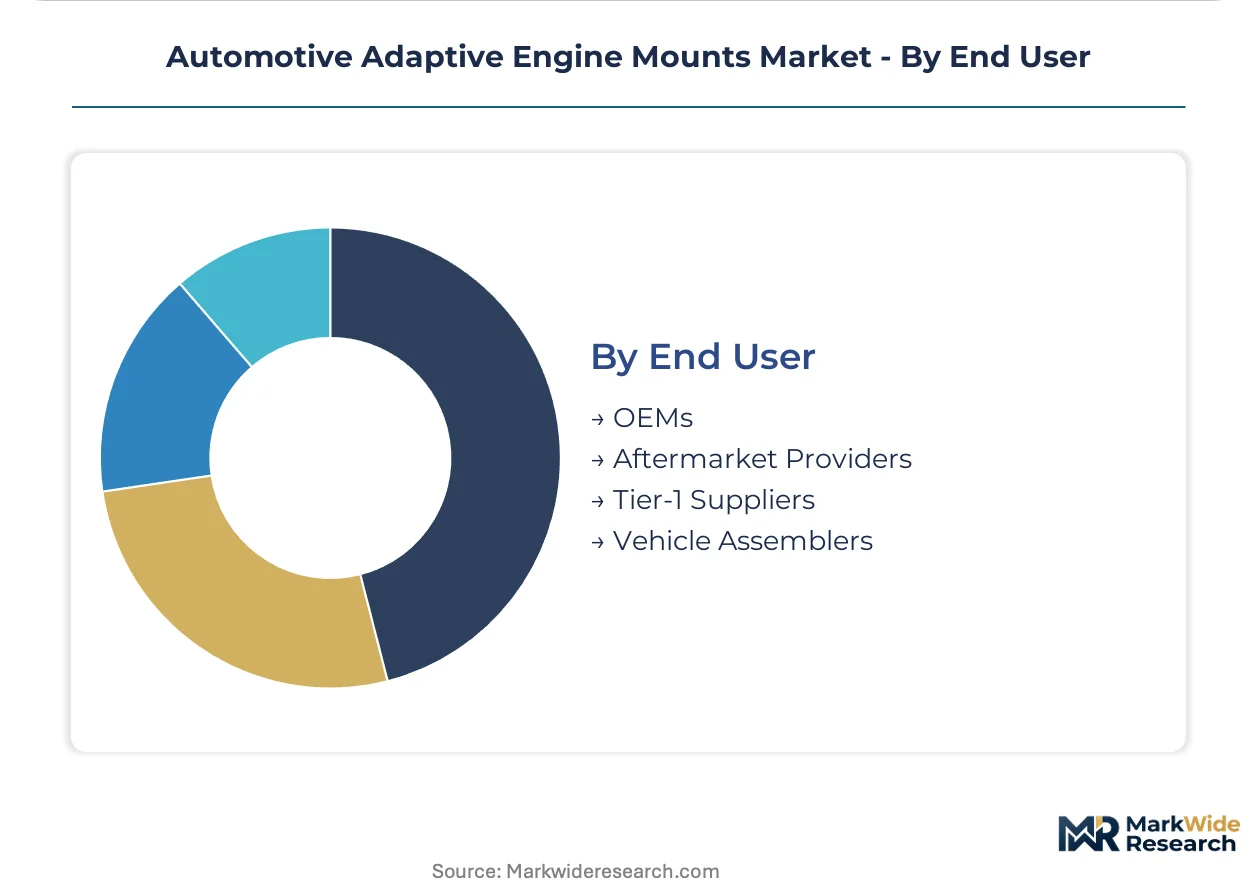
- OEMs:Factory-fit specifications for new vehicle homologation demand ASIL-D functional safety certification. Toyota and Honda have shifted to platform-level vibration control sourcing for BEV architectures.
- Tier-1 Suppliers:System integration contracts bundle adaptive mounts with chassis modules. Sumitomo Riko leverages rubber-to-electronics heritage to dominate active mount architectures for hybrid platforms.
- Vehicle Assemblers:Contract manufacturers in China's Yangtze River Delta cluster procure through consolidated chassis integration agreements rather than discrete component purchasing.
- Aftermarket Providers:Independent distributors serve aging premium vehicle parc with reverse-engineered replacements. Price competition limits technology upgrade penetration.
OEM channels concentrate value capture. Tier-1 supplier relationships are where competitive positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adaptive engine mount supply chains concentrate in three manufacturing corridors: Germany's Stuttgart-Munich axis, Japan's Toyota City-Nagoya belt, and China's Yangtze River Delta. These clusters feed distinct regulatory environments and powertrain transition timelines.
China
MIIT subsidies for NEV exports drive Yangtze River Delta procurement of electromechanical mounts with sub-ten millisecond response latencies. GB standards NVH certification tightens product development cycles for suppliers serving BYD and NIO. Jiangsu and Zhejiang province factories reconfigure for aluminum die-cast housings under dual carbon goals.
Germany
KBA noise directives mandate factory-fit adaptive mounts for luxury sedan homologation. Stuttgart OEMs specify magnetorheological fluid systems calibrated to EU vehicle noise limits. Bavaria's rubber-to-electronics integration heritage anchors ContiTech's hydraulic adaptive system production.
Japan
JIS vibration standards tightened in 2023 accelerate piezoelectric stack adoption for active harmonic cancellation. Toyota and Honda shifted to platform-level vibration control sourcing for BEV architectures in Nagoya and Toyota City. METI industrial policy supports sensor-actuator loop development.
United States
NHTSA durability testing timelines extend validation cycles for structural integrity certification. Detroit Three OEMs concentrate procurement of hydraulic mounts for full-size truck platforms. Michigan and Ohio suppliers face margin pressure from direct OEM platform-integration contracts.
India
PLI scheme incentives for automotive components create localization opportunities serving Maruti Suzuki and Hyundai Motor India. Tamil Nadu and Gujarat manufacturing clusters absorb technology transfer from Japanese and Korean parent companies. BIS standards for NVH compliance remain less stringent than EU or Japanese equivalents.
Automotive Adaptive Engine Mounts Market Competitive Environment
Vertically integrated conglomerates and rubber-to-electronics specialists split the market between hydraulic legacy systems and electromechanical next-generation architectures. The vendor base concentrates around three strategic archetypes: integrated rubber-electronics hybridizers, polyurethane formulation backward integrators, and hydraulic system incumbents defending European OEM relationships. Competitive moves center on sensor integration firmware development and single-source chassis bundling contracts displacing discrete component purchasing.
Within the rubber-electronics hybridizer tier, Sumitomo Riko exemplifies the archetype through its heritage in active mount architectures for hybrid platforms. Among North American diversified suppliers, Tenneco occupies a position representing backward integration into proprietary polyurethane formulations. ContiTech anchors the hydraulic incumbent tier, its European base reflecting long-standing OEM calibration relationships. These three entities represent distinct capability configurations rather than interchangeable competitors.
| Leading Market Players |
|---|
| Sumitomo Riko |
| Tenneco |
| ContiTech |
| Yamashita Rubber |
| Magna International |
| Hutchinson |
| Trelleborg |
| Federal-Mogul |
| Vibracoustic |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Jiangsu province rubber-molding corridor is compressing supplier margins while simultaneously accelerating price competition for electromechanical mount architectures. This utilization imbalance forces Tier-1 suppliers to absorb rare earth input volatility rather than pass through costs, reshaping procurement negotiations with Yangtze River Delta vehicle assemblers.
Pricing Analysis
EU vehicle noise directives dictate the pricing tier structure across factory-fit adaptive mount procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified electromechanical systems from hydraulic homologation-grade units and passive elastomeric replacements. Cost compression in economy segments is intensifying because Indian and Chinese aftermarket providers reverse-engineer legacy rubber-to-metal bonds. Fleet procurement managers at commercial vehicle operators exhibit highest price sensitivity, while German luxury OEM platform engineers prioritize NVH certification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk planning for magnetorheological fluid formulations. Manufacturing concentrates in Germany, China, and Japan, with each corridor feeding distinct regulatory certification requirements. Specialty iron particle formulations draw from captive Chinese rare earth processing, creating single-source vulnerability for Tier-1 suppliers. Distribution runs through consolidated chassis integration contracts rather than discrete component purchasing, compressing standalone negotiation leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical mount architectures are displacing hydraulic incumbent revenue streams, forcing substitution defense strategies across rubber-to-electronics supply chains. Incumbents must navigate piezoelectric stack qualification timelines that favor sensor-integration specialists over legacy fluid-system providers.
For Market Incumbents: Insulate factory-fit relationships by accelerating ASIL-D certification investment for active mount control firmware. Backward integration into polyurethane formulation sustains margin control against Tenneco's captive supply advantages. Defensive patent positioning around sub-ten millisecond response latency algorithms blocks emerging sensor-fusion entrants from Tier-1 qualification.
For New Entrants and Emerging Players: Pursue India's PLI scheme localization opportunities serving Maruti Suzuki and Hyundai Motor India procurement committees. Tamil Nadu manufacturing clusters absorb technology transfer with less stringent BIS NVH compliance costs than EU or Japanese equivalents. White space exists in retrofit electromechanical brackets for aging premium vehicle parc maintenance channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rubber-to-electronics hybridizers with hybrid platform heritage. Long-term viability favors suppliers with sensor-actuator loop development capabilities spanning the 5-10 year EV transition window. Acquisition targets should demonstrate firmware talent pools for real-time control algorithms. The signal to monitor is MIIT subsidy renewal timing for Yangtze River Delta NEV export programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Actuator Firmware Development | Sub-ten millisecond response latencies satisfy Japan's tightened JIS vibration standards for BEV platforms. |
| ASIL-D Functional Safety Certification | Integration with chassis domain architectures opens premium pricing for safety-certified electromechanical mounts. |
| Aluminum Die-Cast Housing Expansion | Jiangsu province reconfiguration under dual carbon goals reduces unsprung mass for battery-protected EV architectures. |
| Rare Earth Supply Diversification | Magnetorheological fluid input volatility exposure constrains margin stability for hydraulic system incumbents. |
| Platform-Level Vibration Control Sourcing | Toyota and Honda consolidation patterns displace discrete component purchasing in favor of system-level relationships. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distribution heads, and rubber-to-electronics R&D directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT NEV subsidy disclosures, and KBA homologation filings. Bottom-up segment sizing triangulated against top-down macroeconomic automotive production forecasts.
Calibration across the analysis window employed vehicle platform refresh cycle modeling, content-per-vehicle trajectory analysis by propulsion architecture, and regional production cluster demand aggregation. Segmentation dimensions included mount technology type, vehicle class, OEM tier positioning, and regional regulatory framework. CAGRs derived from fitted growth curves against historical technology substitution patterns, with electromechanical adoption curves calibrated to NEV penetration timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese sensor-integration specialists or Indian PLI scheme beneficiaries would shift outcomes. Macroeconomic automotive demand contraction, REACH substance restriction expansion, or rare earth export control tightening would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Suspension Spring Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Smart Adaptive Headlights Market