
 Automotive Engine Cooling Fan Market | 2026-2036
Automotive Engine Cooling Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Cooling Fan Market Analytics
Aftermarket service revenue is tilting toward brushless motor refurbishment and predictive thermal system diagnostics. DENSO Corporation leverages its integrated motor-control IP to capture recurring service contracts across Asian vehicle platforms. Valeo SA sustains competitive intensity through modular fan-assembly architectures that reduce dealer inventory complexity. Robert Bosch GmbH anchors its position in European OEM channels with temperature-sensor-integrated fan modules.
An automotive engine cooling fan is a thermomechanical device that regulates engine operating temperature by forcing airflow across the radiator heat exchanger, typically employing polyamide-reinforced blade composites or stamped steel constructions rated for continuous duty cycles exceeding 10,000 hours at ambient temperatures up to 120°C. Electric fans now dominate new vehicle platforms as belt-driven configurations retreat to legacy commercial and budget segments. Brushless technology commands the fastest expansion trajectory due to its efficiency gains and electromagnetic compatibility with stop-start systems. Variable speed control systems concentrate margin pools in the OEM channel where thermal calibration services bundle hardware with embedded software.
EPA tailpipe regulations and NHTSA corporate average fuel economy standards compel OEMs to specify higher-efficiency cooling fans that reduce engine parasitic losses. EMA and China's MIIT enforce comparable thermal efficiency benchmarks that shape export product designs for multi-homologated platforms. Stakeholders must monitor how solid-state active grille shutters and predictive thermal algorithms redefine the boundary between mechanical and electronic cooling components.
Market Dynamics
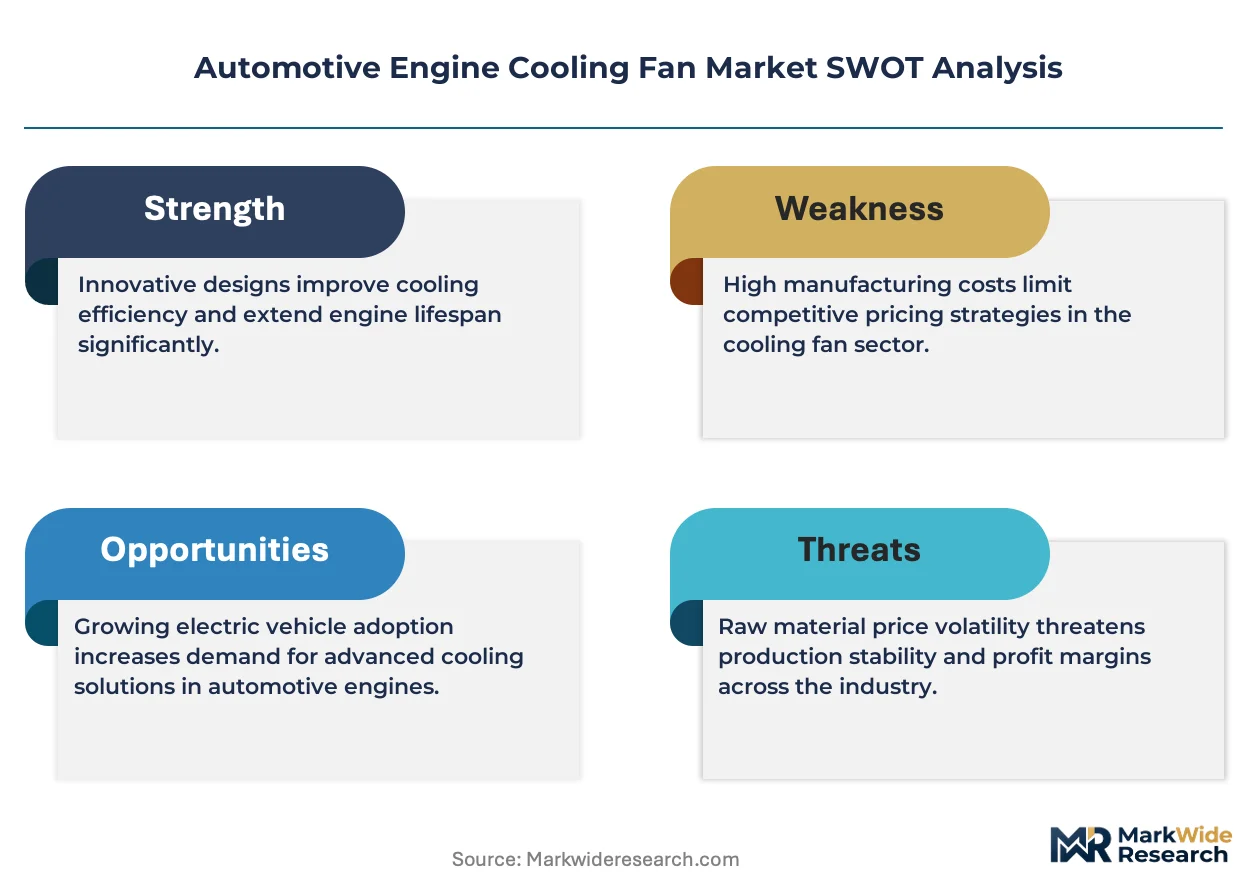
Brushless DC motor architectures are displacing brushed designs across OEM thermal management specifications, compressing supplier margins on legacy belt-driven assemblies while concentrating procurement authority among integrated motor-control specialists.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Commercial vehicle fleets in the United States face tightening thermal efficiency mandates that accelerate electric fan retrofits on legacy diesel platforms.
- Hybrid powertrain cooling architectures:German and Japanese OEMs redesign front-end modules to accommodate dual thermal loops for battery and combustion systems.
- Predictive thermal algorithms:Fleet operators deploy sensor-integrated fan modules that optimize airflow based on real-time engine load and ambient conditions.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies in China's processing infrastructure expose brushless motor supply chains to export control volatility.
- Polyamide composite input costs:Glass-fiber-reinforced blade materials face petrochemical price swings that compress molding contract margins.
- Electromagnetic compatibility certification:Stop-start system integration demands expensive CISPR 25 testing cycles that delay platform launches.
Strategic Opportunities
- India commercial vehicle electrification:The country's Bureau of Indian Standards finalizes thermal management norms for electric buses that create specification windows for localized brushless motor production.
- Active grille shutter convergence:Cooling fan suppliers partner with shutter actuator manufacturers to deliver integrated front-end thermal modules.
- Aftermarket diagnostic services:Predictive maintenance contracts for brushless motor windings and bearing assemblies unlock recurring revenue streams.
Industry Challenges
- Embedded software calibration:OEM thermal engineers must validate fan control algorithms across temperature and altitude matrices, extending development timelines.
- Legacy platform coexistence:Suppliers maintain parallel production lines for belt-driven and electric architectures, fragmenting capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Cooling Fan Market |
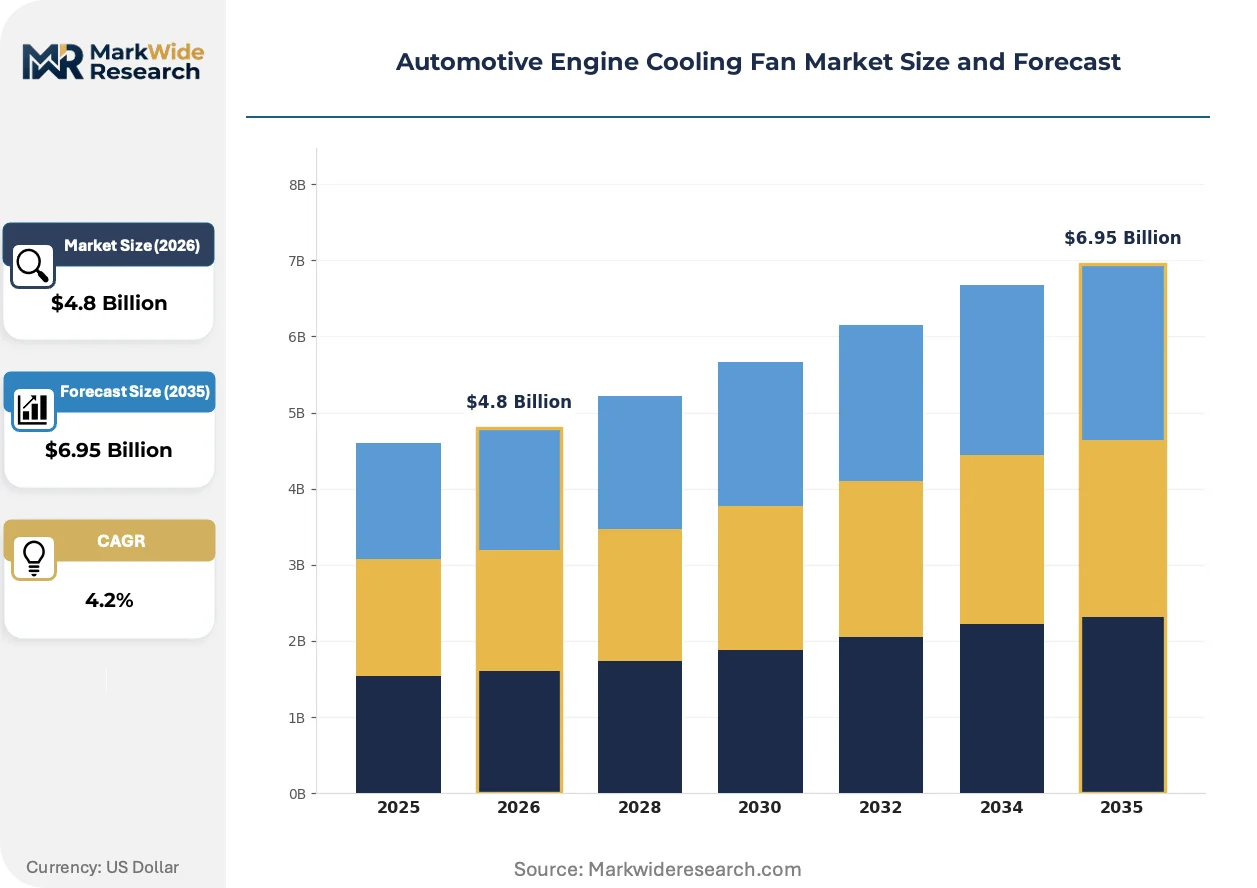
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fans, Mechanical Fans, Belt Driven Fans, Auxiliary Fans Technology: Variable Speed, Fixed Speed, Dual Speed, Brushless End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Motorcycles |
| Companies Covered | DENSO Corporation, Valeo SA, Robert Bosch GmbH, Continental AG, SPAL Automotive, MAHLE GmbH, BorgWarner Inc., Johnson Electric Holdings Limited, Delta Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Cooling Fan Market Evolving Landscape
Thermal management architectures are fragmenting into software-defined subsystems, with mechanical components becoming programmable nodes within predictive control loops rather than fixed-duty hardware.
Digital twin simulation is virtualizing thermal validation workflows for cooling fan specification. Tier 1 suppliers deploy physics-based models to predict airflow patterns across radiator geometries before physical prototyping. BMW and Toyota compress development cycles by correlating virtual test results with track data, reducing wind tunnel iterations by half.
REACH restrictions on per- and polyfluoroalkyl substances are forcing blade coating reformulations across European supply chains. Manufacturers phase out PTFE-based mold release agents in favor of ceramic-reinforced surface treatments. The ECHA substance evaluation process accelerates substitution timelines for polyamide compounds used in high-temperature fan housings.
Fleet procurement departments unbundle hardware from calibration services in commercial vehicle contracts. Buyers source brushless fan assemblies through open-catalog platforms while negotiating thermal mapping and control software separately. This bifurcation concentrates margin in firmware development capabilities and compresses commodity motor pricing in North American heavy-duty segments.
Automotive Engine Cooling Fan Market Segmentation
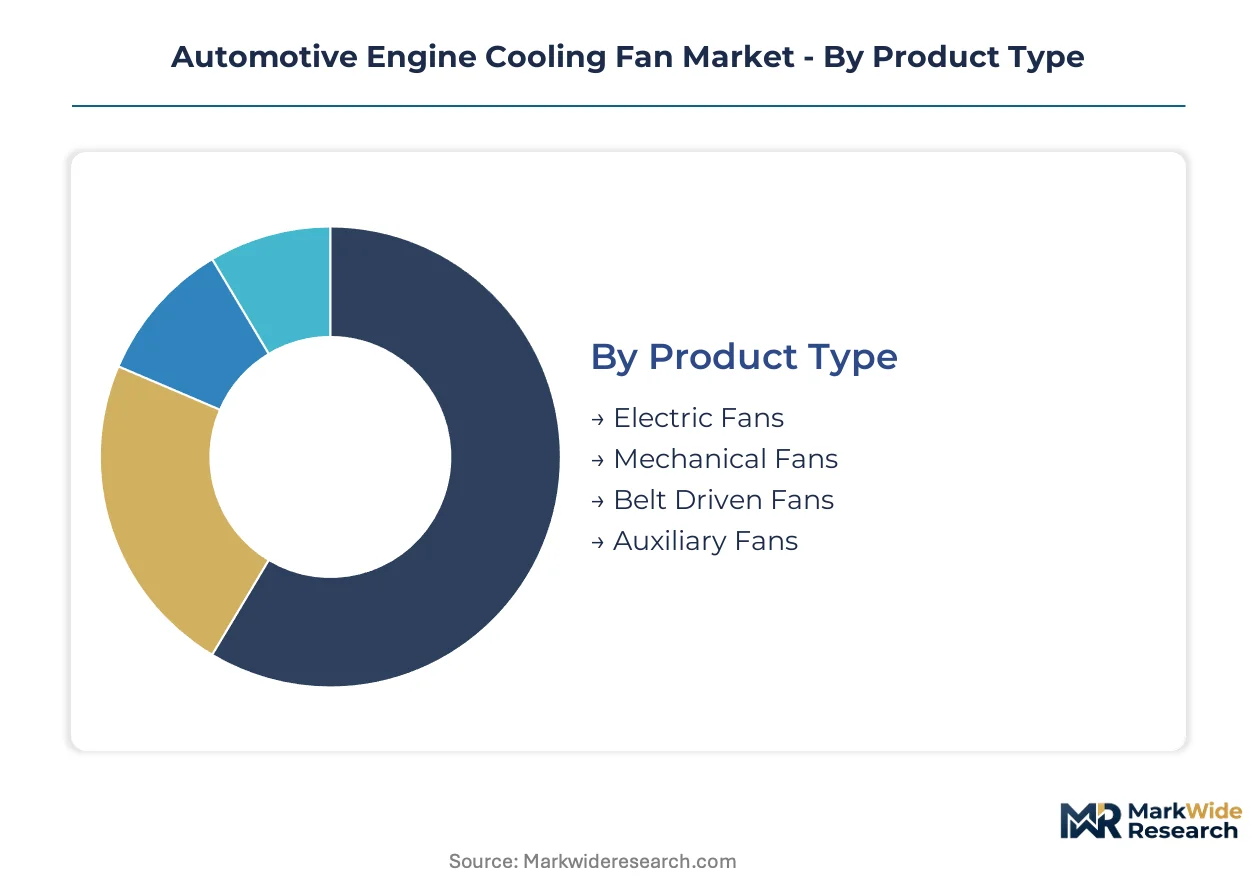
Segmentation in the automotive engine cooling fan market reflects the technology transition from mechanical to electromechanical thermal management. Procurement patterns diverge sharply between OEM channels seeking integrated motor-control solutions and aftermarket providers focused on refurbishment services.
Product Type:
Mature belt-driven configurations coexist with emerging electric architectures as commercial fleets retrofit legacy platforms.
- Electric Fans:Brushless DC motor assemblies with integrated speed controllers dominate new vehicle specifications. German and Japanese OEMs specify these for hybrid powertrain dual-loop cooling systems.
- Mechanical Fans:Direct engine-coupled designs using stamped steel or composite blade constructions persist in cost-sensitive commercial segments. EPA Phase 3 standards are accelerating replacement schedules in North American heavy-duty fleets.
- Belt Driven Fans:Legacy serpentine-belt configurations with viscous clutches serve budget vehicle platforms and developing market commercial vehicles.
- Auxiliary Fans:Supplementary cooling units for transmission oil coolers and charge air coolers address thermal loads in high-performance applications.
Electric fans handle the majority of throughput; auxiliary fans are gaining share fastest in performance and hybrid segments.
Technology:
Cost tiers separate premium brushless systems from commodity fixed-speed alternatives across procurement contracts.
- Brushless:Electronically commutated motor architectures with rare earth magnet rotors deliver efficiency gains and electromagnetic compatibility with stop-start systems. Supply concentration in China's neodymium processing infrastructure creates sourcing volatility.
- Variable Speed:Pulse-width-modulated control systems optimize airflow based on real-time thermal load. Fleet operators in North America deploy these for predictive thermal management contracts.
- Fixed Speed:Single-speed on-off operation serves entry-level passenger vehicles where thermal calibration complexity must be minimized.
- Dual Speed:Two-stage motor windings provide basic load adaptation for mid-range commercial vehicles without full variable-speed electronics.
Brushless systems command the steepest expansion trajectory; fixed-speed products retain volume in budget segments.
End User:
Customer type determines whether procurement bundles hardware with embedded software or sources components separately.
- OEMs:Integrated thermal module specifications combining fans with active grille shutters and temperature sensors. These buyers negotiate multi-year calibration service contracts alongside hardware.
- Aftermarket Providers:Independent distributors and service chains focus on brushless motor refurbishment and predictive diagnostics. Revenue is tilting toward recurring maintenance contracts.
- Vehicle Assemblers:Contract manufacturers and kit builders sourcing open-catalog fan assemblies without proprietary thermal mapping software.
- Fleet Operators:Commercial vehicle buyers unbundling hardware from calibration services, sourcing through digital procurement platforms.
OEMs concentrate procurement authority; fleet operators are expanding fastest as retrofit demand accelerates.
Application:
Application scope spans passenger comfort priorities through commercial durability requirements.
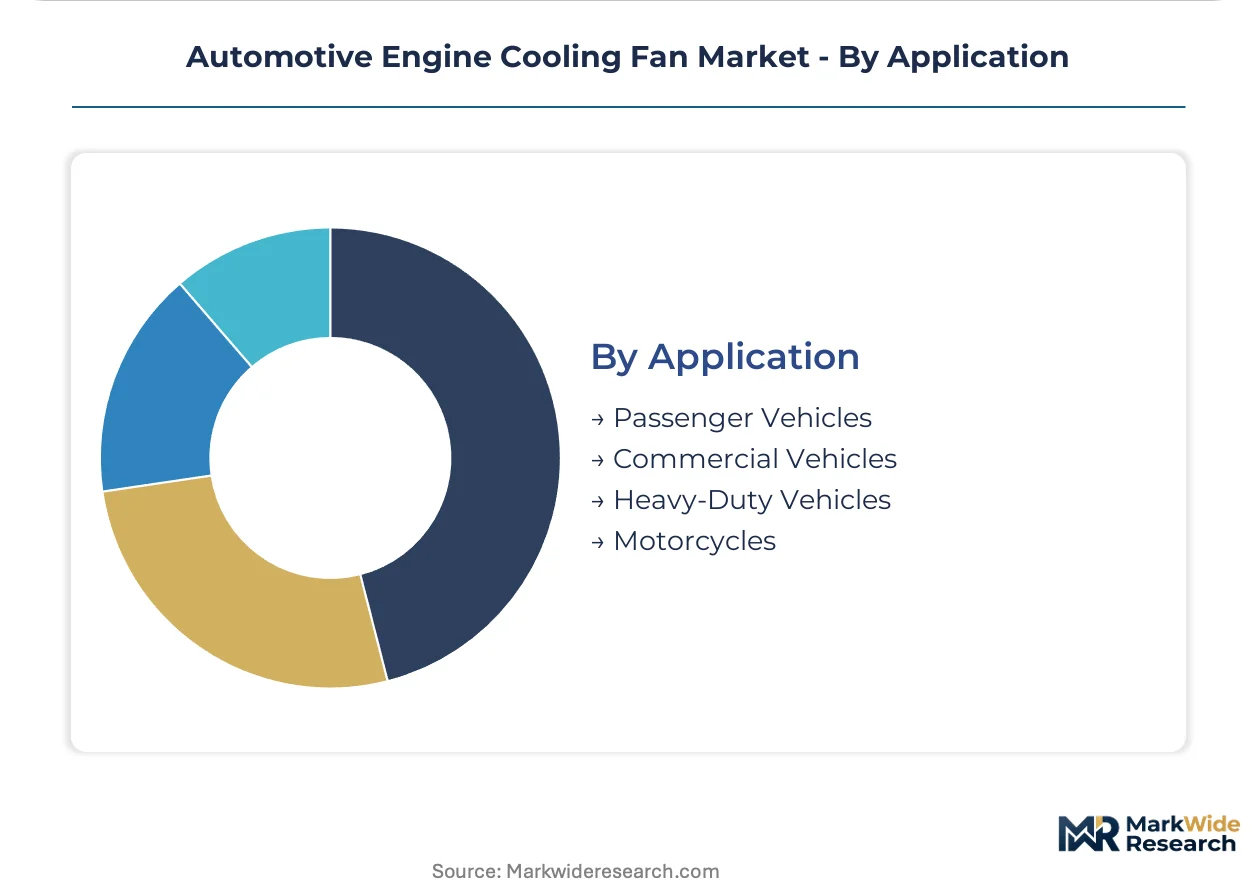
- Passenger Vehicles:Noise-optimized blade designs with polyamide-reinforced composites for thermal efficiency and acoustic comfort. Stop-start compatibility drives brushless adoption.
- Commercial Vehicles:Heavy-duty thermal loads require redundant cooling capacity. EPA and NHTSA regulations mandate efficiency improvements that favor electric retrofits.
- Heavy-Duty Vehicles:Continuous-duty cycles exceeding 10,000 hours at 120°C ambient drive specification of stamped steel constructions and sealed bearing assemblies.
- Motorcycles:Compact electric fans with high power density address space-constrained cooling in performance and touring segments.
Commercial vehicles generate the highest unit volumes; motorcycles are climbing fastest on electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooling fan procurement patterns diverge sharply by geography. The United States prioritizes heavy-duty fleet retrofits under tightening emissions rules. Germany and Japan lead hybrid-thermal redesigns. China concentrates rare-earth processing for brushless motors. India commercial vehicle electrification opens new specification windows.
United States
Heavy-duty diesel fleets dominate cooling fan demand as operators retrofit legacy trucks to meet EPA Phase 3 standards. The NHTSA corporate average fuel economy framework pushes OEMs toward electric fan architectures that cut parasitic losses. Manufacturing clusters in Michigan and Ohio supply thermal modules for Detroit-based vehicle programs.
Germany
Hybrid powertrain proliferation drives dual-loop cooling system specifications across passenger and commercial platforms. The KBA enforces thermal efficiency benchmarks that shape export-ready component designs. Suppliers in Baden-Württemberg and Bavaria develop integrated motor-control modules for European OEM thermal architectures.
Japan
Stop-start system penetration accelerates brushless DC motor adoption to ensure electromagnetic compatibility. METI efficiency guidelines push thermal management redesigns for hybrid and range-extended vehicles. Industrial concentration in Aichi and Kanagawa prefectures supports precision motor manufacturing for domestic OEM supply chains.
China
Rare earth magnet processing infrastructure concentrates neodymium and dysprosium supply for brushless motor rotors. MIIT thermal efficiency standards align domestic vehicle production with export market requirements. Manufacturing hubs in Jiangsu and Zhejiang provinces produce fan assemblies for both local OEMs and international tier-1 suppliers.
India
Commercial vehicle electrification creates specification opportunities as the Bureau of Indian Standards finalizes thermal management norms for electric buses. State transport undertakings in Maharashtra and Karnataka pilot localized brushless motor production for fleet retrofits. Tamil Nadu automotive clusters expand component sourcing for thermal system integrators.
Automotive Engine Cooling Fan Market Competitive Landscape
Capability concentration sits with integrated motor-control specialists; scale advantage sits with diversified thermal module suppliers. The vendor base separates into three tiers: multinational tier-1 system integrators, regional motor specialists, and commodity fan assemblers. Strategic moves center on active grille shutter partnerships and predictive thermal algorithm development. Geographic expansion into Indian commercial vehicle electrification and unbundled fleet procurement platforms represent dominant competitive vectors.
Within the integrated motor-control tier, DENSO Corporation and Valeo SA occupy positions defined by embedded software calibration capabilities and modular assembly architectures. Robert Bosch GmbH anchors the European OEM channel through temperature-sensor-integrated module supply. These three entities exemplify the shift toward firmware-driven margin capture as hardware commoditization pressures intensify across brushless motor production.
| Leading Market Players |
|---|
| DENSO Corporation |
| Valeo SA |
| Robert Bosch GmbH |
| Continental AG |
| SPAL Automotive |
| MAHLE GmbH |
| BorgWarner Inc. |
| Johnson Electric Holdings Limited |
| Delta Electronics, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's rare earth magnet processing infrastructure is compressing supplier margins while amplifying pricing volatility for brushless motor manufacturers serving North American and European OEMs. This utilization imbalance forces tier-1 suppliers to absorb cost fluctuations or renegotiate long-term offtake terms with fleet operators seeking fixed-price thermal module contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement between OEMs and integrated motor-control specialists, while spot-market transactions persist for commodity fan blade materials. Three-tier pricing structure across premium brushless systems, standard variable-speed units, and economy fixed-speed alternatives separates buyers by thermal calibration complexity and electromagnetic compatibility certification. Pricing pressure stems from polyamide composite input volatility and CISPR 25 testing cost absorption. Fleet operators exhibit highest price sensitivity as they unbundle hardware from software services, while premium OEMs prioritize thermal efficiency over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts neodymium magnet flows for brushless motor rotors concentrated in Jiangsu and Zhejiang provinces. The supply chain draws from China's rare earth processing, Germany's precision motor manufacturing, and Mexico's nearshore assembly for North American vehicle programs. Critical dependencies include neodymium-dysprosium alloys, glass-fiber-reinforced polyamide compounds, and temperature sensor modules. Single-source vulnerability in Chinese magnet refining creates procurement risk. Distribution runs through tier-1 system integrators to OEM assembly plants and aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 greenhouse gas standards are accelerating a technology disruption that favors electric fan architectures over legacy belt-driven systems, compressing the window for suppliers to reposition their portfolios.
For Market Incumbents: Harden embedded software calibration capabilities to defend against firmware commoditization as hardware margins compress. Deepen backward integration into rare earth magnet sourcing or secure captive supply agreements with Chinese processors to mitigate export control volatility. Expand predictive thermal algorithm development to capture recurring service revenue from fleet operators unbundling procurement. For New Entrants and Emerging Players: Pursue localized brushless motor production for India's electric bus fleet retrofits as the Bureau of Indian Standards finalizes thermal management norms. Target aftermarket diagnostic services for bearing assembly refurbishment where incumbent coverage remains fragmented. Lead with open-catalog hardware platforms paired with unbundled calibration software to penetrate fleet procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward integrated motor-control specialists with proprietary thermal mapping IP and established OEM calibration service contracts. The five-to-ten year viability window favors acquirers who can consolidate firmware development capabilities ahead of hardware commoditization. Watch for inflection signals in active grille shutter partnership announcements as indicators of front-end thermal module consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Standardization | Reduces OEM validation cycles across hybrid and electric vehicle architectures. |
| Rare Earth Magnet Supply Agreement | Secures neodymium processing capacity from China's Jiangsu province infrastructure. |
| Predictive Thermal Algorithm Development | Captures recurring revenue from fleet operators deploying sensor-integrated modules. |
| Active Grille Shutter Partnership | Integrates cooling fans with front-end thermal modules for European OEM programs. |
| Aftermarket Diagnostic Service Launch | Monetizes brushless motor refurbishment through predictive maintenance contracts. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EPA regulatory filings, and customs trade records. Bottom-up volume modeling triangulated with top-down market sizing across propulsion architecture, vehicle class, and regional production clusters.
Scenario-bracketing around EPA Phase 3 implementation timing and hybrid powertrain penetration rates framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, motor technology tier, end-user procurement pattern, and application thermal load. CAGRs derived from correlated growth drivers spanning regulatory compliance deadlines, powertrain electrification curves, and aftermarket service contract expansion. Industry-specific inputs incorporated rare earth magnet price indices and CISPR 25 certification cycle durations.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle fleet investment cycles or Chinese export control enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding thermal efficiency mandate adoption and brushless motor cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Automotive Belts Market