
 Automotive Parking Heater Market | 2026-2036
Automotive Parking Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Parking Heater Market Analysis
Aluminum heat exchangers are rebalancing cost structures against traditional copper-brass cores in parking heater assemblies. Eberspächer Gruppe GmbH & Co. KG leverages captive foundry capacity in Germany to control thermal-component costs. Webasto SE sustains broad OEM relationships across passenger and commercial vehicle programs. Hebei Nanfeng Automobile Equipment (Group) Co., Ltd. anchors volume production for Asia-Pacific supply chains with localized diesel-hydronic platforms.
An automotive parking heater is an auxiliary thermal device that pre-warms engine coolant or cabin air independently of main engine operation, typically drawing 12–24V electrical power and achieving combustion temperatures of 800–1,200°C in fuel-fired variants. Its primary purpose is to eliminate cold-start emissions, reduce engine wear, and deliver occupant comfort in ambient conditions below -10°C. Diesel heaters occupy the largest installed base in heavy commercial vehicles where overnight idling restrictions apply. Electric heaters are gaining share in battery-electric platforms where waste heat from internal combustion is unavailable. Fixed installation systems dominate OEM fitment, while modular units capture retrofit demand from aftermarket providers serving cold-climate owner-operators.
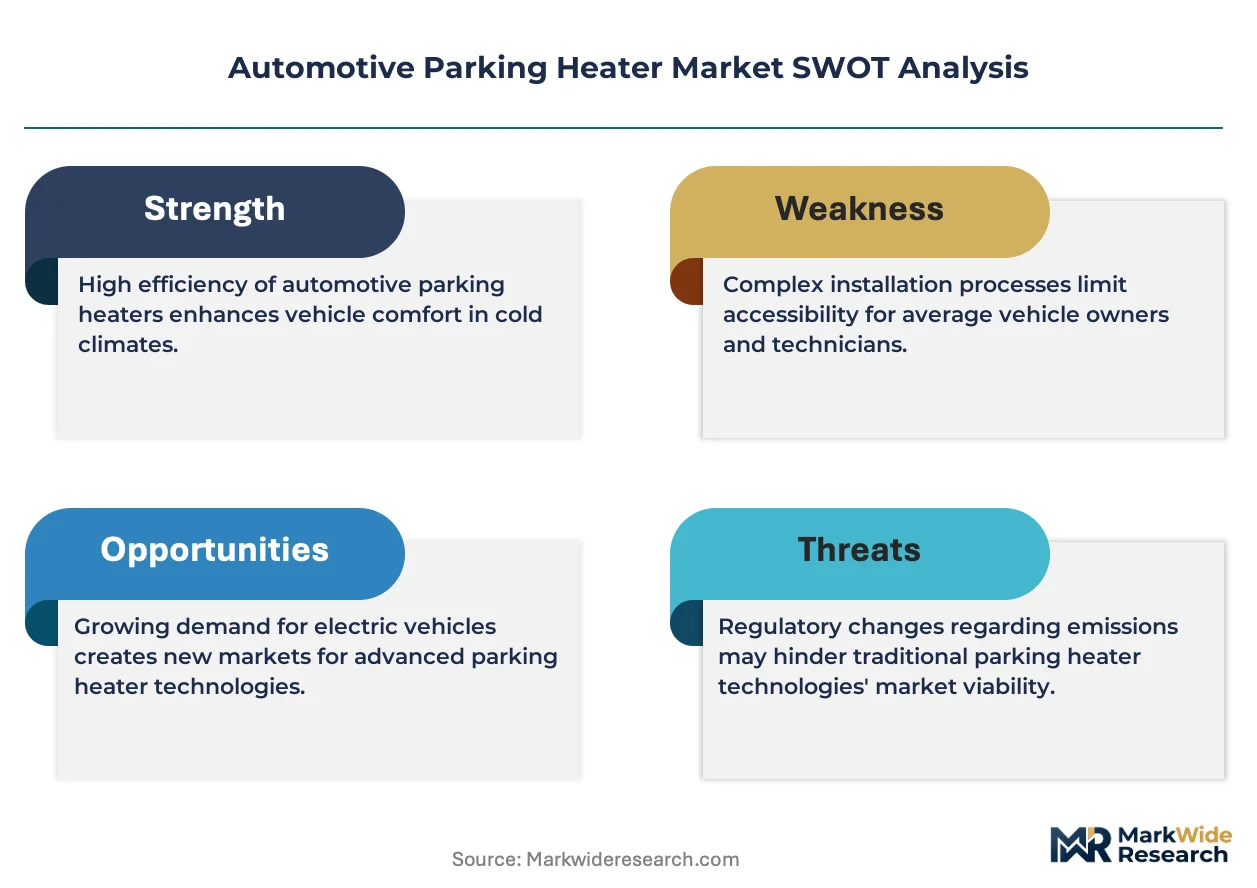
NHTSA safety standards govern electrical isolation and fire suppression in cabin heating systems sold into the United States. EPA emission thresholds for small non-road engines constrain hydrocarbon-burning heater designs in California and federal jurisdictions. ECE R122 type approval administered by Germany's KBA shapes baseline safety architecture for heaters sold across Europe. Stakeholders must monitor divergence between EPA tailpipe rules and EU Green Deal thermal-efficiency benchmarks when allocating R&D across regional product lines.
Market Dynamics
Electrification of thermal management architectures is forcing incumbents to reengineer combustion-based platforms while defending installed bases in heavy commercial fleets. This structural pivot compresses development cycles and fragments R&D allocation across incompatible technology paths.
Growth Catalysts
- Euro 7 emission thresholds:Stringent particulate limits for auxiliary engines are accelerating OEM integration of electric pre-conditioning systems in light commercial vehicles across Germany, France, and Italy.
- Fleet electrification mandates:Battery-electric bus operators in Scandinavia require cabin heating without engine waste heat, creating dedicated demand for high-voltage electric heater modules.
- Idling restriction enforcement:Overnight engine ban ordinances in Canadian provinces and US states are compelling long-haul operators to adopt fuel-fired parking heaters as compliance equipment.
Market Restraints
- Aluminum alloy price volatility:Heat exchanger manufacturers face margin compression when LME aluminum spikes, as copper-brass alternatives carry weight penalties unacceptable for OEM fuel-economy targets.
- Foundry capacity concentration:Precision die-casting for burner housings clusters in southern Germany and eastern China, exposing supply chains to regional energy cost shocks or logistics disruptions.
- Combustion heater technical ceiling:Fuel-fired units cannot achieve zero tailpipe emissions, hard-capping their addressable market as cities implement low-emission zones barring diesel auxiliary engines.
Strategic Opportunities
- India commercial vehicle aftermarket:Cold-chain logistics expansion into Himalayan corridor routes creates first-time demand for retrofit hydronic heaters among refrigerated truck owner-operators.
- Vehicle-to-grid thermal integration:Bidirectional charging infrastructure enables parked EVs to sell stored energy while running cabin heaters, creating new revenue streams for fleet managers.
- US Inflation Reduction Act clean commercial vehicle credits:Tax incentives for zero-emission trucks indirectly subsidize electric heater adoption by improving total cost of ownership calculations for thermal system upgrades.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 compliance for automotive-grade heater controllers requires specialized embedded systems talent concentrated in Germany and Japan, elongating hiring timelines.
- Dual certification burden:Suppliers must secure both ECE R122 type approval and EPA small non-road engine certification to serve transatlantic OEM programs, duplicating test cycles and documentation costs.
- Legacy fleet integration complexity:Retrofit electric heaters into existing diesel vehicle electrical architectures demand custom harness engineering and battery capacity upgrades, constraining aftermarket scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Parking Heater Market |
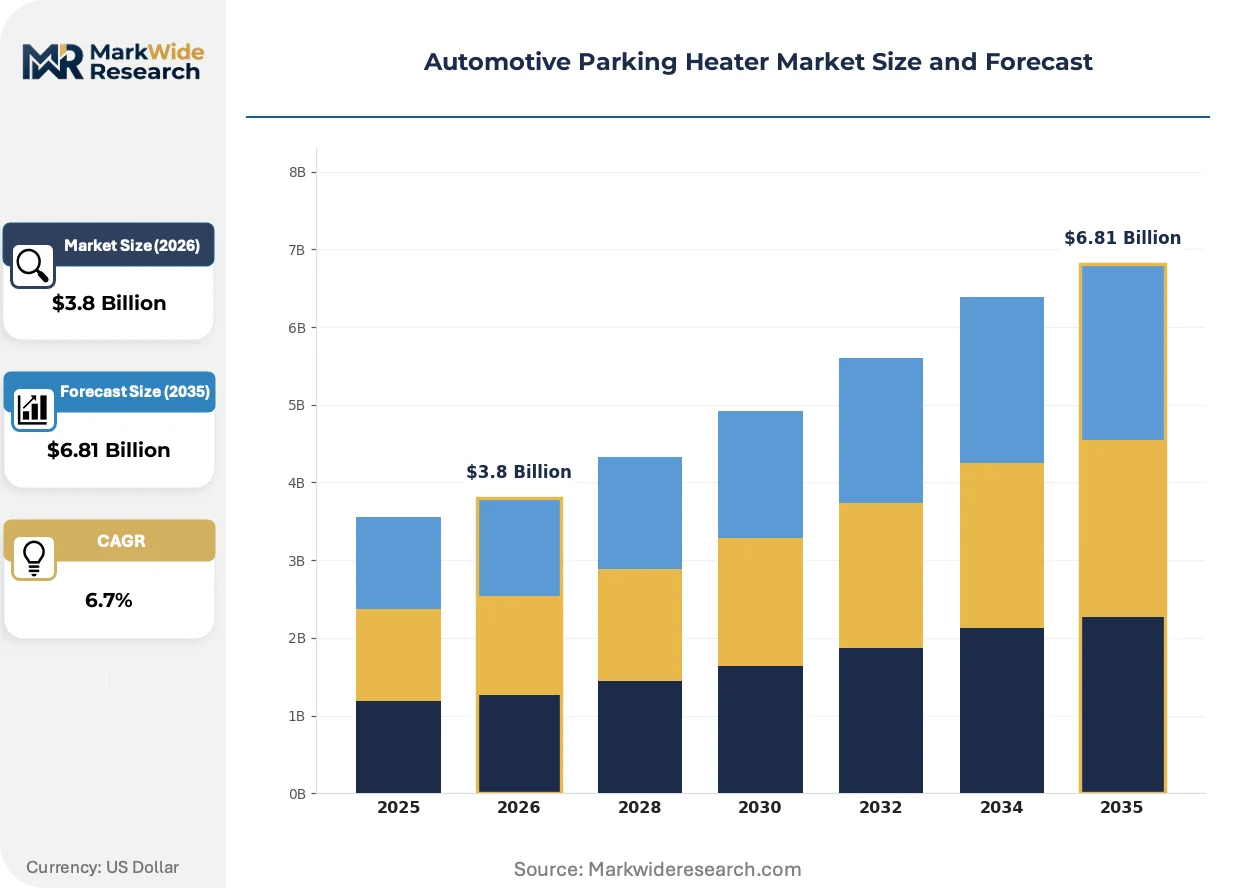
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Heaters, Gas Heaters, Electric Heaters, Hydronic Heaters End User: OEMs, Dealerships, Aftermarket Providers, Vehicle Assemblers Installation Type: Portable Installation, Fixed Installation, Integrated Systems, Modular Units Fuel Type: Diesel, Gasoline, Propane, Electric |
| Companies Covered | Webasto SE, Eberspächer Gruppe GmbH & Co. KG, Truma Gerätetechnik GmbH & Co. KG, DEFA AS, Calix AB, DBK David + Baader GmbH, Hebei Nanfeng Automobile Equipment (Group) Co., Ltd., Planar Heating Co. Ltd., Proheat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Parking Heater Market Emerging Trajectories
Carbon-based heating elements and solid-state power electronics are redefining thermal efficiency benchmarks while regulatory pressure on combustion particulates intensifies. These forces are compressing the technology lifecycle for conventional fuel-fired architectures.
Silicon carbide power semiconductors are absorbing switching losses in high-voltage electric heater inverters, enabling faster cabin warm-up cycles with reduced battery drain. Battery-electric truck manufacturers in Sweden and Norway are specifying SiC-based thermal modules for sub-zero operating conditions. This transition is absorbing engineering resources from incumbent suppliers' legacy combustion heater divisions, accelerating portfolio rationalization.
EPA small non-road engine emission standards are tightening hydrocarbon limits for auxiliary power units, compelling heater manufacturers to deploy after-treatment catalysts or abandon fuel-fired designs for California-compliant variants. The compliance burden falls heaviest on compact gasoline heaters serving recreational vehicle aftermarket channels, where price sensitivity limits absorption of catalytic converter costs. Suppliers are responding with geographic product segmentation, withholding catalyst-equipped SKUs from non-CARB jurisdictions to preserve margin.
Direct-to-fleet procurement platforms are disintermediating traditional aftermarket distributors for high-volume heater orders. Large logistics operators in Germany and the Netherlands are negotiating frame agreements with heater OEMs for standardized pre-conditioning specifications across tractor replacement cycles. This consolidation concentrates specification-setting power with procurement functions at Deutsche Post DHL and similar operators, marginalizing independent service networks that historically influenced retrofit decisions.
Automotive Parking Heater Market Segmentation
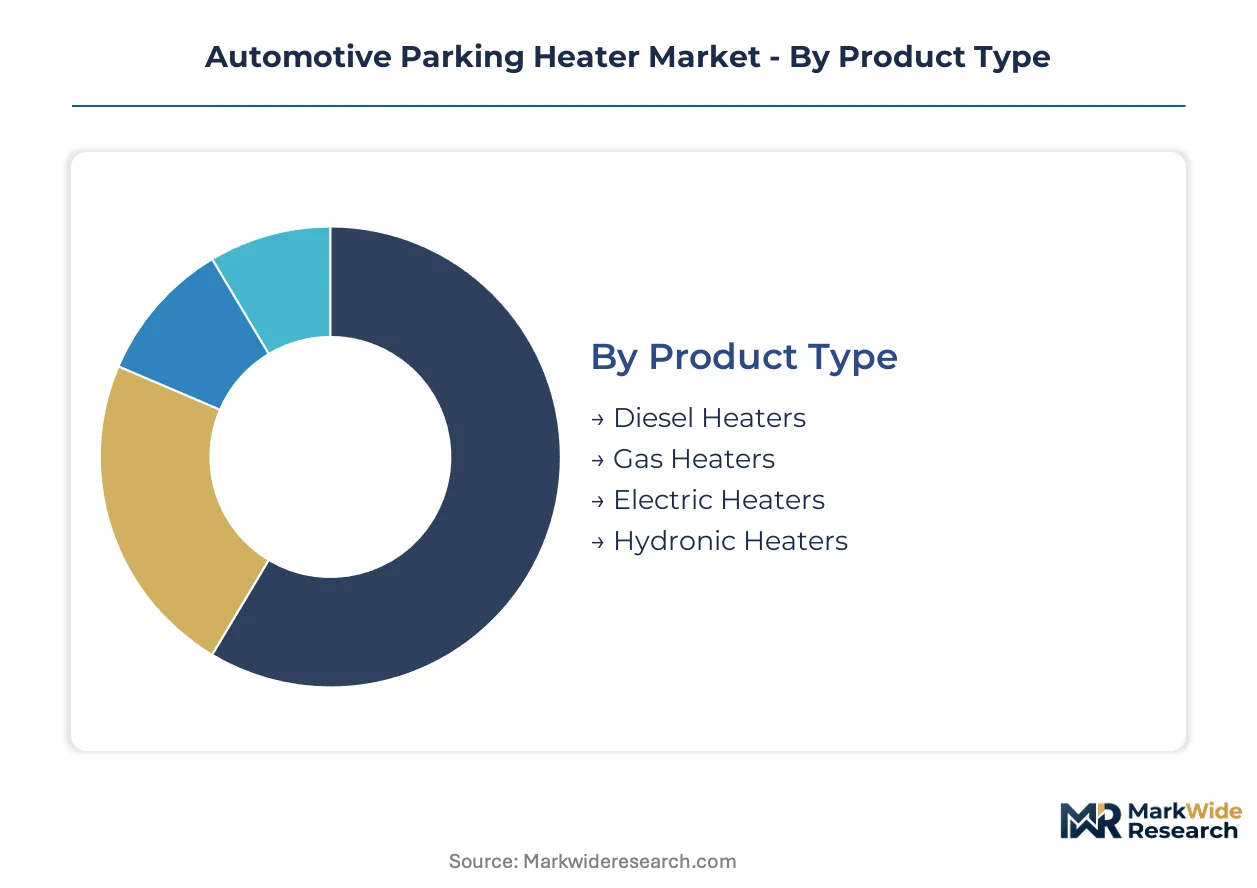
Segmentation in automotive parking heaters reveals how regulatory pressure and fleet electrification are fragmenting demand across incompatible technology platforms. Supply chain configuration varies sharply by product architecture, with combustion-based systems clustering around foundry-dependent manufacturing while electric variants depend on semiconductor and power electronics ecosystems.
Product Type:
Supply concentration for diesel heater burner housings clusters in southern Germany and eastern China, creating divergent cost structures against electric alternatives.
- Diesel Heaters:Fuel-fired units achieving combustion temperatures of 800–1,200°C through precision die-cast aluminum burner housings. Demand concentrates in heavy commercial fleets across Scandinavia and North America where overnight idling restrictions apply; Euro 7 particulate limits are forcing costly after-treatment additions.
- Electric Heaters:High-voltage modules drawing from battery-electric vehicle architectures, utilizing silicon carbide power semiconductors to minimize switching losses. Battery-electric bus operators in Sweden and Norway specify these for sub-zero cabin conditioning; waste heat unavailability in BEVs makes these mandatory rather than optional.
- Gas Heaters:Compact gasoline-burning variants serving recreational vehicle aftermarket channels.
- Hydronic Heaters:Engine coolant pre-conditioning systems integrated into commercial vehicle thermal management loops.
Today's leader: Diesel Heaters. Tomorrow's challenger: Electric Heaters.
End User:
Procurement centralization among large logistics operators is compressing margins for traditional aftermarket channels.
- OEMs:Original equipment manufacturers specify parking heaters during vehicle platform development, integrating thermal management into electrical architectures at design stage. Light commercial vehicle programs across Germany, France, and Italy are accelerating electric pre-conditioning integration to meet Euro 7 thresholds.
- Aftermarket Providers:Independent service networks and retrofit specialists serving cold-climate owner-operators with modular installation solutions. Refrigerated truck operators in India's Himalayan corridor routes are emerging as first-time demand sources for hydronic retrofit kits.
- Dealerships:Authorized distribution points for brand-compliant heater accessories and warranty service.
- Vehicle Assemblers:Contract manufacturers integrating heater subsystems into finished vehicle production.
OEMs command specification authority. Aftermarket Providers capture geographic expansion.
Installation Type:
Fixed installation systems dominate where factory integration enables regulatory compliance documentation.
- Fixed Installation:Permanent mounting configurations factory-integrated into vehicle platforms with full ECE R122 type approval documentation. OEM fitment across passenger and commercial vehicle programs requires ISO 26262 functional safety compliance for heater controllers.
- Modular Units:Retrofit-compatible systems enabling aftermarket deployment without platform redesign. Long-haul operators in Canadian provinces adopt these as compliance equipment under overnight engine ban ordinances; custom harness engineering demands constrain scalability.
- Portable Installation:Temporary deployment configurations for non-permanent heating requirements.
- Integrated Systems:Fully embedded thermal management architectures sharing components with HVAC and battery conditioning loops.
Fixed Installation locks in OEM relationships. Modular Units unlock fleet retrofit opportunities.
Fuel Type:
Margin structures diverge between hydrocarbon-burning variants facing emission compliance costs and electric alternatives absorbing battery capacity trade-offs.
- Diesel:Dominant fuel for commercial vehicle auxiliary heaters, constrained by EPA small non-road engine emission thresholds and urban low-emission zone restrictions.
- Electric:Grid and battery-sourced power eliminating tailpipe emissions entirely; vehicle-to-grid thermal integration creates new revenue streams for parked EVs selling stored energy.
- Gasoline:Compact heater fuel serving price-sensitive recreational vehicle channels where catalytic converter costs face absorption limits.
- Propane:Alternative hydrocarbon fuel for specialized off-highway and remote operation applications.
Diesel retains installed base dominance. Electric posts the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's southern industrial corridor houses the densest concentration of automotive parking heater engineering and captive foundry capacity for precision die-cast thermal components.
Germany
Cold-climate fleet operators across Bavaria and Baden-Württemberg demand pre-conditioning systems to cut engine wear and cabin warm-up times. KBA-administered ECE R122 type approval shapes baseline safety architecture for heaters distributed across Europe. Stuttgart and Munich anchor manufacturing clusters where Eberspächer Gruppe GmbH & Co. KG and Webasto SE maintain captive foundry operations.
United States
Long-haul operators in Minnesota, North Dakota, and Alaska face overnight idling restrictions that compel fuel-fired parking heater adoption as compliance equipment. NHTSA safety standards govern electrical isolation and fire suppression in cabin heating systems nationwide. Detroit's automotive supplier ecosystem concentrates thermal management engineering talent serving domestic OEM programs.
China
GB 18352.6-2016 compliance requirements accelerate shifts from fuel-burning heaters to electric thermal management in light commercial vehicles. Battery-electric bus fleets in Harbin and Changchun require high-voltage cabin heating without engine waste heat. Hebei province anchors volume production through Hebei Nanfeng Automobile Equipment (Group) Co., Ltd. for Asia-Pacific supply chains.
Sweden
Scandinavian fleet electrification mandates create dedicated demand for electric heater modules in battery-electric bus operations. National low-emission zone frameworks in Stockholm and Gothenburg hard-cap diesel auxiliary engine deployments. Göteborg's automotive engineering cluster concentrates silicon carbide power electronics development for sub-zero thermal applications.
Canada
Provincial overnight engine ban ordinances in Ontario, Quebec, and Alberta drive retrofit hydronic heater installations among refrigerated truck operators. Environment Canada emission thresholds align with tightening EPA small non-road engine standards for cross-border fleet compatibility. Toronto and Calgary serve as distribution hubs for aftermarket thermal equipment penetrating northern resource extraction corridors.
Automotive Parking Heater Market Vendor Landscape
Global majors compete with regional champions across thermal management engineering and foundry-dependent manufacturing cost structures. The vendor base stratifies into combustion-platform incumbents defending heavy commercial installed bases and electric-thermal specialists capturing battery-electric vehicle mandates. Three archetypes dominate: captive-foundry integrated German engineering houses, Asia-Pacific volume manufacturers with localized diesel-hydronic platforms, and Nordic electric-thermal specialists. Competitive moves concentrate on portfolio diversification across incompatible technology paths and geographic expansion into India's Himalayan cold-chain corridors.
Among German-based engineering houses, Eberspächer Gruppe GmbH & Co. KG and Webasto SE occupy positions exemplifying captive-foundry integration and broad OEM relationship maintenance. Hebei Nanfeng Automobile Equipment (Group) Co., Ltd. represents the Asia-Pacific volume manufacturing archetype with localized production platforms. Truma Gerätetechnik GmbH & Co. KG sits within the specialized recreational vehicle equipment tier. These three anchors illustrate how competitive positioning fragments across technology generations and regional supply chain configurations.
| Leading Market Players |
|---|
| Webasto SE |
| Eberspächer Gruppe GmbH & Co. KG |
| Truma Gerätetechnik GmbH & Co. KG |
| DEFA AS |
| Calix AB |
| DBK David + Baader GmbH |
| Hebei Nanfeng Automobile Equipment (Group) Co., Ltd. |
| Planar Heating Co. Ltd. |
| Proheat Inc. |
| Others |
Supply Flow & Price Mechanics
Captive foundry integration among German engineering houses anchors both supply security and pricing power in precision die-cast aluminum burner housings. Eberspächer and Webasto leverage in-house southern German casting capacity to buffer LME aluminum volatility while commanding OEM premiums for ECE R122-certified fixed installations.
Pricing Analysis
Aluminum alloy cost pass-through dominates margin structures for combustion heater manufacturers when LME prices spike. Three-tier pricing structure across premium ECE R122-certified, standard EPA-compliant, and economy non-catalyst tiers reflects certification burden divergence. Cost compression in gasoline RV aftermarket channels intensifies because catalytic converter mandates face absorption limits. Fleet procurement departments at Deutsche Post DHL and similar operators exhibit lowest price sensitivity due to standardization benefits, while independent Himalayan corridor retrofitters remain most exposed.
Supply Chain Analysis
Precision die-cast aluminum supply rests on captive foundry capacity in southern Germany and eastern China's Hebei province. Silicon carbide power semiconductor sourcing draws from Sweden's Göteborg cluster and Japanese specialty ceramic producers. Single-source vulnerability concentrates in burner housing tooling where southern German mold-making expertise lacks ready substitutes. Distribution runs through direct-to-fleet procurement platforms disintermediating traditional aftermarket channels for high-volume orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Euro 7 particulate mandates and Scandinavian fleet electrification shift procurement toward premium-certified electric thermal modules.
For Market Incumbents: Hedge combustion-platform decline by accelerating silicon carbide inverter development for battery-electric bus mandates in Sweden and Norway. Secure captive foundry capacity expansions in eastern China to offset southern German energy cost exposure. Channel control through direct fleet frame agreements marginalizes independent service networks and locks in specification authority across replacement cycles. For New Entrants and Emerging Players: Direct-to-fleet procurement platforms offer the most penetrable route for electric heater specialists lacking legacy combustion installed bases. Target India's Himalayan cold-chain corridor for first-time hydronic retrofit demand among refrigerated truck owner-operators. Pursue vehicle-to-grid thermal integration software as a differentiated go-to-market angle capturing bidirectional charging revenue streams. For Investors and Strategic Acquirers: Roll-up economics work for Nordic electric-thermal specialists because battery-electric vehicle mandates create captive demand growth independent of hydrocarbon price cycles. Long-term viability favors acquirers of ISO 26262 functional safety engineering talent concentrated in Germany and Japan. Watch EPA small non-road engine standard tightening velocity as the inflection indicator for combustion heater portfolio rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Development | Enables sub-zero cabin warm-up for battery-electric trucks in Scandinavian fleets without excessive battery drain. |
| Captive Foundry Capacity Expansion | Hebei province localization insulates against southern German energy cost shocks in precision die-casting operations. |
| Direct Fleet Procurement Platform Launch | Disintermediates aftermarket distributors and concentrates specification-setting power with large logistics operators. |
| Vehicle-to-Grid Thermal Integration | Creates revenue streams for parked EVs selling stored energy while running cabin heaters through bidirectional charging. |
| Euro 7 After-Treatment Catalyst Integration | Preserves diesel heater market access in German, French, and Italian low-emission zones facing particulate restrictions. |
Methodological Framework
Coverage spans Germany, China, Sweden, and North America, with primary inputs from each regional cluster combining interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and fleet thermal specification managers. Secondary validation draws from ECE R122 type approval databases, EPA small non-road engine certification records, vehicle production registries, and customs trade flows for aluminum alloy and silicon carbide components. Bottom-up unit economics triangulate against top-down addressable fleet population estimates.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. Segmentation dimensions span product architecture (diesel, electric, gasoline, hydronic), installation type (fixed, modular, portable), and end-user procurement mode (OEM specification, aftermarket retrofit, direct fleet). CAGRs derive from installed base turnover modeling and regulatory compliance deadline alignment. Industry-specific forecast inputs include Euro 7 implementation phasing and Scandinavian battery-electric bus fleet conversion schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook for high-voltage electric heater demand. Forecasts reflect assumptions about foundry capacity expansion timelines and semiconductor supply normalization. Regulatory divergence between EPA tailpipe rules and EU Green Deal benchmarks warrants ongoing watch as a revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Small Engine Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Drum Brake Market