
 North America Automotive Parts Zinc Die Casting Market | 2026-2036
North America Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Parts Zinc Die Casting Market Analytics
Mexico is narrowing its cost advantage as labor rates rise and logistics complexity grows across the border. Dynacast International LLC leverages its multi-plant footprint to sustain just-in-time delivery contracts with Detroit-based OEMs. Pace Industries anchors its position through specialized high-pressure die casting cells dedicated to transmission cases. Northwest Die Casting LLC competes on shorter lead times for low-volume chassis programs serving regional vehicle assemblers.
North America automotive parts zinc die casting involves injecting zinc alloys at pressures exceeding 1,000 bar into hardened steel molds to produce complex, net-shape components with wall thicknesses below one millimeter. The process yields parts with excellent dimensional stability, corrosion resistance, and electromagnetic shielding properties for under-hood and structural automotive applications. Engine components and transmission cases dominate volume demand, though control modules represent the fastest-expanding margin pool as electrified powertrains multiply sensor and housing requirements. High-pressure die casting leads technology deployment, while vacuum die casting gains share where porosity-sensitive brake and steering components require X-ray certification.
EPA Corporate Average Fuel Economy standards and NHTSA Federal Motor Vehicle Safety Standards directly shape alloy selection and part consolidation strategies, pressuring suppliers to demonstrate crashworthiness and recyclability. Mexico's environmental regulator SEMARNAT enforces foundry emissions rules that affect cross-border supply chain configuration for die casters operating maquiladora plants. Stakeholders must monitor evolving EPA tailpipe regulations and state-level zero-emission vehicle mandates that could redirect zinc demand toward thermal management housings for hybrid architectures.
Market Dynamics
The EPA Corporate Average Fuel Economy standards and NHTSA safety mandates are compressing design cycles for chassis and powertrain components, forcing die casters to prove crashworthiness and recyclability before contract award.
Growth Catalysts
- Lightweighting mandates:EPA fuel economy standards push automakers toward zinc alloys for precision chassis components that consolidate multiple steel stampings into single net-shape castings.
- Electrification sensor proliferation:Hybrid powertrain architectures multiply control module housing requirements across Michigan-Ohio and northern Mexico manufacturing corridors.
- High-pressure process maturation:Vacuum-assisted die casting technology enables X-ray-certified brake and steering components that command premium positioning in safety-critical applications.
Market Restraints
- Aluminum substitution pressure:Magnesium-aluminum alloys compete for transmission cases and structural brackets where weight reduction targets exceed zinc's density advantages.
- Cross-border logistics friction:Customs complexity and border congestion between Mexico and the United States erode just-in-time delivery reliability for maquiladora-dependent suppliers.
- Emissions compliance costs:SEMARNAT foundry emissions rules in Mexico require capital-intensive abatement systems that compress margins for mid-volume producers.
Strategic Opportunities
- Thermal management housing expansion:State-level zero-emission vehicle mandates in California and New York redirect zinc demand toward battery and inverter enclosures for hybrid architectures.
- Short-run chassis specialization:Regional vehicle assemblers in the US Southeast seek low-volume die casting partners for niche truck and SUV platforms bypassed by high-volume suppliers.
- Recyclability certification premium:OEM sustainability scorecards reward suppliers demonstrating closed-loop zinc recovery, creating margin differentiation beyond unit pricing.
Industry Challenges
- Tooling engineer scarcity:Hardened steel mold design expertise concentrates among aging specialists in the Great Lakes region, constraining capacity expansion timelines.
- Multi-physics simulation integration:Die casters must merge thermal, flow, and structural analysis tools to predict porosity and distortion before cutting production tooling.
- Legacy equipment retrofit costs:Older high-pressure cells require sensor and control system upgrades to meet traceability requirements for safety-critical brake components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Parts Zinc Die Casting Market |
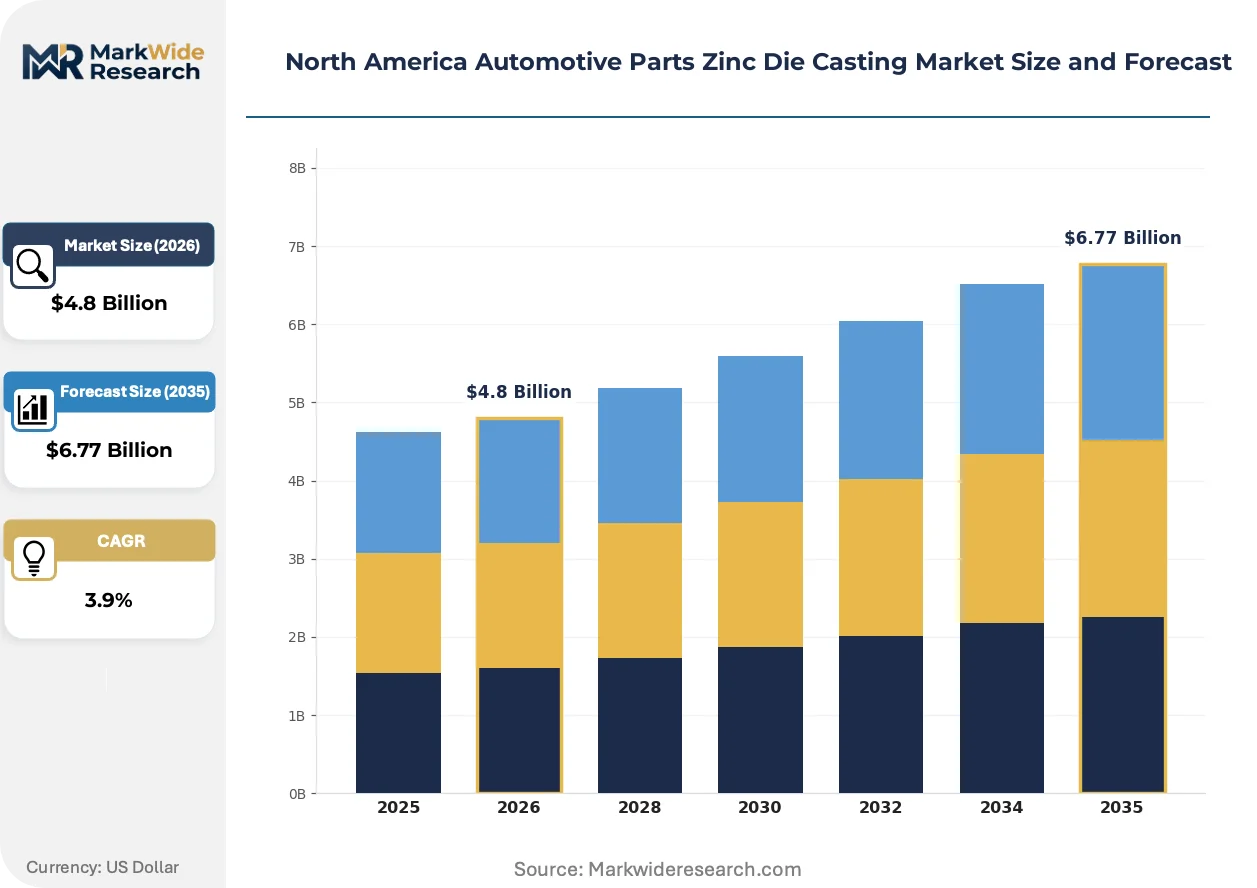
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Chassis Parts, Control Modules End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Form: Die Cast Parts, Machined Components, Finished Assemblies, Semi-Finished Goods Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Vacuum Die Casting, Permanent Mold Casting |
| Companies Covered | Dynacast International LLC, Pace Industries, Northwest Die Casting LLC, Texas Die Casting, Gibbs Die Casting, Weiss-Aug, Alcoa Corporation, Martinrea International Inc, Carteret Die Casting Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Parts Zinc Die Casting Market Evolving Landscape
Digital twin technology and real-time process monitoring are compressing qualification timelines for new die casting programs, while regulatory pressure on recyclability reshapes alloy sourcing strategies across the value chain.
Multi-cavity simulation software is virtualizing mold design validation before physical prototyping. Tier-1 suppliers in Detroit and Guanajuato deploy these tools to predict thermal gradients and solidification patterns. The technology is virtualizing traditional trial-and-error tooling iterations that once consumed months of development calendar.
EPA tailpipe regulations and California Air Resources Board zero-emission mandates are tightening material provenance requirements. Automakers now demand cradle-to-grave recyclability documentation for zinc alloy feedstock. Die casters serving Ford and GM powertrain divisions must certify closed-loop recovery rates to maintain preferred supplier status.
Fleet procurement departments are consolidating supplier rosters around vertically integrated partners capable of design, tooling, and finishing under single accountability. This concentration displaces fragmented vendor bases that previously segmented engineering from production. The shift is most visible among electric vehicle startups in Texas and Arizona seeking turnkey chassis component supply.
North America Automotive Parts Zinc Die Casting Market Segmentation
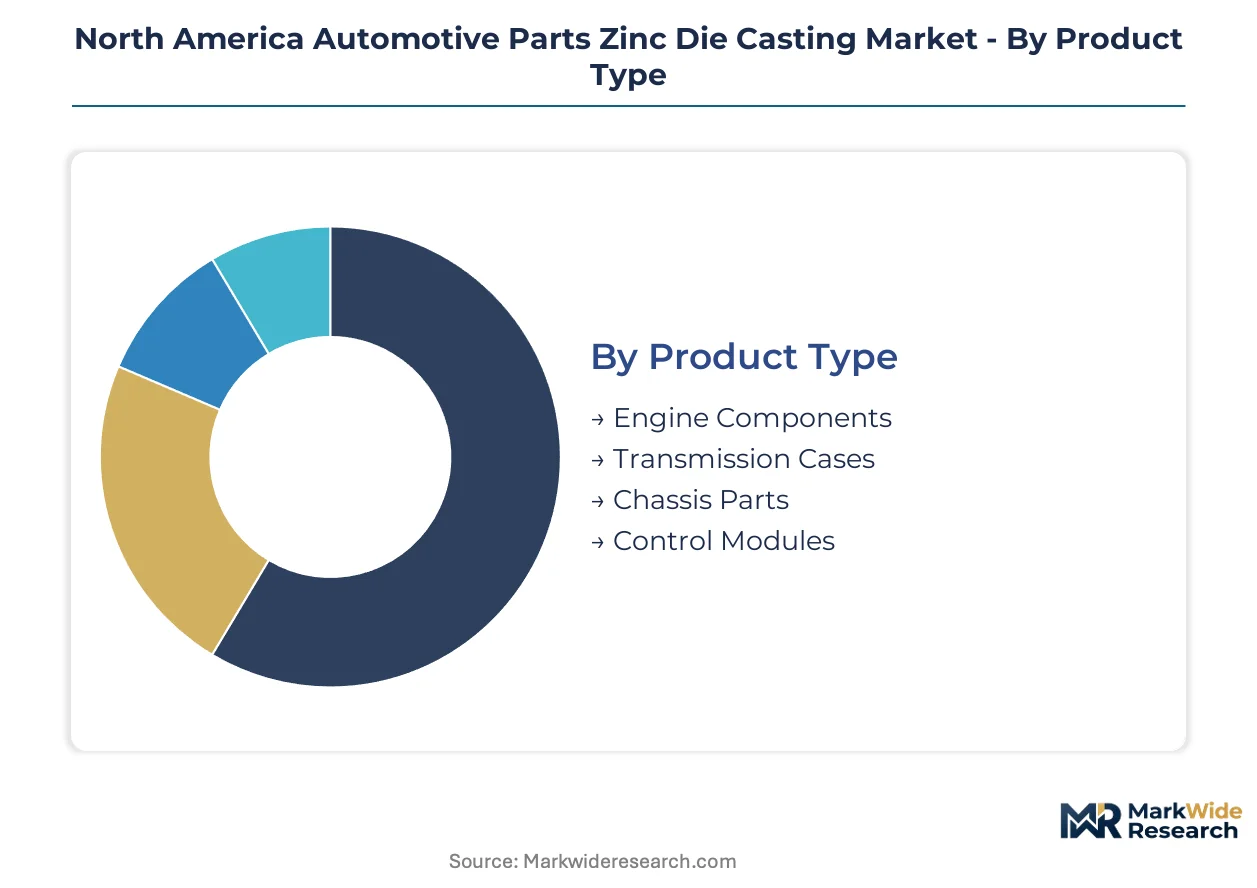
Zinc die casting procurement patterns diverge sharply across product maturity, customer integration depth, and process sophistication. Understanding these fault lines reveals where margin pools concentrate and which technical capabilities command premium positioning in contract negotiations.
Product Type:
Mature chassis applications coexist alongside emerging electrification-driven segments, creating a bifurcated investment landscape for die casters.
- Engine Components:Piston housings, valve covers, and timing chain enclosures utilize ZA-8 and ZA-12 alloys for thermal conductivity and wear resistance. Demand concentrates in Michigan-Ohio corridor rebuild programs as ICE platforms extend production runs amid hybrid transition delays.
- Transmission Cases:Complex multi-cavity housings for automatic and dual-clutch transmissions require porosity control below ASTM E505 Level 2. Mexico's Guanajuato and Querétaro clusters anchor volume production for Detroit Three OEMs seeking tariff-advantaged supply.
- Chassis Parts:Structural brackets and suspension knuckles consolidate multiple stamped steel assemblies into single zinc castings. EPA lightweighting mandates accelerate substitution in pickup truck platforms where payload capacity competes with fuel economy targets.
- Control Modules:Sensor housings and ECU enclosures for electrified powertrains demand electromagnetic shielding properties intrinsic to zinc alloys. California and New York zero-emission vehicle procurement rules multiply sensor counts per vehicle, expanding addressable unit volumes.
Transmission cases retain volume leadership; control modules hold the steepest expansion curve.
End User:
Customer integration depth determines qualification timelines and contract tenure, with captive foundry operations competing against independent suppliers for platform awards.
- OEMs:Ford, GM, and Stellantis operate captive zinc die casting facilities for powertrain-critical components, prioritizing design control over unit cost. NHTSA safety certification requirements favor in-house production for brake and steering hardware.
- Aftermarket Providers:Independent distributors serving collision repair and classic vehicle restoration prioritize inventory breadth over tooling investment. Regional warehouse networks in Texas and California anchor distribution.
- Tier-1 Suppliers:Dana, Magna, and ZF source zinc castings for subsystem integration into larger modules, demanding single-source accountability across design, tooling, and finishing. JIT delivery contracts concentrate around Detroit metropolitan logistics hubs.
- Vehicle Assemblers:Electric vehicle startups in Texas and Arizona seek turnkey chassis component supply, consolidating fragmented vendor bases that previously segmented engineering from production.
Tier-1 suppliers dominate contract value; vehicle assemblers are climbing the fastest as EV production scales.
Form:
Value-added processing intensity separates commodity feedstock from engineered solutions capable of capturing design-in relationships.
- Die Cast Parts:Net-shape castings delivered to customer machining centers for final dimensional refinement. Standard tolerance bands of ±0.05 mm suit high-volume powertrain applications where downstream processing is captive.
- Machined Components:Post-cast CNC finishing achieves precision surfaces for sealing interfaces and bearing bores. Michigan-based suppliers invest in five-axis machining centers to capture margin beyond raw casting value.
- Finished Assemblies:Fully integrated modules incorporating insert molding, surface coating, and functional testing. OEM sustainability scorecards reward suppliers demonstrating closed-loop zinc recovery.
- Semi-Finished Goods:Shot-blasted and trimmed castings awaiting customer-specific heat treatment or impregnation. Mexico maquiladora plants favor this form to minimize capital intensity while preserving tariff advantages.
Finished assemblies command premium positioning; machined components gain share fastest as tolerance requirements tighten.
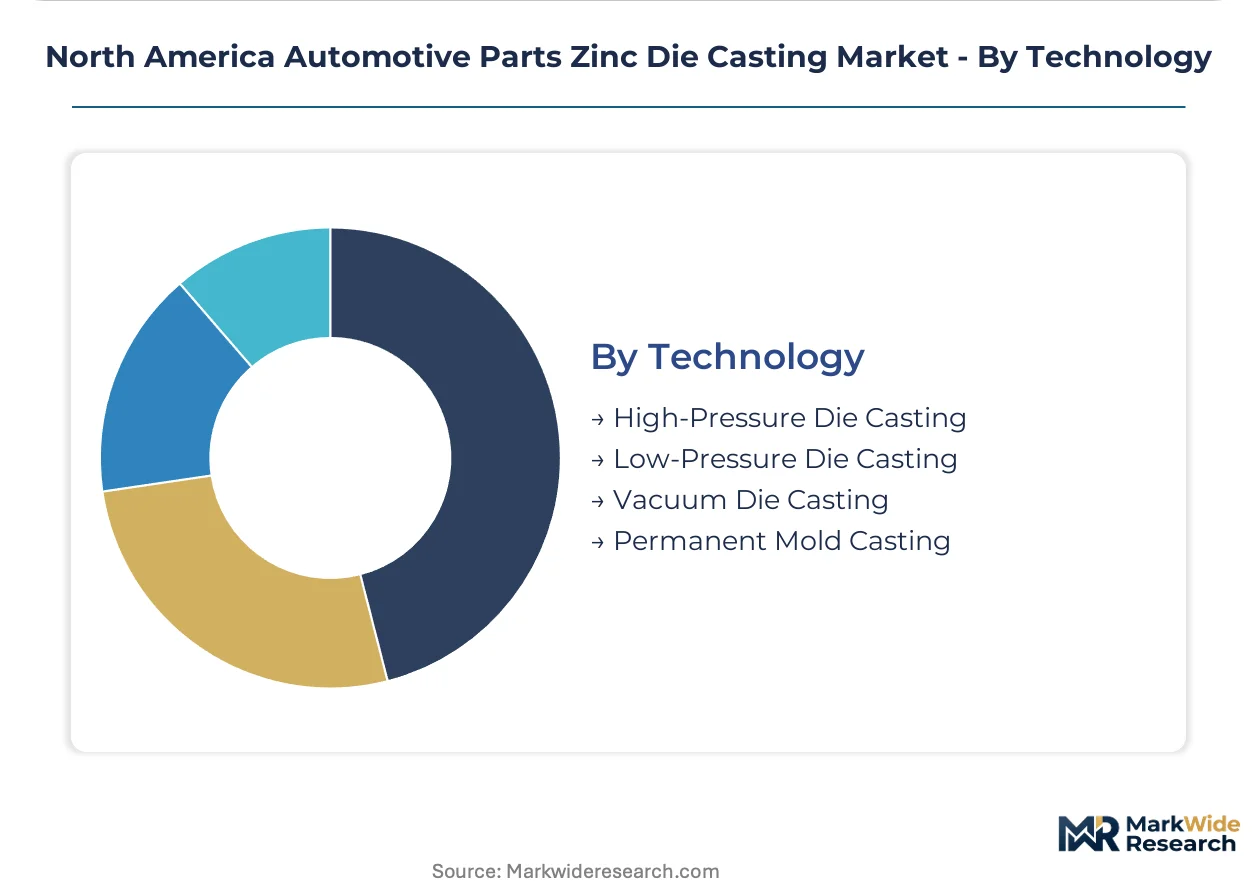
Technology:
Process selection trades capital efficiency against defect sensitivity, with safety-critical applications demanding premium technology investment.
- High-Pressure Die Casting:Injection pressures exceeding 1,000 bar enable thin-wall complexity below one millimeter. Dominates engine and transmission volume production across United States and Mexico manufacturing corridors.
- Low-Pressure Die Casting:Reduced turbulence minimizes porosity for hydraulic valve bodies and fuel system components. Slower cycle times limit deployment to medium-volume programs where defect costs exceed throughput penalties.
- Vacuum Die Casting:Evacuated mold cavities enable X-ray certification for brake calipers and steering knuckles requiring 100% radiographic inspection. SEMARNAT emissions compliance adds capital burden for Mexican installations.
- Permanent Mold Casting:Gravity-fed processes suit thick-section chassis brackets where dimensional precision requirements relax. Tooling longevity advantages attract low-volume truck and SUV platform suppliers in US Southeast.
High-pressure die casting retains volume leadership; vacuum die casting holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Die casting capacity clusters along the Great Lakes manufacturing belt and Mexico's central industrial corridor, with cross-border supply chains linking Detroit-area engineering centers to Guanajuato production plants. NHTSA safety certification requirements and EPA fuel economy mandates drive alloy selection and process investment across both nations. Regional specialization deepens as labor cost differentials narrow and logistics complexity reshapes procurement geography.
United States
OEM captive foundries and independent suppliers anchor production in Michigan and Ohio for powertrain-critical brake and steering hardware. EPA Corporate Average Fuel Economy standards compress design cycles for chassis lightweighting programs. The Detroit-Windsor corridor concentrates high-pressure die casting expertise for transmission cases serving Ford, GM, and Stellantis assembly plants.
Mexico
Maquiladora plants in Querétaro and Nuevo León capture volume contracts for automatic transmission housings and engine brackets. SEMARNAT foundry emissions rules require capital-intensive abatement systems that favor larger producers with multi-plant footprints. Northern Mexico manufacturing clusters sustain just-in-time delivery contracts with Detroit-based OEMs despite cross-border logistics friction.
Canada
Ontario-based suppliers serve as satellite operations for US Tier-1 integration, particularly for machined transmission components requiring precision finishing. Environment and Climate Change Canada regulations on industrial emissions align with EPA standards, simplifying cross-border compliance for integrated North American programs. The Windsor-Toronto corridor specializes in low-volume chassis castings for regional truck and SUV platforms.
North America Automotive Parts Zinc Die Casting Market Competitive Landscape
Multi-plant specialists and regional low-volume fabricators split the market between high-volume powertrain contracts and niche chassis programs. Consolidation pressure intensifies as OEM procurement departments reduce supplier rosters around vertically integrated partners. Three archetypes dominate: scale-driven multi-plant operators, process-specialized transmission case producers, and short-run regional chassis suppliers. Competitive moves center on geographic footprint expansion and vacuum-assisted technology licensing for safety-critical brake components.
Among North American die casting specialists, Dynacast International LLC and Pace Industries exemplify the scale-driven archetype through multi-plant operational footprints. Northwest Die Casting LLC occupies a position within the short-run regional tier, serving niche vehicle platforms bypassed by high-volume competitors. These three entities represent the strategic segmentation visible across the supplier base, with each archetype commanding distinct contract tenure and margin structures based on customer integration depth.
| Leading Market Players |
|---|
| Dynacast International LLC |
| Pace Industries |
| Northwest Die Casting LLC |
| Texas Die Casting |
| Gibbs Die Casting |
| Weiss-Aug |
| Alcoa Corporation |
| Martinrea International Inc |
| Carteret Die Casting Corporation |
| Others |
Value Network & Pricing Analysis
Cross-border tariff exposure on zinc alloy feedstock and finished die castings determines both pricing tier spreads and supply chain shape across the United States-Mexico automotive corridor. NHTSA safety certification requirements and EPA fuel economy mandates compress margins for non-certified suppliers while rewarding vertically integrated producers with multi-plant footprints.
Pricing Analysis
EPA Corporate Average Fuel Economy standards dictate the pricing tier structure across the North America automotive parts zinc die casting market. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-certified brake component suppliers from commodity chassis casters and maquiladora semi-finished goods producers. Price differentiation hinges on X-ray certification grade and geographic delivery cost to Detroit-area OEM assembly plants. Cost compression in economy-tier semi-finished goods is intensifying because SEMARNAT emissions compliance adds capital burden without corresponding quality premiums. Aftermarket distributors in Texas and California exhibit highest price sensitivity; captive OEM foundries in Michigan show least sensitivity due to design control priorities.
Supply Chain Analysis
Extended payment terms from Detroit Three OEMs and supply-chain finance facilities anchor working capital structures for Tier-1 die casting suppliers. Geographic supply concentration centers on the United States, Mexico, and Canada, with Michigan-Ohio engineering clusters feeding Guanajuato production plants. Raw material dependencies rest on zinc ingot from domestic smelters, hardened steel mold blanks from specialized Great Lakes toolmakers, and specialized release agents from chemical formulators. Single-source vulnerability concentrates in mold design expertise among aging specialists in the Detroit-Windsor corridor. Distribution runs through JIT rail and truck networks linking northern Mexico maquiladora plants to Michigan assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification sensor proliferation across hybrid powertrain architectures is accelerating demand for precision control module housings, creating a high-growth disruption window for suppliers with vacuum die casting capabilities and closed-loop zinc recovery certification.
For Market Incumbents: Pre-empt aluminum-magnesium substitution in transmission cases by investing in vacuum-assisted technology licensing for safety-critical brake and steering components. Secure captive mold design capacity in the Great Lakes region before tooling engineer scarcity constrains expansion timelines. Backward integration into closed-loop zinc recovery systems captures sustainability scorecard premiums from Ford and GM procurement divisions. For New Entrants and Emerging Players: Short-run chassis specialization for regional electric vehicle assemblers in Texas and Arizona represents the most penetrable entry point, bypassing high-volume competitors focused on Detroit Three contracts. Thermal management housing production for California and New York zero-emission vehicle mandates offers second white-space target with lower certification barriers than safety-critical brake components. Go-to-market angle should emphasize turnkey design-to-delivery modules consolidating fragmented vendor bases. For Investors and Strategic Acquirers: NHTSA Federal Motor Vehicle Safety Standards updates reshapes the acquisition landscape toward suppliers with in-house X-ray certification capabilities and multi-physics simulation integration. Long-term viability over the next decade favors vertically integrated mid-cap specialists with captive tooling engineering and Guanajuato production presence. Watch for EPA tailpipe regulation tightening as inflection signal redirecting zinc demand toward thermal management applications.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Die Casting Technology Licensing | Enables X-ray certification for NHTSA safety-critical brake calipers and steering knuckles. |
| Closed-Loop Zinc Recovery Investment | Captures OEM sustainability scorecard premiums from Ford and GM powertrain divisions. |
| Multi-Physics Simulation Integration | Compresses tooling qualification timelines before cutting hardened steel production molds. |
| Geographic Footprint Expansion | Establishes Guanajuato presence to serve tariff-advantaged Detroit Three transmission case contracts. |
| Tooling Engineer Talent Acquisition | Secures scarce mold design expertise concentrated among aging Great Lakes specialists. |
Research Methodology
Desk research of automotive production databases, SEC filings from listed suppliers, EPA regulatory dockets, and trade flow statistics preceded structured interviews with Tier-1 supplier procurement managers, OEM platform engineers, die casting plant managers, and aftermarket distribution heads. Primary fieldwork across Michigan-Ohio and Guanajuato-Querétaro manufacturing corridors combined with secondary validation from IHS Markit vehicle registration data and customs records. Bottom-up unit volume estimates triangulated against top-down market value assessments.
Forecast assumptions held fixed the current EPA Corporate Average Fuel Economy standard trajectory and NHTSA safety certification requirements while varying electrification penetration rates and hybrid architecture mixes across the projection horizon. Segmentation dimensions modeled include product type, end-user integration depth, form processing intensity, and technology sophistication. CAGRs derived from regression analysis of historical production volumes against regulatory milestone timing. Industry-specific inputs incorporated vehicle platform lifecycle data and zinc alloy price elasticity coefficients.
Practitioners should monitor EPA tailpipe regulation revisions, SEMARNAT emissions enforcement intensity, and aluminum-magnesium alloy substitution rates for early signals of forecast deviation. Macroeconomic contraction in automotive production, regulatory rollback of fuel economy standards, or breakthroughs in alternative lightweighting materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Automotive Coolant Aftermarket Market