
 Global Paper Bags Market | 2026-2036
Global Paper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paper Bags Market Foresight
Multi-source procurement for kraft pulp is expanding as converters diversify away from single-origin supply contracts. Smurfit Kappa leverages integrated forestry assets across Iberia and the Baltics to secure fiber cost stability. Mondi Group anchors its competitive position through proprietary extrusion coatings that marry moisture resistance with repulpability. Stora Enso competes by converting idled graphic paper machines into bag-grade kraft capacity in Finland and Poland.
Paper bags are container products fabricated from bleached or unbleached kraft fiber sheets, typically weighing 70–150 gsm, formed with glued or stitched seams and optional twisted paper or flat tape handles for load-bearing. They serve retail checkout, food carryout, and bulk commodity packaging where breathability, printability, and end-of-life biodegradability outweigh moisture-barrier limitations. Kraft paper commands the largest share of material-type volume owing to its tear strength and sulfur-free pulping compatibility with brown-bag aesthetics. Flat-bottom and block-bottom styles capture disproportionate value in premium grocery and specialty coffee segments where shelf-standing stability drives unit economics.
The EU Packaging and Packaging Waste Regulation, FDA food-contact substance notifications in the United States, and China's GB standards for paper packaging collectively tighten compositional thresholds for heavy metals and fluorinated treatments. REACH restrictions on certain ink chemistries and the EU Green Deal circularity mandates push converters toward water-based coatings and mineral-oil-free print systems. Stakeholders must monitor evolving extended-producer-responsibility fee structures that could shift cost advantages between virgin kraft and recycled-content grades faster than raw fiber spreads suggest.
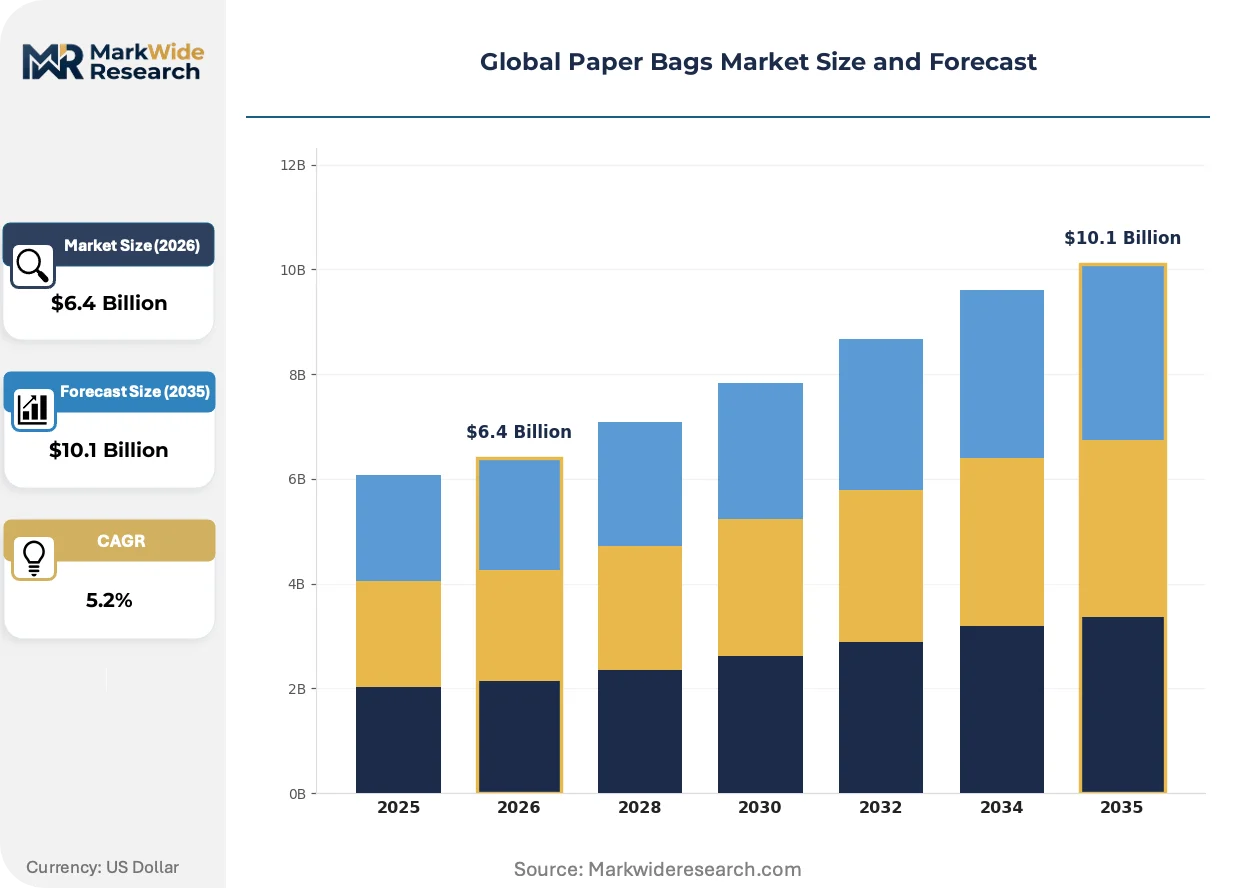
Market Dynamics
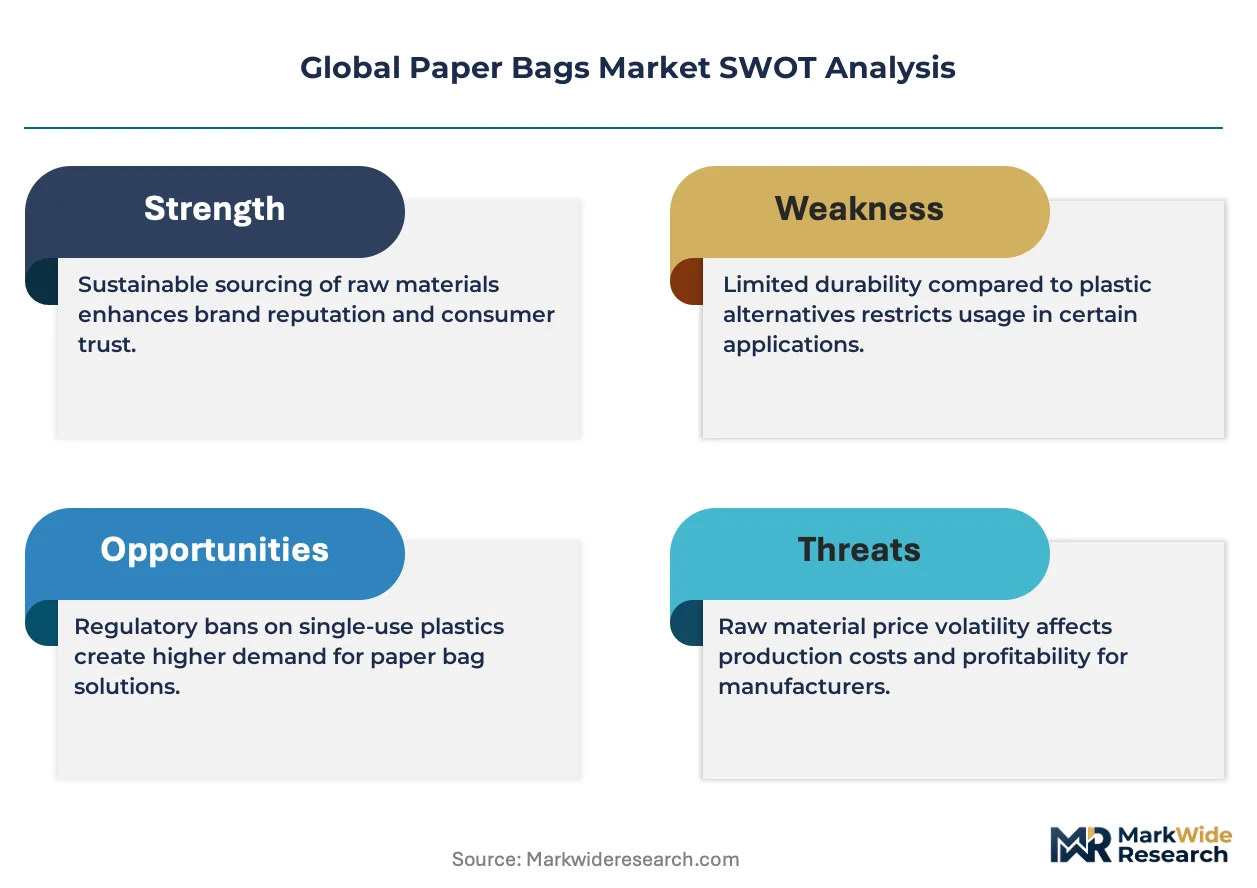
The EU Single-Use Plastics Directive compels brand owners to source fiber-based alternatives, creating a structural pull that concentrates converter investment in kraft capacity expansion and moisture-barrier coating innovation.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility fees for plastic packaging redirect foodservice procurement toward paper sack standards in Germany, France, and Italy.
- Quick-service restaurant chains:North American foodservice operators are replacing plastic carryout containers with flat-bottom paper bags for hot and cold food transport.
- Kraft pulp substitution:Sulfur-free pulping compatibility with brown-bag aesthetics drives material preference in grocery retail checkout applications.
Market Restraints
- Softwood pulp cost volatility:Kraft fiber prices fluctuate with Nordic and Baltic timber supply cycles, compressing converter margins during input spikes.
- Moisture-barrier limitations:Uncoated kraft fails in wet-food carryout, restricting penetration into soup and sauce packaging segments dominated by plastic.
- REACH ink chemistry restrictions:Mineral-oil-free print system mandates increase pre-press compliance costs for converters serving EU brand owners.
Strategic Opportunities
- India food retail modernization:Organized grocery expansion in Mumbai and Delhi creates first-mover advantage for block-bottom bag specifications in bulk commodity packaging.
- Water-based coating convergence:Barrier technologies combining repulpability with grease resistance unlock quick-service fried-food segments previously closed to fiber.
- China GB standards alignment:Heavy metal thresholds in paper packaging create certified-supplier preference for exporters serving dual domestic and EU markets.
Industry Challenges
- Extrusion coating line retrofitting:Converting idled graphic paper machines to bag-grade kraft requires capital-intensive drying section upgrades and skilled commissioning teams.
- FDA food-contact notification timelines:Substance safety clearances for novel barrier coatings extend go-to-market cycles by 18-24 months for US-bound product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paper Bags Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Kraft Paper, Virgin Paper, Recycled Paper, Cardboard, Bamboo Fiber End Use Sector: Foodservice, Personal Care, Electronics Packaging, Stationery Products, Apparel Packaging Bag Style: Flat Bottom, Handle, Gusseted, Block Bottom, Envelope Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Department Stores, Convenience Stores |
| Companies Covered | International Paper, Mondi Group, Smurfit Kappa, Novolex, DS Smith, Oji Holdings Corporation, Stora Enso, Nine Dragons Paper, Klabin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paper Bags Market Shifts & Advancements
Barrier coating chemistry and machine-direction fiber orientation are rewriting the technical boundaries between paper and plastic packaging, enabling fiber-based solutions to capture moisture-sensitive applications previously closed to kraft.
Proprietary extrusion coatings that marry moisture resistance with repulpability are rewriting the competitive map for hot-food carryout packaging. Quick-service chains in Germany and the Netherlands are piloting these specifications for fried and sauced items. The technology is rewriting margin structures by commanding 40-60% price premiums over standard kraft while maintaining end-of-life compostability credentials.
REACH restrictions on certain ink chemistries and the EU Green Deal circularity mandates are compressing the technology window for solvent-based print systems. Converters face accelerated capital redeployment toward water-based flexo and mineral-oil-free offset configurations. Specialty coffee and premium grocery segments in Scandinavia are responding fastest, specifying certified barrier papers ahead of southern EU markets.
Direct procurement relationships between grocery retailers and integrated forestry groups are displacing traditional converter-distributor networks in northern Europe. German and Polish supermarket chains now specify fiber origin and carbon intensity in bag tender requirements. This pattern is most visible in the flat-bottom sack segment, where shelf-standing stability requirements favor suppliers with captive pulp supply and in-house coating capability.
Global Paper Bags Market Segmentation
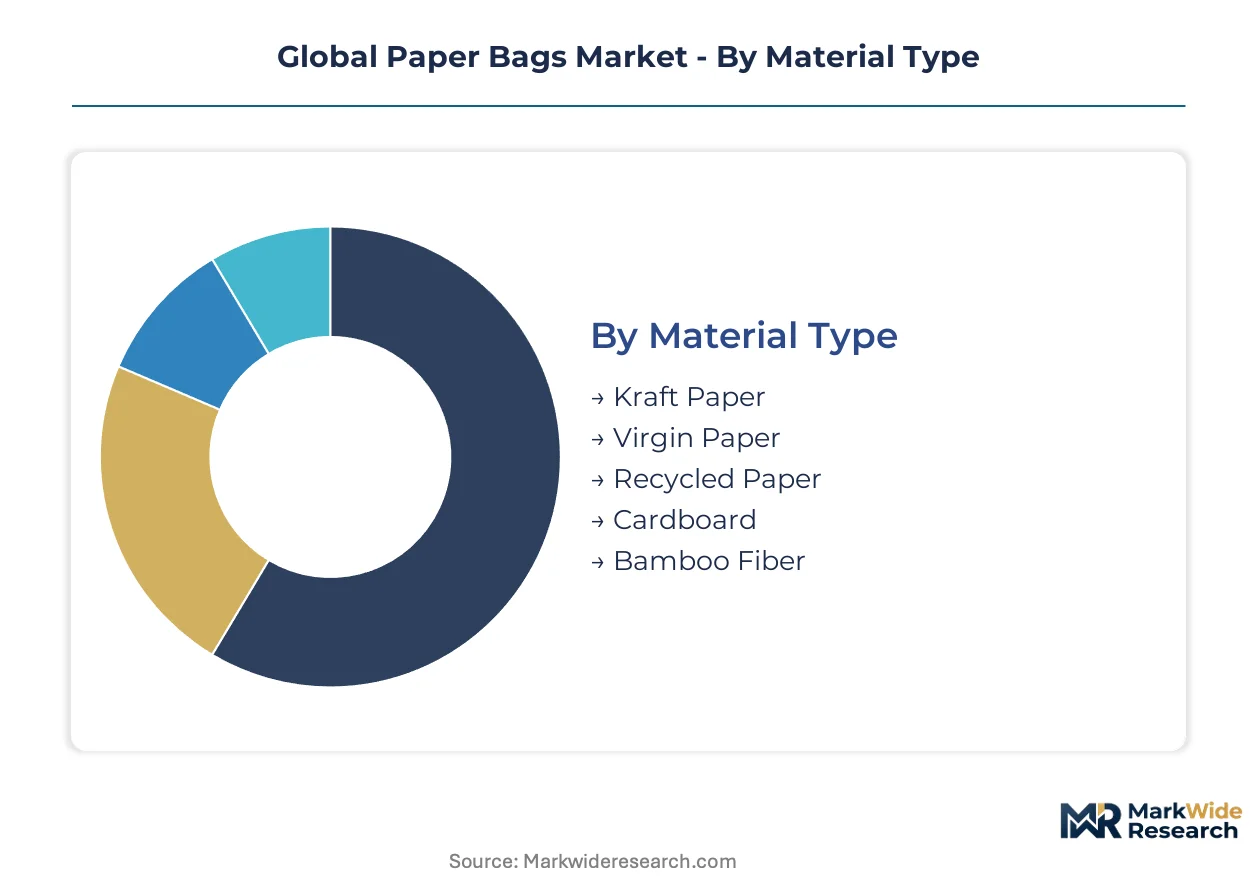
Paper bag specifications fragment across material grades, end-use performance demands, and retail channel requirements. Converters must match fiber sourcing strategies to the structural and barrier needs of each segment while navigating divergent regulatory thresholds across geographies.
Material Type:
Integrated forestry groups concentrate kraft pulp supply across Nordic and Baltic regions, locking in feedstock access for converters serving EU brand owners.
- Kraft Paper:Unbleached sulfate pulp delivers tear strength and sulfur-free compatibility with brown-bag aesthetics. German grocery retailers and quick-service restaurants specify this grade ahead of neighboring markets, driven by EU Single-Use Plastics Directive procurement mandates.
- Recycled Paper:Post-consumer fiber content reduces scope-three emissions for brand owners reporting under CSRD requirements. REACH restrictions on mineral-oil contamination in recovered streams complicate compliance for converters serving Scandinavian premium segments.
- Virgin Paper:Bleached hardwood pulp offers superior printability for high-end retail branding applications.
- Cardboard:Multi-ply construction supports heavier load-bearing requirements in electronics and bulk commodity packaging.
- Bamboo Fiber:Rapid-renewable feedstock appeals to sustainability-positioned personal care brands seeking differentiation in Asian markets.
Today's leader: Kraft Paper. Tomorrow's challenger: Recycled Paper.
End Use Sector:
Foodservice procurement patterns concentrate volume in quick-service chains replacing plastic carryout containers, while personal care and electronics segments command premium pricing for specialized barrier specifications.
- Foodservice:Flat-bottom and block-bottom styles dominate hot and cold food transport, with proprietary extrusion coatings unlocking fried-food segments previously closed to fiber. North American chains are piloting moisture-resistant specifications for sauced items.
- Personal Care:Bleached kraft and bamboo fiber grades serve cosmetic and skincare brands requiring premium tactile surfaces and certified compostability credentials for EU Green Deal alignment.
- Electronics Packaging:Anti-static coatings and structural rigidity specifications protect fragile components during e-commerce fulfillment.
- Stationery Products:Lightweight envelope-style constructions target gift and craft retail channels with minimal barrier requirements.
- Apparel Packaging:Twisted-handle designs support brand visibility in boutique and department store environments.
Foodservice commands current volume concentration. Personal Care is climbing the fastest on sustainability premiums.
Bag Style:
Structural engineering choices determine shelf-standing stability, load distribution, and automated packaging line compatibility across retail formats.
- Flat Bottom:Glued base construction enables vertical display in premium grocery and specialty coffee segments. German and Polish supermarket chains specify this style with captive pulp origin requirements in tender documentation.
- Block Bottom:Reinforced corner gussets maximize cubic volume efficiency for bulk commodity packaging in Indian organized retail expansion.
- Handle:Twisted paper or flat tape reinforcements support heavier loads in apparel and department store applications.
- Gusseted:Expandable side panels accommodate irregular product shapes in gift and promotional packaging.
- Envelope:Minimal material usage targets lightweight stationery and document protection segments.
Flat Bottom holds installed base dominance. Block Bottom shows steepest expansion trajectory in emerging market retail modernization.
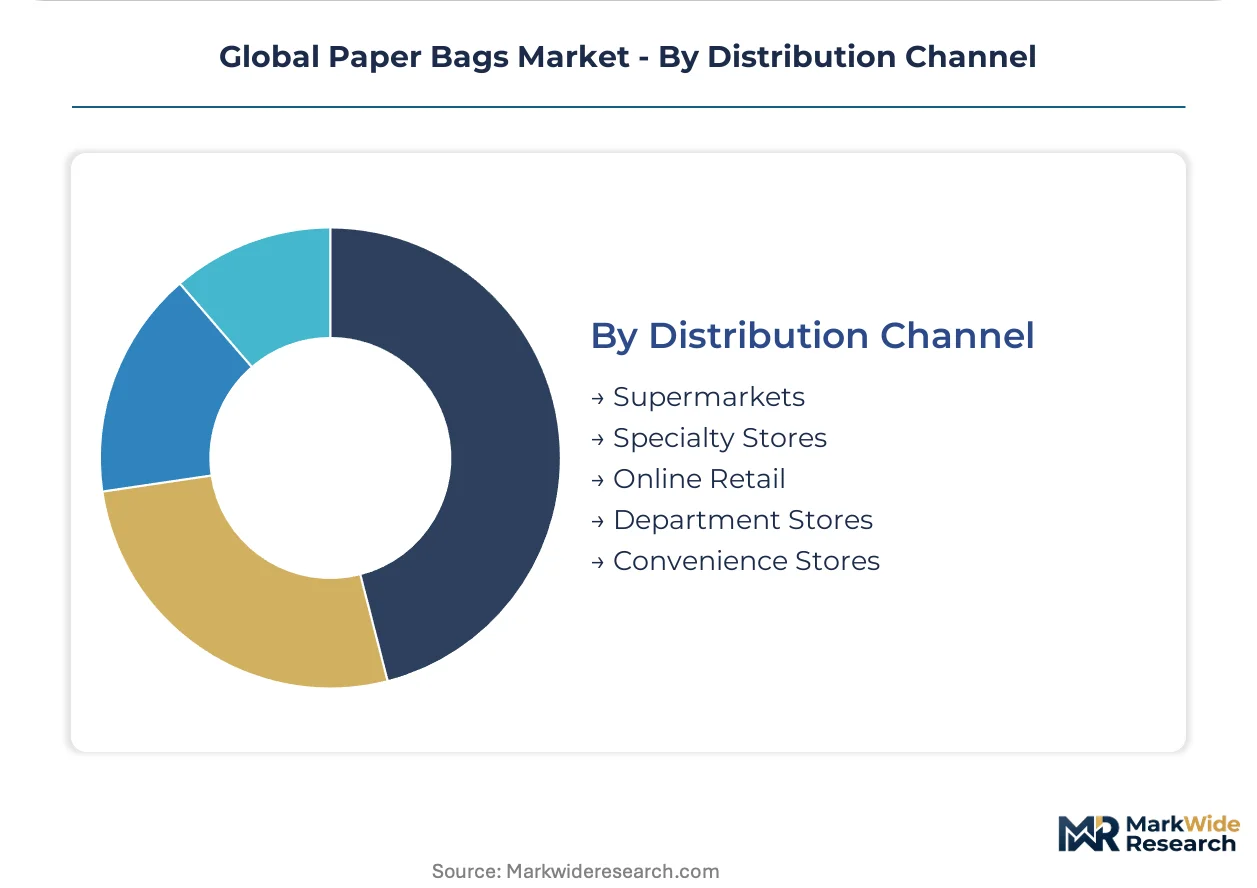
Distribution Channel:
Channel-specific packaging specifications reflect automation levels, inventory velocity, and private-label concentration differences across retail formats.
- Supermarkets:High-volume automated checkout drives standardization around block-bottom and flat-bottom kraft specifications with GS1 barcode compliance.
- Specialty Stores:Custom print runs and tactile finishes support brand differentiation in coffee, wine, and gourmet food segments.
- Online Retail:E-commerce fulfillment demands enhanced structural integrity for last-mile handling, favoring multi-ply cardboard and reinforced handle designs.
- Department Stores:Twisted-handle premium constructions align with apparel and cosmetics brand positioning requirements.
- Convenience Stores:Limited shelf space favors compact gusseted styles for grab-and-go foodservice items.
Supermarkets anchor procurement scale. Online Retail is gaining share fastest on fulfillment infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German grocery retailers and quick-service restaurants anchor procurement volume for flat-bottom kraft specifications. The EU Single-Use Plastics Directive redirects foodservice sourcing across multiple jurisdictions. REACH restrictions on ink chemistries and extended producer responsibility fees reshape converter investment patterns.
United States
North American foodservice chains pilot moisture-resistant flat-bottom bags for fried and sauced items. FDA food-contact substance notifications govern barrier coating approvals with 18-24 month clearance timelines. Chicago and Dallas metro areas concentrate quick-service procurement headquarters driving specification standardization.
Germany
Supermarket chains specify captive pulp origin and carbon intensity in bag tender documentation. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility fees redirecting procurement from plastic. Hamburg and Berlin-Brandenburg host integrated forestry groups converting idled graphic paper machines into bag-grade capacity.
China
GB standards for heavy metal thresholds in paper packaging create certified-supplier preference for dual-market exporters. NMPA and MIIT align domestic regulations with EU circularity mandates. Yangtze River Delta converters invest in water-based coating lines serving European brand owners.
India
Organized grocery expansion in Mumbai and Delhi generates first-mover demand for block-bottom bag specifications in bulk commodity packaging. BIS standards for food-contact paper tighten compositional thresholds. Maharashtra and Gujarat industrial corridors attract kraft capacity investment from regional converters.
Netherlands
Quick-service chains pilot proprietary extrusion coatings combining moisture resistance with repulpability for hot-food carryout. ECHA REACH restrictions accelerate solvent-to-water-based print system conversion. Randstad logistics hubs distribute coated kraft specifications across northern EU markets.
Global Paper Bags Market Competitive Landscape
Global majors compete with regional champions across integrated forestry assets and coating technology capabilities. The vendor base stratifies between captive pulp suppliers and independent converters sourcing fiber through multi-origin contracts. Three archetypes dominate: integrated forestry groups with backward timber control, specialty coating innovators, and scale-driven packaging conglomerates. Competitive moves concentrate on capacity conversion of idled paper machines and strategic partnerships for barrier chemistry licensing.
Within the integrated forestry tier, Smurfit Kappa and Stora Enso exemplify the captive pulp supply archetype securing feedstock cost stability. Mondi Group occupies a position representing proprietary extrusion coating specialists marrying moisture resistance with repulpability. Among Asia-Pacific fabricators, Nine Dragons Paper and Oji Holdings Corporation anchor regional production gravity serving domestic and export specifications.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| Smurfit Kappa |
| Novolex |
| DS Smith |
| Oji Holdings Corporation |
| Stora Enso |
| Nine Dragons Paper |
| Klabin |
| Others |
Supply & Pricing Matrix
The EU Green Deal circularity mandates gate qualified supply and premium-tier pricing access for converters serving German and Dutch quick-service chains. Brand owners sourcing certified compostable kraft specifications face 40-60% price premiums over standard grades, with barrier coating innovation separating compliant suppliers from commodity competitors.
Pricing Analysis
Softwood pulp cost pass-through dominates converter pricing models across Nordic and Baltic supply bases. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance and carbon intensity certification. Price differentiation hinges on proprietary extrusion coating capabilities and REACH-compliant mineral-oil-free print systems. Cost compression in standard kraft grades is intensifying because of multi-origin fiber sourcing competition, while quick-service chains in Germany prove least price-sensitive due to regulatory compliance deadlines.
Supply Chain Analysis
Direct-to-retailer channels handle hyperscale grocery procurement across German and Polish supermarket networks. Raw material flows draw from Sweden, Finland, and Poland as primary softwood pulp sources. Converter operations rest on kraft fiber, water-based coating chemistries, and twisted-handle tape inputs. Single-source vulnerability concentrates in proprietary barrier coating formulations licensed from limited technology holders. Distribution runs through Randstad logistics hubs serving northern EU markets with coated kraft specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in paper bags rests on water-based coating convergence unlocking fried-food segments at premium pricing tiers. Converters capturing barrier technology licensing advantages command sustainable margin premiums over commodity kraft suppliers.
For Market Incumbents: Anticipate REACH ink chemistry restrictions accelerating solvent-to-water-based print system conversion costs. Defend market position through captive pulp supply integration across Iberia and Baltic forestry assets. Deepen backward integration into kraft capacity conversion of idled graphic paper machines in Finland and Poland to secure feedstock cost stability against Nordic timber supply cycles. For New Entrants and Emerging Players: Launch via direct procurement relationships with organized grocery retailers in Mumbai and Delhi bypassing traditional converter-distributor networks. Target block-bottom bag specifications in Indian bulk commodity packaging where BIS standards create first-mover certification advantages. Pursue white-label coating partnerships with Yangtze River Delta fabricators serving dual China-EU market exporters. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with water-based coating line investments because EU extended producer responsibility fees redirect foodservice procurement toward compliant suppliers. Target mid-cap specialists with certified barrier paper capabilities and captive pulp supply in northern European markets. Monitor FDA food-contact notification timelines as inflection indicator for US market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Technology Licensing | Proprietary extrusion coatings from Mondi Group unlock moisture-resistant kraft specifications for quick-service fried-food segments. |
| Idled Machine Capacity Conversion | Stora Enso's graphic-to-bag-grade kraft conversion in Finland and Poland secures regional supply for EU Single-Use Plastics Directive compliance. |
| Water-Based Print System Transition | Mineral-oil-free flexo configurations satisfy REACH restrictions and EU Green Deal circularity mandates for Scandinavian premium segments. |
| Direct Retailer Procurement Relationships | German supermarket chains now specify fiber origin and carbon intensity in flat-bottom sack tender documentation. |
| Dual-Market Certification Alignment | China GB standards for heavy metal thresholds create certified-supplier preference for exporters serving domestic and EU markets simultaneously. |
Research Methodology
Direct dialogue with kraft pulp procurement managers, converter operations directors, quick-service restaurant packaging specification leads, and EU regulatory compliance officers grounded this analysis. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of integrated forestry groups, ECHA REACH substance restriction updates, and FDA food-contact substance notification databases. Bottom-up volume modeling across material grades and bag styles triangulated against top-down market sizing from pulp production statistics and retail channel procurement patterns.
Bottom-up segmentation modeling tracked kraft paper, recycled paper, and barrier-coated specifications across foodservice, personal care, and grocery retail end uses. The analytical framework projected demand evolution across flat-bottom, block-bottom, and handle-reinforced bag styles throughout the forecast period. CAGRs derived from installed capacity conversion timelines, regulatory compliance deadline clustering, and quick-service chain rollout schedules. Industry-specific inputs incorporated EU Packaging and Packaging Waste Regulation fee structures and Nordic timber supply cycle volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pulp price spike scenarios and FDA coating approval timeline extensions. Projections reflect assumptions on water-based coating technology adoption curves and extended producer responsibility fee implementation schedules across EU member states. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
MAP Trays Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Mottled Test Liner Market