
 Cooler Bags Market | 2026-2036
Cooler Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cooler Bags Market Outlook
Asset-light direct-to-consumer leasing is fragmenting capital requirements across the cooler bags competitive set. YETI Holdings leverages premium brand equity to sustain wholesale-plus-DTC hybrid margins. RTIC Outdoors anchors its position through manufacturing scale and aggressive value-tier pricing. Igloo Products dominates mass retail channels with deep seasonal replenishment cycles.
Cooler bags are thermally insulated portable containers engineered with closed-cell foam cores, radiant barrier linings, and welded seam construction to maintain sub-ambient temperatures for perishable goods during transit. Soft-sided variants using laminated EVA shells and TPU-coated nylon face fabrics now lead volume shipments due to packability and weight advantages over rotational-molded hard shells. Backpack coolers represent the fastest-growing product type as day-hiking and urban commuting applications expand. Polyester remains the dominant material segment by tonnage, though nylon variants command margin premiums in tactical and marine sub-segments.
The EPA regulates volatile organic compound emissions from adhesive and coating processes in domestic cooler bag manufacturing, while the EU REACH framework restricts phthalate plasticizers in PVC-based liner films. California's Proposition 65 labeling requirements shape product compliance costs for brands distributing in the United States. Stakeholders must monitor evolving state-level extended producer responsibility proposals and insulation material bans to anticipate reformulation timelines and geographic sourcing shifts.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale reformulation of insulation materials across the cooler bags supply base, compressing margins for foam-dependent converters while creating first-mover advantages for aerogel and vacuum-panel adopters.
Growth Catalysts
- Alpine Tourism Concentration:Germany's festival culture and mountain recreation infrastructure sustain premium soft-sided cooler consumption, with day-hiking applications driving backpack cooler variants.
- National Park Procurement:US outdoor recreation programs are expanding portable cold-chain equipment purchases for backcountry ranger stations and visitor services.
- F-Gas Phase-Down:The EU regulatory framework is accelerating converter migration toward vacuum-insulated panels and aerogel liners ahead of hydrofluorocarbon bans.
Market Restraints
- Petrochemical Input Volatility:EVA shell laminates and TPU-coated nylon face fabrics expose manufacturers to ethylene and propylene price swings.
- Adhesive Emission Controls:EPA volatile organic compound regulations constrain domestic manufacturing throughput and capital deployment.
- Rotational-Molded Substitution:Hard-shell coolers retain performance advantages in multi-day expedition contexts, limiting soft-sided penetration in professional guiding segments.
Strategic Opportunities
- Urban Commuting Expansion:Day-hiking and bicycle-commuter applications in German and Austrian metropolitan corridors are driving backpack cooler format adoption.
- Extended Producer Responsibility:California's evolving state-level proposals create compliance-service revenue streams for brands with reformulation capabilities.
- Marine Sub-Segment Premiumization:Nylon variants command margin premiums in tactical and saltwater fishing applications where abrasion resistance determines replacement cycles.
Industry Challenges
- Welded Seam Technician Scarcity:RF welding and hot-air sealing expertise concentrates in Asian contract manufacturers, constraining nearshoring ambitions.
- REACH Compliance Timeline Compression:ECHA phthalate restrictions in PVC liner films demand accelerated supplier audits and material qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooler Bags Market |
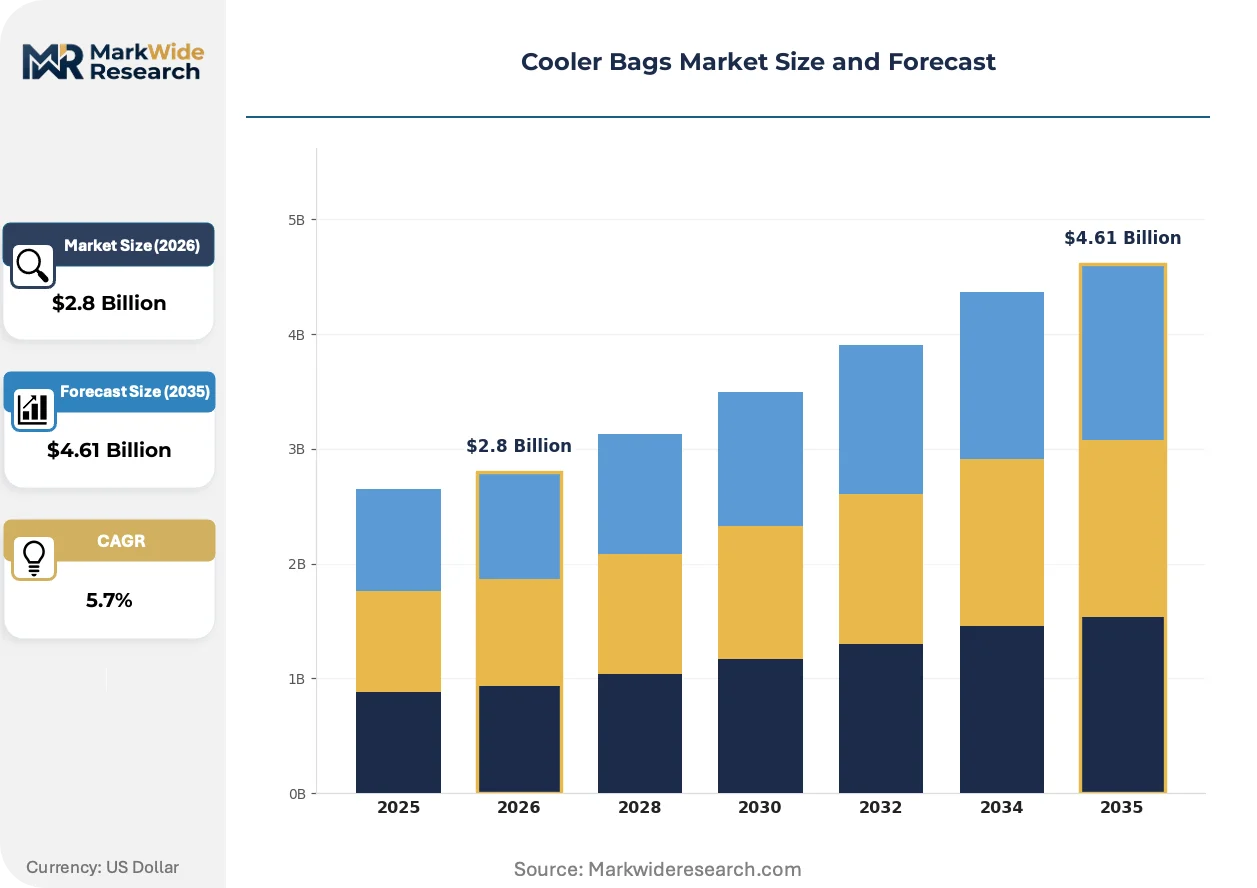
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bags, Soft-sided Coolers, Hard-sided Coolers, Backpack Coolers Material: Polyester, Nylon, PVC, EVA End User: Outdoor Enthusiasts, Sports Teams, Picnic Goers, Beach Visitors Size: Small, Medium, Large, Extra Large |
| Companies Covered | Engel Coolers, RTIC Outdoors, YETI Holdings, Arctic Zone, Stanley, Igloo Products, Thermos, AO Coolers, Coleman Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooler Bags Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to reshape thermal performance benchmarks and manufacturing footprints across the cooler bags category.
Vacuum-insulated panel technology is migrating from medical cold-chain applications into consumer cooler bags, enabling sub-ambient temperature maintenance with sub-50% foam thickness. Alpine equipment manufacturers in Bavaria and Tyrol are piloting VIP-lined day packs for glacier trekking. This migration from medical-grade to recreational deployment is compressing the performance gap between soft-sided and hard-shell thermal retention.
The EU F-Gas Regulation's hydrofluorocarbon phase-down schedule is mandating polyurethane foam reformulation across converter networks. German insulation specialists are retooling extrusion lines for pentane-blown alternatives ahead of 2027 quota reductions. Soft-sided manufacturers sourcing from EU-based foam suppliers face 18-24 month material qualification cycles.
Asset-light direct-to-consumer leasing is fragmenting capital requirements across the competitive set. Festival operators in Germany and Austria are contracting seasonal cooler inventory rather than purchasing depreciating assets. This rental-channel expansion is most visible in Munich's Oktoberfest supply chain and Salzburg's summer music festival logistics.
Cooler Bags Market Segmentation
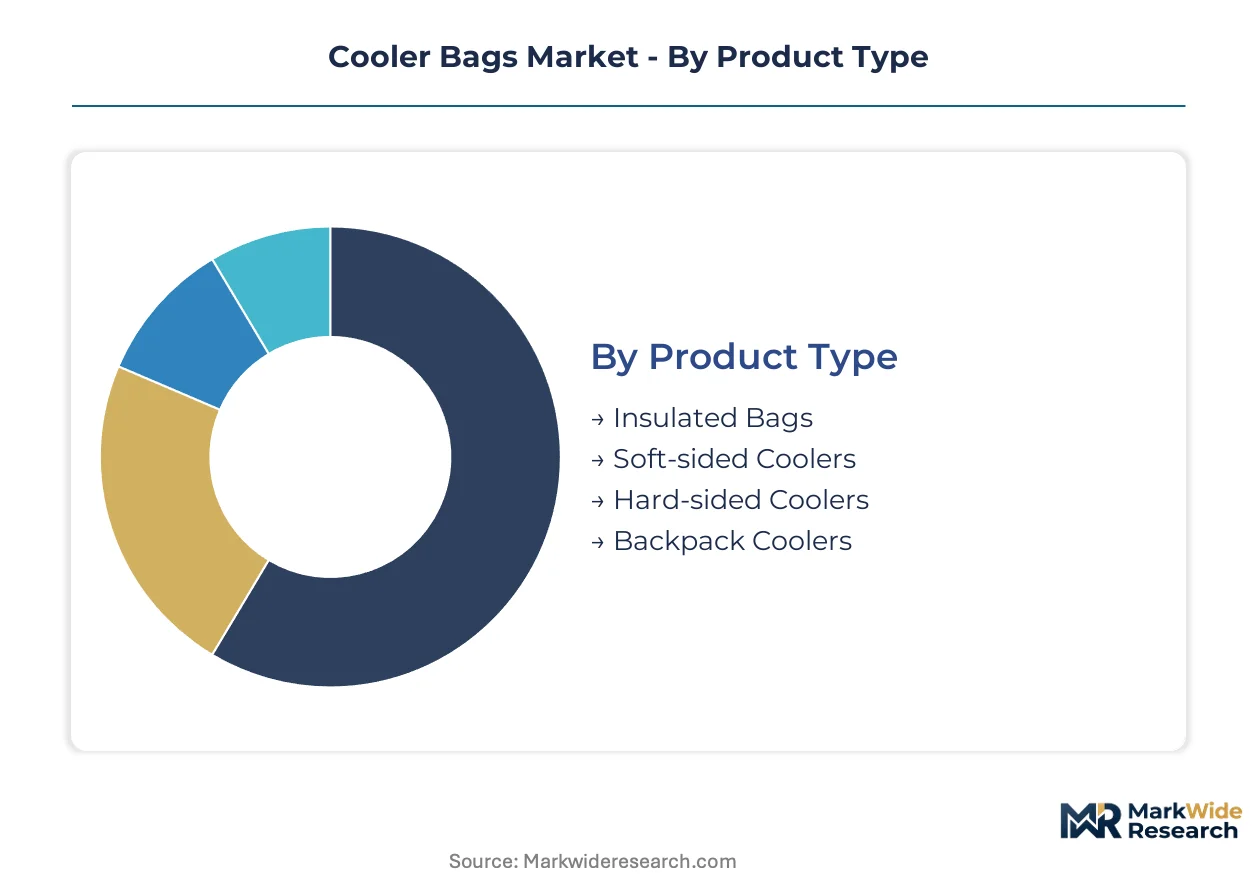
Segmentation in cooler bags determines thermal performance specifications, distribution channel selection, and margin architecture. Product format and material composition dictate manufacturing investment intensity, while end-use concentration shapes seasonal demand patterns and replacement cycle velocity.
Product Type:
After-sales-service intensity varies sharply across product formats, with hard-sided coolers requiring warranty fulfillment infrastructure and soft-sided variants demanding minimal post-purchase support.
- Soft-sided Coolers:Laminated EVA shells and TPU-coated nylon face fabrics deliver packability and weight advantages over rotational-molded alternatives. Demand concentrates in Germany's alpine tourism corridors and festival logistics, where day-hiking applications prioritize portability over multi-day ice retention.
- Backpack Coolers:Thermally insulated daypacks with welded seam construction target bicycle commuters and urban hikers in Austrian and German metropolitan corridors. This format climbs the fastest as dual-use work-leisure mobility patterns expand in Central European cities.
- Insulated Bags:Basic thermal liners with minimal structural rigidity serve single-use picnic and grocery transport applications.
- Hard-sided Coolers:Rotational-molded polyethylene shells retain performance advantages in multi-day expedition contexts despite weight penalties.
Soft-sided coolers hold the largest share; momentum sits with backpack coolers.
Material:
Material selection drives cost tier positioning and regulatory compliance burden, with synthetic polymers facing distinct chemistry constraints across EU and US jurisdictions.
- Polyester:Dominates tonnage shipments through cost efficiency and dye-sub printing compatibility for branded merchandise. Mass retail channels in the United States rely on polyester variants for deep seasonal replenishment cycles.
- Nylon:Commanding margin premiums in tactical and saltwater fishing sub-segments where abrasion resistance determines replacement cycles. Bavarian alpine equipment manufacturers specify nylon face fabrics for glacier trekking packs.
- EVA:Closed-cell foam cores laminated to textile substrates enable sub-ambient temperature maintenance in soft-sided formats.
- PVC:Facing REACH-mandated phthalate restrictions that compress formulation flexibility and accelerate supplier audit cycles.
Polyester holds the largest share; momentum sits with nylon.
End User:
Customer type determines purchase frequency, price elasticity, and channel preference, with institutional buyers exhibiting divergent procurement patterns from consumer segments.
- Outdoor Enthusiasts:Premium thermal performance requirements and equipment replacement cycles align with specialty retail and direct-to-consumer channels. US national park backcountry ranger stations are expanding portable cold-chain equipment procurement.
- Sports Teams:Volume purchasers with seasonal concentration and logo customization requirements that favor contract manufacturing relationships.
- Picnic Goers:Price-sensitive occasional users driving mass retail volume through impulse purchase placement.
- Beach Visitors:Salt exposure and sand abrasion create demand for marine-grade material specifications in coastal markets.
Outdoor enthusiasts hold the largest share; momentum sits with sports teams.
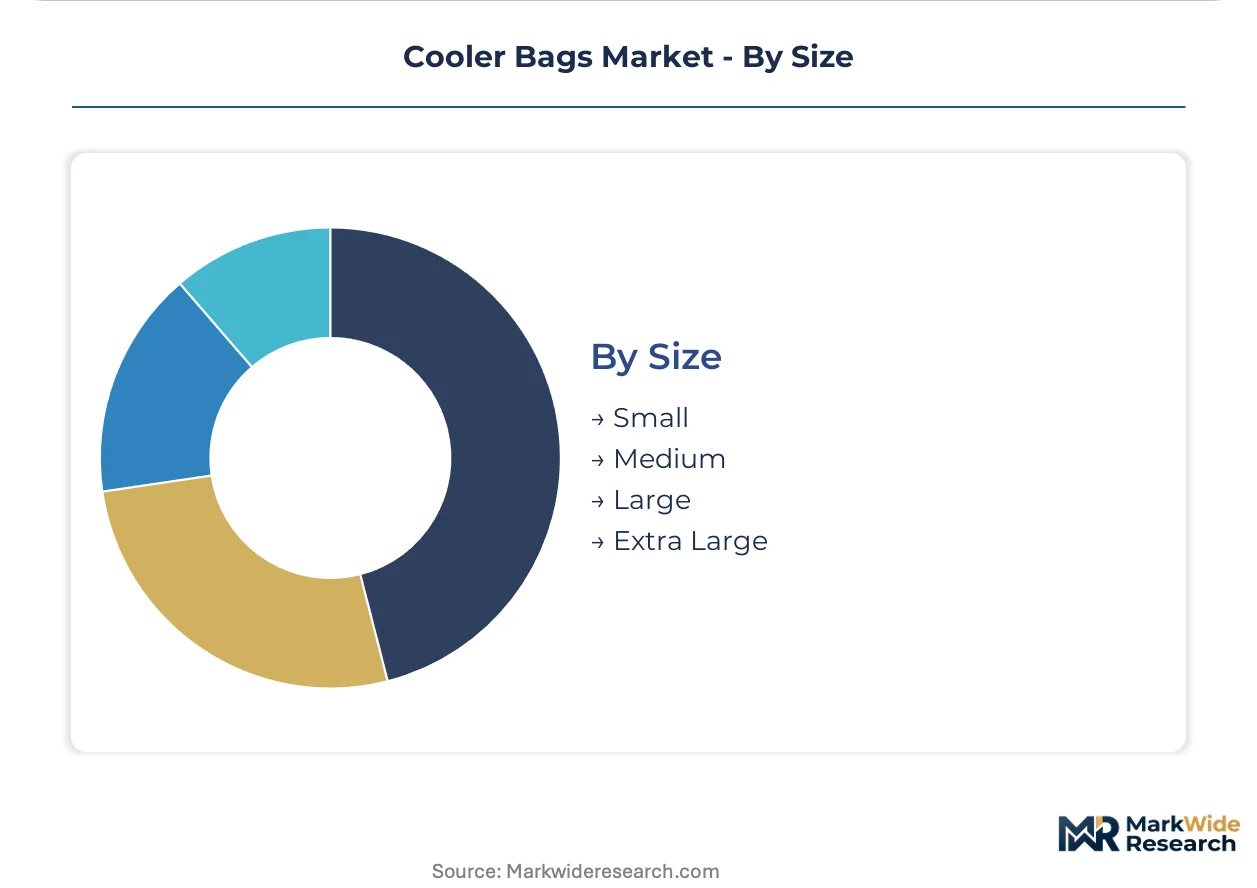
Size:
Capacity segmentation maps directly to use-case duration and mobility constraints, with dimensional limits determining airline carry-on eligibility and bicycle pannier compatibility.
- Small:Sub-12 liter capacities targeting single-meal transport and personal beverage storage in urban commuting contexts.
- Medium:Day-trip configurations balancing thermal mass against packability for hiking and festival applications.
- Large:Multi-day group provisioning formats favored by car-camping and tailgate segments.
- Extra Large:Expedition-scale capacities with wheeled transport features for professional guiding and event catering logistics.
Medium holds the largest share; momentum sits with small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in cooler bags track closely to outdoor recreation infrastructure investment and regulatory chemistry mandates. Countries with strong alpine tourism or extended coastline access show net import dependence for premium soft-sided variants, while rotational-molded hard-shell production concentrates near petrochemical feedstock sources.
United States
National Park Service procurement of portable cold-chain equipment for backcountry ranger stations drives institutional demand. EPA volatile organic compound regulations constrain domestic adhesive and coating throughput, pushing converters toward compliance capital expenditure. Austin and Houston anchor soft-sided manufacturing clusters serving festival logistics and tailgate culture.
Germany
Alpine tourism in Bavaria and festival culture sustain premium soft-sided cooler consumption, with day-hiking applications prioritizing packability. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs, forcing polyurethane foam reformulation across converter networks. Munich and Salzburg supply chains pilot vacuum-insulated panel technology for glacier trekking packs.
China
Contract manufacturing concentration for RF welding and hot-air sealing expertise supports global soft-sided output. MIIT industrial standards and dual carbon goals pressure foam suppliers toward pentane-blown alternatives. Guangdong and Zhejiang provinces host laminated EVA shell production for export markets.
Japan
Urban commuting and bicycle mobility patterns in Tokyo and Osaka metropolitan corridors expand backpack cooler adoption. METI energy efficiency guidelines shape insulation material selection for domestic distribution. Nagoya industrial clusters refine welded seam construction for marine-grade nylon variants.
Australia
Saltwater fishing and coastal recreation sustain demand for abrasion-resistant marine sub-segment specifications. TGA-equivalent product safety frameworks govern food-contact liner materials. Sydney and Melbourne distribution networks serve expedition-scale hard-shell requirements for professional guiding segments.
Cooler Bags Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: premium brand equity players, manufacturing scale specialists, and mass retail channel dominators. Competitive positioning depends on thermal performance credentials, seasonal replenishment cycle depth, and direct-to-consumer leasing capability. M&A activity targets foam reformulation expertise and vacuum-insulated panel technology licensing. Geographic expansion concentrates on German alpine corridors and US national park procurement channels.
Within the premium brand equity tier, YETI Holdings and RTIC Outdoors exemplify divergent margin architectures. YETI Holdings leverages wholesale-plus-DTC hybrid structures to sustain pricing power. RTIC Outdoors anchors its position through value-tier pricing and manufacturing scale. Igloo Products occupies a position in mass retail channel dominance with deep seasonal replenishment relationships.
| Leading Market Players |
|---|
| Engel Coolers |
| RTIC Outdoors |
| YETI Holdings |
| Arctic Zone |
| Stanley |
| Igloo Products |
| Thermos |
| AO Coolers |
| Coleman Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Guangdong province's RF welding contract manufacturing is compressing converter margins while fragmenting pricing power across German alpine equipment brands and US mass retail private labels. Utilization rates below 70% at Zhejiang laminated EVA shell producers are forcing price concessions downstream, even as EU F-Gas compliance costs inflate landed costs for vacuum-insulated panel adopters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the cooler bags market. Price differentiation rests on thermal performance certification grade and brand premium, with YETI Holdings commanding wholesale-plus-DTC hybrid premiums against RTIC Outdoors value-tier positioning. Cost compression in the standard tier is intensifying because of ethylene price volatility and REACH-mandated PVC liner reformulation. Mass retail channels exhibit highest price sensitivity, while alpine tourism procurement in Bavaria shows lowest elasticity for glacier-grade specifications.
Supply Chain Analysis
Ethylene and propylene feedstock volatility in the US Gulf Coast and Middle Eastern petrochemical complexes is transmitting through EVA shell laminate costs. Manufacturing concentrates in China, Vietnam, and Germany, with Guangdong province hosting RF welding expertise and Bavaria anchoring vacuum-insulated panel pilot production. Single-source vulnerability concentrates in Asian hot-air sealing technician pools. Distribution runs through wholesale-plus-DTC hybrid channels for premium brands and deep seasonal replenishment cycles for mass retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cooler bags market reads as a service-attach opportunity where direct-to-consumer leasing and seasonal festival rental channels are expanding faster than hardware unit sales. Recurring revenue from asset-light inventory management is displacing traditional depreciation models in German and Austrian metropolitan corridors.
For Market Incumbents: Build regulatory compliance moats around EU F-Gas foam reformulation expertise and California extended producer responsibility service capabilities. Incumbents should deepen backward integration into pentane-blown polyurethane extrusion ahead of 2027 quota reductions. Aerogel liner qualification cycles and vacuum-insulated panel licensing agreements defend against rotational-molded hard-shell substitution in expedition segments. For New Entrants and Emerging Players: Build out urban commuting white-space in German and Austrian bicycle mobility corridors where backpack cooler penetration remains below alpine tourism saturation. Target saltwater fishing marine sub-segments in Australia and US coastal markets where nylon abrasion resistance commands replacement-cycle premiums. Direct-to-consumer leasing partnerships with festival operators offer lowest customer acquisition cost versus wholesale channel buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light direct-to-consumer leasing sub-segments while rising for EU-based foam reformulation specialists. Long-term viability over the next decade favors converters with vacuum-insulated panel technology licensing and seasonal rental platform infrastructure. Acquisition target archetypes include German alpine equipment manufacturers with VIP pilot production and US national park procurement relationships. The signal to watch is EU F-Gas quota auction pricing as inflection indicator for foam-dependent converter margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Leasing Platform Launch | Festival operators in Munich and Salzburg contract seasonal inventory rather than purchasing depreciating assets. |
| Vacuum-Insulated Panel Technology Licensing | Bavarian alpine equipment manufacturers pilot VIP-lined day packs for glacier trekking applications. |
| EU F-Gas Compliance Service Expansion | German converters retool extrusion lines for pentane-blown alternatives ahead of hydrofluorocarbon quota reductions. |
| Marine-Grade Nylon Specification Development | Saltwater fishing applications in Australia and US coastal markets prioritize abrasion resistance over cost efficiency. |
| National Park Procurement Channel Penetration | US outdoor recreation programs expand portable cold-chain equipment purchases for backcountry ranger stations. |
Study Parameters
A standing panel of RF welding technicians, foam extrusion plant managers, alpine equipment brand procurement directors, and festival logistics operators provided ongoing calibration across primary interview cycles. Secondary validation drew from EU ECHA substance restriction databases, US EPA volatile organic compound emission filings, customs trade data for EVA shell laminates, and SEC 10-K disclosures from listed outdoor recreation companies. Bottom-up unit economics triangulated against top-down category spend estimates across German alpine tourism and US national park procurement channels.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product format, material composition, end-use concentration, and regional regulatory cluster. CAGRs derived from modeled replacement cycle velocity and seasonal demand pattern analysis. Industry-specific forecast inputs included EU F-Gas phase-down compliance timelines and pentane-blown foam qualification cycle durations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vacuum-insulated panel technology licensors or rotational-molded hard-shell premium repositioning would shift outcomes. Forecasts assume stable petrochemical feedstock availability and no acceleration of state-level extended producer responsibility mandates beyond California's current trajectory. Cross-checking against IEA plastics demand benchmarks and outdoor recreation participation surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Waterproof Bags Market
Bags and Containers
Compression Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Counter Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Breather Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market