
 Bag Clips Market | 2026-2036
Bag Clips Market Size, Share, and Industry Trends Forecast 2026-2036
Bag Clips Market Outlook
Premium-grade closure specifications is collapsing the gap between commodity bag clips and engineered fastening systems for perishable goods. ITW leverages its polymer science portfolio to supply food-contact-compliant clips through captive resin compounding operations. CCL Industries anchors North American label-and-closure bundling contracts with retail grocery chains. Kwik Lok Corporation dominates bread-bag twist-tie substitution with high-speed applicator-compatible designs.
Bag clips are mechanical fastening devices engineered to create repeatable seals on flexible packaging, typically specifying closure force retention above 2.5 N and food-grade substrate compliance for direct food contact applications. Plastic clips in polyethylene formulations lead volume due to injection molding scalability, while stainless steel variants command margin pools in industrial and commercial food service channels where thermal sterilization cycles demand metal durability. Magnetic clips represent the fastest-growing material segment as silicone-bonded neodymium designs penetrate premium household organization and specialty retail display applications. Small and medium sizes sustain the majority of unit demand, though extra large formats are concentrating in industrial bulk packaging where load retention requirements exceed 10 kg.
FDA food-contact substance notifications and EU REACH chemical compliance frameworks govern substrate selection for clips entering food packaging streams, with EFSA migration limit testing increasingly shaping European supplier qualification timelines. The EU Packaging and Packaging Waste Regulation is forcing redesign investments toward mono-material polyethylene clips that simplify mechanical recycling sortation. Stakeholders must monitor evolving extended producer responsibility fee structures and decide whether to absorb compliance costs or pass them through channel pricing before substrate lock-in commitments harden across major retail supply agreements.
Market Dynamics
EU REACH chemical compliance frameworks are forcing substrate redesigns across bag clip supply chains as migration limit testing tightens qualification timelines for polyethylene formulations entering food-contact applications.
Growth Catalysts
- Prepared meal packaging specifications:Food service operators now mandate resealable closures for ready-to-eat containers, pulling engineered clip designs into commercial kitchen procurement cycles.
- EU Packaging and Packaging Waste Regulation:The mandate for mono-material packaging is accelerating mechanical recycling compatibility investments among clip manufacturers supplying European retail private-label programs.
- Neodymium-bonded silicone magnetic designs:Specialty retail display applications are absorbing premium-priced magnetic clips for household organization systems, creating margin expansion outside commodity food packaging channels.
Market Restraints
- Resin price volatility:Polyethylene feedstock fluctuations compress margins on injection-molded clips where pricing is locked into annual retail supply agreements.
- Supplier concentration in Asian resin compounding:Captive polymer science capabilities remain limited to a handful of integrated manufacturers, creating qualification bottlenecks for food-contact-compliant formulations.
- Stainless steel thermal sterilization durability:Metal clips command persistent cost premiums that exclude them from high-volume bread and produce bag applications where plastic dominates unit economics.
Strategic Opportunities
- Extended producer responsibility fee structures:Early movers designing easily sortable mono-material clips can capture preferential placement in retailer sustainability scorecards before substrate lock-in hardens.
- High-speed applicator compatibility:Automated bakery packaging lines in Germany and France present white space for twist-tie substitution at throughput rates exceeding 300 units per minute.
- Smart kitchen integration:RFID-enabled clips for inventory tracking are converging with connected refrigerator systems, opening premium household segments in Japan and South Korea.
Industry Challenges
- EFSA migration limit testing timelines:European supplier qualification cycles now extend 18-24 months, delaying new substrate introductions and freezing formulation innovation pipelines.
- Food-contact substance notification complexity:FDA compliance documentation for novel polymer blends requires specialized regulatory affairs capacity that mid-tier manufacturers struggle to staff.
- Mechanical recycling sortation integration:Clip designs must now coordinate with municipal waste stream infrastructure that varies dramatically across North American and European processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag Clips Market |
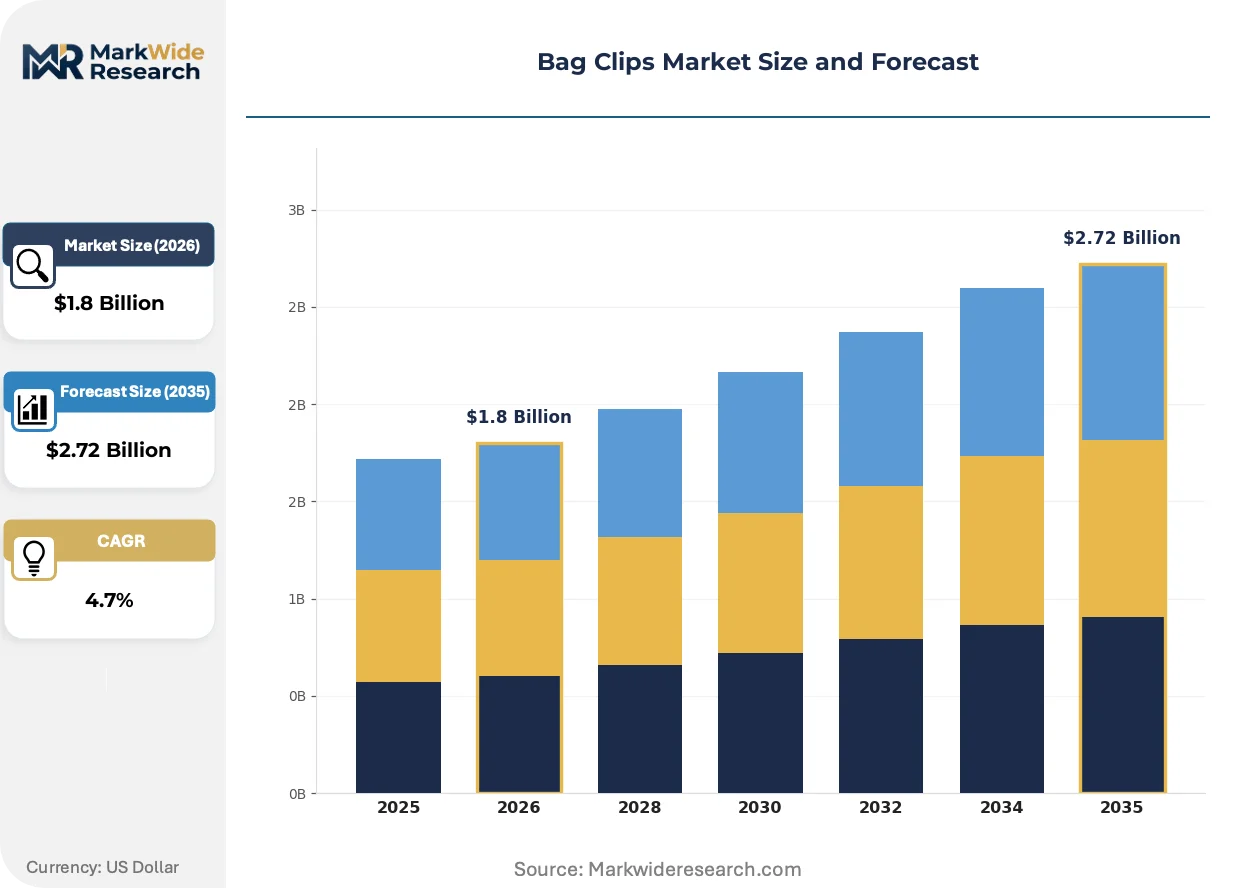
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Clips, Metal Clips, Wooden Clips, Magnetic Clips Size: Small, Medium, Large, Extra Large Material: Polyethylene, Stainless Steel, Bamboo, Silicone End User: Household, Retail, Food Service, Industrial |
| Companies Covered | ITW, CCL Industries, Kwik Lok Corporation, DuraClip, Berry Global, Bedford Industries, Plas-Ties, ClipsShop, Schutte Bagclosures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag Clips Market Strategic Shifts
Material science advances and regulatory redesign mandates are splitting the bag clip market into divergent specification tracks, with food-contact compliance and sustainability sortability becoming non-negotiable design constraints.
Mono-material polyethylene clip engineering is bifurcating the supplier base between legacy multi-layer designs and simplified single-substrate constructions. German and French retail chains are mandating the latter for private-label bread and produce packaging. This shift is compressing margins for compounders lacking captive resin reformulation capabilities while rewarding integrated polymer science operations.
EFSA migration limit testing protocols are extending European supplier qualification timelines from 12 to 24 months. The industrial consequence is a freeze on novel substrate introductions as manufacturers await regulatory clearance. Small and medium-sized clip producers serving pan-European grocery distributors face the most severe pipeline constraints, with several delaying planned launches into 2027.
Commercial kitchen procurement is consolidating around bundled label-and-closure contracts that unbundle after-sales technical support. North American food service operators now specify clip performance guarantees tied to closure force retention metrics above 2.5 N. This certification-driven preference shift is most visible in US regional restaurant chains upgrading from twist-tie to resealable clip systems for prepared meal containers.
Bag Clips Market Segmentation
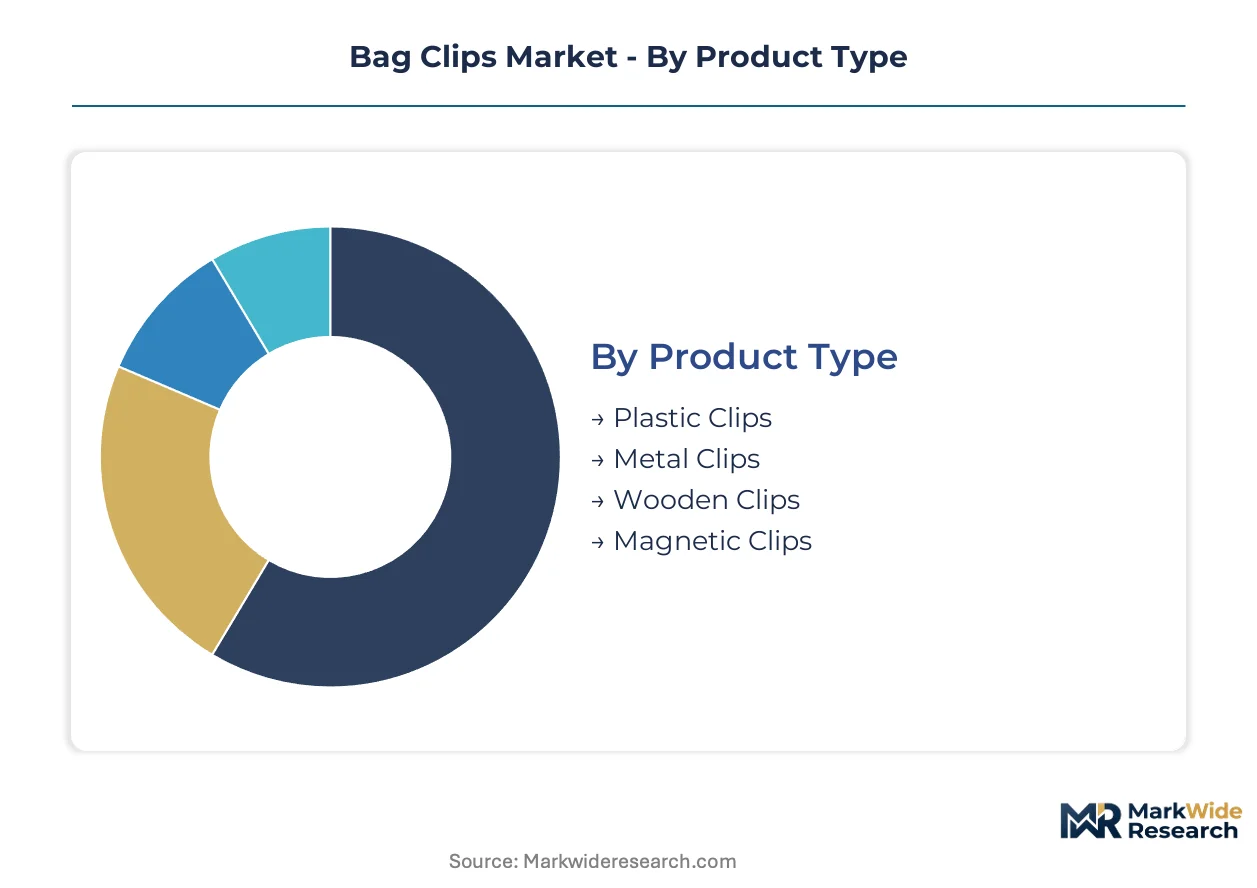
Bag clip procurement diverges sharply across channels, with food-contact compliance and load-bearing specifications creating incompatible design requirements between household convenience buyers and industrial bulk packaging operators. Segment boundaries are hardening as substrate regulations in the EU and FDA jurisdictions force single-purpose formulations rather than universal designs.
Product Type:
Plastic clips face the most intense substitution pressure from twist-tie systems in high-speed bakery applications, while magnetic and metal variants defend niche positions through functional differentiation that plastics cannot replicate.
- Plastic Clips:Injection-molded polyethylene constructions dominate unit economics through scalable production, though EFSA migration testing timelines now extend qualification cycles for food-contact formulations. German and French retail chains are mandating mono-material designs to satisfy EU Packaging and Packaging Waste Regulation mechanical recycling requirements.
- Metal Clips:Stainless steel variants withstand thermal sterilization cycles in commercial kitchen environments, commanding persistent cost premiums that exclude them from bread and produce bag applications. US food service operators specify these for prepared meal container closures where durability justifies procurement spend.
- Wooden Clips:Bamboo-sourced constructions serve premium household organization segments and specialty retail gift packaging where tactile aesthetics override functional performance metrics.
- Magnetic Clips:Neodymium-bonded silicone designs penetrate household organization systems and retail display fixtures, creating margin expansion outside commodity food packaging channels.
Plastic clips anchor the volume base while magnetic clips gain share at the steepest rate.
Size:
Cost tier stratification runs inverse to unit volume, with small formats moving through mass retail at thin margins while extra large industrial specifications capture value through engineered load retention.
- Small:Polyethylene constructions under 5 cm length serve bread bag and snack packaging where closure force requirements remain minimal. These move through high-velocity retail channels with annual supply agreement pricing.
- Medium:Versatile formats spanning 5-10 cm address the majority of household food storage applications, balancing grip strength against material cost.
- Large:Heavy-duty polyethylene or stainless steel designs secure bulk ingredient bags in commercial kitchen environments where contents exceed 2 kg.
- Extra Large:Industrial specifications engineered for load retention above 10 kg concentrate in bulk packaging applications for agricultural and chemical commodities.
Small and medium formats generate the highest unit throughput while extra large specifications expand most quickly in industrial procurement.
Material:
Supply concentration in Asian resin compounding operations shapes competitive access to food-contact-compliant polyethylene, while alternative substrates remain fragmented across specialty suppliers.
- Polyethylene:The dominant injection-molding substrate achieves cost scalability but faces reformulation mandates under EU REACH migration limit protocols. Captive resin compounding capabilities at integrated manufacturers create qualification bottlenecks for mid-tier competitors.
- Stainless Steel:304 and 316 grade alloys satisfy FDA food-contact durability requirements through repeated commercial dishwasher cycles. Thermal sterilization compatibility sustains demand in hospital and institutional catering procurement.
- Bamboo:Renewable sourcing addresses sustainability scorecard requirements for premium private-label retail programs, though moisture sensitivity limits functional applications.
- Silicone:Bonded constructions in magnetic clip assemblies provide grip surfaces and neodymium encapsulation for household organization systems.
Polyethylene sustains the volume base while silicone-bonded constructions climb the fastest in premium segment expansion.
End User:
Customer type determines specification stringency, with food service and industrial buyers imposing performance guarantees that household and retail channels do not require.
- Household:Convenience-driven procurement through mass retail and e-commerce channels prioritizes unit price over closure force retention metrics. Magnetic and wooden designs concentrate here for organization and aesthetic applications.
- Retail:Private-label bread and produce packaging in Germany and France now mandates mono-material polyethylene clips to satisfy extended producer responsibility frameworks. High-speed applicator compatibility at 300+ units per minute distinguishes supplier qualification.
- Food Service:US regional restaurant chains specify resealable closures for prepared meal containers with closure force retention above 2.5 N. Bundled label-and-closure contracts consolidate procurement around integrated suppliers.
- Industrial:Bulk packaging operators require extra large formats with load retention exceeding 10 kg for agricultural and chemical commodity handling.
Household and retail channels anchor volume throughput while food service procurement demonstrates the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in bag clips track polymer compounding capacity and retail packaging demand density. Germany and the United States run structural deficits in food-contact-compliant resin formulations, sourcing injection-molded polyethylene clips from integrated Asian compounders while exporting stainless steel variants for commercial kitchen applications.
United States
Regional restaurant chains drive specification upgrades for prepared meal container closures with mandated retention force above 2.5 N. FDA food-contact substance notifications govern polyethylene substrate selection for bread and produce bag applications. Chicago and Dallas-Fort Worth anchor food service distribution networks where bundled label-and-closure procurement consolidates around integrated suppliers.
Germany
High-speed bakery packaging lines exceeding 300 units per minute pull twist-tie substitution demand for applicator-compatible clip designs. EU Packaging and Packaging Waste Regulation mandates mono-material polyethylene constructions to satisfy mechanical recycling sortation requirements. Bavaria concentrates injection molding capacity for retail private-label programs serving Aldi and Lidl supply chains.
China
Captive resin compounding operations supply global volume demand for commodity polyethylene clips while domestic food service adoption lags Western specification standards. GB standards for food-contact plastics shape substrate formulation choices for export-oriented manufacturers. Yangtze River Delta clusters in Jiangsu and Zhejiang provinces dominate injection molding scale for North American and European retail procurement.
France
Extended producer responsibility fee structures incentivize mono-material clip designs that simplify municipal waste stream processing. EFSA migration limit testing extends supplier qualification timelines to 18-24 months for novel polyethylene formulations. The Paris basin hosts specialty retail display manufacturers absorbing premium magnetic clip volumes for household organization systems.
Japan
Connected refrigerator integration creates premium demand for RFID-enabled inventory tracking clips in smart kitchen applications. METI circular economy guidelines pressure redesign toward easily disassembled mono-material constructions. Osaka-Kobe industrial corridors concentrate precision molding capacity for neodymium-bonded silicone magnetic assemblies serving domestic organization product brands.
Bag Clips Market Competitive Environment
Concentration sits with integrated polymer science operations that control captive resin compounding for food-contact-compliant formulations. The supplier base fragments across injection molding specialists serving commodity bread bag applications and metal fabricators defending commercial kitchen niches. Two archetypes dominate: vertically integrated resin-to-clip manufacturers and bundled label-and-closure integrators. Competitive moves center on qualification timeline acceleration through pre-submitted FDA notifications and backward integration into polyethylene compounding to escape Asian supply bottlenecks.
Among North American integrated manufacturers, ITW and CCL Industries exemplify the polymer science archetype with control over substrate formulation and regulatory compliance capacity. Kwik Lok Corporation anchors the high-speed applicator specialization vector, representing the machinery-compatible design tier that dominates bread-bag twist-tie substitution. These three companies sit within distinct competitive positions—resin integration, bundled supply contracts, and automated packaging line compatibility—rather than direct product overlap.
| Leading Market Players |
|---|
| ITW |
| CCL Industries |
| Kwik Lok Corporation |
| DuraClip |
| Berry Global |
| Bedford Industries |
| Plas-Ties |
| ClipsShop |
| Schutte Bagclosures |
| Others |
Value Chain & Pricing Dynamics
FDA food-contact substance notifications and EU REACH migration limits simultaneously gate supplier qualification and stratify price tiers across the bag clip market. These dual regulatory frameworks force manufacturers to absorb compliance costs upfront or pass them through channel pricing, with integrated resin compounders capturing margin premiums unavailable to specification buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on closure force certification grade above 2.5 N and food-contact compliance tier, with stainless steel variants commanding persistent premiums over polyethylene. Pricing pressure stems from resin feedstock volatility locked into annual retail supply agreements. Household mass retail channels exhibit highest price sensitivity, while commercial kitchen procurement prioritizes performance guarantees over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-North America trade lanes expose inbound logistics cost volatility for resin-dependent manufacturers. Supply concentrates in China, South Korea, and Taiwan for polyethylene compounding, with Yangtze River Delta clusters feeding global injection molding scale. Raw material dependencies center on ethylene feedstock, neodymium for magnetic assemblies, and 304/316 grade stainless steel. Single-source vulnerability sits with Asian resin compounders holding captive food-contact formulation capabilities. Distribution runs through retail private-label programs, food service distribution networks, and industrial bulk packaging channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA and EU jurisdictions is creating niche entry points for specialized compliance providers. The divergence between food-contact certification timelines and sustainability mandates rewards agile substrate innovators.
For Market Incumbents: Compound defensive positioning through backward integration into polyethylene compounding to escape Asian supply bottlenecks. Accelerate pre-submitted FDA notification pipelines to compress qualification timelines against EFSA migration testing delays. Prioritize mono-material engineering investments before retailer substrate lock-in hardens across European private-label agreements. For New Entrants and Emerging Players: Lead with RFID-enabled inventory tracking clips for Japanese smart kitchen integration, the most penetrable premium segment outside commodity food packaging. Target German and French high-speed bakery automation lines for twist-tie substitution at throughput rates exceeding 300 units per minute. Deploy regulatory affairs specialization as the primary go-to-market wedge against mid-tier competitors lacking compliance capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across magnetic clip assemblies due to neodymium-bonded silicone precision molding requirements. The five-to-ten year viability window favors integrated polymer science operations with captive resin formulation and existing food-contact certification infrastructure. Watch EFSA migration limit testing timeline extensions as the critical signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene formulation escapes Asian supply bottlenecks and accelerates FDA notification timelines. |
| Mono-Material Clip Engineering | EU Packaging and Packaging Waste Regulation compliance secures preferential placement in Aldi and Lidl supply chains. |
| RFID-Enabled Smart Kitchen Clips | Connected refrigerator integration opens premium household segments in Japan and South Korea. |
| High-Speed Applicator Compatibility Investment | Automated bakery line qualification at 300+ units per minute displaces twist-tie systems in Germany and France. |
| Regulatory Affairs Capacity Expansion | Specialized FDA and EFSA compliance staffing addresses 18-24 month qualification timeline bottlenecks. |
Study Parameters
The analysis maps plastic, metal, magnetic, and wooden clip sub-sectors, each validated through plant managers at injection molding operations, procurement leads at retail grocery chains, regulatory affairs directors, and food service distribution executives. Primary interview findings triangulated against customs trade data, FDA food-contact substance notification databases, EU REACH registration dossiers, and SEC filings from integrated manufacturers. Bottom-up unit volume estimates and top-down value projections were reconciled across polyethylene resin consumption patterns and clip applicator installation counts.
Consistency checks validated volume and value outputs against external benchmarks including regional retail packaging demand indices and commercial kitchen equipment procurement surveys. The analytical framework modeled product type, material substrate, size tier, and end-user channel dimensions across the projection horizon. CAGRs were derived from segment-level growth rate synthesis anchored to resin compounding capacity expansion and regulatory mandate implementation schedules. Forecast inputs incorporated EFSA migration testing timeline trajectories and EU extended producer responsibility fee structure evolution.
Forecasts assume regulatory continuity in FDA food-contact substance notification regimes and EU REACH frameworks; material policy shifts would require re-modeling. Specific risk factors include polyethylene feedstock price volatility, qualification timeline extensions, and mechanical recycling infrastructure deployment variance across North American and European municipal waste streams. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Multiwall Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Bin Liners Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Crates Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Bags and Containers Market