
 Baggage Packaging Service Market | 2026-2036
Baggage Packaging Service Market Size, Share, and Industry Trends Forecast 2026-2036
Baggage Packaging Service Market Analysis
The premium baggage packaging tier is repositioning around damage-liability guarantees and branded tamper-evidence, while commodity wrap services compete on speed and per-unit cost. DHL Group leverages its airport logistics footprint to bundle packaging with last-mile tracking. Berry Global sustains material science leadership through proprietary high-tensile stretch films. Intertek Group anchors quality assurance credibility with airline-certified testing protocols.
Baggage packaging service denotes the commercial application of protective materials and containment structures to shield luggage from mechanical stress, moisture intrusion, and theft during transit. Operators deploy heat-sealed polyethylene wraps, corrugated triple-wall boxes, and expanded polyethylene foam inserts based on item fragility and dimensional weight pricing. Plastic wrap and bubble wrap dominate volume due to low unit cost and rapid application at airport kiosks, though cardboard and foam capture margin pools in corporate contract segments requiring custom crating for high-value cargo. The customer type dimension reveals airlines as the fastest-growing procurement channel as carriers outsource damage-prevention liability to third-party packaging vendors.
The FAA mandates fire-resistant packaging standards for lithium-ion batteries in checked baggage, while the EU Green Deal drives substitution mandates for single-use plastics at European airports. Germany's KBA and France's CNIL influence cross-border data collection from smart packaging tags that track baggage location. Stakeholders must monitor how biometric baggage handling systems integrate with packaging verification workflows without triggering privacy enforcement actions.
Market Dynamics
Carrier liability outsourcing is restructuring the baggage packaging value chain, as airlines transfer damage-prevention accountability to specialized third-party vendors at major hub airports.
Growth Catalysts
- EU Green Deal plastic substitution mandates:European airports accelerate procurement of recyclable films and bio-based foam alternatives to comply with single-use plastic restrictions.
- Lithium-ion battery fire-safety protocols:The FAA mandates fire-resistant packaging standards for checked baggage containing power cells, expanding demand for certified containment materials.
- Hub airport passenger volume concentration:Germany, the United States, and China process the highest international passenger flows, concentrating packaging service demand at Frankfurt, Atlanta, and Beijing facilities.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil markets, compressing margins for stretch-film operators.
- REACH chemical compliance costs:ECHA substance restrictions force reformulation of adhesive coatings and flame-retardant additives, extending product development timelines.
- Reusable hard-shell luggage substitution:Premium travelers increasingly purchase polycarbonate and aluminum suitcases with integrated damage resistance, reducing per-trip packaging demand.
Strategic Opportunities
- Biometric baggage handling integration:Smart packaging tags that interface with facial-recognition boarding systems create data-rich tracking services at Dubai and Singapore airports.
- Corporate cargo contract expansion:High-value electronics and pharmaceutical shippers seek custom crating with tamper-evidence certification for air freight.
- India aviation infrastructure buildout:Greenfield airports at Navi Mumbai and Jewar generate first-mover positioning for protective packaging vendors.
Industry Challenges
- Cross-border data privacy enforcement:France's CNIL and Germany's KBA impose conflicting requirements on location-tracking tag data retention, complicating smart-packaging rollout.
- Certification timeline compression:Airline-specific damage-liability guarantees require extended testing protocols against Intertek Group standards, delaying vendor onboarding.
- Legacy warehouse management system integration:Older airport logistics platforms lack API connectivity for real-time packaging verification, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baggage Packaging Service Market |
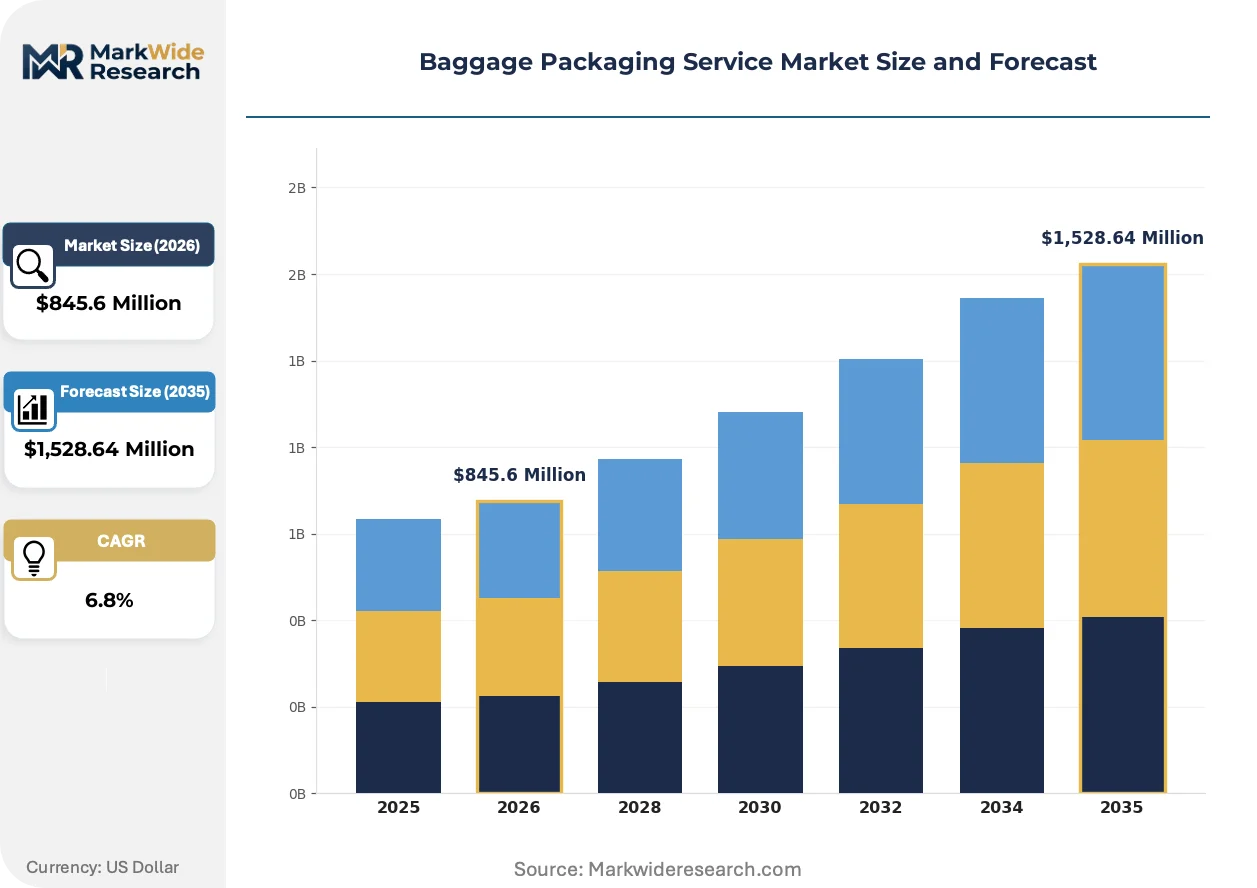
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,528.64 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wrap, Box, Pallet, Crate Material Type: Plastic, Cardboard, Foam, Bubble Wrap Customer Type: Individual Travelers, Corporations, Logistics Providers, Airlines Distribution Channel: Direct Sales, Retail Outlets, E-commerce, Airport Kiosks |
| Companies Covered | SGS North America, Intertek Group, DHL Group, Berry Global, All Packaging Services, PakFactory, Crown Packaging, Econo-Pak, Industrial Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baggage Packaging Service Market Emerging Trajectories
Material science convergence with digital tracking infrastructure is redefining value capture in protective packaging, shifting competition from commodity wrap speed to integrated damage-prevention systems.
High-tensile stretch films engineered from post-industrial recycled polyethylene are expanding into airline contract segments previously dominated by virgin-material suppliers. Lufthansa and Delta procurement teams now specify minimum recycled content thresholds in request-for-proposal documents. This material transition is expanding into premium service tiers where carriers bundle sustainability credentials with damage-liability coverage.
REACH chemical restrictions and the EU Green Deal timeline are forcing substitution of halogenated flame retardants in battery packaging foams. German and French airport operators now reject non-compliant materials at receiving docks, redirecting procurement toward bio-based alternatives. Cargo handlers at Amsterdam Schiphol and Paris Charles de Gaulle have established dedicated compliance verification lanes for sustainable packaging certification.
Airline procurement departments now unbundle damage-prevention services from ground-handling contracts, creating direct vendor relationships with specialized packaging firms. This disintermediation bypasses traditional airport service consortiums and compresses pricing negotiation cycles. The shift is most visible at United States hub airports where major carriers have established standalone packaging procurement offices with dedicated category managers.
Baggage Packaging Service Market Segmentation
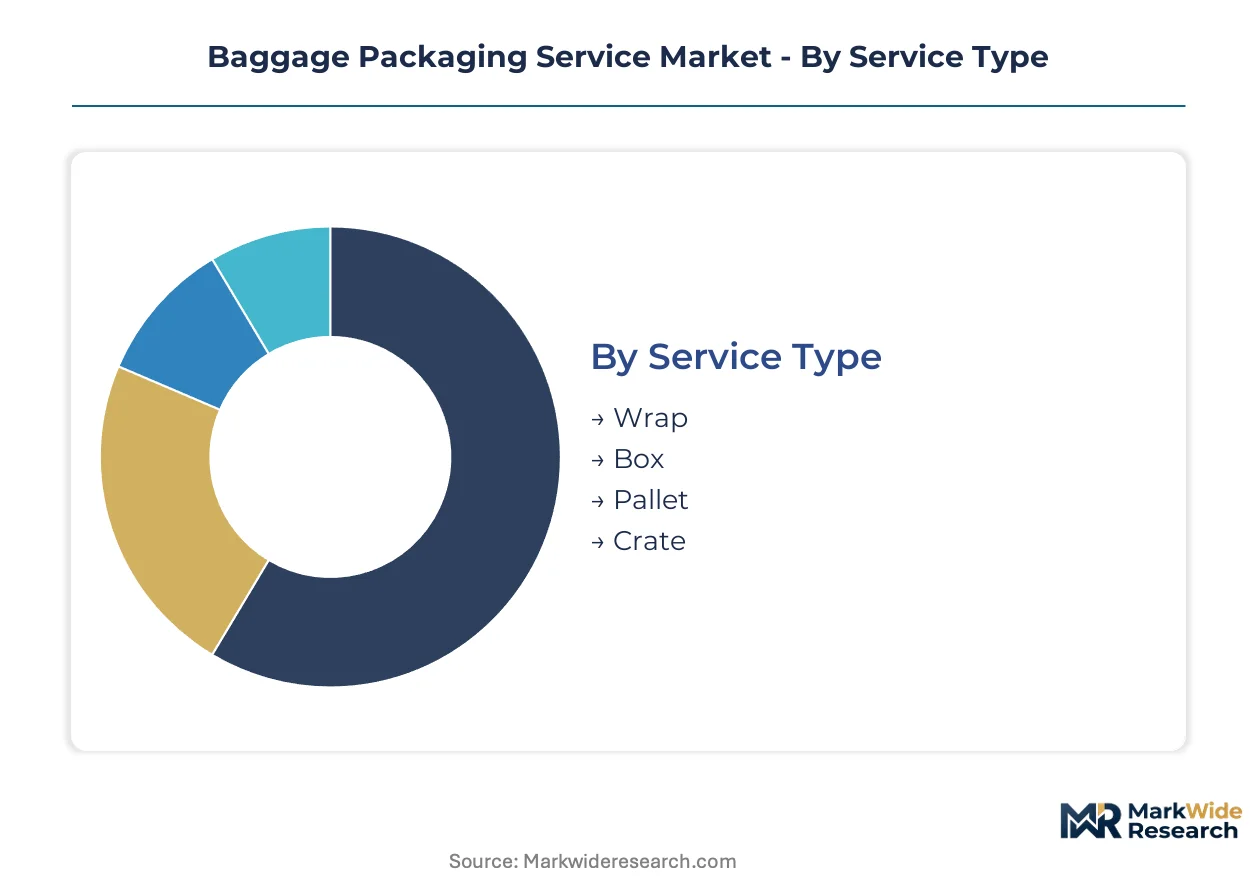
Baggage packaging service segmentation reveals how procurement power concentrates across distinct operational tiers. Material specifications and channel access determine margin capture, while customer type governs contract scale and liability structures.
Service Type:
Service type supply concentrates at hub airport facilities where throughput economics favor automated wrap stations over manual crating operations.
- Wrap:Heat-sealed polyethylene films applied through automated turntable systems dominate passenger terminal volumes. Demand concentrates at Frankfurt, Atlanta, and Beijing where per-unit processing speed drives carrier procurement decisions.
- Box:Corrugated triple-wall containers with reinforced corners capture corporate contract segments requiring dimensional weight optimization. Logistics providers at Amsterdam Schiphol and Paris Charles de Gaulle specify crush-tested certification for high-value electronics freight.
- Pallet:Unit-load containment for cargo consolidation through net wrapping and corner board reinforcement.
- Crate:Custom timber or plywood structures for fragile industrial equipment and exhibition materials.
Today's leader: Wrap. Tomorrow's challenger: Box.
Material Type:
Material procurement patterns split between commodity resin contracts for high-volume wrap operations and specialized foam formulations for battery compliance.
- Plastic:Linear low-density polyethylene stretch films with post-industrial recycled content now meet Lufthansa and Delta minimum thresholds. REACH chemical restrictions force adhesive reformulation at European receiving docks.
- Foam:Expanded polyethylene inserts engineered for lithium-ion battery fire containment. FAA mandates drive specification at United States hub airports where power cell shipments concentrate.
- Cardboard:Recycled-content corrugated board for lightweight containment of non-fragile items.
- Bubble Wrap:Air-encapsulation films for surface protection of consumer electronics in retail packaging.
Plastic commands current procurement volumes. Foam gains share fastest on regulatory tailwinds.
Customer Type:
Customer concentration follows airline outsourcing trends, with damage-liability transfer creating direct vendor relationships at major carrier procurement offices.
- Airlines:Carriers unbundle damage-prevention from ground-handling contracts, establishing standalone packaging procurement functions. United States hub airports host dedicated category managers negotiating service-level agreements with specialized vendors.
- Corporations:High-value electronics and pharmaceutical shippers seek tamper-evidence certification for air freight. Custom crating contracts at Dubai and Singapore airports specify biometric tag integration.
- Individual Travelers:Per-trip wrap purchases at airport kiosk terminals.
- Logistics Providers:DHL Group bundles packaging with last-mile tracking across integrated airport networks.
Airlines anchor contract value. Corporations represent the steepest expansion trajectory.
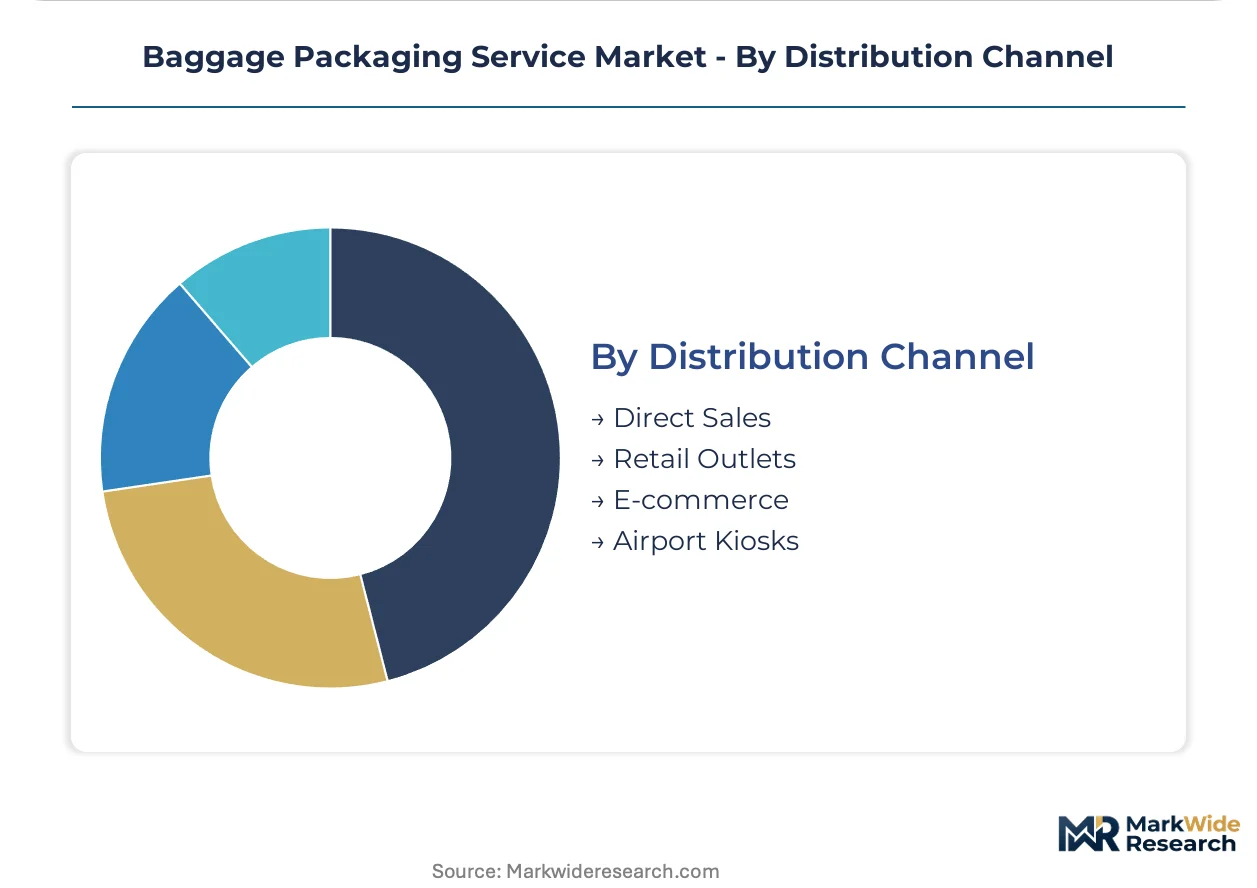
Distribution Channel:
Channel configuration reflects the physical constraints of airport security zones and passenger flow patterns.
- Airport Kiosks:Automated wrap stations positioned post-security screening capture impulse procurement from time-constrained travelers. Germany's KBA and France's CNIL impose conflicting data retention requirements on smart packaging tags deployed at these locations.
- Direct Sales:Corporate procurement teams negotiate multi-year service agreements with packaging vendors. This channel bypasses traditional airport service consortiums at United States facilities.
- Retail Outlets:Pre-trip packaging supply through travel goods stores and hotel concierge services.
- E-commerce:Online booking platforms for baggage protection add-ons during flight reservation.
Airport kiosks dominate transaction frequency. Direct sales capture contract margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled logistics workforces at Frankfurt, Atlanta, and Beijing anchor procurement concentration for protective packaging services. Carrier procurement offices cluster at these hub airports where passenger throughput economics justify dedicated category management. Regulatory divergence between EU Green Deal mandates and FAA fire-safety protocols fragments material specifications across jurisdictions.
United States
Hub concentration at Hartsfield-Jackson Atlanta and Dallas-Fort Worth drives carrier outsourcing of damage-prevention services. FAA lithium-ion battery fire-safety protocols mandate certified containment materials at United States facilities. Procurement offices at Chicago O'Hare and Denver International negotiate standalone service-level agreements bypassing traditional ground-handling consortiums.
Germany
Frankfurt Airport's cargo throughput sustains Europe's densest packaging vendor ecosystem for high-value freight. KBA vehicle safety standards influence smart packaging tag data retention requirements for biometric baggage integration. Amsterdam Schiphol and Paris Charles de Gaulle receiving docks now reject non-REACH-compliant materials, redirecting procurement toward bio-based foam alternatives.
China
Beijing Capital and Shanghai Pudong process Asia's highest international passenger volumes, concentrating automated wrap station deployment. SAMR product safety standards govern lithium battery packaging certification for air cargo exports. Guangzhou Baiyun and Shenzhen Bao'an greenfield terminals generate first-mover positioning for recyclable film vendors.
India
Navi Mumbai and Jewar greenfield airports create infrastructure buildout opportunities for protective packaging vendors entering the market. BIS quality standards shape domestic certification requirements for imported containment materials. Bangalore Kempegowda and Hyderabad Rajiv Gandhi cargo terminals attract corporate contract segments seeking custom crating for electronics exports.
United Arab Emirates
Dubai International's biometric baggage handling infrastructure enables smart packaging tag integration with facial-recognition boarding systems. MOHAP health product regulations influence pharmaceutical shipper packaging specifications for temperature-sensitive air freight. Abu Dhabi Zayed International cargo consolidation lanes specialize in high-value electronics containment with tamper-evidence certification.
Baggage Packaging Service Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the baggage packaging service structure. Asset-intensive stretch-film manufacturers and automated kiosk operators face competition from specialized testing laboratories and logistics integrators that design service architectures without captive production. The vendor base splits between material science specialists, quality assurance certifiers, and integrated logistics bundlers. Consolidation pressure operates through carrier procurement centralization and airline-specific damage-liability guarantee requirements.
Among testing and certification specialists, Intertek Group and SGS North America exemplify quality assurance archetypes anchoring airline-certified protocol credibility. DHL Group occupies a position within integrated logistics bundlers that leverage airport footprints to combine packaging with tracking services. Berry Global represents material science leadership through proprietary high-tensile stretch film formulations serving carrier recycled content thresholds.
| Leading Market Players |
|---|
| SGS North America |
| Intertek Group |
| DHL Group |
| Berry Global |
| All Packaging Services |
| PakFactory |
| Crown Packaging |
| Econo-Pak |
| Industrial Packaging |
| Others |
Supply Flow & Price Mechanics
EU Green Deal plastic substitution mandates gate both qualified supply and premium-tier pricing access, as REACH-compliant bio-based foams and recyclable films command procurement preference at Frankfurt and Amsterdam Schiphol receiving docks while non-compliant virgin-material suppliers face exclusion from airline contract pools. Carriers now specify minimum recycled content thresholds in request-for-proposal documents, bifurcating the vendor base between sustainability-certified premium tiers and commodity wrap operations competing on per-unit processing speed.
Pricing Analysis
The bundled-vs-unbundled service split separates damage-liability guarantees with tamper-evidence certification from transactional wrap-only purchases at airport kiosk terminals. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with airline procurement offices at Chicago O'Hare and Denver International negotiating standalone service-level agreements that bypass traditional ground-handling consortiums. Cost compression in commodity wrap tiers is intensifying because petrochemical feedstock volatility compresses polyethylene resin margins. Individual travelers at post-security automated stations exhibit highest price sensitivity, while corporate pharmaceutical shippers accept premium positioning for temperature-sensitive containment with biometric tag integration.
Supply Chain Analysis
Linear low-density polyethylene resin supply rests on petrochemical producers in the United States, Germany, and China, with post-industrial recycled content sourcing anchored in European mechanical recycling infrastructure. Bio-based foam formulations for lithium-ion battery containment draw from specialty chemical producers in Germany and France subject to ECHA substance restrictions. Single-source vulnerability concentrates in halogenated flame-retardant additive supply chains facing REACH-driven phaseout timelines. Distribution runs through hub airport logistics zones where DHL Group and integrated handlers bundle packaging with last-mile tracking across captive terminal networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs at European airports and FAA fire-safety protocol requirements at United States facilities, with material specification divergence creating procurement optimization opportunities for dual-certified vendors.
For Market Incumbents: To counter carrier procurement centralization and airline-specific damage-liability guarantee requirements, Berry Global and material science specialists should deepen backward integration into post-industrial recycled polyethylene sourcing to secure Lufthansa and Delta minimum content thresholds. Intertek Group and testing laboratories must expand certification capacity for REACH-compliant bio-based foam alternatives to capture vendor onboarding demand at Amsterdam Schiphol and Paris Charles de Gaulle compliance verification lanes. For New Entrants and Emerging Players: Capture first-mover positioning at Navi Mumbai and Jewar greenfield airports in India where BIS quality standards create domestic certification barriers for incumbent import-dependent vendors. Target corporate cargo contract segments seeking custom crating with tamper-evidence certification for high-value electronics exports through Bangalore Kempegowda and Hyderabad Rajiv Gandhi cargo terminals, leveraging direct sales channel bypass of traditional airport service consortiums established by United States carrier procurement offices. For Investors and Strategic Acquirers: Roll-up economics work for regional packaging specialists with established airline procurement relationships because carrier outsourcing of damage-prevention liability is compressing vendor onboarding timelines and favoring scaled service providers with Intertek-certified testing protocols. Long-term viability hinges on biometric baggage handling integration capabilities at Dubai and Singapore airports. Watch for FAA lithium-ion battery fire-safety protocol expansion beyond power cells to other hazardous cargo categories as inflection indicator for certified containment material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | Secures post-industrial polyethylene supply for Lufthansa and Delta minimum content thresholds. |
| REACH-Compliant Bio-Based Foam Certification | Unlocks procurement access at Amsterdam Schiphol and Paris Charles de Gaulle receiving docks. |
| Biometric Tag Integration Development | Enables smart packaging data services at Dubai International's facial-recognition boarding systems. |
| Greenfield Airport Market Entry | Captures first-mover positioning at Navi Mumbai and Jewar infrastructure buildouts before incumbent saturation. |
| Airline Procurement Office Direct Sales | Bypasses traditional ground-handling consortiums at United States hub airports with standalone category managers. |
Methodological Framework
Multiple input streams — primary interviews with airline procurement managers, ground-handling operations directors, and packaging vendor sales executives; secondary validation through FAA regulatory filings, ECHA substance restriction databases, and carrier request-for-proposal documents; plus customs and trade data on polyethylene resin imports — were reconciled through bottom-up and top-down triangulation to construct segment-level volume and value estimates across the analysis window.
Historical growth patterns were cross-referenced against panel input from industry participants to model expansion trajectories across service type, material type, customer type, and distribution channel dimensions, with particular attention to biometric baggage handling integration complexity and REACH chemical compliance timeline acceleration. CAGRs were derived from segmented growth rate application to baseline estimates, incorporating lithium-ion battery fire-safety protocol expansion and EU Green Deal substitution mandate enforcement as industry-specific forecast inputs.
Petrochemical feedstock price volatility, regulatory timeline slippage for bio-based material certification, and biometric data privacy enforcement divergence between Germany's KBA and France's CNIL are the dominant revision risks to modeled outcomes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Mesh Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Counter Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Bag-In-Box Packaging Market