
 Lunch Boxes and Lunch Bags Market | 2026-2036
Lunch Boxes and Lunch Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Lunch Boxes and Lunch Bags Market Foresight
Premium-grade thermal insulation is reorganizing competitive dynamics across the lunch container category. Thermos LLC leverages decades of vacuum-flask expertise to sustain pricing power in high-performance segments. Newell Brands anchors broad retail distribution through Rubbermaid's mass-market penetration. Zojirushi differentiates through precision-engineered stainless steel bento systems that command loyalty in Asian and North American markets.
Lunch boxes and lunch bags comprise portable food storage vessels engineered with thermal retention specifications, leak-resistant sealing mechanisms, and food-grade material compositions designed to maintain safe temperatures and prevent contamination during transport. Insulated bags lead volume due to workplace meal-prep habits, while stainless steel containers capture margin pools from durability-focused buyers. Fabric materials compete aggressively on sustainability positioning, and the eco-friendly design tier attracts regulatory tailwinds across multiple jurisdictions.
FDA food-contact regulations govern plastic and stainless steel compositions in the United States, while REACH and the EU Green Deal restrict certain chemical additives and mandate recyclability disclosures across Europe. Japan's Ministry of Economy, Trade and Industry (METI) promotes circular-economy standards that influence material selection for export-oriented manufacturers. Stakeholders must monitor evolving chemical-compliance thresholds and thermal-performance certification requirements as procurement criteria tighten across institutional and retail channels.
Market Dynamics
Working professionals across the United States, Germany, and Japan are reconfiguring demand around thermal retention performance and material compliance, forcing manufacturers to recalibrate product portfolios around REACH-mandated material substitutions and FDA food-contact specifications.
Growth Catalysts
- EU Green Deal material mandates:REACH compliance requirements are accelerating stainless steel and glass adoption across European supply chains, creating premium tier expansion for durable alternatives.
- Workplace meal-prep normalization:Office return patterns in the United States are sustaining insulated bag volume through institutional procurement channels.
- METI circular-economy standards:Japan's export-oriented manufacturers are redesigning material specifications to capture regulatory alignment advantages in Asian markets.
Market Restraints
- Petrochemical input volatility:Fabric insulation materials face margin compression from petroleum-derived synthetic fiber price swings.
- Supply concentration in East Asian manufacturing:Stainless steel container production clusters heavily in specific industrial zones, creating geographic risk exposure.
- Thermal performance certification friction:Divergent testing standards across FDA, REACH, and JIS frameworks increase compliance overhead for multi-market launches.
Strategic Opportunities
- Underpenetrated German institutional channels:Corporate cafeteria outsourcing contracts represent whitespace for bulk thermal container procurement.
- Smart temperature monitoring convergence:Integration of IoT sensors with vacuum-flask construction is opening connected-lunchbox segments.
- US workplace wellness incentives:Employer-sponsored meal-prep subsidies are creating new B2B distribution pathways.
Industry Challenges
- Food-grade polymer chemist scarcity:Formulation expertise for BPA-free sealing compounds is concentrated among a narrow specialist pool.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and JIS approvals extend product launch cycles substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lunch Boxes and Lunch Bags Market |
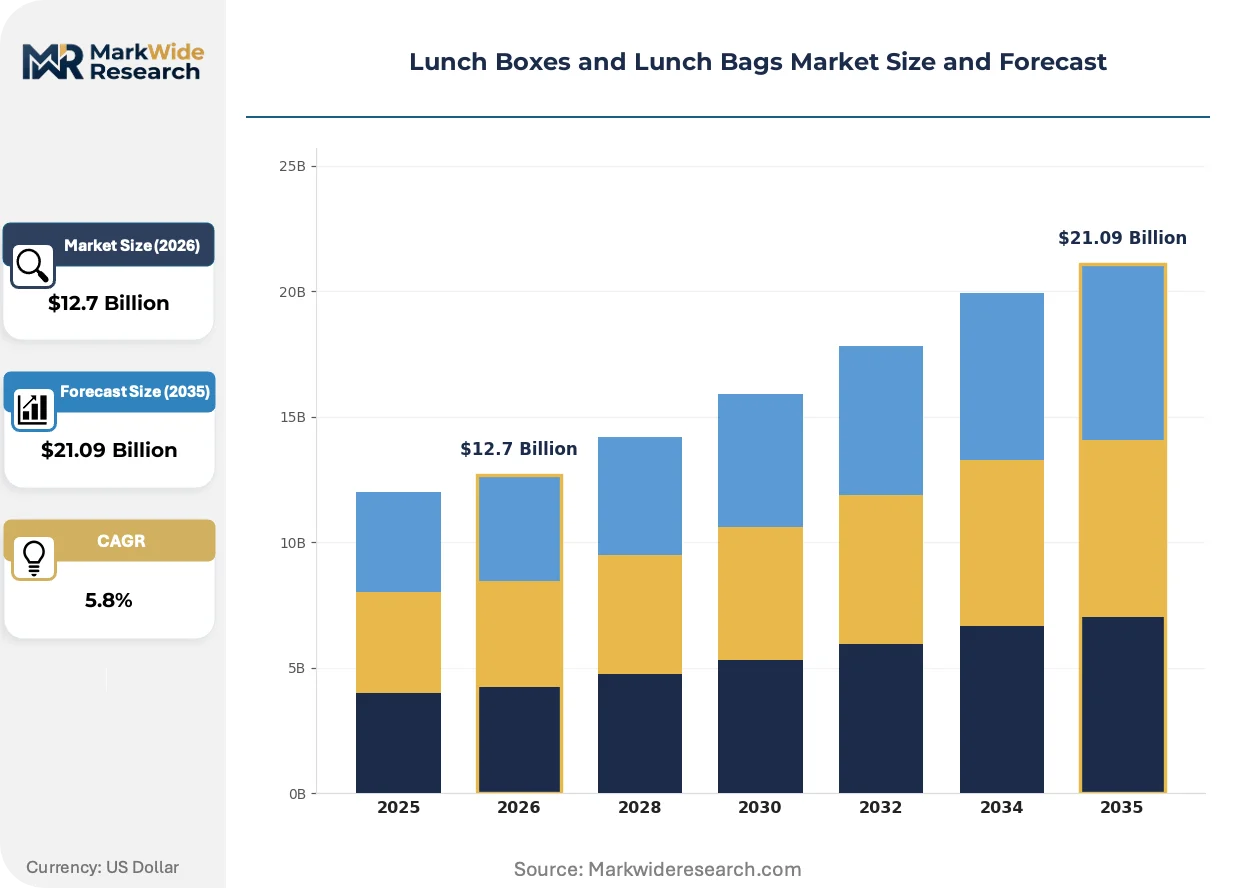
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bags, Bento Boxes, Reusable Containers, Disposable Bags Material: Plastic, Fabric, Stainless Steel, Glass End User: Students, Professionals, Parents, Travelers Design: Eco-Friendly, Customizable, Trendy, Minimalist |
| Companies Covered | Thermos LLC, Newell Brands, Tupperware Brands, Zojirushi, Pacific Market International, Bentgo, Igloo Products, Rubbermaid, PackIt LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lunch Boxes and Lunch Bags Market Shifts & Advancements
Vacuum-insulation engineering, regulatory material bans, and workplace consumption patterns are converging to reshape product architecture and go-to-market strategies across the lunch container category.
Phase-change material inserts are miniaturizing thermal management systems into slim-profile bag constructions. Corporate procurement managers in the United States are specifying these systems for executive meal programs. The technology is miniaturizing what previously required rigid vacuum-flask geometry into flexible textile formats.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy water-repellent coatings from European-market fabric products. Manufacturers are reformulating with silicone-based alternatives at higher unit cost. The insulated bag segment is absorbing the steepest compliance burden through pricing tier compression.
Subscription-based meal-kit delivery services are decoupling container ownership from food preparation. Urban professionals in Japan are shifting toward rental or lease-to-own thermal systems. This behavior is most visible in Tokyo and Osaka metropolitan corridors where space constraints favor minimal inventory models.
Lunch Boxes and Lunch Bags Market Segmentation
Thermal retention specifications and material compliance thresholds fragment the lunch container category into sharply differentiated tiers. Procurement managers in corporate and institutional channels weight segments differently than retail consumers, creating parallel demand curves that manufacturers must serve simultaneously.
Product Type:
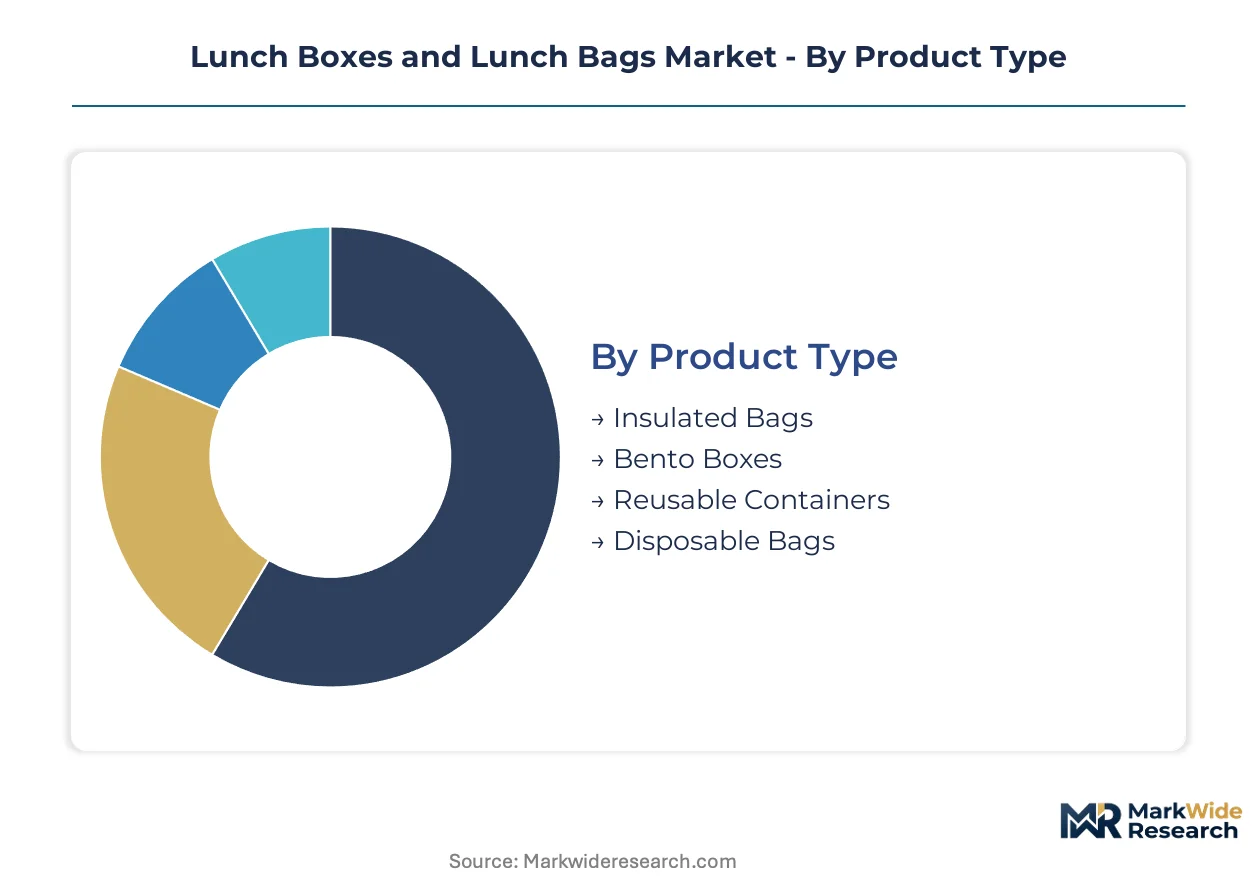
Insulated bags dominate domestic consumption in the United States and Japan, while bento boxes and stainless steel systems drive export manufacturing from East Asian production clusters.
- Insulated Bags:Multi-layer fabric construction with closed-cell foam cores delivers four-to-six-hour temperature retention. Demand concentrates among office professionals in the United States and Germany, where workplace meal-prep habits sustain volume through institutional procurement channels.
- Bento Boxes:Compartmentalized designs with precision-molded sealing mechanisms accommodate portion-controlled meal preparation. Japanese and North American markets anchor consumption, driven by METI circular-economy standards that favor durable, reusable formats over disposable alternatives.
- Reusable Containers:Modular plastic and glass systems with snap-lock lids target family meal-prep routines. Parents in suburban United States markets represent the core demographic.
- Disposable Bags:Single-use paper and thin-film constructions serve occasional-use and emergency-purchase occasions. Travelers and infrequent users generate sporadic demand across airport and convenience retail channels.
Insulated bags hold the largest share; momentum sits with bento boxes.
Material:
Cost tiers stratify sharply between petroleum-derived synthetics and premium-grade alternatives, with regulatory mandates in Europe compressing mid-market positioning.
- Plastic:FDA-compliant polypropylene and Tritan copolyester formulations dominate mass-market price points. REACH Annex XVII restrictions on certain additives are forcing reformulation cycles among European-market suppliers.
- Fabric:Polyester and nylon textiles with polyurethane foam insulation balance flexibility with thermal performance. Petrochemical input volatility is squeezing margins across synthetic fiber supply chains.
- Stainless Steel:Vacuum-insulated double-wall construction with food-grade 18/8 alloy specifications commands durability-focused premiums. Production concentrates in specific East Asian industrial zones, creating geographic concentration risk.
- Glass:Borosilicate and tempered soda-lime compositions with silicone sleeve protection target health-conscious consumers. EU Green Deal recyclability mandates are accelerating adoption across German and French markets.
Plastic retains volume leadership; glass is climbing the fastest on regulatory tailwinds.
End User:
Application context determines thermal performance requirements and price sensitivity, with professional use cases demanding certification-grade specifications that student and family segments rarely require.
- Students:Lightweight, leak-resistant designs with graphic customization options dominate K-12 and university channels. Parents drive purchase decisions with durability and cost-per-use calculations.
- Professionals:Slim-profile, executive-appropriate aesthetics with extended thermal retention anchor workplace meal-prep adoption. Corporate wellness subsidies in the United States are opening B2B distribution pathways.
- Parents:Multi-compartment, family-size configurations with dishwasher-safe components target household meal-prep efficiency. Suburban United States markets show highest penetration.
- Travelers:Collapsible and TSA-compliant formats with odor-resistant linings serve air travel and extended mobility use cases. Airport retail and direct-to-consumer channels dominate distribution.
Professionals generate the steepest expansion trajectory; students represent the largest installed base.
Design:
Margin pools concentrate in aesthetic differentiation tiers, with sustainability signaling and personalization capabilities commanding price premiums across all material categories.
- Eco-Friendly:Recycled-content fabrics, biodegradable components, and plastic-free packaging align with EU Green Deal disclosure requirements. German and French consumers show strongest willingness-to-pay premiums.
- Customizable:Monogram services, interchangeable components, and modular accessory systems enable personalization at point of purchase. Corporate gifting and loyalty program channels drive volume.
- Trendy:Seasonal color palettes, influencer collaborations, and limited-edition drops target fashion-conscious urban consumers. Social media discovery drives trial among younger demographics.
- Minimalist:Reduced-component, neutral-aesthetic designs with concealed hardware appeal to design-conscious professionals. Japanese and Scandinavian markets show highest affinity.
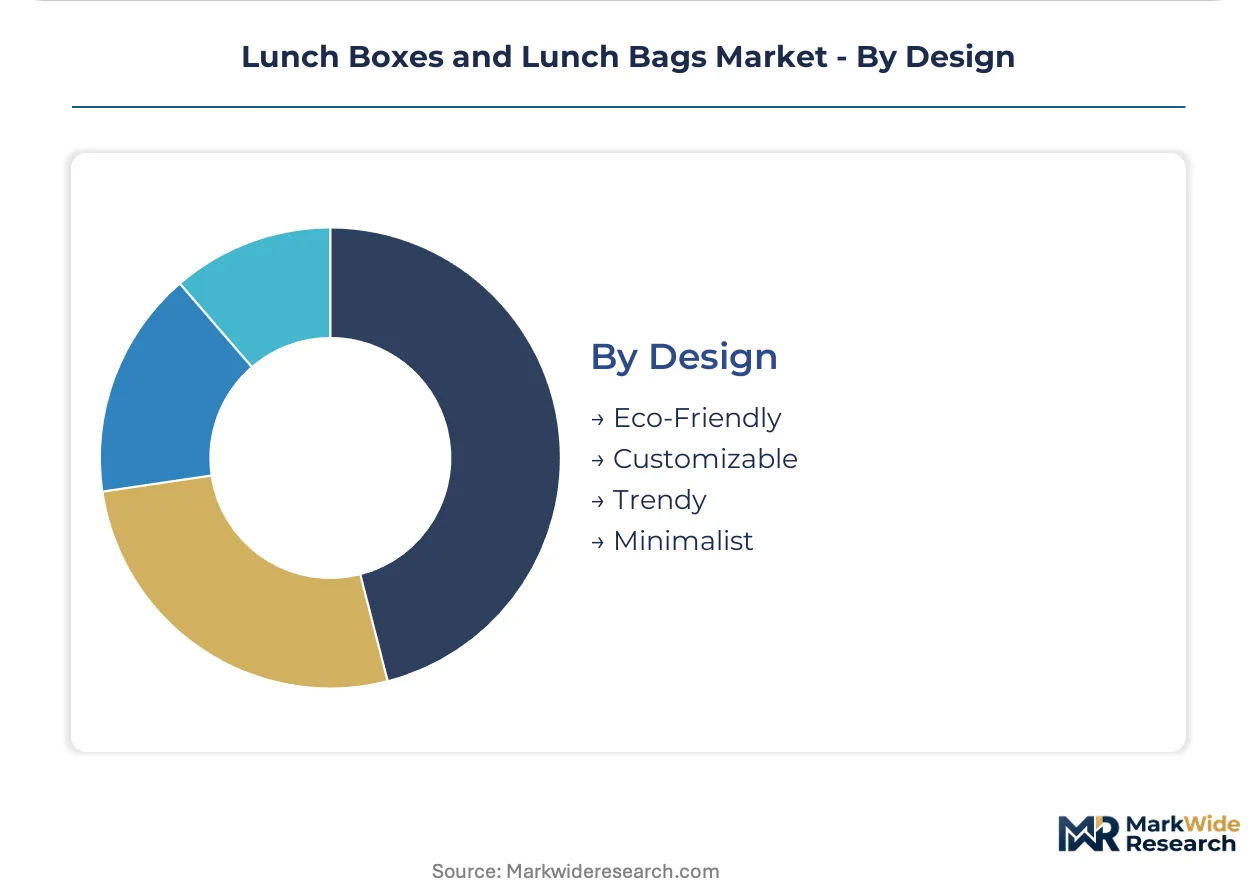
Eco-friendly designs hold the largest share; customizable formats are gaining share fastest on corporate procurement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in East Asia supply thermal container demand across North America and Europe, while regional regulatory divergence creates compliance complexity for multi-market product launches.
United States
Workplace meal-prep normalization sustains insulated bag volume through corporate procurement channels. FDA food-contact regulations govern plastic and stainless steel compositions, forcing reformulation cycles among import suppliers. Chicago and Dallas metropolitan corridors anchor B2B distribution networks for institutional thermal container contracts.
Germany
EU Green Deal material mandates accelerate stainless steel and glass adoption across consumer and institutional segments. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate legacy water-repellent coatings from fabric products. Industrial clusters in North Rhine-Westphalia concentrate precision metalworking capacity for vacuum-flask manufacturing.
Japan
METI circular-economy standards promote durable, reusable formats over disposable alternatives in domestic and export markets. Precision-engineered stainless steel bento systems command loyalty among urban professionals. Osaka and Nagoya manufacturing zones specialize in compact thermal retention engineering for premium-tier products.
China
Dual carbon goals and GB standards influence material specifications for export-oriented manufacturers serving European and North American buyers. Yangtze River Delta industrial zones cluster stainless steel container production, creating geographic concentration risk. Zhejiang and Guangdong provinces dominate fabric insulation supply chains.
Lunch Boxes and Lunch Bags Market Competitive Landscape
Concentration sits with diversified housewares conglomerates and specialized thermal engineering firms. The vendor base spans mass-market distributors, premium vacuum-flask specialists, and regional fabricators serving institutional channels. Three archetypes dominate: heritage thermal engineering brands with decades of vacuum-flask expertise, diversified consumer goods portfolios leveraging broad retail access, and agile specialists targeting design-forward urban demographics. Competitive moves center on material compliance certification acceleration and B2B procurement channel penetration.
Among heritage thermal engineering specialists, Thermos LLC and Zojirushi exemplify the premium-tier vacuum-flask archetype, while Newell Brands occupies a position within diversified housewares conglomerates leveraging scale-driven distribution. These three anchors represent distinct competitive vectors: precision-engineered thermal retention, mass-market retail penetration, and Asian manufacturing-export integration.
| Leading Market Players |
|---|
| Thermos LLC |
| Newell Brands |
| Tupperware Brands |
| Zojirushi |
| Pacific Market International |
| Bentgo |
| Igloo Products |
| Rubbermaid |
| PackIt LLC |
| Others |
Supply & Pricing Matrix
REACH-mandated material substitutions simultaneously reshape supply geography toward East Asian stainless steel clusters and compress pricing economics across European-market fabric tiers. Buyers absorb reformulation costs through tier migration, while manufacturers recalibrate margin structures around compliance-driven input switches.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across institutional procurement channels. Price differentiation hinges on certification grade alignment with FDA and REACH thresholds, plus volume scale in multi-year agreements. Cost compression in mid-market fabric tiers intensifies because petrochemical input volatility squeezes synthetic fiber margins. Corporate wellness program administrators show lowest price sensitivity; infrequent retail purchasers exhibit highest elasticity.
Supply Chain Analysis
China, Japan, and South Korea anchor vacuum-flask manufacturing and precision metalworking capacity for thermal retention systems. Production draws from 18/8 stainless steel feedstock, closed-cell polyurethane foam, and food-grade silicone sealing compounds. Single-source vulnerability concentrates in Yangtze River Delta industrial zones where geographic clustering amplifies disruption risk. Distribution runs through mass-market retail chains, direct-to-consumer platforms, and corporate procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as workplace meal-prep normalization drives institutional adoption beyond traditional consumer segments. Regulatory tailwinds across multiple jurisdictions extend replacement demand for compliant material formats.
For Market Incumbents: Secure backward integration into food-grade polymer formulation capacity to defend against specialist chemist scarcity. Accelerate multi-jurisdiction certification pipelines to compress launch timelines against emerging design-forward competitors. Channel control through exclusive corporate wellness contracts represents a critical defensive lever. For New Entrants and Emerging Players: Anchor in German institutional cafeteria outsourcing contracts where incumbent penetration remains shallow. Target connected-lunchbox segments integrating IoT temperature monitoring as the most penetrable white-space. A direct-to-corporate sales model bypasses retail slotting barriers that protect established brands. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-engineered thermal specialists with compliance certification depth. Long-term viability over the next decade rests on regulatory alignment capabilities rather than volume scale alone. Watch for inflection signals in employer-sponsored meal-prep subsidy expansion across United States metropolitan corridors.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Acceleration | Fast-tracked ECHA approvals unlock premium-tier European market access before competitors complete reformulation cycles. |
| IoT Sensor Integration Partnership | Collaboration with semiconductor specialists enables smart temperature monitoring features for executive meal programs. |
| Corporate Wellness Channel Expansion | Direct B2B contracts with United States employers bypass retail margin compression and secure recurring revenue streams. |
| East Asian Manufacturing Footprint Consolidation | Concentrated production in Osaka and Nagoya clusters captures METI circular-economy standards for export markets. |
| Sustainability Repositioning | EU Green Deal-aligned material disclosures attract German and French consumer willingness-to-pay premiums. |
Research Methodology
Cross-validation between primary interviews with supply chain directors and secondary customs data anchors the qualitative findings. Product development leads at thermal engineering specialists, procurement managers at corporate foodservice operators, regulatory affairs directors at housewares conglomerates, and category buyers at mass-market retailers provided operational perspective. Secondary sources include FDA food-contact guidance documents, ECHA REACH restriction updates, METI circular-economy white papers, and retail audit databases. Bottom-up demand modeling and top-down macroeconomic triangulation ensure consistency across estimation approaches.
Sensitivity analysis across petrochemical price scenarios and regulatory timeline variations stress-tests projection robustness. Segmentation dimensions span product type, material composition, end-user archetype, and design positioning across the modeling period. CAGRs derive from curve-fitting historical shipment patterns against adoption rate assumptions. Industry-specific inputs incorporate thermal performance certification friction costs and institutional procurement cycle lengths.
Underlying assumptions cover sustained workplace return patterns and stable REACH enforcement intensity, with deviation risk concentrated in petrochemical price volatility and multi-jurisdiction approval delays. Recalibration cycles align with material shifts in regulatory disclosure requirements and corporate wellness program expansion trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Carry Bag Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Slider Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market