
 Lay Flat Bags Market | 2026-2036
Lay Flat Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Lay Flat Bags Market Foresight
Modular sizing configurations are recalibrating buyer choice across the lay flat bags sector, as fulfillment operations demand interchangeable formats that reduce warehouse SKU complexity. Constantia Flexibles leverages its European manufacturing footprint to supply standardized modular dimensions to major retail chains. Poly Pak Plastics anchors its position through deep specialization in custom polyethylene formulations for protective shipping applications.
Lay flat bags are flexible, two-dimensional pouches manufactured from extruded film substrates, typically ranging from 1.5 to 6 mil in thickness, designed to collapse into a flat profile for efficient storage and low-cost distribution. Polyethylene dominates material type selection due to its cost-efficiency and heat-seal compatibility, though polyester is gaining traction in electronics end use where puncture resistance commands premium positioning. Ziplock closure formats are expanding fastest among e-commerce end users seeking reusable return pathways, while heat seal configurations retain margin strength in food industry applications requiring hermetic barrier properties.
REACH compliance through ECHA governs chemical content in European-sourced films, while FDA regulations under 21 CFR 177.1520 dictate polyethylene purity standards for food-contact lay flat bags in the United States. These frameworks elevate testing costs for multi-market suppliers but simultaneously lock out non-compliant imports, tightening competitive access. Stakeholders must track evolving extended producer responsibility schemes to anticipate which closure and material combinations will retain channel eligibility.
Market Dynamics
E-commerce fulfillment networks are compressing packaging specifications toward lighter, standardized formats that cut dimensional weight charges and warehouse handling costs. This structural pull is forcing film converters to abandon legacy thickness gradients in favor of modular dimension sets that slot directly into automated polybagging lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightened recyclability mandates are accelerating substitution of rigid mailers with compliant flexible films in German and French distribution centers.
- Ziplock closure technology:Reusable return pathways are expanding fastest among apparel e-commerce platforms seeking to reduce return shipping friction and customer service touchpoints.
- Polyethylene heat-seal compatibility:Cost-efficient hermetic barrier properties are sustaining demand from food industry applications requiring extended shelf stability.
Market Restraints
- Resin price volatility:Ethylene feedstock fluctuations squeeze converter margins and complicate long-term contract pricing with fulfillment clients.
- European supply concentration:Extrusion capacity clusters in Germany and Benelux create geographic vulnerability to energy cost spikes and logistics disruptions.
- Mechanical recycling contamination:Multi-layer barrier films face technical limitations in standard reprocessing streams, threatening circular economy claims.
Strategic Opportunities
- Indian e-commerce expansion:Underpenetrated fulfillment infrastructure in tier-2 cities creates white space for lightweight polybag adoption as logistics networks mature.
- Post-consumer recycled content mandates:California's SB 54 and similar state-level extended producer responsibility schemes will force brand owners to source certified recycled polyethylene films.
- RFID-embedded film integration:Convergence of inventory tracking technology with flexible packaging enables real-time shipment visibility for high-value electronics shippers.
Industry Challenges
- Extrusion die engineering talent:Specialized knowledge in multi-layer coextrusion is scarce as veteran technicians retire without sufficient apprenticeship pipeline replacement.
- Migration testing protocols:REACH compliance through ECHA demands extended certification timelines for new additive formulations, delaying product launches by 8-14 months.
- Legacy warehouse management system integration:Automated bagging lines require API connectivity with existing WMS platforms that many mid-tier 3PLs have not modernized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lay Flat Bags Market |
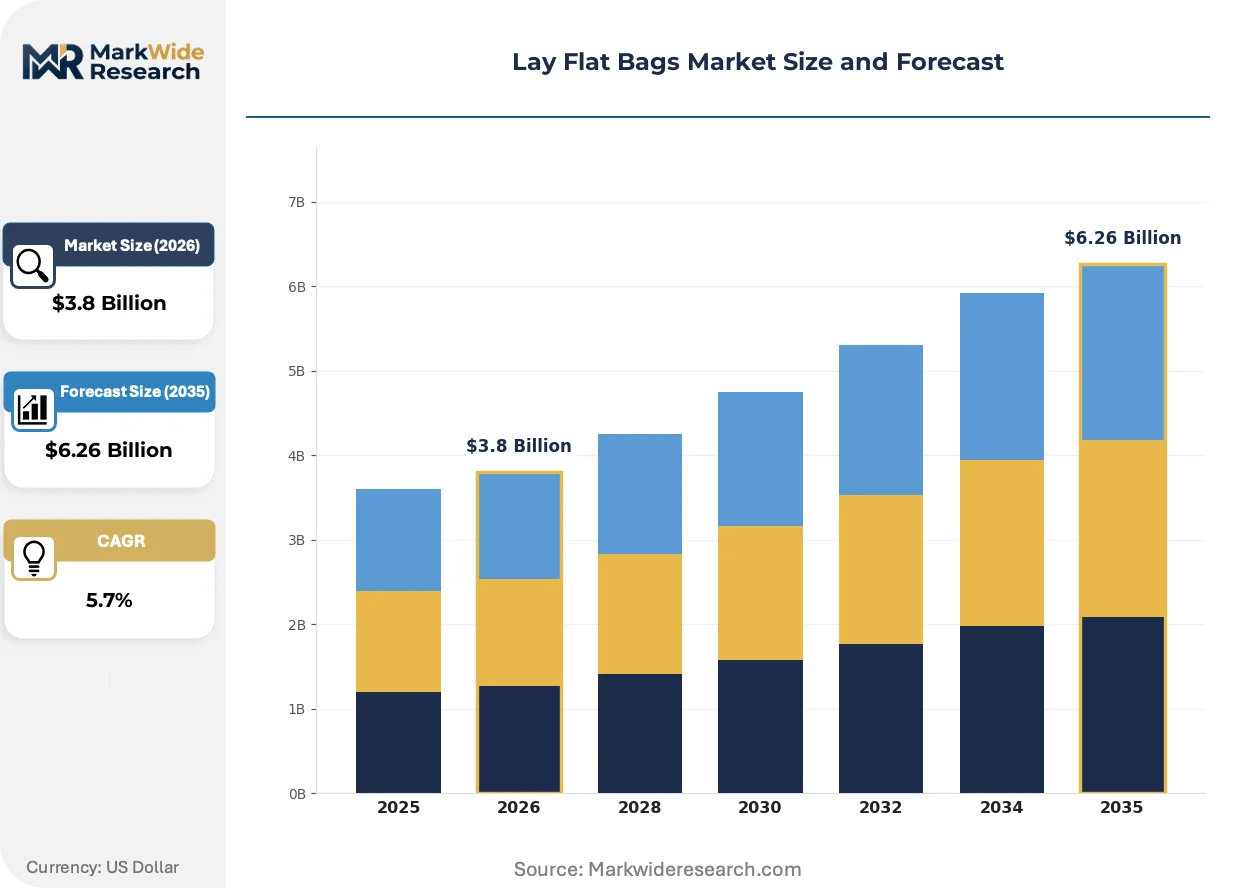
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyester, Paper Closure Type: Ziplock, Heat Seal, Open End, Adhesive End User: Retailers, E-commerce, Food Industry, Electronics Size: Small, Medium, Large, Custom |
| Companies Covered | CarePac, Poly Pak Plastics, Constantia Flexibles, Bison Bag, A-Pac Manufacturing, Printpack, Baishen Pack, Scientex, ShieldPro Flexible, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lay Flat Bags Market Shifts & Advancements
Film substrate engineering and closure mechanism design are converging to produce packaging formats that simultaneously satisfy automation compatibility, regulatory recyclability, and end-user reusability demands. These simultaneous pressures are compressing the viable design space for commodity converters.
Mono-material polyethylene structures are consolidating technical development across European and North American extrusion houses. Electronics manufacturers and premium apparel brands are adopting these simplified substrates at accelerating pace to preempt EPR sorting requirements. The shift is consolidating competitive position around converters with in-house recycling and reprocessing capabilities, marginalizing multi-layer specialists without closed-loop infrastructure.
REACH authorization procedures through ECHA are tightening scrutiny of slip agents and anti-static additives in food-contact films. Industrial consequence includes reformulation costs and supplier qualification delays for converters serving dual food and non-food end uses. Food industry buyers are responding by consolidating supplier bases toward integrated compounders with dedicated regulatory affairs functions.
Buyers are compressing specification cycles from annual to quarterly reviews as e-commerce peak seasons demand rapid format adjustments. Direct-to-brand procurement models are displacing traditional distributor relationships in North American and Western European markets. This behavioral shift is most visible in German retail consolidation, where centralized packaging engineering teams now mandate direct mill relationships for standardized bag formats.
Lay Flat Bags Market Segmentation
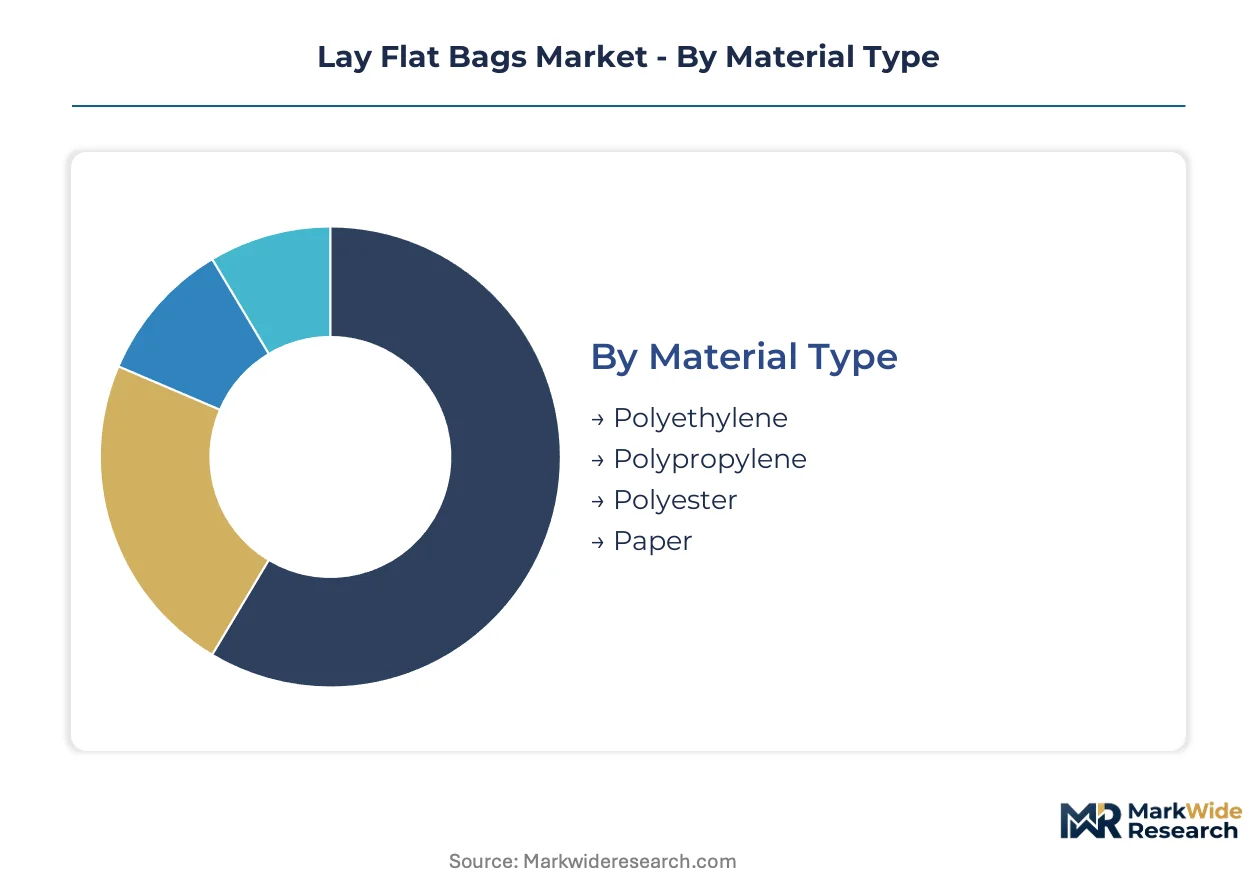
Lay flat bag procurement decisions cascade through material chemistry, closure mechanics, and dimensional specifications. Each segmentation axis carries distinct margin profiles and automation compatibility requirements that reshape supplier selection criteria.
Material Type:
Polyethylene formulations dominate standalone shipping applications where cost minimization outweighs barrier performance. Polyester and paper substrates embed into premium product protection systems requiring puncture resistance or sustainability credentials.
- Polyethylene:Extruded low-density and linear low-density films provide heat-seal compatibility and dimensional stability at sub-3-mil gauges. E-commerce fulfillment centers in Germany and France specify polyethylene lay flat bags to meet EU Packaging and Packaging Waste Regulation recyclability thresholds while cutting dimensional weight charges.
- Polypropylene:Oriented cast films deliver higher clarity and stiffness than polyethylene alternatives, supporting retail display applications where bag aesthetics influence shelf impact. Electronics manufacturers specify polypropylene for anti-static additive compatibility in semiconductor shipping.
- Polyester:Superior tensile strength and puncture resistance command premium positioning in high-value electronics protection.
- Paper:Kraft and glassine substrates serve sustainability-focused apparel brands seeking plastic-free packaging certifications.
Volume placements concentrate in Polyethylene; the faster expansion belongs to Paper.
Closure Type:
Closure selection determines reusability economics and automation throughput. Ziplock mechanisms add per-unit cost but enable return logistics; heat seal configurations maximize line speed in high-volume food operations.
- Ziplock:Interlocking polyethylene tracks create reusable pathways that reduce return shipping friction for apparel e-commerce platforms. Ziplock adoption accelerates among direct-to-consumer brands seeking to consolidate customer service touchpoints through simplified return workflows.
- Heat Seal:Impulse and continuous band sealing deliver hermetic barrier properties required for extended shelf stability in food industry applications. Heat seal formats retain margin strength where FDA 21 CFR 177.1520 compliance elevates testing costs for alternative closure systems.
- Open End:Uncapped tubes minimize material cost in bulk textile shipping where temporary containment suffices.
- Adhesive:Pressure-sensitive strips enable tamper-evident sealing for pharmaceutical and cosmetic distribution.
Procurement volumes favor Heat Seal configurations; Ziplock closures are climbing the fastest as return logistics expand.
End User:
End-use segmentation separates commodity volume buyers from specification-intensive niche purchasers. E-commerce networks drive standardization while electronics and food buyers impose material purity and barrier requirements.
- E-commerce:Automated polybagging lines demand modular dimension sets that slot directly into warehouse management systems. Fulfillment networks compress specifications toward lighter formats that cut handling costs across German and Benelux distribution centers.
- Food Industry:Hermetic barrier requirements and migration testing protocols under REACH authorization procedures extend certification timelines. Food industry buyers consolidate supplier bases toward integrated compounders with dedicated regulatory affairs functions.
- Retailers:Centralized packaging engineering teams mandate direct mill relationships for standardized bag formats.
- Electronics:Puncture resistance and anti-static specifications command premium material selection in semiconductor and device shipping.
Shipment volumes concentrate in E-commerce; the steepest expansion trajectory belongs to Electronics as high-value device distribution grows.
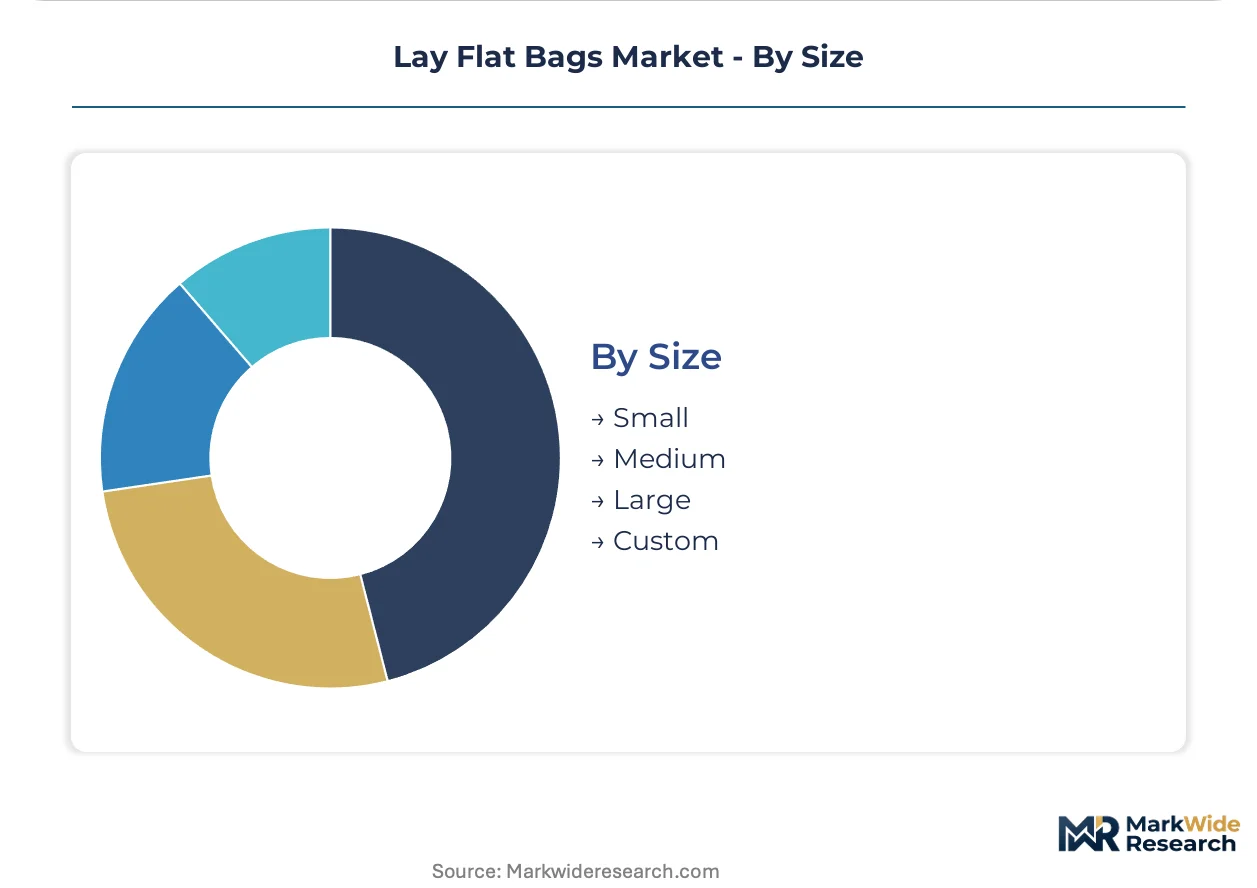
Size:
Size segmentation reflects warehouse SKU complexity trade-offs against dimensional weight optimization. Custom formats capture specification-intensive buyers while standard sizes enable inventory pooling.
- Custom:Tailored dimensions eliminate void fill requirements for irregular product geometries. German retail consolidation drives custom specification demand as centralized engineering teams optimize packaging for specific product categories.
- Medium:12x15 inch and 14x19 inch formats dominate apparel shipping with optimal postage tier positioning. Medium sizes gain share fastest as modular dimension sets replace legacy thickness gradients in automated fulfillment lines.
- Small:Compact formats serve jewelry, accessories, and component shipping with minimal material cost.
- Large:Extended dimensions accommodate bulk textile and soft-goods distribution with reduced per-unit handling.
Unit volumes concentrate in Medium sizes; Custom specifications are gaining share fastest as direct-to-brand procurement displaces distributor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity concentrates in Germany and Benelux while consumption spreads across fulfillment networks in France, the United Kingdom, and the United States. This geographic split shapes resin procurement patterns and regulatory compliance investments.
Germany
Fulfillment centers in the Rhine-Ruhr and Bavaria drive polyethylene lay flat bag consumption for apparel shipping. ECHA REACH compliance mandates dominate supplier qualification timelines. Extrusion clusters around Cologne and Düsseldorf supply modular dimension sets to major retail chains.
United States
E-commerce platforms in California and Texas compress specifications toward lighter formats that cut dimensional weight charges. FDA 21 CFR 177.1520 standards dictate polyethylene purity for food-contact applications. Automated polybagging lines in Chicago and Dallas-Fort Worth demand API-compatible bag formats.
France
Centralized packaging engineering teams in Paris and Lyon mandate direct mill relationships for standardized formats. EU Packaging and Packaging Waste Regulation recyclability thresholds accelerate substitution of rigid mailers. Distribution centers in Lille and Strasbourg specify mono-material polyethylene structures.
China
Export-oriented manufacturing in Guangdong and Zhejiang produces custom polyethylene formulations for protective shipping. GB standards govern film substrate specifications for domestic electronics end users. Yangtze River Delta converters supply puncture-resistant polyester variants for semiconductor distribution.
India
Underpenetrated fulfillment infrastructure in tier-2 cities creates white space for lightweight polybag adoption. BIS certification requirements extend product launch timelines for imported film substrates. Logistics networks in Maharashtra and Karnataka mature toward automated warehouse integration.
Lay Flat Bags Market Competitive Landscape
The competitive structure tilts toward integrated compounders with dedicated regulatory affairs functions. Film converters cluster around extrusion capacity in Germany and Benelux, with mid-tier specialists competing on custom formulation agility. Three archetypes dominate: European integrated compounders, North American automation-compatible specialists, and Asia-Pacific export-oriented fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure resin supply and fulfillment network access.
Among European integrated compounders, Constantia Flexibles exemplifies the regulatory-heavy archetype with its manufacturing footprint positioned for REACH compliance. Poly Pak Plastics occupies a position within the North American specialization tier, representing deep focus on custom polyethylene formulations. CarePac anchors the premium-service segment, sitting within the direct-to-brand procurement model that displaces traditional distributor relationships.
| Leading Market Players |
|---|
| CarePac |
| Poly Pak Plastics |
| Constantia Flexibles |
| Bison Bag |
| A-Pac Manufacturing |
| Printpack |
| Baishen Pack |
| Scientex |
| ShieldPro Flexible |
| Others |
Supply & Pricing Matrix
German retail consolidation toward centralized packaging engineering teams is forcing extrusion houses to absorb REACH compliance costs directly, compressing margin structures for converters without integrated regulatory affairs functions while elevating pricing power among compliant integrated compounders.
Pricing Analysis
Cost compression in standard polyethylene formats reflects ethylene feedstock volatility and automated fulfillment line integration demands. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-contact films from industrial shipping grades and commodity open-end configurations. Price differentiation hinges on REACH migration testing completion and mono-material recyclability certification. E-commerce fulfillment centers exhibit highest price sensitivity due to dimensional weight optimization mandates, while food industry buyers accept premium positioning for hermetic barrier performance.
Supply Chain Analysis
Return logistics flows through ziplock-enabled reusable pathways are reshaping downstream distribution economics as apparel e-commerce platforms consolidate customer service touchpoints. Extrusion capacity clusters in Germany, Belgium, and the Netherlands, drawing from Saudi and US Gulf Coast ethylene feedstock. Raw material dependencies rest on linear low-density polyethylene resin, anti-static additive compounds, and interlocking closure track components. Single-source vulnerability concentrates around Cologne-Düsseldorf extrusion clusters exposed to energy cost spikes. Distribution runs through direct mill relationships displacing traditional distributor networks in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lay Flat Bags Market functions as a cost-of-compliance story where ECHA REACH authorization procedures create barrier-to-entry moats favoring integrated compounders with dedicated regulatory affairs capabilities over commodity converters.
For Market Incumbents: Anticipate margin compression from mono-material polyethylene standardization by securing backward integration into post-consumer recycled content streams. Defensive positioning requires captive recycling infrastructure to meet California SB 54 mandates and EU extended producer responsibility schemes. Capacity consolidation around Benelux extrusion clusters mitigates logistics disruption exposure while locking in major retail chain direct mill relationships. For New Entrants and Emerging Players: Tier-2 Indian e-commerce fulfillment infrastructure presents accessible white space as logistics networks mature toward automated warehouse integration. Specialty electronics protection films with anti-static additive compatibility command premium positioning with limited incumbent saturation. Go-to-market execution should anchor on BIS certification partnerships to compress product launch timelines against imported substrate competitors. For Investors and Strategic Acquirers: Re-rating potential sits with European integrated compounders given REACH compliance moat expansion and food industry buyer consolidation toward qualified supplier bases. Long-term viability favors converters with closed-loop recycling infrastructure over multi-layer barrier specialists facing mechanical recycling contamination limitations. Monitor EPR scheme implementation timelines across German federal states as inflection indicators for recyclability-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Recycling | California SB 54 compliance secures brand owner offtake agreements ahead of mandate deadlines. |
| Mono-Material Polyethylene Transition | Eu Packaging and Packaging Waste Regulation recyclability thresholds displace multi-layer competitors without reprocessing infrastructure. |
| Direct Mill Relationship Establishment | German retail consolidation toward centralized engineering teams eliminates distributor margin capture. |
| RFID-Embedded Film Development | Real-time inventory tracking integration captures high-value electronics shipper specifications. |
| REACH Regulatory Affairs Function Buildout | Migration testing protocol expertise compresses additive formulation certification timelines by 8-14 months. |
Research Methodology
Document review covered trade association filings, customs records, and ECHA REACH authorization databases, complemented by interviews with film extrusion plant managers, e-commerce fulfillment procurement leads, retail packaging engineering directors, and food industry regulatory affairs specialists. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, FDA 21 CFR 177.1520 compliance guidelines, and resin producer pricing disclosures. Bottom-up shipment data triangulated against top-down consumption estimates across material type, closure mechanism, and end-use segmentation dimensions.
Cross-referencing historical capacity utilization patterns against expert panel input shaped the analytical framework across the analysis window. Modeled segmentation spanned material chemistry tiers, closure automation compatibility, dimensional specification categories, and geographic regulatory clusters. CAGRs derived from weighted average growth assumptions calibrated to e-commerce fulfillment network expansion rates and electronics distribution volume trajectories. Industry-specific inputs included extrusion die engineering talent availability and automated polybagging line API integration penetration.
Revisions become necessary when ethylene feedstock volatility exceeds modeled ranges, EPR scheme implementation accelerates beyond regulatory timelines, or mechanical recycling contamination breakthroughs disrupt mono-material competitive positioning. Practitioners should monitor REACH authorization backlog lengths, German energy cost trajectories, and Indian logistics automation adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Bag-In-Box Packaging Market