
 Shrink Bags Market | 2026-2036
Shrink Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Bags Market Analytics
REACH compliance is repositioning the cost-of-entry calculus for European suppliers of shrink bags used in food contact applications. Sealed Air Corporation leverages its Cryovac technology platform to dominate high-performance protein packaging specifications across North America. Amcor Plc sustains global scale through integrated film extrusion and conversion operations that span multiple polymer platforms. Mondi Group Plc anchors its competitive position with kraft-paper hybrid structures that navigate rising fiber-based packaging mandates in the EU.
Shrink bags are heat-shrinkable flexible containers, typically manufactured from polyolefin, PVC, or PET through biaxial orientation and irradiation cross-linking processes, designed to conform tightly to product contours for moisture barrier and tamper-evident protection in perishable goods distribution. Polyolefin shrink bags occupy the largest volume share due to balanced clarity, seal strength, and compatibility with high-speed form-fill-seal equipment across meat and poultry operations. PVC retains residual demand in consumer goods bundling where cost sensitivity outweighs regulatory pressure, while LDPE variants at 75 micron and 100 micron thickness specifications represent the fastest-growing configuration as processors optimize film yield against puncture resistance requirements.
The EU's Packaging and Packaging Waste Regulation, FDA food contact substance notifications, and ISO 9001 quality management standards collectively shape material approval timelines, migration testing protocols, and market access conditions for shrink bag suppliers competing in regulated end uses. ECHA substance restrictions on phthalate plasticizers in PVC formulations are forcing compound reformulation investments that favor polyolefin migration pathways. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability labeling mandates that will determine which polymer platforms retain cost-competitive positioning in European food packaging procurement.
Market Dynamics
Protein packaging automation in North American meat processing plants is compressing specification cycles for shrink bags, forcing suppliers to accelerate barrier film R&D while managing resin cost volatility.
Growth Catalysts
- High-barrier polyolefin formulations:Meat processors in the United States demand extended shelf-life performance for case-ready beef and pork distribution, driving specification upgrades from standard LDPE structures.
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are redirecting converter capital toward mono-material PE and PP platforms that simplify post-consumer sorting infrastructure.
- German meat processing automation:Industrial robot deployment in sausage and cured meat packaging lines requires shrink bags with precise dimensional stability for high-speed form-fill-seal compatibility.
Market Restraints
- Ethylene and propylene feedstock volatility:Crude oil price swings transmit directly to polyolefin resin contracts, compressing converter margins on fixed-price annual supply agreements.
- Chinese film extrusion capacity concentration:Low-cost biaxial orientation lines in Shandong and Zhejiang provinces flood export markets with commodity-grade shrink film, eroding pricing power for regional European suppliers.
- Phthalate restrictions under REACH:ECHA substance evaluations force PVC compound reformulation, eliminating cost advantages for legacy plasticizer systems in food contact applications.
Strategic Opportunities
- India cold chain infrastructure expansion:FSSAI-mandated food safety modernization in poultry and seafood distribution creates first-mover advantage for high-barrier shrink bag specifications in Mumbai and Chennai processing clusters.
- Paper-film hybrid structures:Mondi Group's kraft-paper laminate innovations align with EU fiber-based packaging mandates, opening premium positioning in retail-ready meat cases.
- Blockchain-enabled traceability integration:Smart packaging layers that combine shrink barrier function with serialized authentication respond to retailer demands for farm-to-fork visibility in North American protein supply chains.
Industry Challenges
- Migration testing protocol complexity:FDA food contact substance notifications and EFSA compliance timelines extend product approval cycles to 18-24 months, delaying revenue recognition for novel barrier coatings.
- Irradiation cross-linking technician scarcity:Specialized electron beam and gamma radiation process engineers command premium compensation, constraining capacity expansion at mid-scale conversion facilities.
- Legacy PVC line retrofit requirements:Converters seeking polyolefin migration face capital-intensive extruder die and cooling system modifications that strain balance sheets during interest rate elevation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Bags Market |
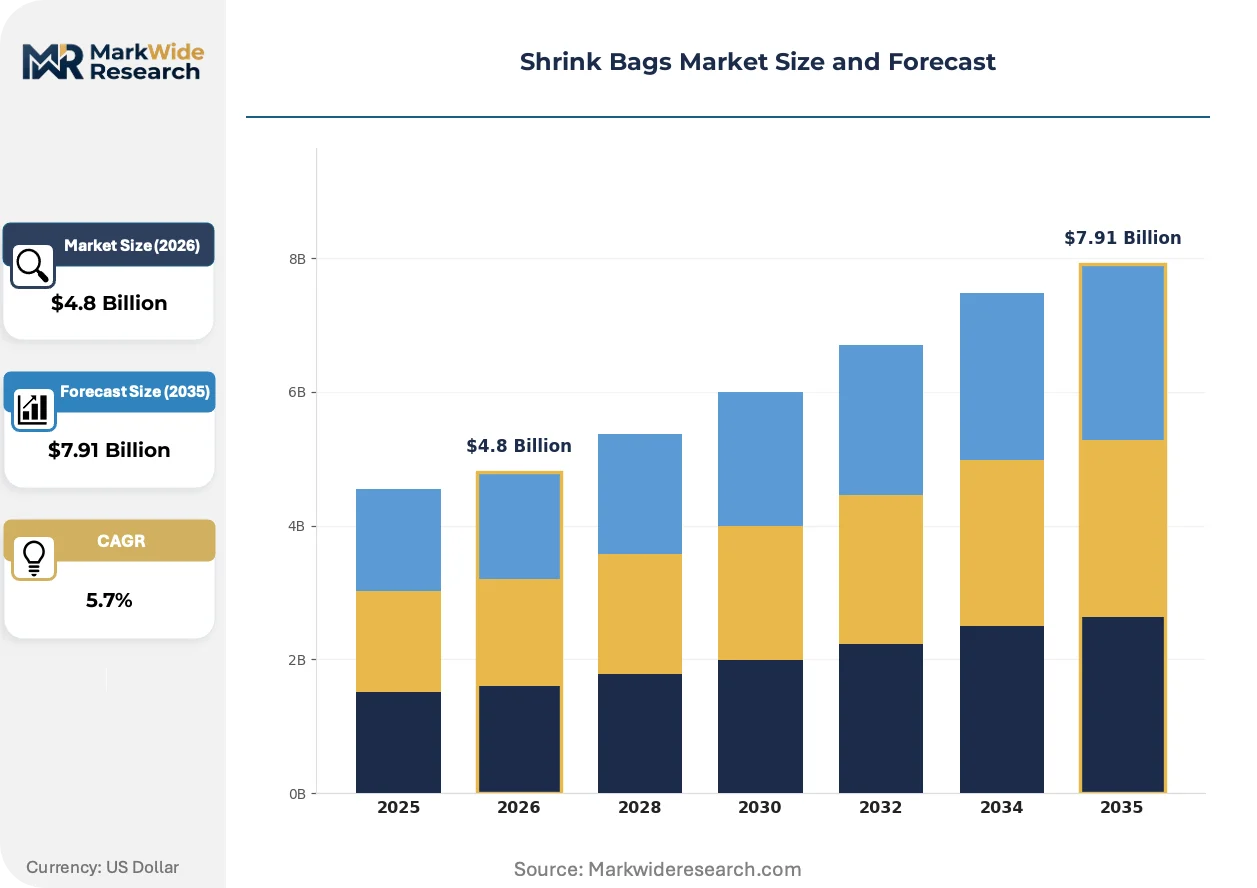
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, PET, LDPE End User: Food Packaging, Pharmaceuticals, Consumer Goods, Electronics Thickness: 50 Micron, 75 Micron, 100 Micron, 125 Micron Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Sealed Air Corporation, Amcor Plc, Bemis Company Inc., Berry Global Inc., Coveris Holdings, Winpak Ltd., Kureha Corporation, Mondi Group Plc, Clondalkin Group Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Bags Market Evolving Landscape
Active and intelligent packaging layers are penetrating protein preservation applications, while regulatory pressure on recyclability compresses acceptable material portfolios and automation demands reshape dimensional tolerance specifications.
Bio-based barrier coatings derived from cellulose nanocrystals are converging with conventional polyolefin substrates to maintain oxygen transmission rates below 5 cc/m²/day. North American premium beef processors are piloting these structures for dry-aging applications. The technology is converging with high-value protein segments that justify 15-20% film cost premiums for extended color stability.
REACH authorization requirements for substances of very high concern are eliminating certain slip and anti-fog additives from EU food contact formulations. Compounders must qualify replacement chemistries through EFSA migration testing. Small and mid-size converters in Poland and Romania face disproportionate compliance burdens relative to integrated multinational suppliers.
Direct procurement relationships between protein processors and film converters are displacing distributor intermediaries in North American poultry packaging. Tyson Foods and JBS USA have established captive supply agreements with extrusion specialists for 75-micron LDPE specifications. This consolidation concentrates volume with three to four approved suppliers per processing plant, marginalizing regional converters without backward resin integration.
Shrink Bags Market Segmentation
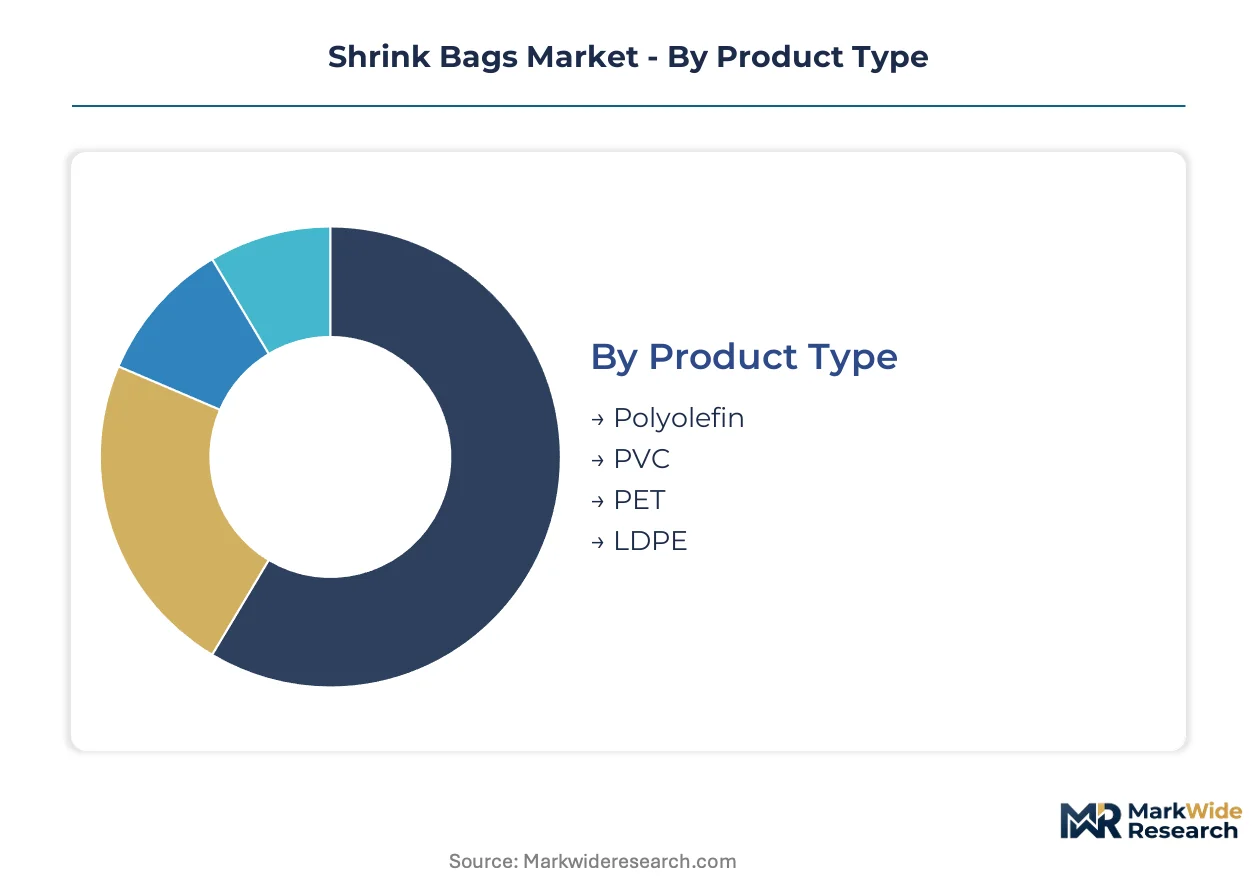
Shrink bag procurement decisions hinge on barrier performance, equipment compatibility, and regulatory compliance across distinct material platforms and end-use environments. Segmentation reveals how protein processors, pharmaceutical packagers, and consumer goods distributors prioritize divergent specifications.
Product Type:
Material selection determines barrier properties, seal integrity, and recyclability pathways in automated packaging lines.
- Polyolefin:Biaxially oriented multilayer structures deliver balanced oxygen transmission rates and puncture resistance for high-speed meat and poultry operations. Demand concentrates in U.S. beef processing plants upgrading from standard LDPE to extended shelf-life specifications.
- PVC:Legacy formulations retain cost-sensitive applications in consumer goods bundling where clarity and low-temperature shrink performance outweigh regulatory pressure. REACH phthalate restrictions are forcing compound reformulation investments that erode historical cost advantages.
- PET:High-clarity structures serve premium retail-ready meat cases requiring optical inspection compatibility.
- LDPE:Single-layer and coextruded variants dominate commodity protein packaging with 75-micron and 100-micron specifications gaining traction for yield optimization.
Volume sits with polyolefin; growth tilts toward LDPE as processors balance puncture resistance against resin yield targets.
End User:
Application-specific barrier requirements and regulatory exposure reshape converter R&D allocation across customer verticals.
- Food Packaging:Protein preservation applications in beef, pork, and poultry distribution demand oxygen barriers below 5 cc/m²/day. German sausage processing automation is driving dimensional stability specifications for form-fill-seal compatibility.
- Pharmaceuticals:Medical device and diagnostic kit applications require validated sterilization compatibility and lot traceability.
- Consumer Goods:Multi-pack bundling of household products prioritizes cost-per-unit and printability over barrier performance.
- Electronics:Static-dissipative formulations protect sensitive components during distribution.
Food packaging commands the installed base; pharmaceuticals show the steepest expansion trajectory as serialization mandates proliferate.
Thickness:
Film gauge selection reflects the trade-off between material yield, puncture resistance, and equipment throughput.
- 75 Micron:Mid-gauge specifications are displacing 50-micron alternatives in North American poultry packaging as processors optimize film yield without sacrificing bone-puncture resistance.
- 100 Micron:Heavy-duty structures serve bone-in meat cuts and export shipments requiring enhanced abuse resistance.
- 50 Micron:Thin-gauge films retain processed meat and sliced deli applications where product geometry is uniform.
- 125 Micron:Maximum-gauge specifications address frozen protein distribution and sharp-edged industrial components.
75-micron specifications anchor current volume; 100-micron grades are climbing the fastest as export-oriented processors upgrade abuse resistance.
Distribution Channel:
Channel structure determines technical support intensity, inventory positioning, and pricing transparency for converter-customer relationships.
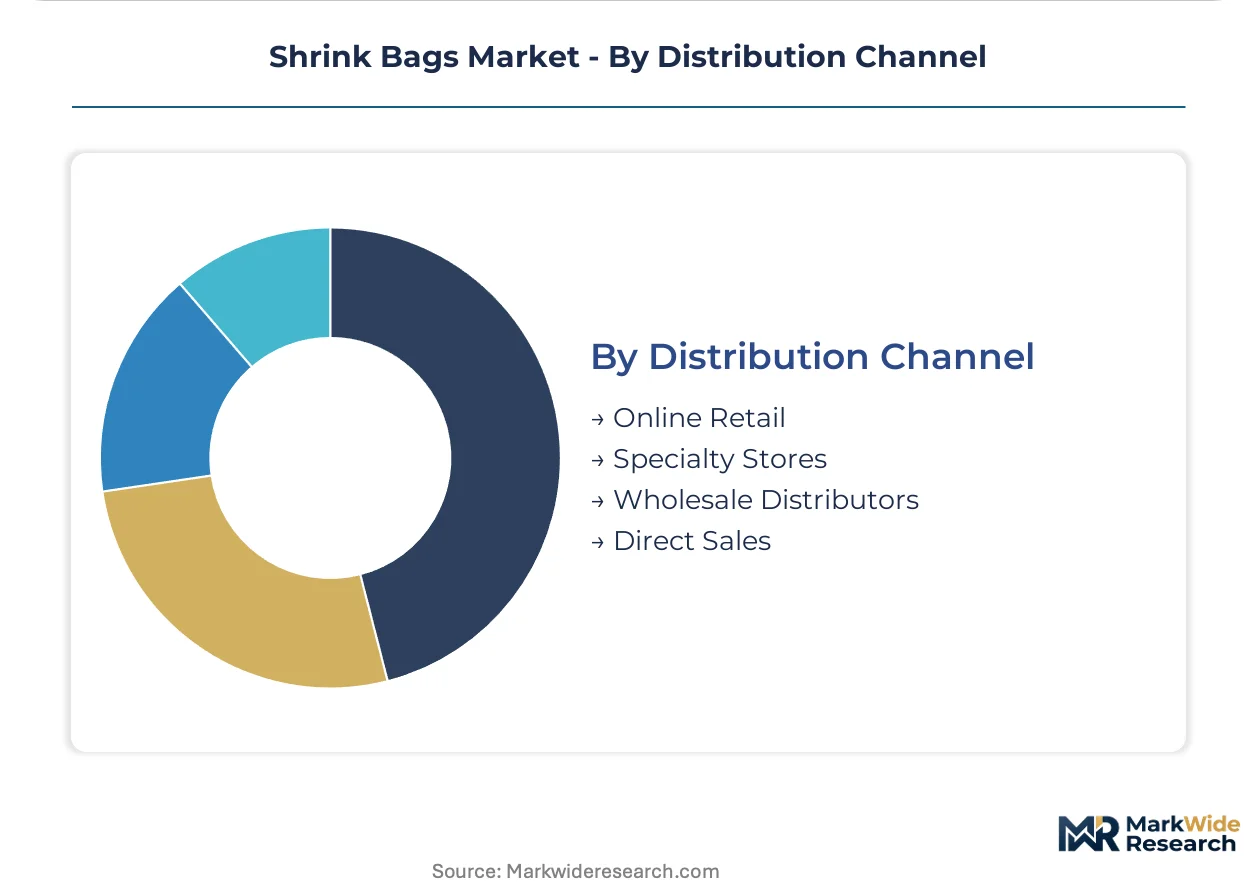
- Direct Sales:Tyson Foods and JBS USA have established captive supply agreements with extrusion specialists, displacing distributor intermediaries and concentrating volume with approved suppliers per processing plant.
- Wholesale Distributors:Regional converters rely on film distributors for resin procurement and logistics in fragmented European markets.
- Specialty Stores:Small-batch and custom-printed specifications serve craft meat processors and artisanal food producers.
- Online Retail:E-commerce platforms are emerging for standardized industrial shrink film specifications in maintenance-repair-operations procurement.
Direct sales capture the largest share; online retail is gaining traction fastest among small and mid-size processors seeking price transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Thailand and Vietnam are concentrating new extrusion capacity for export-oriented shrink bag production, while North American protein processors drive specification upgrades through captive supply agreements with film converters.
United States
Beef and poultry processors in Nebraska and Iowa are accelerating purchases of high-barrier polyolefin structures for case-ready meat distribution. FDA food contact substance notifications govern migration testing protocols for new barrier coatings. Tyson Foods and JBS USA have established direct procurement relationships with extrusion specialists in the Midwest, displacing traditional distributor channels.
Germany
Industrial robot deployment in sausage and cured meat packaging lines demands shrink bags with precise dimensional stability for high-speed form-fill-seal compatibility. ECHA substance restrictions under REACH are forcing compound reformulation investments that favor polyolefin migration pathways. Meat processing clusters in Bavaria and Lower Saxony are upgrading specifications as automation penetration exceeds 60 percent in large facilities.
China
Low-cost biaxial orientation lines in Shandong and Zhejiang provinces flood export markets with commodity-grade shrink film, eroding pricing power for regional European suppliers. GB standards for food contact materials establish migration limits that domestic converters must meet for domestic distribution. The Yangtze River Delta hosts the highest concentration of film extrusion capacity serving both domestic protein processors and export markets.
India
FSSAI-mandated food safety modernization in poultry and seafood distribution creates first-mover advantage for high-barrier shrink bag specifications. The Production Linked Incentive scheme for food processing infrastructure is accelerating cold chain investments. Mumbai and Chennai processing clusters are upgrading from basic LDPE to multilayer barrier structures as modern retail penetration expands.
Brazil
Beef export processors in São Paulo and Mato Grosso are adopting 100-micron specifications for abuse resistance in ocean freight distribution. ANVISA food contact regulations align with Mercosur standards for migration testing. The São Paulo state meatpacking corridor is consolidating procurement with approved suppliers capable of lot traceability and blockchain-enabled documentation.
Shrink Bags Market Competitive Landscape
North American producers anchor one tier with integrated resin-to-film operations; European specialists hold another through mono-material recyclability platforms. The vendor base separates into three strata: multinational converters with captive extrusion, regional specialists serving single-country markets, and commodity traders importing standardized specifications from Asia. Strategic archetypes include barrier technology leaders, sustainability-focused mono-material innovators, and low-cost volume suppliers. Consolidation through backward integration into resin compounding and geographic expansion through distributor acquisition represent the dominant competitive moves.
Within the multinational converter tier, Sealed Air Corporation and Amcor Plc exemplify scale-driven positioning through integrated film extrusion and conversion operations spanning multiple polymer platforms. Mondi Group Plc occupies a distinct position representing the fiber-based hybrid archetype with kraft-paper laminate structures that navigate rising EU mandates for recyclable packaging materials. These three entities collectively illustrate how competitive positioning diverges across barrier performance, sustainability credentials, and vertical integration depth.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor Plc |
| Bemis Company Inc. |
| Berry Global Inc. |
| Coveris Holdings |
| Winpak Ltd. |
| Kureha Corporation |
| Mondi Group Plc |
| Clondalkin Group Holdings |
| Others |
Value Network & Pricing Analysis
Irradiation cross-linking technician scarcity in the Midwestern United States and Bavaria generates labor-cost differentials that widen pricing-tier spreads between premium barrier specifications and commodity-grade alternatives. These specialized electron beam and gamma radiation process engineers command premium compensation that converters pass through to protein processors or absorb through margin compression.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with processors paying premiums for sub-72-hour delivery windows while spot inventory commands discounts from converters clearing excess film stock. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated high-barrier structures from generic LDPE specifications and imported commodity film. Price differentiation rests on certification grade and volume scale, with annual offtake agreements above 500-ton thresholds unlocking standard-tier access. Pricing pressure stems from Chinese film extrusion capacity flooding export markets, eroding regional European supplier margins. Small-batch artisanal meat processors exhibit highest price sensitivity, while Tyson Foods and JBS USA demonstrate lowest sensitivity through captive supply arrangements.
Supply Chain Analysis
Certification and qualification gating through FDA food contact substance notifications and EFSA compliance timelines restricts supplier pools to pre-approved converters with validated migration testing protocols. Geographic supply concentration centers on the United States, Germany, and China, with the Yangtze River Delta hosting the highest film extrusion density. Raw material dependencies draw from ethylene and propylene feedstocks, cellulose nanocrystal bio-barrier coatings, and kraft-paper laminate substrates. Supply chain risk hinges on single-source vulnerability for irradiation cross-linking equipment manufacturers. Distribution runs through direct sales channels displacing wholesale intermediaries in North American poultry packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shrink bags market operates as a vertical-integration race where converters pursue backward control over resin compounding to defend margin structures against feedstock volatility and qualification timeline compression.
For Market Incumbents: Deploy captive extrusion capacity additions in Nebraska and Iowa to lock in Tyson Foods and JBS USA procurement relationships before regional competitors achieve FDA validation. Accelerate mono-material PE platform R&D to preempt EU Packaging and Packaging Waste Regulation compliance deadlines that will disqualify multilayer structures from extended producer responsibility fee advantages. Threat substitution from paper-film hybrid structures demands barrier performance parity investments. For New Entrants and Emerging Players: Premium-to-economy tier price-point gaps exceeding 15-20% in Indian poultry processing create entry windows for mid-barrier specifications that balance FSSAI compliance with cost positioning below multinational converter rates. Target Mumbai and Chennai cold chain infrastructure clusters where modern retail penetration is accelerating specification upgrades from basic LDPE. Go-to-market angle should emphasize 75-micron gauge optimization with localized technical service support. For Investors and Strategic Acquirers: Re-rating potential sits with mono-material recyclability specialists given EU regulatory catalysts that will redirect procurement toward simplified post-consumer sorting infrastructure. Long-term viability over the 5-10 year window favors converters with integrated film extrusion and validated barrier coating capabilities rather than commodity traders. Acquisition target archetype: mid-scale European specialists with REACH-compliant compound formulations and dormant capacity for electron beam expansion. Signal to watch is ECHA substance restriction announcements that accelerate PVC-to-polyolefin migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene supply hedges against crude-linked contract volatility for Midwestern converters. |
| Mono-Material Platform Certification | EU recyclability mandates redirect R&D spending toward PE and PP structures that simplify sorting infrastructure. |
| Irradiation Cross-Linking Capacity Expansion | Electron beam line additions address technician scarcity constraining mid-scale facility growth. |
| Direct Procurement Relationship Establishment | Tyson Foods and JBS USA captive agreements displace distributor intermediaries and concentrate volume. |
| Bio-Based Barrier Coating Development | Cellulose nanocrystal formulations target premium beef dry-aging applications with 15-20% film cost premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with film extrusion plant managers, protein processor procurement leads, distribution channel partners, and technical R&D directors at barrier coating compounders. Secondary validation drew from FDA food contact substance notification databases, ECHA REACH restriction proposals, SEC 10-K disclosures from packaging converters, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up and top-down triangulation cross-checked volume estimates across polymer resin consumption data and end-use protein packaging demand.
Granularity-level framing modeled shrink bag demand at the material platform, thickness specification, end-use vertical, and regional production cluster dimensions across the analysis window. Segmentation dimensions included polyolefin versus PVC versus PET versus LDPE material splits, 50/75/100/125 micron gauge tiers, food packaging versus pharmaceutical versus consumer goods versus electronics end uses, and country-specific regulatory framework clusters. CAGRs were derived from trend extrapolation of protein processing automation rates and cold chain infrastructure investment trajectories. Industry-specific forecast inputs incorporated FSSAI modernization timelines in India and EU extended producer responsibility fee structure implementations.
Inputs from FDA notification databases and ECHA restriction evaluations were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around short-term pricing trajectory assumptions. Forecasts reflect assumptions regarding resin cost pass-through mechanisms and qualification timeline compression. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation implementation schedules or ECHA phthalate restriction enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Crates Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Padding Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Global Bubble Lined Courier Bag Market