
 4-Loop FIBC Market | 2026-2036
4-Loop FIBC Market Size, Share, and Industry Trends Forecast 2026-2036
4-Loop FIBC Market Outlook
ISO 21898 certification is reorganizing competitive access in the 4-Loop FIBC market, forcing smaller weavers to upgrade testing infrastructure or exit. Greif leverages captive resin sourcing and North American plant networks to sustain margin stability. LC Packaging anchors European supply through its Netherlands-based production and circular-service models. Alpine FIBC competes on conductive-fabric specialization for chemical-sector buyers.
4-Loop FIBCs are woven polypropylene bulk containers with four corner lifting loops, typically rated for one-tonne payloads and designed for mechanized handling via forklift or crane in granular material logistics. The fabric weight, UV-stabilization grade, and loop tensile strength determine duty-cycle performance across fill-empty-transport cycles. Standard FIBCs dominate volume but carry thin margins, while conductive and anti-static variants command premium positioning in chemicals and food-grade segments where electrostatic discharge and contamination risks gate procurement. Polypropylene remains the structural backbone of the category, though recycled-content grades are gaining specification traction among sustainability-focused end users.
REACH and the EU Green Deal shape material compliance obligations for European producers, while FDA food-contact regulations govern U.S. shipments into food and beverage channels. ECHA substance restrictions and emerging extended-producer-responsibility frameworks are raising reformulation costs for virgin resin formulations. Stakeholders must monitor how regional recycling mandates and loop-fabric durability standards evolve, as these will determine which production footprints and material certifications retain commercial viability.
Market Dynamics
REACH compliance and the EU Green Deal are compressing margins for virgin polypropylene formulations while rewarding producers with verified recycled-content supply chains and closed-loop recovery infrastructure.
Growth Catalysts
- EU Green Deal circularity mandates:Extended producer responsibility frameworks in Germany and the Netherlands now require minimum recycled-content thresholds for industrial packaging, pulling demand toward certified circular FIBC suppliers.
- Port of Rotterdam logistics hub expansion:Bulk chemical throughput at Europe's largest seaport is mechanizing handling protocols, standardizing four-loop lift configurations for automated crane operations.
- Anti-static fabric innovation:Conductive yarn integration is opening specification gates in fine-chemical and pharmaceutical logistics where electrostatic discharge risks previously excluded woven polypropylene containers.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and regional refinery output swings transmit directly to woven fabric production costs, compressing converter margins on standard-duty FIBCs.
- Testing infrastructure concentration:ISO 21898 certification capacity clusters in Germany and Belgium, forcing distant weavers to absorb freight costs for sample validation or defer market entry.
- Flexible intermediate bulk container rental pooling:Reusable rigid IBC systems are capturing share in closed-loop chemical plant operations where transport distances justify return logistics.
Strategic Opportunities
- Food-contact certification gap:EFSA-compliant fabric weaving capacity remains underdeveloped in Eastern Europe, creating first-mover positioning for producers achieving migration-tested polypropylene grades.
- Carbon border adjustment mechanism preparation:CBAM phase-in from 2026 is incentivizing EU-based converters to document scope-three emissions, rewarding local production footprints with compliance-ready supply chains.
- Digital product passport integration:QR-code traceability embedded in loop tags is enabling batch-level recycling documentation, differentiating suppliers to sustainability procurement teams at multinational chemical groups.
Industry Challenges
- Masterbatch formulation expertise:UV stabilization and anti-static additive blending requires polymer science capabilities scarce among traditional textile weavers transitioning into technical fabric production.
- ISO 21898 testing timeline compression:Cyclic top-lift and drop-test validation cycles extend six to eight weeks, delaying customer qualification and locking working capital in finished goods inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4-Loop FIBC Market |
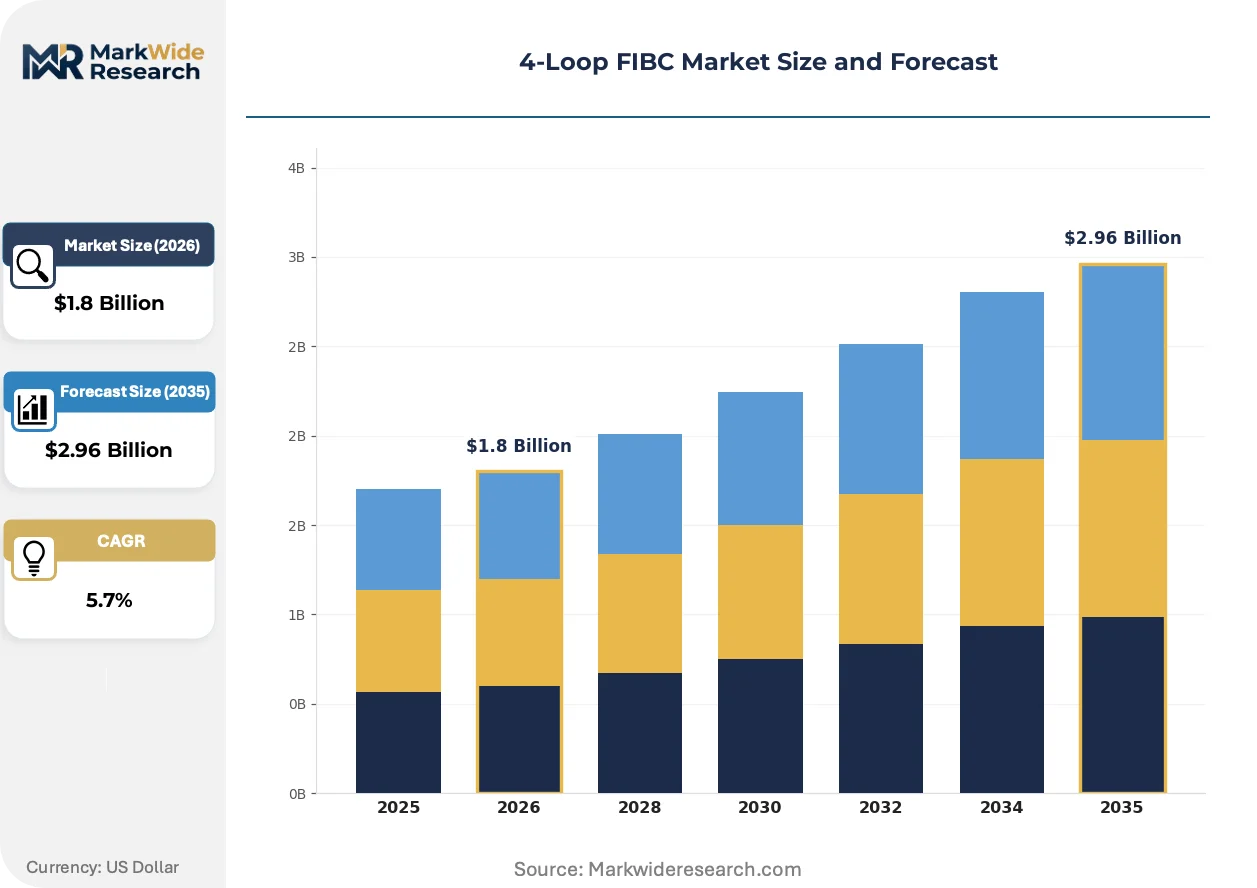
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard FIBC, Conductive FIBC, Super Sack, Anti-Static FIBC End User: Agriculture, Chemicals, Food & Beverage, Construction Material: Polypropylene, Polyester, Nylon, Jute Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Global-Pak, LC Packaging, Alpine FIBC, LARE FIBC, Muscat Polymers, Greif, BAG Corp, Umasree Texplast, Shalimar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Loop FIBC Market Strategic Shifts
Active material science and regulatory digitization are restructuring how FIBC producers compete on compliance velocity and circular proof points rather than unit cost alone.
Conductive tape yarn technology is miniaturizing electrostatic dissipation pathways within standard woven constructions, eliminating the weight and stiffness penalties of earlier carbon-filament grids. Specialty chemical distributors in the Rhine-Ruhr corridor are specifying these grades for solvent and powder handling where ATEX zones previously mandated rigid packaging. The technology is compressing the premium gap between standard and anti-static FIBC categories, forcing incumbent conductive specialists to defend positioning through faster certification turnaround.
REACH substance restriction updates through ECHA are tightening phthalate and heavy-metal thresholds in color masterbatches, compelling reformulation of UV-stabilized fabrics used in outdoor agricultural storage. German chemical processors are now requiring full material disclosure documentation upstream of purchase orders, shifting supplier evaluation criteria toward traceability systems rather than per-unit pricing. This regulatory friction is most acute in food-adjacent applications where EFSA migration limits overlap with industrial durability requirements.
Buyer consolidation among pan-European chemical distributors is consolidating purchase authority into centralized procurement functions with standardized technical specifications. Regional packaging distributors serving mid-sized compounders are losing specification influence as direct manufacturer relationships replace layered channel structures. This concentration is most visible in the Netherlands, where integrated logistics providers now bundle FIBC supply with warehousing and inventory management services, compressing standalone converter margins.
4-Loop FIBC Market Segmentation
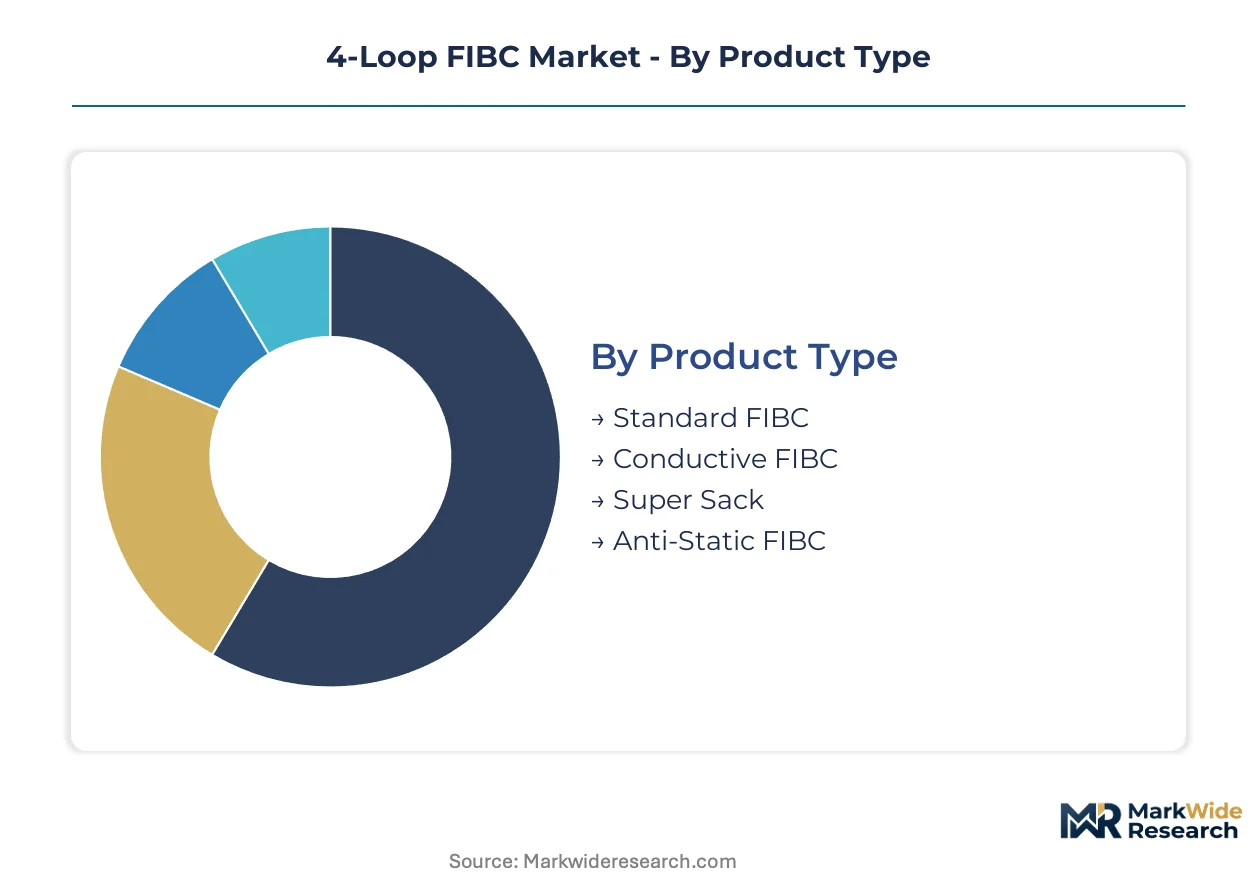
Segmentation in the 4-Loop FIBC market determines which production footprints and certification investments align with buyer procurement hierarchies. Chemical processors in Germany and the Netherlands route premium conductive grades through direct manufacturer relationships, while agricultural buyers in Eastern Europe rely on distributor networks for standard-duty volumes.
Product Type:
Channel mix varies sharply by hazard rating: conductive and anti-static variants flow through direct sales to REACH-compliant chemical processors, while standard FIBCs move through wholesale networks serving price-sensitive agricultural compounders.
- Standard FIBC:Woven polypropylene containers rated for one-tonne payloads without specialized hazard protection. Demand concentrates in Rhine-Ruhr agricultural distribution where UV-stabilized grades serve outdoor grain storage. Margin pressure from propylene feedstock volatility limits converter investment in testing infrastructure.
- Conductive FIBC:Fabric integrates carbon-filament or conductive tape yarn pathways to dissipate electrostatic charge in ATEX zones. Fine-chemical distributors in the Netherlands specify these for solvent handling where earlier rigid packaging dominated. REACH substance disclosure requirements now gate procurement approval.
- Super Sack:High-capacity variants exceeding standard one-tonne ratings for dense mineral and construction aggregate logistics.
- Anti-Static FIBC:Dissipative fabric grades for pharmaceutical powder handling where contamination control intersects with electrostatic risk.
By volume, Standard FIBC leads. By growth pace, Conductive FIBC is expanding most quickly.
End User:
Cost tier stratification separates premium-certified chemical and food-grade applications from economy agricultural and construction segments where per-unit pricing dominates procurement.
- Chemicals:Processors require ISO 21898 certification plus conductive or anti-static fabric grades for hazardous material handling. ECHA substance restrictions and ATEX zone compliance compress supplier qualification timelines. Rotterdam logistics hub expansion standardizes four-loop configurations for automated crane operations.
- Food & Beverage:EFSA migration-tested polypropylene and FDA food-contact certification govern fabric specification. German dairy and beverage processors now require full material disclosure documentation upstream of purchase orders. Recycled-content thresholds under EU Green Deal circularity mandates pull demand toward certified suppliers.
- Agriculture:Grain and fertilizer handling drives volume through distributor channels serving mid-sized compounders in Poland and Hungary.
- Construction:Cement and mineral aggregate logistics favor high-denier fabric constructions with reinforced loop attachments.
Chemicals commands the highest unit margins. Food & Beverage shows the steepest certification-barrier expansion.
Material:
Supply concentration in virgin polypropylene resin determines regional converter competitiveness, with recycled-content grades gaining specification traction among sustainability-focused procurement teams.
- Polypropylene:Homopolymer and copolymer grades form the structural backbone with tunable UV stabilization and anti-static masterbatch integration. REACH compliance and EU Green Deal circularity mandates are compressing margins for virgin formulations while rewarding verified recycled-content supply chains. German and Dutch producers with closed-loop recovery infrastructure capture specification preference.
- Polyester:Higher tensile strength and moisture resistance for specialized chemical and food-grade applications where dimensional stability gates performance.
- Nylon:Abrasion-resistant grades for construction aggregate handling with extended duty-cycle requirements.
- Jute:Biodegradable alternative for single-use agricultural applications with limited reuse logistics.
Polypropylene dominates tonnage. Recycled-content polypropylene is gaining share fastest among sustainability-mandated buyers.
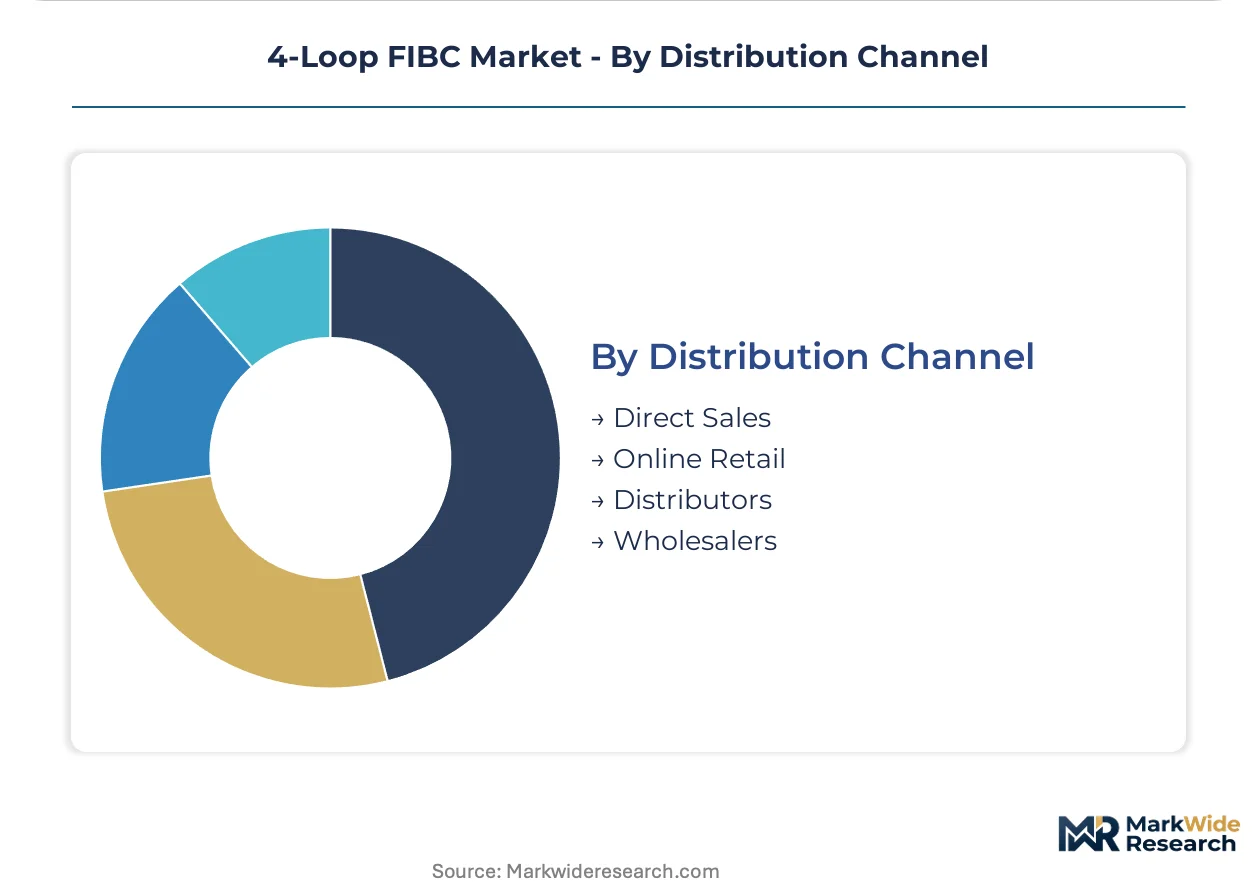
Distribution Channel:
Customer type fragmentation separates multinational chemical groups with centralized procurement functions from regional agricultural distributors losing specification influence to direct manufacturer relationships.
- Direct Sales:Manufacturer relationships with pan-European chemical distributors and integrated logistics providers in the Netherlands. Bundled FIBC supply with warehousing and inventory management services compresses standalone converter margins. Digital product passport integration via QR-code loop tags differentiates suppliers to sustainability procurement teams.
- Distributors:Regional packaging distributors serving mid-sized compounders in Eastern Europe with standardized technical specifications.
- Online Retail:E-procurement platforms for standardized agricultural and construction grades with immediate availability requirements.
- Wholesalers:Volume aggregation for price-sensitive buyers with limited technical specification complexity.
Direct Sales captures the premium tier. Online Retail is climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pan-European chemical distributors and integrated logistics providers concentrate procurement authority for conductive and anti-static grades, while agricultural buyers in Eastern Europe route standard volumes through distributor networks. REACH compliance and EU Green Deal circularity mandates are compressing margins for virgin polypropylene formulations across the region.
Germany
Chemical processors in the Rhine-Ruhr industrial corridor are expanding orders for conductive variants to handle solvent logistics in ATEX zones. ECHA substance restrictions under REACH now require full material disclosure documentation upstream of purchase orders. The Port of Hamburg serves as a northern logistics hub where mechanized handling protocols standardize four-loop lift configurations.
Netherlands
Fine-chemical distributors specify anti-static FIBCs for pharmaceutical powder handling where contamination control intersects with electrostatic risk. EU Green Deal extended producer responsibility frameworks mandate minimum recycled-content thresholds for industrial packaging. The Port of Rotterdam anchors European bulk chemical throughput, driving automation-compatible container specifications.
United States
Food and beverage processors require FDA food-contact certification for woven polypropylene containers in dairy and grain logistics. The EPA governs chemical handling standards for hazardous material packaging in industrial applications. Gulf Coast petrochemical corridors supply virgin resin feedstock to domestic converters serving agricultural markets in the Midwest.
India
Agricultural compounders in Gujarat and Maharashtra drive volume demand for UV-stabilized standard FIBCs in grain and fertilizer handling. BIS certification requirements are tightening fabric tensile strength and loop attachment standards for export-bound shipments. The Delhi-Mumbai Industrial Corridor concentrates logistics infrastructure for mechanized bulk material handling.
China
Construction aggregate logistics favor high-denier fabric constructions with reinforced loop attachments for cement and mineral transport. GB standards and MIIT regulations govern industrial packaging quality benchmarks for domestic and export markets. The Yangtze River Delta clusters woven fabric production capacity serving chemical and agricultural end users.
4-Loop FIBC Market Competitive Environment
Player mix skews toward integrated packaging conglomerates with captive resin sourcing and specialized fabric weavers competing on conductive-fabric certification velocity. Tiered competitive structure separates multinational converters with closed-loop recovery infrastructure from regional weavers absorbing ISO 21898 testing freight costs. Two strategic archetypes dominate: vertically integrated resin-to-fabric producers and conductive-specialist technical weavers. Capacity expansion in recycled-content grades and strategic partnerships for digital product passport integration represent the dominant competitive moves.
Among Netherlands-based producers, LC Packaging anchors European supply through circular-service models and regional production footprints. Greif exemplifies the integrated conglomerate archetype with North American plant networks sustaining margin stability against propylene feedstock volatility. Alpine FIBC occupies a specialist position competing on conductive-fabric expertise for chemical-sector buyers. These three represent the competitive spectrum from scale-driven integration to technical specialization.
| Leading Market Players |
|---|
| Global-Pak |
| LC Packaging |
| Alpine FIBC |
| LARE FIBC |
| Muscat Polymers |
| Greif |
| BAG Corp |
| Umasree Texplast |
| Shalimar Group |
| Others |
Value Chain & Pricing Dynamics
Recycled-content polypropylene substitution for virgin resin is redrawing supply geography toward German and Dutch converters with closed-loop recovery infrastructure while compressing premium pricing power for standard-duty grades. This input shift simultaneously elevates certification costs for distant weavers and rewards regional producers with EU Green Deal-compliant material traceability systems.
Pricing Analysis
Cost-plus contracts indexed to propylene monomer benchmarks dominate long-term agreements between Rhine-Ruhr chemical processors and woven fabric converters. Three-tier pricing structure across conductive-certified, food-grade, and standard agricultural tiers reflects ISO 21898 validation burden and UV stabilization complexity. Cost compression in standard FIBCs is intensifying because naphtha-cracking margin volatility transmits directly to converter margins. Agricultural buyers in Eastern Europe exhibit highest price sensitivity, while Dutch fine-chemical distributors prioritize conductive-fabric certification velocity over per-unit cost.
Supply Chain Analysis
Rotterdam port congestion and Rhine barge capacity constraints periodically choke polypropylene resin flows to Northwest European weavers. Germany, the Netherlands, and Belgium concentrate woven fabric production and ISO 21898 testing infrastructure. Virgin homopolymer resin, conductive tape yarn, and UV-stabilizing masterbatches constitute critical input dependencies. Single-source vulnerability concentrates in Belgian cyclic top-lift testing facilities where six-to-eight-week validation queues delay customer qualification. Distribution runs through direct manufacturer relationships with pan-European chemical distributors and integrated logistics providers bundling FIBC supply with warehousing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pan-European chemical distributors with centralized procurement functions, fragmenting influence among regional packaging distributors that previously gated specification authority for mid-sized compounders.
For Market Incumbents: Fortify closed-loop recovery infrastructure in Germany and the Netherlands to capture EU Green Deal recycled-content mandates before certification capacity saturates. Deepen backward integration into masterbatch formulation to defend margin position against propylene feedstock volatility and ECHA substance restriction compliance costs. For New Entrants and Emerging Players: Differentiate on EFSA-compliant food-contact fabric weaving capacity in Eastern Europe where migration-tested polypropylene grades remain underdeveloped. Target Polish and Hungarian agricultural distributors with digital product passport integration that batch-level traceability documentation can unlock. For Investors and Strategic Acquirers: Capital is best deployed toward technical weavers with ISO 21898 certification velocity and conductive-fabric specialization rather than commodity standard-FIBC converters facing margin compression. Watch for inflection when carbon border adjustment mechanism documentation requirements phase in and reward EU-based production footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Formulation | Captive UV stabilization and anti-static additive blending reduces ECHA compliance cost exposure for REACH-certified producers. |
| Closed-Loop Recovery Infrastructure Expansion | German and Dutch facilities with verified recycled-content supply chains capture EU Green Deal procurement preference. |
| Digital Product Passport Integration | QR-code traceability embedded in loop tags differentiates suppliers to sustainability teams at multinational chemical groups. |
| EFSA-Compliant Food-Contact Capacity Buildout | Eastern European first-movers in migration-tested polypropylene grades exploit certification gap before incumbent expansion. |
| Conductive-Fabric Certification Velocity Investment | Faster ISO 21898 turnaround compresses premium gap and defends positioning against miniaturized conductive tape yarn entrants. |
Study Parameters
Initial hypotheses were tested against primary input from FIBC plant managers, chemical processor procurement leads, distribution channel partners, and technical R&D directors at masterbatch suppliers, then refined against customs and trade data, Cefic chemical industry reports, SEC filings from integrated packaging conglomerates, and REACH substance restriction databases. Bottom-up volume estimates from converter capacity utilization were triangulated with top-down demand projections from end-use industry consumption patterns.
Variance decomposition across product type, end-use industry, material grade, and distribution channel segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from weighted average growth contributions across these segments, incorporating propylene feedstock price elasticity, EU Green Deal recycled-content mandate penetration curves, and Port of Rotterdam bulk chemical throughput expansion as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement of extended producer responsibility frameworks would require recalibration. Forecasts reflect assumptions about REACH substance restriction timelines and conductive-fabric specification adoption rates in ATEX zones. Practitioners should keep alternative scenarios live as ECHA phthalate threshold revisions and carbon border adjustment mechanism phase-ins evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Net Bags Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Padding Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Bag Clips Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Trash Bags Market