
 Multiwall Bags Market | 2026-2036
Multiwall Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Multiwall Bags Market Outlook
The price-performance gap between premium laminated multiwall bags and commodity kraft grades is hardening as food-grade certification requirements tighten. Mondi Group leverages its integrated pulp-to-bag operations across European mills to sustain margin capture in specialty agriculture applications. Smurfit Kappa dominates recycled-content paper bag supply to Western European cement and building materials customers, while ProAmpac differentiates through high-barrier plastic multiwall formats for chemical and mineral markets.
Multiwall bags are industrial containers constructed from multiple plies of paper, plastic film, or non-woven fabric, typically featuring 2-6 layers with grammages ranging from 70-120 g/m² per ply, designed to achieve specified tensile strength and moisture vapor transmission rates for bulk solids handling. Paper bags retain the largest volume share across food and beverage applications where breathability and stackability govern performance, while composite bags combining kraft outer plies with polyethylene inner barriers command the fastest growth in chemical and hygroscopic mineral segments where moisture protection determines spoilage risk. Stitching closure types remain standard for agricultural commodity flows, though heat seal formats are displacing mechanical closures in food-grade dairy and starch applications where contamination control is paramount.
REACH compliance through ECHA governs chemical contact materials for European multiwall bag producers, while FDA food contact substance notifications shape product specifications for U.S.-bound food and beverage packaging. India's BIS certification requirements for paper-based food packaging are tightening testing protocols for heavy metal migration and fiber sourcing traceability. Stakeholders must monitor how diverging regional recycling infrastructure investments reshape material specifications and cross-border qualification timelines for multiwall bag suppliers.
Market Dynamics
The EU Packaging and Packaging Waste Regulation (PPWR) is compressing qualification timelines for multiwall bag suppliers while simultaneously fragmenting material specifications across member states with divergent recycling infrastructure maturity.
Growth Catalysts
- REACH compliance mandates:Chemical contact material rules through ECHA are forcing formulation upgrades that favor barrier-enhanced multiwall constructions over commodity alternatives in European industrial applications.
- Brazilian grain export infrastructure:Agricultural commodity handling modernization across Mato Grosso and Paraná is driving specification upgrades for moisture-resistant stitched closures in 50 kg fertilizer and seed applications.
- Heat-seal technology adoption:Contamination-sensitive dairy and starch processors are displacing mechanical stitched formats with hermetic seal systems that eliminate fiber shedding risk during filling operations.
Market Restraints
- Pulp cost volatility:Unbleached kraft fiber prices swing with Nordic and Brazilian softwood supply cycles, compressing margin predictability for integrated converters.
- Recycled-content supply concentration:Western European recovered paper streams cluster around Smurfit Kappa's captive mill network, creating qualification bottlenecks for second-tier bag producers.
- Polyethylene barrier substitution limits:Mono-material paper solutions cannot match MVTR performance of PE-lined composites in hygroscopic mineral applications, locking out sustainability-driven specification shifts.
Strategic Opportunities
- India's northern agricultural belt:Food grain storage infrastructure modernization in Punjab and Haryana is opening specification windows for BIS-certified food-grade multiwall bags with heavy metal migration testing.
- Digital printing integration:Variable-data outer ply decoration enables lot-traceable QR coding for pharmaceutical and specialty chemical end-uses that batch-stamp systems cannot serve.
- Biopolymer barrier convergence:PLA and PHA inner seal layers paired with kraft exteriors address PPWR recyclability targets while maintaining moisture protection for sensitive agricultural inputs.
Industry Challenges
- FDA food contact notification timelines:U.S.-bound dairy and starch bag specifications face 6-12 month pre-market clearance cycles that compress product launch windows against European competitors.
- Legacy stitching equipment retrofit costs:Heat-seal migration requires capital outlays for ultrasonic sealing systems that mid-tier agricultural bag converters in Southeast Asia cannot absorb without financing support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiwall Bags Market |
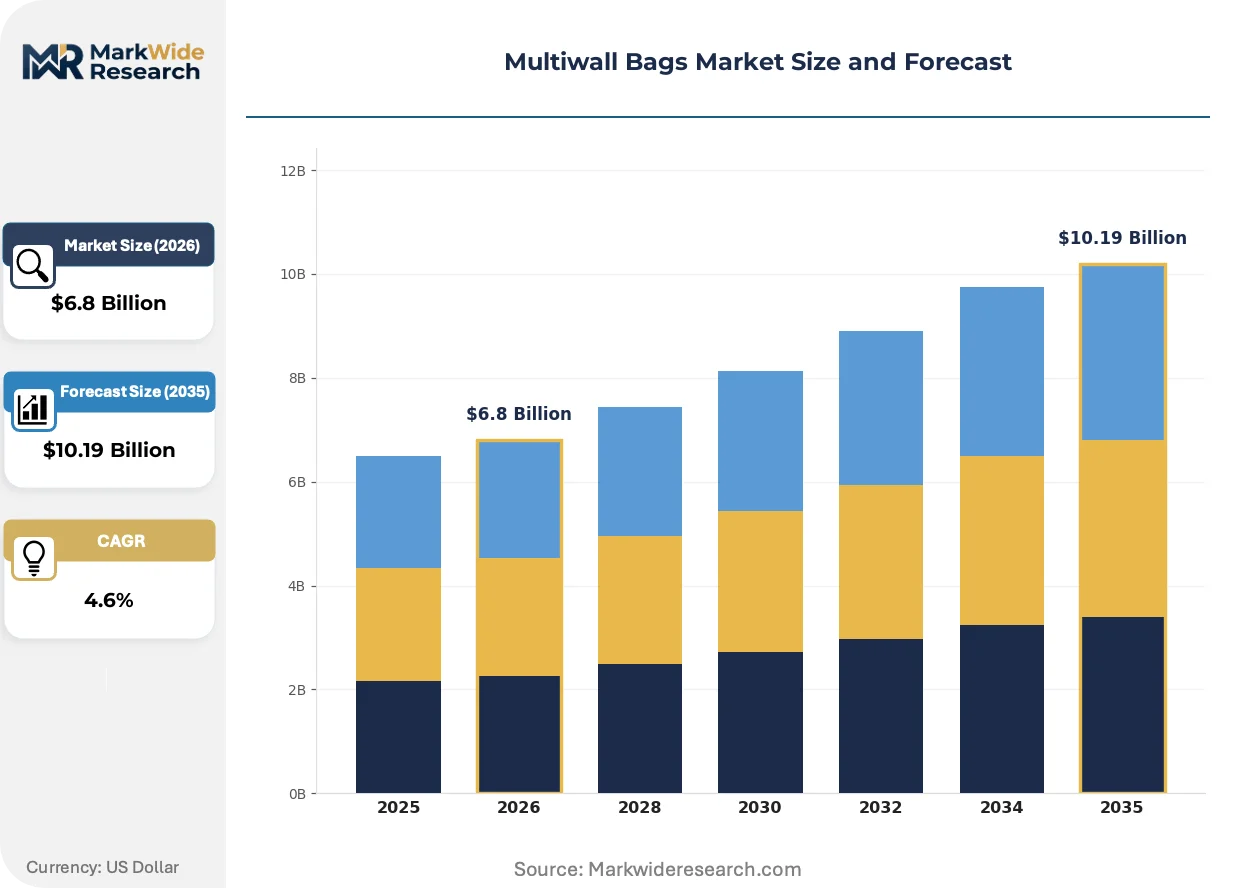
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Bags, Plastic Bags, Non-Woven Bags, Composite Bags End Use Industry: Food & Beverage, Agriculture, Chemicals, Building Materials Closure Type: Heat Seal, Stitching, Ties, Taping Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Mondi Group, Smurfit Kappa Group, WestRock Company, Hood Packaging Corporation, LC Packaging, Berry Global Inc., Sonoco Products Company, ProAmpac, Global-Pak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiwall Bags Market Strategic Shifts
Active material science convergence and regulatory specification tightening are compressing the viable technology set while elevating performance thresholds for qualified suppliers.
High-barrier coextruded polyethylene inner plies are consolidating technical specifications for hygroscopic mineral and chemical applications. Fertilizer blenders and specialty salt processors are specifying these constructions at accelerating rates to reduce spoilage claims. The technology is consolidating supplier tiers by eliminating paper-only converters from qualified vendor lists for moisture-critical end-uses.
REACH Article 33 substance of very high concern (SVHC) disclosure rules are forcing supply chain documentation depth that commodity bag assemblers cannot sustain. Industrial chemical handlers must now certify full material composition down to 0.1% weight thresholds. German and Benelux chemical distributors are most affected, responding by consolidating procurement around vertically integrated producers with captive laboratory testing capacity.
Direct mill-to-filler procurement contracts are compressing distributor margins in Western European cement and building materials channels. Large construction chemical formulators are bypassing wholesale intermediaries to secure volume commitments with recycled-content guarantees. This pattern is most visible in France and Germany where CSRD reporting obligations drive Scope 3 emissions documentation requirements that distributors cannot efficiently provide.
Multiwall Bags Market Segmentation
Multiwall bag specifications diverge sharply across end-use requirements, with moisture sensitivity and contamination risk driving material selection. Procurement patterns cluster around regional agricultural cycles and chemical handling standards that reward specialized construction expertise.
Product Type:
Customization intensity varies from commodity kraft grades to engineered barrier laminates requiring laboratory validation.
- Paper Bags:Unbleached kraft constructions with 70-120 g/m² grammages dominate food grain storage where breathability prevents condensation spoilage. India's BIS-certified procurement in Punjab and Haryana concentrates specification upgrades for heavy metal migration compliance.
- Composite Bags:Kraft outer plies bonded to polyethylene inner barriers achieve MVTR performance thresholds that hygroscopic mineral applications demand. Fertilizer blenders across Brazil's Mato Grosso corridor specify these constructions to reduce moisture-induced caking claims.
- Plastic Bags:Coextruded polyethylene multiwall formats serve chemical contact applications governed by REACH Article 33 SVHC disclosure rules.
- Non-Woven Bags:Polypropylene fabric constructions target building materials handling where abrasion resistance outweighs moisture protection priorities.
Most installed capacity flows through paper bags. Expansion is steepest in composite bags.
End Use Industry:
Margin structures align with regulatory burden intensity rather than volume scale alone.
- Food & Beverage:Dairy and starch processors specify heat-seal closures to eliminate fiber contamination during high-speed filling lines. FDA food contact notification timelines compress product launch windows against European competitors with faster EFSA clearance pathways.
- Chemicals:Industrial formulators require full material composition documentation down to 0.1% weight thresholds under REACH Article 33. German and Benelux distributors are consolidating procurement around vertically integrated producers with captive laboratory testing capacity.
- Agriculture:Brazilian grain export infrastructure modernization across Paraná drives specification upgrades for moisture-resistant stitched closures in 50 kg fertilizer applications.
- Building Materials:Cement and construction chemical handlers in France and Germany are bypassing distributors for direct mill contracts that satisfy CSRD Scope 3 emissions documentation requirements.
Volume concentrates in agriculture. Value capture is climbing fastest in chemicals.
Closure Type:
Technology migration tracks contamination sensitivity gradients across end-use categories.
- Stitching:Mechanical closure systems remain standard for agricultural commodity flows where cost sensitivity dominates and fiber shedding poses minimal risk. Southeast Asian mid-tier converters face capital constraints retrofitting legacy equipment to heat-seal formats.
- Heat Seal:Ultrasonic and thermal bonding systems displace mechanical closures in contamination-sensitive dairy and pharmaceutical applications. Hermetic seals eliminate particle generation during automated filling operations.
- Ties:Drawstring closures persist in artisanal food and specialty chemical segments where batch sizes resist automation economics.
- Taping:Adhesive strip formats serve interim applications requiring resealability without equipment investment.
Equipment base remains weighted toward stitching. Technology investment is accelerating in heat seal.
Distribution Channel:
Channel selection reflects documentation depth requirements and volume concentration patterns.
- Direct Sales:Large construction chemical formulators in Western Europe negotiate mill-direct contracts with recycled-content guarantees that distributors cannot efficiently document. CSRD reporting obligations drive this procurement consolidation.
- Distributors:Wholesale intermediaries retain relevance in fragmented agricultural markets where smallholder procurement lacks scale for direct supplier engagement.
- Online:Digital platforms serve spot procurement for specialty chemical and pharmaceutical applications requiring variable-data lot traceability.
- Retail:Counter sales persist in developing market building materials channels where contractor purchasing patterns resist digital migration.
Transaction volume flows primarily through distributors. Margin compression is sharpest in direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-bag production clusters anchor competitive positioning across the multiwall bags industry, with workforce concentrations around Nordic softwood processing zones and Brazilian agribusiness corridors shaping supply-side capabilities.
United States
Dairy and starch processors drive heat-seal closure adoption to eliminate fiber contamination during automated filling operations. FDA food contact substance notification timelines compress product launch windows against European competitors with faster regulatory pathways. Midwest agricultural belt facilities concentrate procurement for grain handling applications.
Germany
Construction chemical formulators bypass wholesale distributors for direct mill contracts satisfying CSRD Scope 3 emissions documentation requirements. REACH Article 33 SVHC disclosure rules force supply chain documentation depth that commodity assemblers cannot sustain. Rhine-Ruhr industrial corridor hosts vertically integrated producers with captive laboratory testing capacity.
Brazil
Grain export infrastructure modernization across Mato Grosso and Paraná drives specification upgrades for moisture-resistant stitched closures in 50 kg fertilizer and seed applications. ANVISA chemical contact material regulations shape product specifications for domestic agricultural input packaging. São Paulo state anchors converted paper bag capacity serving Mercosur distribution networks.
India
Food grain storage infrastructure modernization in Punjab and Haryana opens specification windows for BIS-certified food-grade multiwall bags with heavy metal migration testing. DGFT import substitution policies favor domestic paper-based packaging for fertilizer and agricultural commodity handling. Northern agricultural belt procurement concentrates demand during rabi and kharif harvest cycles.
China
Chemical and mineral processors specify high-barrier composite constructions to reduce moisture-induced spoilage claims in hygroscopic applications. GB standards for food contact paper packaging tighten testing protocols for heavy metal migration and fiber sourcing traceability. Yangtze River Delta manufacturing clusters integrate digital printing capabilities for lot-traceable pharmaceutical and specialty chemical end-uses.
Multiwall Bags Market Competitive Environment
Top-tier vendors anchor specialty barrier and food-grade segments, while mid-tier converters concentrate in commodity agricultural applications. The vendor base stratifies across integrated pulp-to-bag operators, recycled-content specialists, and high-barrier plastic format innovators. Three archetypes dominate: vertically integrated European paper producers, North American diversified packaging conglomerates, and Asia-Pacific regional specialists. Competitive moves center on direct mill-to-filler procurement contract expansion and heat-seal equipment retrofit partnerships.
Within the integrated European tier, Mondi Group and Smurfit Kappa Group exemplify archetypes of captive pulp supply and recycled-content concentration respectively. ProAmpac occupies a position among North American specialists in barrier-enhanced constructions. These three entities represent the spectrum from upstream fiber control through downstream specification customization, with each anchoring distinct competitive vectors in chemical, agricultural, and building materials end-uses.
| Leading Market Players |
|---|
| Mondi Group |
| Smurfit Kappa Group |
| WestRock Company |
| Hood Packaging Corporation |
| LC Packaging |
| Berry Global Inc. |
| Sonoco Products Company |
| ProAmpac |
| Global-Pak Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated pulp-to-bag workforce concentrations across Nordic softwood processing zones and São Paulo state manufacturing clusters feed labor-cost differentials that widen pricing-tier spreads between commodity agricultural grades and specialty barrier laminates.
Pricing Analysis
Bundled certification-plus-logistics services command premiums over unbundled commodity kraft transactions. Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified food-grade constructions from BIS-certified agricultural grades and untreated commodity bags. Price differentiation hinges on REACH Article 33 documentation depth and captive laboratory testing capacity. Margins are tightening in commodity tiers due to pulp cost volatility, while chemical and pharmaceutical buyers show lowest price sensitivity for SVHC-compliant barrier formats.
Supply Chain Analysis
Warehouse-distribution layer consolidation around Rhine-Ruhr regional distribution centers and Yangtze River Delta hub-and-spoke patterns compresses lead times for European chemical and Chinese pharmaceutical end-users. Raw material supply draws from Nordic unbleached kraft pulp mills, Brazilian eucalyptus fiber plantations, and Saudi petrochemical feedstock for polyethylene barrier films. Single-source vulnerability concentrates in Smurfit Kappa's captive Western European recovered paper network. Distribution runs through direct mill-to-filler contracts for large construction chemical formulators and wholesale agricultural distributors for fragmented smallholder procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through heat-seal equipment retrofit partnerships that capture premium-tier specification upgrades from contamination-sensitive dairy and starch processors.
For Market Incumbents: To counter mid-tier Southeast Asian converters gaining share via undifferentiated commodity pricing, deepen captive pulp supply control through Nordic mill network expansion and accelerate BIS certification pre-positioning ahead of India's northern agricultural belt procurement windows. Heat-seal technology licensing partnerships with regional equipment distributors create switching costs that stitched-closure rivals cannot match.
For New Entrants and Emerging Players: Launch via digital printing-enabled lot-traceability platforms serving pharmaceutical and specialty chemical spot procurement channels that established players underserve. White-space concentration sits in India's Punjab-Haryana food grain storage modernization and Brazilian Mato Grosso fertilizer export corridor specification upgrades. Biopolymer barrier convergence offerings targeting PPWR recyclability mandates provide differentiated entry positioning against incumbent polyethylene-lined composites.
For Investors and Strategic Acquirers: Construction chemical formulators are the most active acquirer in this space, consolidating backward into captive packaging supply to secure CSRD Scope 3 emissions documentation. Long-term viability favors targets with integrated laboratory testing capacity and heat-seal equipment fleets over pure-play stitched-closure assemblers. Watch for ECHA SVHC list expansion announcements as inflection indicators that trigger qualification-driven procurement consolidation toward vertically integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Mondi Group's captive Nordic softwood operations insulate margin capture from commodity fiber price swings. |
| Heat-Seal Equipment Retrofit Partnerships | Ultrasonic sealing system deployment locks in dairy and starch processor switching costs against stitched-closure rivals. |
| BIS Certification Pre-Positioning | Heavy metal migration testing capacity captures India's northern agricultural belt food-grade specification windows. |
| Direct Mill-to-Filler Contract Expansion | CSRD reporting obligations drive French and German construction chemical formulators toward integrated suppliers. |
| Biopolymer Barrier R&D Convergence | PLA and PHA inner seal layers address PPWR recyclability targets while maintaining moisture protection for agricultural inputs. |
Study Parameters
Coverage spans Western Europe, North America, Brazil, India, and China, with primary inputs from each combining interviews with plant managers at integrated pulp-to-bag producers, procurement leads at fertilizer blenders and dairy processors, distribution channel partners in agricultural wholesale networks, and technical R&D directors at barrier film specialists. Secondary validation draws from ECHA REACH registrations, FDA food contact substance notifications, BIS certification databases, and customs trade data for unbleached kraft pulp and polyethylene resin flows. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic indicators.
Granularity-level modeling disaggregates volume and value across product type, end-use industry, closure technology, and regional production hub clusters throughout the forecast period. CAGRs derive from segment-specific demand elasticity coefficients applied to baseline capacity utilization rates. Industry-specific forecast inputs include Brazilian grain export infrastructure investment pipelines, EU PPWR implementation timelines, and India's DGFT import substitution policy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pulp cost volatility spikes and ECHA SVHC list expansion scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Craft Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Ventilated FIBC Market