
 Padding Bags Market | 2026-2036
Padding Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Padding Bags Market Analytics
The split between premium cushioned mailers and commodity-grade kraft padding is repositioning procurement criteria across fulfillment networks. Sealed Air Corp leverages multi-layer film technology to sustain margins in temperature-sensitive pharmaceutical shipments. ProAmpac LLC anchors its position through geographic dominance in North American e-commerce channel supply.
Padding bags are flexible protective enclosures constructed from laminated polyethylene films, bubble wrap composites, or foam-corrugated hybrids, engineered to absorb impact forces between 15 and 50 G during transit handling. Their primary commercial purpose centers on reducing product damage rates for shipped goods while minimizing dimensional weight penalties relative to rigid box alternatives. Polyethylene-based cushioned mailers lead volume due to cost scalability, yet foam-lined variants command superior margin pools in electronics and medical device segments where electrostatic discharge protection is specified. Bubble wrap configurations retain mature demand in manufacturing spare parts distribution, while adhesive seal closure types capture the fastest growth in automated fulfillment lines.
The EPA regulates volatile organic compound emissions from adhesive lamination processes, while FDA guidelines govern padding materials in direct-contact medical device packaging, and ISO 2234 standards define stacking performance thresholds for transport packaging validation. These frameworks compel manufacturers to reformulate sealants and document chain-of-custody for recycled content claims. Stakeholders must monitor how pending state-level extended producer responsibility laws in California and New York reshape cost allocation between converters and brand owners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to requalify entire material portfolios against recycled content minimums, compressing sourcing timelines and elevating compliance costs across European fulfillment networks.
Growth Catalysts
- E-commerce dimensional weight penalties:Fulfillment centers are expanding padded mailer procurement to circumvent carrier pricing surcharges on rigid corrugated alternatives. Amazon, Shopify, and regional logistics hubs drive volume concentration.
- REACH chemical compliance:European adhesive reformulation mandates are accelerating migration from solvent-based lamination to water-based and UV-cured systems, opening specification windows for compliant converters.
- Automotive just-in-time packaging:German parts distributors require certified protective enclosures for precision components, creating demand for foam-lined and anti-static variants with documented impact resistance.
Market Restraints
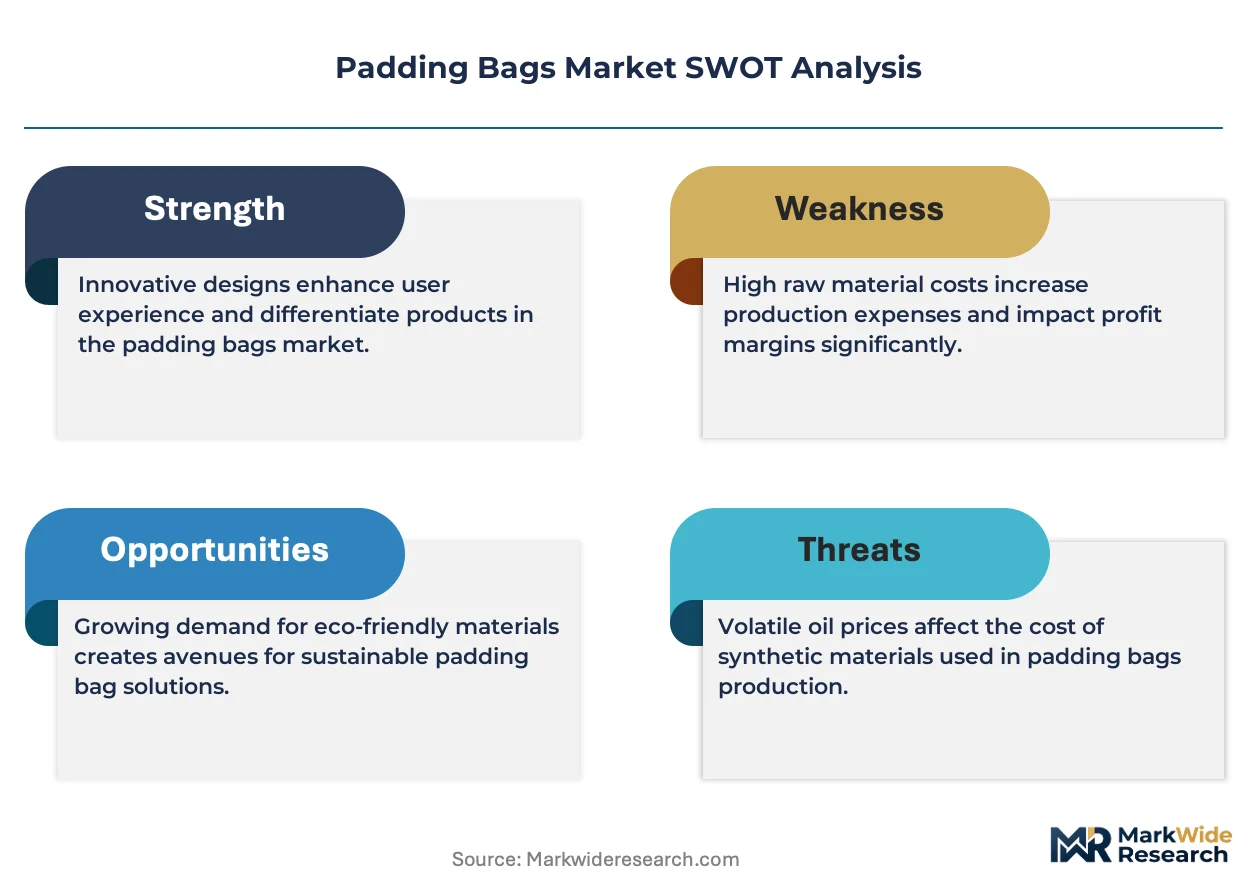
- Recycled polyethylene feedstock scarcity:Post-consumer film collection infrastructure remains underdeveloped in Eastern Europe, constraining local compliance with EU recycled content floors and forcing import dependence.
- Adhesive VOC emission controls:EPA regulations on volatile organic compound limits from lamination processes add capital equipment burdens for North American converters without grandfathering provisions.
- Rigid box substitution in premium electronics:Unboxing experience requirements from Apple, Samsung, and Dyson retain fiberboard preference for flagship product launches, capping padded mailer penetration in high-margin segments.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-sensitive biologic distribution is expanding padded envelope demand with phase-change material integration, supported by CDSCO packaging guidelines for injectable stability.
- California extended producer responsibility:Pending state legislation will shift end-of-life cost allocation toward brand owners, creating service revenue streams for converters offering take-back and recycling logistics.
- RFID-bubble composite convergence:Embedding track-and-trace sensors within cushioning layers enables pharmaceutical and high-value electronics shippers to consolidate protection and visibility in single-sku procurement.
Industry Challenges
- ISO 2234 stacking certification timelines:Transport packaging validation protocols require 12-18 month testing cycles, delaying new product commercialization and freezing specification decisions during regulatory transition periods.
- Multi-material separation for recycling:Laminated polyethylene-foam-adhesive constructions complicate mechanical recycling streams, forcing converters to redesign for mono-material compatibility without sacrificing cushioning performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Padding Bags Market |
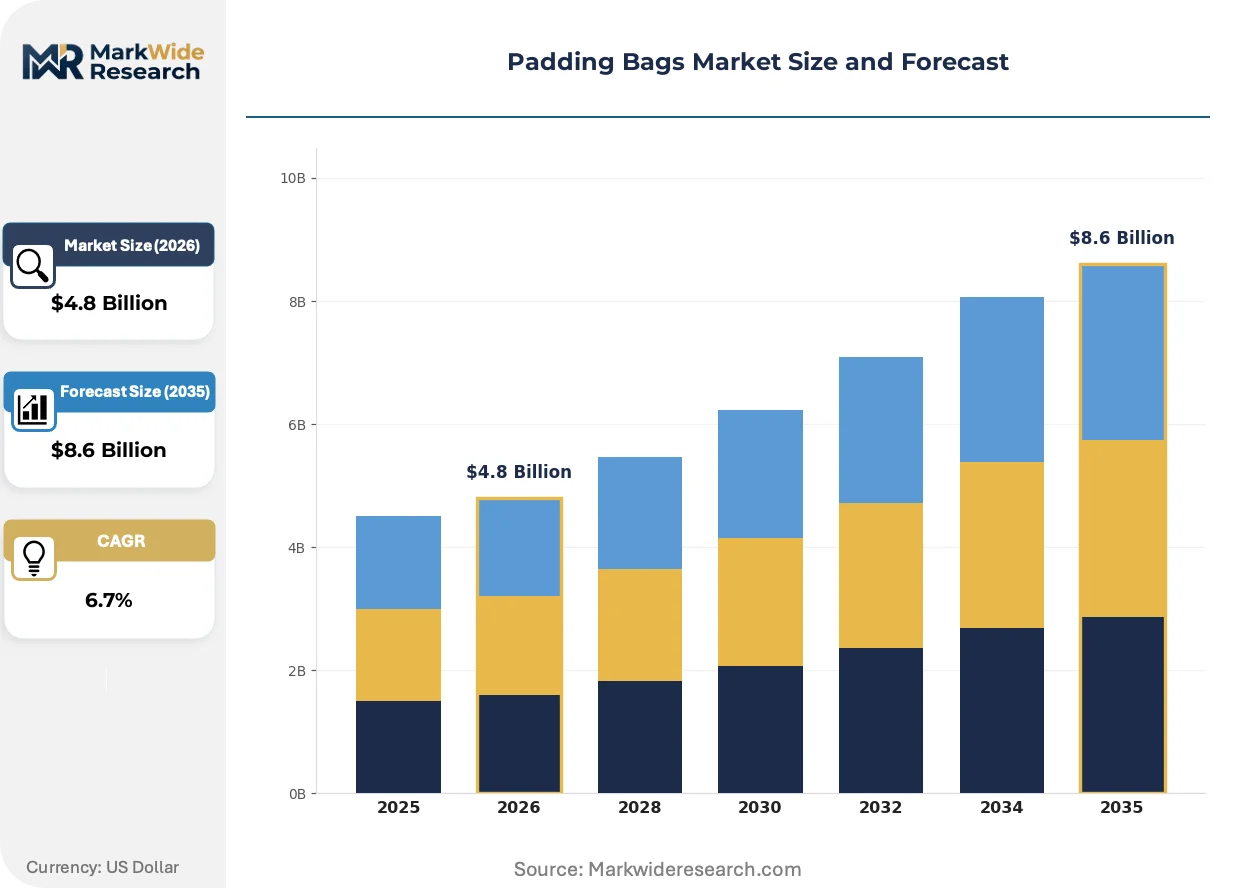
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Bubble Wrap, Foam, Corrugated Cardboard End User: E-commerce, Manufacturing, Retail, Logistics Closure Type: Adhesive Seal, Zip Lock, Tie String, Heat Seal Bag Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | Polycell International Corp, ProAmpac LLC, Sealed Air Corp, Jiffy Packaging Co Limited, Vereinigte Papierwarenfabriken GmbH, Polyair Inter Pack Inc, 3M Company, Pregis LLC, Pac Worldwide Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Padding Bags Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine performance benchmarks and procurement criteria across protective packaging value chains.
Algae-derived barrier films are rewriting moisture protection standards for padded mailers. Pharmaceutical distributors in the Netherlands and Denmark are piloting these bio-based laminates at scale. The technology is compressing petroleum-based film margins in applications where aerobic biodegradability carries compliance weight.
REACH substance restriction updates are eliminating certain phthalate plasticizers from polyethylene formulations. European converters face reformulation deadlines with limited qualified alternative supply. Medical device exporters to Germany and France are accelerating supplier audits to preempt certification gaps.
Automated fulfillment line integration is compressing order cycle times for adhesive seal closure specifications. E-commerce operators in the United States and United Kingdom are rejecting legacy gummed-flap designs that jam high-speed insertion equipment. Equipment OEMs are co-developing mailer formats with converters to optimize throughput at picking stations.
Padding Bags Market Segmentation
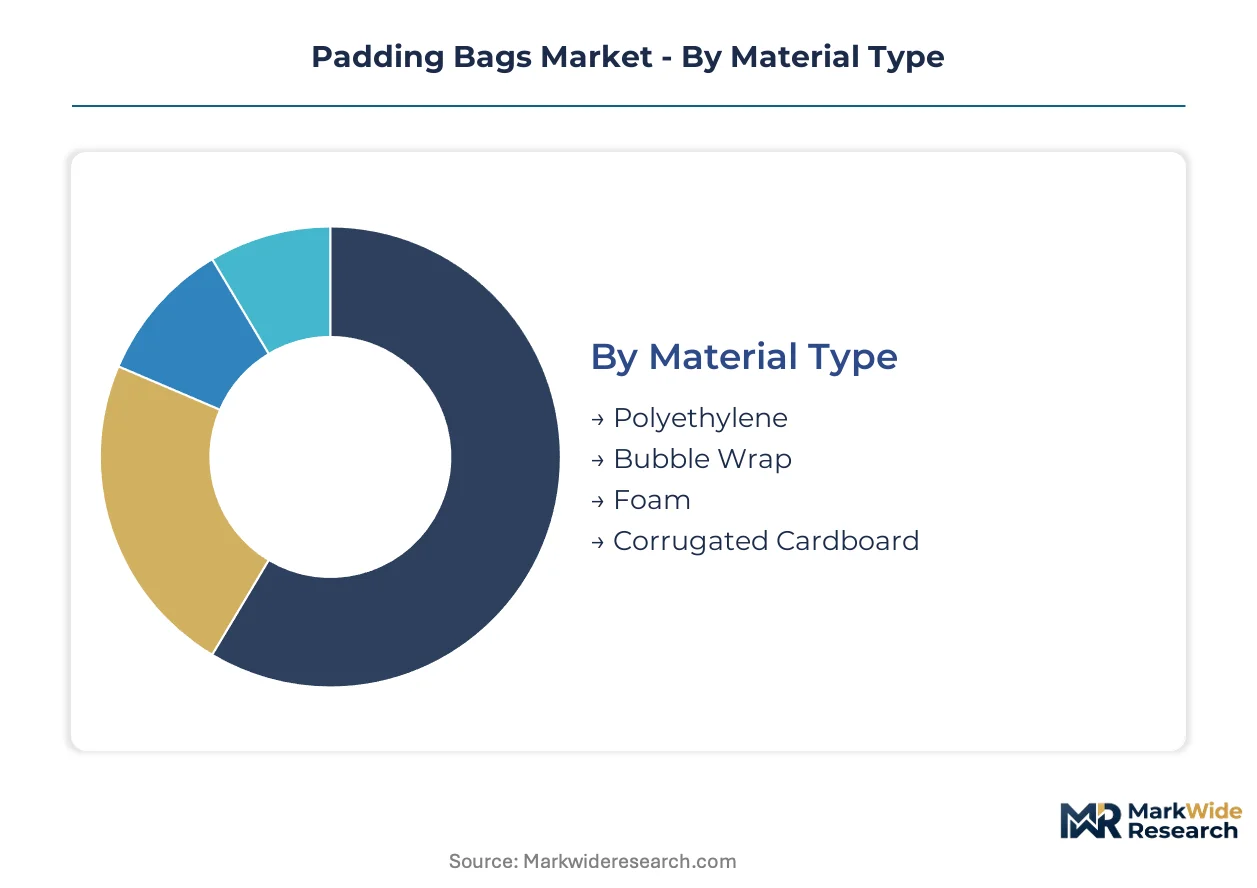
Padding bag procurement decisions pivot on material performance thresholds, closure automation compatibility, and dimensional weight optimization. Specification mismatches between cushioning technology and handling intensity drive damage rate variance across fulfillment networks.
Material Type:
Technical specifications define impact absorption capacity and recyclability pathways across converter portfolios.
- Polyethylene:Multi-layer coextruded films dominate volume through cost scalability and moisture barrier performance. E-commerce fulfillment centers in Germany and the United States specify polyethylene cushioned mailers to minimize dimensional weight penalties on small parcel networks.
- Bubble Wrap:Air-entrapped polymer matrices deliver 15-35 G impact absorption for manufacturing spare parts distribution. German automotive distributors require bubble wrap configurations with documented ISO 2234 stacking certification for just-in-time precision component delivery.
- Foam:Expanded polyethylene and polyurethane variants command premium positioning in electrostatic-sensitive electronics packaging.
- Corrugated Cardboard:Fiberboard-padded hybrids serve applications demanding rigid edge protection with limited flexibility.
Mature deployment sits with Polyethylene. Newer deployment is concentrated in Foam.
End User:
Operational intensity and damage cost exposure differentiate procurement criteria across customer categories.
- E-commerce:Automated fulfillment lines demand adhesive-seal padded mailers compatible with high-speed insertion equipment. Amazon and Shopify distribution networks drive specification standardization around tear-resistant polyethylene films with printed branding surfaces.
- Manufacturing:Spare parts distributors prioritize impact resistance documentation and batch traceability. German automotive suppliers mandate foam-lined variants with anti-static properties for electronic control module shipment.
- Retail:Store-brand packaging programs emphasize printed surface quality and shelf-ready presentation.
- Logistics:Third-party carriers specify universal sizing compatibility across heterogeneous shipper bases.
Volume concentrates in E-commerce. Margin expansion is steepest in Manufacturing.
Closure Type:
Automation compatibility and tamper evidence requirements reshape converter product development priorities.
- Adhesive Seal:Pressure-sensitive hot-melt formulations enable sub-second closure on automated fulfillment lines. United Kingdom and United States e-commerce operators reject legacy gummed-flap designs that jam picking station equipment.
- Zip Lock:Reclosable interlocking profiles serve pharmaceutical sample distribution and return-enabled retail programs.
- Tie String:Cotton and synthetic cord closures persist in artisanal and gift packaging segments with low automation exposure.
- Heat Seal:Thermal bonding systems deliver hermetic integrity for temperature-sensitive biologic distribution in Indian pharmaceutical cold chains.
Adhesive Seal captures the steepest expansion trajectory. Heat Seal retains niche premium positioning.
Bag Size:
Dimensional optimization and carrier pricing tier alignment determine size specification distribution.
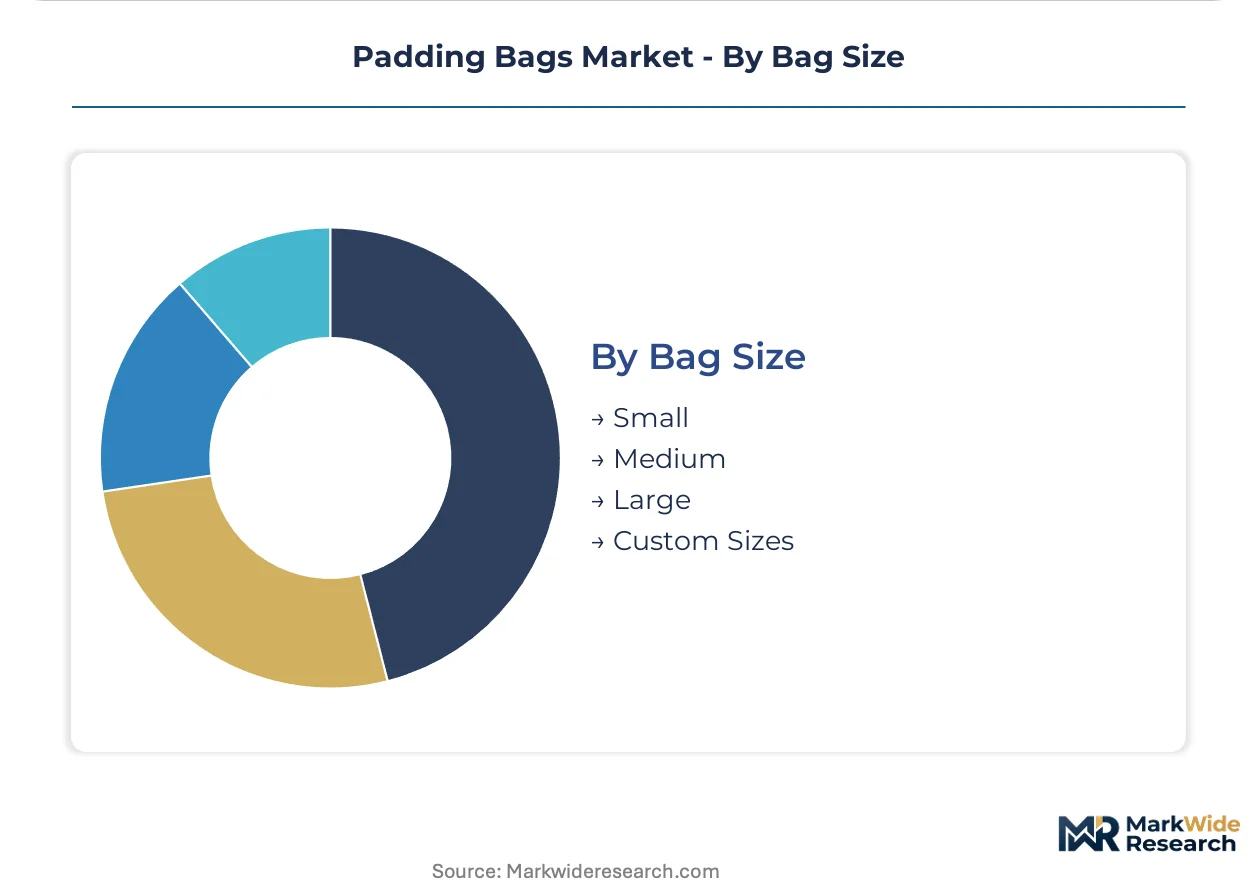
- Small:Envelope formats under 6x9 inches minimize first-class postal surcharges for jewelry and electronics accessories. United States Postal Service dimensional pricing tiers concentrate demand in this specification band.
- Medium:Standard corrugated alternative replacements for apparel and soft goods command balanced volume across European fulfillment networks.
- Large:Expanded formats approaching small parcel dimensional limits serve bulky lightweight items with high damage risk.
- Custom Sizes:Die-cut and branded configurations support unboxing experience requirements for direct-to-consumer premium brands.
Standardization dominates Medium. Differentiation concentrates in Custom Sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates German automotive parts distribution networks that mandate certified protective packaging for just-in-time supply chains.
United States
Amazon fulfillment centers in Seattle and Shopify logistics hubs in San Francisco drive adhesive-seal padded mailer procurement to circumvent carrier dimensional weight penalties. EPA volatile organic compound regulations compel solvent-to-water-based adhesive migration. California's pending extended producer responsibility legislation reshapes cost allocation between converters and brand owners in Los Angeles basin distribution networks.
Germany
Automotive precision component distributors in Stuttgart and Munich require foam-lined variants with documented ISO 2234 stacking certification. REACH substance restrictions eliminate phthalate plasticizers from polyethylene formulations, forcing converter reformulation. Hamburg port logistics clusters pilot algae-derived barrier films for pharmaceutical cold chain distribution.
China
E-commerce operators in Shenzhen and Hangzhou scale padded mailer procurement for cross-border parcel networks serving European consumers. MIIT standards govern packaging material recyclability claims in domestic fulfillment channels. Yangtze River Delta manufacturing clusters supply bubble wrap configurations for electronics spare parts distribution.
India
Temperature-sensitive biologic distributors in Mumbai and Hyderabad expand padded envelope demand with phase-change material integration. CDSCO packaging guidelines for injectable stability drive specification standardization. Bangalore pharmaceutical cold chain clusters adopt heat-seal thermal bonding systems for hermetic integrity requirements.
United Kingdom
United Kingdom e-commerce operators reject legacy gummed-flap designs that jam high-speed insertion equipment in Midlands fulfillment centers. ECHA chemical compliance mandates accelerate adhesive system transitions. Manchester logistics hubs co-develop mailer formats with converters to optimize automated picking station throughput.
Padding Bags Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material formulation and automated conversion equipment. The vendor base separates into integrated film extruders, specialized mailer converters, and diversified packaging conglomerates with multi-category portfolios. Three archetypes dominate: polyethylene film specialists with captive resin supply, bubble wrap heritage manufacturers diversifying into mailer formats, and protective packaging pure-plays serving pharmaceutical cold chains. Competitive moves concentrate on geographic expansion into Indian pharmaceutical corridors and portfolio diversification toward temperature-sensitive logistics.
Among diversified packaging conglomerates, Sealed Air Corp and 3M Company exemplify multi-technology platform operators. ProAmpac LLC represents North American channel-focused scale. Vereinigte Papierwarenfabriken GmbH anchors European fiberboard-padded hybrid positioning.
| Leading Market Players |
|---|
| Polycell International Corp |
| ProAmpac LLC |
| Sealed Air Corp |
| Jiffy Packaging Co Limited |
| Vereinigte Papierwarenfabriken GmbH |
| Polyair Inter Pack Inc |
| 3M Company |
| Pregis LLC |
| Pac Worldwide Corporation |
| Others |
Value Network & Pricing Analysis
Captive resin supply through backward integration into polyethylene extrusion anchors both cost position and pricing power for integrated converters serving Amazon and Shopify fulfillment networks. This structural choice insulates margin pools from virgin resin volatility while forcing asset-light competitors toward spot-market exposure and compressed pricing flexibility.
Pricing Analysis
Outcome-based pricing tied to damage-rate guarantees anchors premium positioning for foam-lined variants serving German automotive distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 2234 certification status and electrostatic discharge protection specifications. Pricing pressure stems from recycled polyethylene feedstock scarcity in Eastern Europe, forcing import-dependent converters into cost compression. E-commerce fulfillment centers exhibit highest price sensitivity, while pharmaceutical cold chain buyers prioritize temperature integrity over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and regional logistics hubs, bypassing distributor markups. Geographic supply concentrates in China, Germany, and the United States, with Yangtze River Delta clusters feeding bubble wrap configurations and Ruhr corridor converters serving automotive just-in-time networks. Raw material dependencies center on low-density polyethylene resin, adhesive formulations, and post-consumer recycled film feedstock. Single-source vulnerability runs through phthalate-free plasticizer supply chains facing REACH reformulation deadlines. Distribution runs through converter-direct relationships with fulfillment operators and third-party logistics aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation creates a barrier-to-entry moat for converters with pre-qualified recycled content supply chains, elevating compliance costs for new entrants while entrenching incumbents with documented chain-of-custody systems.
For Market Incumbents: Anchor market position through captive resin supply expansion and ISO 2234 certification pre-qualification for automotive distributor networks. Solvent-to-water-based adhesive migration timelines compress margin recovery windows for converters lacking capital equipment reserves. Geographic diversification into Indian pharmaceutical corridors offsets European regulatory cost burdens through premium temperature-sensitive positioning. For New Entrants and Emerging Players: Temperature-sensitive biologic distributors in Mumbai and Hyderabad represent an underserved buyer archetype with limited incumbent specialization. CDSCO guideline alignment and phase-change material integration capability open specification windows absent entrenched supplier relationships. Co-development partnerships with Bangalore cold chain clusters accelerate heat-seal thermal bonding qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified packaging conglomerates seeking pharmaceutical cold chain capability and geographic expansion into Indian distribution networks. Long-term viability hinges on regulatory compliance infrastructure and mono-material redesign pipelines for circular economy alignment. Watch for California extended producer responsibility implementation as inflection indicator for service revenue model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Supply Chain Integration | EU Packaging and Packaging Waste Regulation compliance secures automotive and pharmaceutical specification access. |
| Water-Based Adhesive System Migration | EPA VOC emission limits and REACH substance restrictions eliminate solvent-based lamination alternatives. |
| Indian Pharmaceutical Cold Chain Expansion | CDSCO packaging guidelines and temperature-sensitive biologic distribution drive padded envelope specification. |
| RFID-Bubble Composite Convergence | Embedding track-and-trace sensors consolidates protection and visibility for high-value electronics shippers. |
| Mono-Material Redesign for Recycling | Mechanical recycling compatibility addresses EU circular economy mandates without sacrificing cushioning performance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across converter operations directors, e-commerce fulfillment procurement leads, automotive packaging engineers, and pharmaceutical supply chain managers. EPA emission disclosure databases, EU ECHA substance restriction updates, and CDSCO packaging guideline repositories provided regulatory validation. Bottom-up volume triangulation against top-down value estimates tested segment-level assumptions.
Material type, closure automation compatibility, and end-use intensity were modeled at the country-cluster level across the analysis window. CAGRs derived from regression-based demand elasticity coefficients applied to carrier dimensional weight pricing tier shifts and e-commerce fulfillment center expansion pipelines. Recycled content compliance timelines and adhesive reformulation cost curves fed scenario-weighted projections.
Revisions become necessary when EU recycled content minimums accelerate, California extended producer responsibility legislation advances, or pharmaceutical cold chain infrastructure investment stalls. Forecasts reflect assumptions on carrier pricing stability and resin supply chain configuration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Slider Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Craft Bags Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Trash Bags Market