
 Piping Bags Market | 2026-2036
Piping Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Piping Bags Market Analytics
Multi-source procurement for food-grade polymers is pivoting toward vertically integrated silicone suppliers as bakeries seek batch traceability. Wilton Brands LLC leverages its retail channel dominance across North American craft stores to sustain brand visibility among home bakers. Matfer Bourgeat International anchors its position through professional-grade reusable bags that dominate European culinary school procurement. Fat Daddio's competes on specialized sizing for commercial tiered cake production.
A piping bag is a conical or cylindrical flexible container, typically constructed from food-grade polyethylene, silicone rubber, or laminated fabric composites with seam weld strengths exceeding burst pressures of 50 psi, designed to extrude viscous food preparations through a fitted nozzle. Its primary commercial purpose is to enable controlled deposition of icings, batters, and savory fillings in high-throughput bakery and foodservice environments. Disposable plastic variants lead volume sales in high-turnover commercial bakeries where sanitation turnaround times compress workflow cycles. Silicone reusable bags capture margin concentration among pastry chefs and culinary schools where durability justifies premium positioning across multiple closure configurations.
The FDA's food contact substance regulations and the EU's REACH framework govern polymer migration limits and phthalate restrictions, directly shaping material selection and supplier qualification timelines for piping bag manufacturers. BIS certification requirements in India and China's GB standards for food-contact silicone create layered compliance obligations for exporters serving multiple national markets. Stakeholders must monitor evolving extended producer responsibility mandates in Europe and North America that could shift cost structures toward recyclable or compostable material platforms.
Market Dynamics
REACH compliance deadlines and the EU's F-Gas Regulation are compressing supplier qualification timelines while forcing rapid material transitions toward medical-grade silicone formulations across European commercial baking operations.
Growth Catalysts
- REACH polymer migration limits:The EU's tightened phthalate restrictions are accelerating silicone adoption as bakeries preempt compliance costs.
- German industrial baking clusters:Concentrated equipment hubs in Bavaria and North Rhine-Westphalia create localized demand density for premium reusable bags.
- Silicone rubber thermal stability:Temperature resistance above 200°C enables extended reuse cycles in high-throughput pastry production.
Market Restraints
- Food-grade polymer input volatility:Polyethylene resin prices fluctuate with crude oil derivatives, squeezing margin on disposable bag production.
- Chinese silicone supply concentration:Over half of medical-grade silicone raw material originates from Zhejiang and Guangdong provinces, creating single-source vulnerability.
- Seam weld technical ceiling:Burst pressure reliability above 75 psi remains unachievable in high-speed automated welding without manual inspection.
Strategic Opportunities
- India BIS certification pathway:Domestic food-contact standards create first-mover advantage for compliant exporters as bakery chains expand in Maharashtra and Karnataka.
- Compostable biopolymer convergence:PLA-starch blends with silicone compatibility layers address extended producer responsibility mandates in France and Italy.
- D2B platform channel:Specialized procurement portals for culinary schools bypass traditional distributor markups in the UK and Netherlands.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and BIS qualification extends product launch cycles by 8-14 months.
- Automated filling equipment integration:Bag closure compatibility with third-party depositor systems requires proprietary adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piping Bags Market |
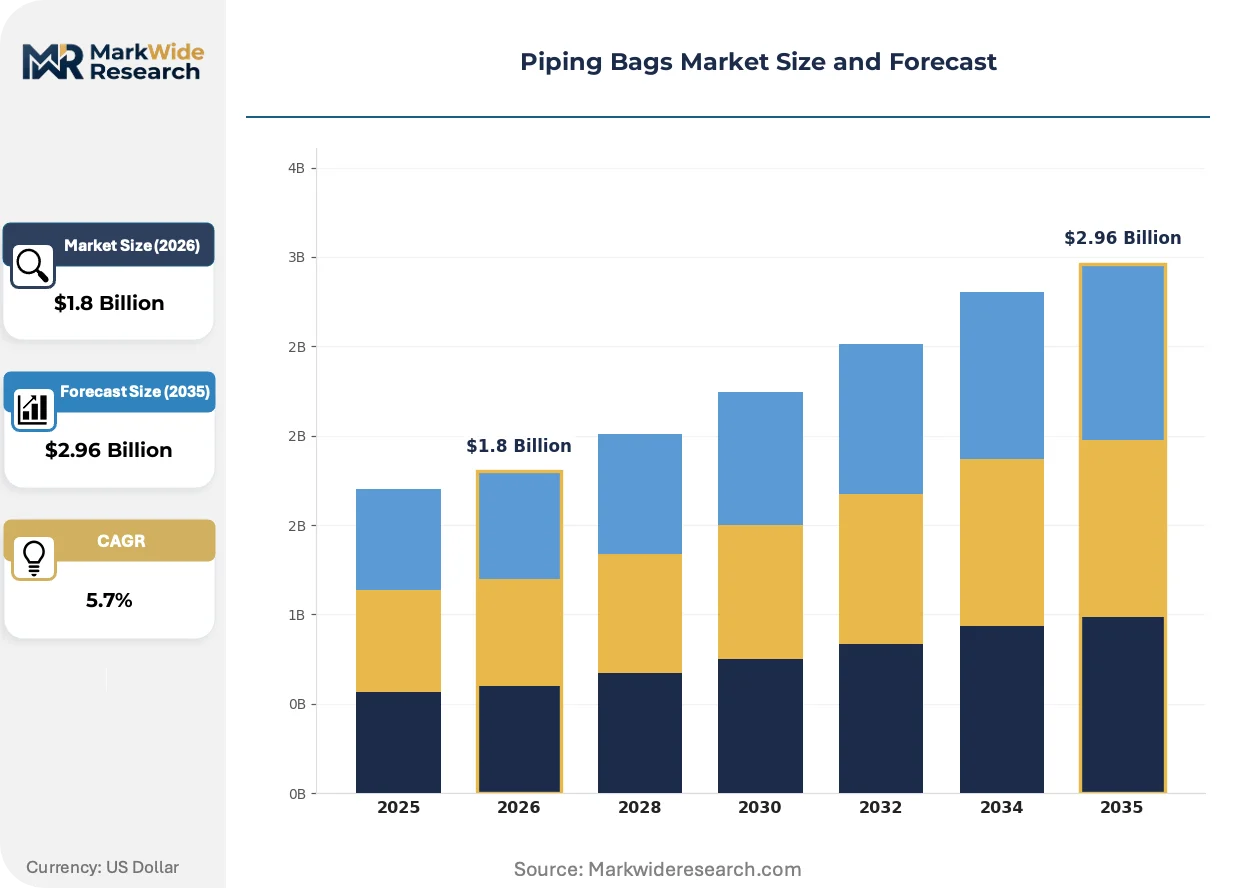
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Silicone, Disposable, Reusable Product Size: Small, Medium, Large, Extra Large Closure Type: Twist Tie, Clip Seal, Nozzle, Zipper End User: Professional Bakers, Home Bakers, Pastry Chefs, Culinary Schools |
| Companies Covered | Conagra Brands, Inc., Fat Daddio's, Matfer Bourgeat International, Bakery Crafts, Kerekes Bakery & Restaurant Equipment Inc., Wilton Brands LLC, Pastry Star (LCB Pastry Star Sdn Bhd), AM Manufacturing Company, Ateco Cake Decorating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piping Bags Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape competitive positioning around traceability, thermal performance, and circularity credentials rather than unit cost alone.
Laminated fabric-silicone hybrid construction is unifying the durability of reusable bags with the disposability economics of single-use variants. Mid-sized commercial bakeries in Belgium and the Netherlands are piloting these formats at 15-20% volume substitution rates. This unification is compressing the traditional premium-economy segmentation by delivering certified food-contact performance at intermediate price points.
The EU's F-Gas Regulation phase-down schedule is forcing refrigerant-dependent cold-chain logistics providers to reconsider silicone bag insulation properties for temperature-sensitive fillings. Industrial bakeries operating across Germany and Poland are now specifying thermal resistance in procurement tenders. This regulatory pressure is accelerating R&D partnerships between bag manufacturers and polymer compounders.
Culinary school procurement committees are consolidating vendor lists around batch-traceability documentation. Three-year framework agreements with silicone specialists are displacing spot purchasing through restaurant supply distributors in France, Switzerland, and Austria. This concentration is most visible in Paris and Lyon, where école hôtelière purchasing cooperatives now mandate polymer origin certificates.
Piping Bags Market Segmentation
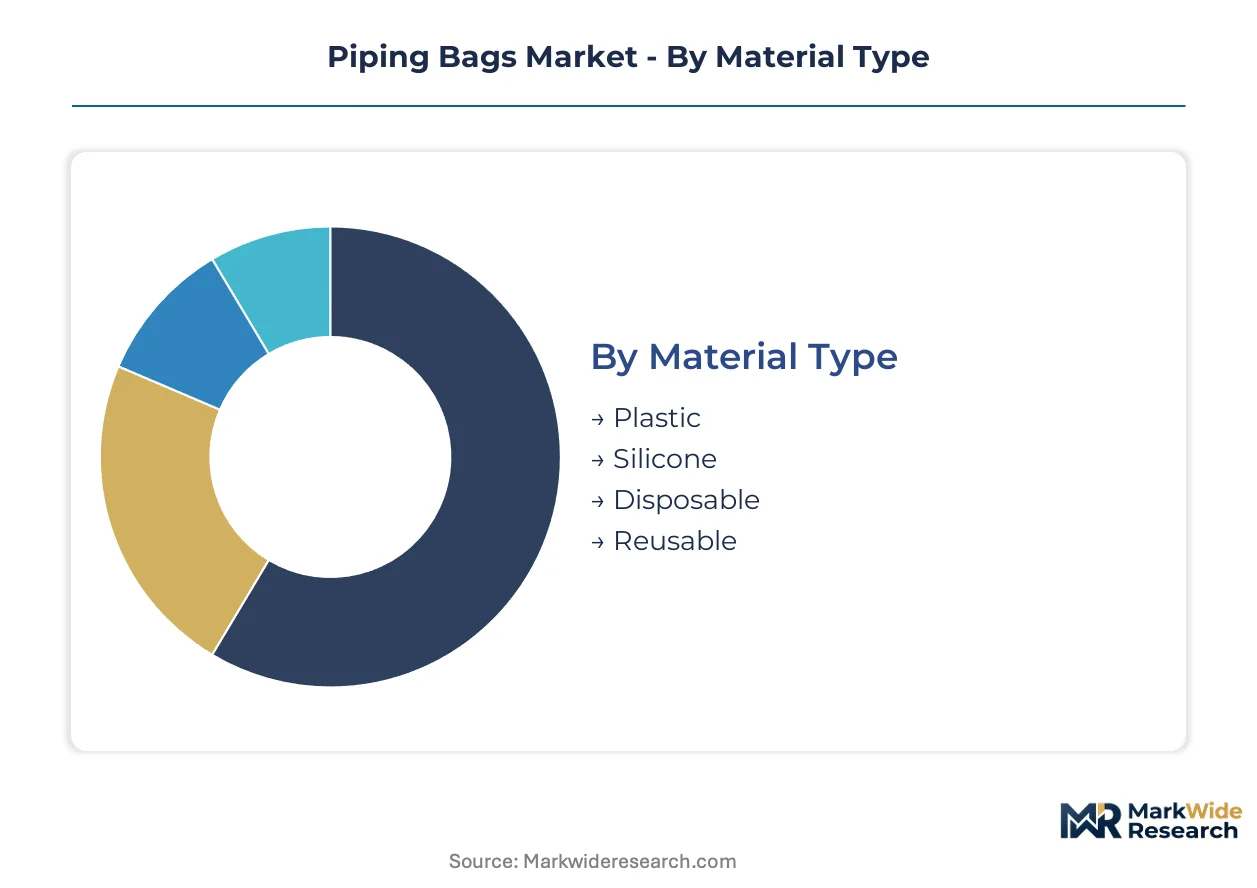
Segmentation in piping bags reveals how material specifications, sizing configurations, and closure mechanics align with distinct operational workflows across commercial and consumer baking environments. Understanding these divisions exposes where compliance costs, reuse economics, and throughput requirements reshape procurement priorities.
Material Type:
Material selection determines thermal tolerance, regulatory compliance burden, and lifecycle economics in professional kitchen environments.
- Plastic:Food-grade polyethylene formulations dominate high-throughput commercial bakeries where single-use sanitation protocols compress turnaround times. Demand concentrates in German industrial baking clusters where REACH phthalate restrictions accelerate transitions toward medical-grade silicone alternatives.
- Silicone:Medical-grade silicone rubber withstands temperatures exceeding 200°C and supports hundreds of reuse cycles. Pastry chefs in French and Swiss culinary schools specify these for durability across extended training curricula.
- Disposable:Laminated fabric-polyethylene hybrids balance unit economics with burst pressure reliability. Belgian and Dutch mid-sized bakeries pilot these at intermediate volume substitution rates.
- Reusable:Seam-welded silicone constructions with reinforced closure zones target premium positioning. Culinary school procurement cooperatives in Paris and Lyon mandate batch-traceability documentation for these formats.
Plastic leads on scale; silicone leads on momentum.
Product Size:
Capacity specifications map directly to production batch volumes and equipment integration requirements across bakery operations.
- Small:6-10 inch bags suit precision decoration and single-portion plating. Home bakers in North American craft retail channels drive volume here.
- Medium:12-16 inch configurations balance manual handling with modest batch throughput. Independent pastry shops in Bavaria standardize on this capacity.
- Large:18-24 inch formats integrate with automated depositor systems in industrial production lines. German equipment manufacturers specify these for compatibility with third-party filling machinery.
- Extra Large:30+ inch industrial bags serve commercial tiered cake production and high-volume savory filling operations. Fat Daddio's specializes in this sizing tier for commercial bakery chains.
Medium bags anchor procurement volume; extra large formats climb the fastest on automation integration.
Closure Type:
Sealing mechanisms determine compatibility with filling equipment, spillage risk, and operator training requirements.
- Twist Tie:Simple polymer or wire bindings offer lowest unit cost and rapid field replacement. High-turnover commercial bakeries favor these for sanitation speed.
- Clip Seal:Reusable polymer clamps enable mid-production content changes without bag replacement. Pastry chains in the Netherlands specify these for workflow flexibility.
- Nozzle:Integrated threaded fittings enable rapid tip exchange and standardized deposition control. Culinary schools in Austria and Switzerland require these for technique consistency.
- Zipper:Track-seal mechanisms support repeated opening for refilling and cleaning. Premium reusable silicone bags increasingly incorporate these for home baker convenience.
Nozzle closures dominate professional specification; zipper formats gain share fastest on consumer segment expansion.
End User:
Customer categories separate volume-driven commercial operations from education-focused institutions and discretionary consumer purchases.
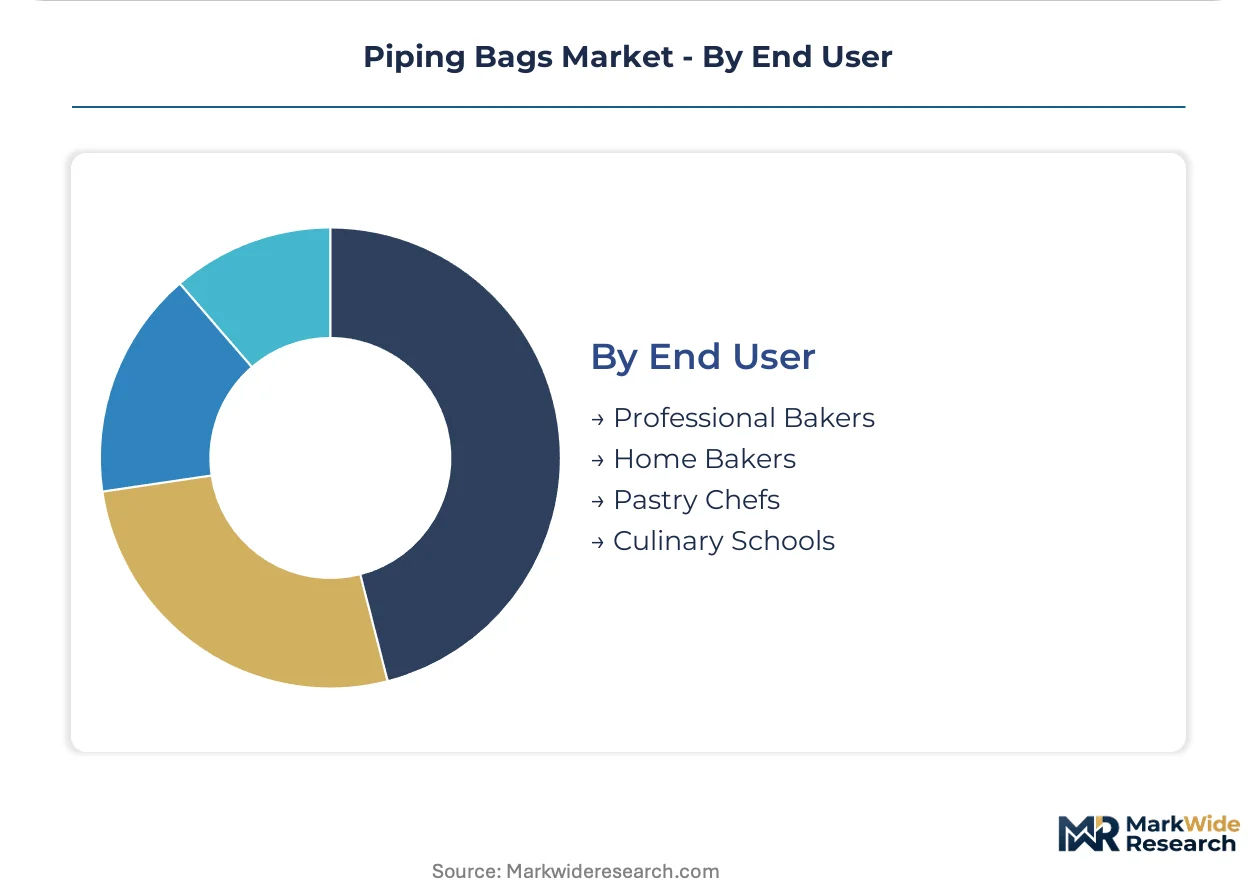
- Professional Bakers:Industrial and retail bakery operations prioritize sanitation compliance and throughput consistency. REACH and FDA food-contact regulations directly shape their material qualification timelines.
- Home Bakers:Discretionary consumers in craft and specialty retail channels respond to brand visibility and price accessibility. Wilton Brands LLC maintains channel dominance here.
- Pastry Chefs:High-end dessert specialists demand thermal stability and precision control for complex preparations. These users justify premium silicone positioning.
- Culinary Schools:École hôtelière cooperatives in France, Switzerland, and Austria consolidate vendor lists around three-year framework agreements. Matfer Bourgeat International anchors supply relationships through professional-grade reusable bag procurement.
Professional bakers represent the largest addressable base; culinary schools deliver the steepest expansion trajectory on vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial baking clusters in Bavaria and North Rhine-Westphalia generate concentrated demand for premium reusable piping bags as commercial bakeries modernize equipment lines.
Germany
REACH polymer migration limits and F-Gas Regulation phase-downs accelerate silicone adoption in commercial baking operations. ECHA compliance deadlines compress supplier qualification timelines for medical-grade formulations. Bavarian equipment manufacturers in Munich and Nuremberg specify thermal-resistant bags for automated depositor integration.
United States
FDA food contact substance regulations govern phthalate restrictions in polyethylene disposable bags. Home baking channels through craft retail sustain volume demand for consumer-grade formats. Wilton Brands LLC leverages nationwide distribution networks to maintain brand visibility among discretionary purchasers.
France
École hôtelière procurement cooperatives in Paris and Lyon mandate batch-traceability documentation for silicone reusable bags. Extended producer responsibility mandates push mid-sized bakeries toward compostable biopolymer trials. Île-de-France pastry chains consolidate vendor lists around three-year framework agreements.
India
BIS certification requirements for food-contact silicone create compliance barriers for imported reusable bags. Domestic bakery chain expansion in Maharashtra and Karnataka generates localized demand density. Mumbai and Pune equipment distributors report accelerating specification of medical-grade silicone for high-throughput operations.
Belgium
Laminated fabric-silicone hybrid construction pilots at 15-20% volume substitution rates in mid-sized commercial bakeries. EU Green Deal circularity targets incentivize recyclable material platforms. Antwerp and Ghent industrial baking clusters test intermediate price-point formats bridging premium and economy tiers.
Piping Bags Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized sizing and material hybridization. The vendor base distributes across three tiers: multinational kitchenware conglomerates with retail channel dominance, professional-grade equipment specialists serving culinary institutions, and regional fabricators targeting price-sensitive commercial bakeries. Two strategic archetypes predominate: silicone specialists leveraging regulatory compliance as differentiation, and disposable-format producers optimizing unit economics at scale. Competitive moves concentrate on backward integration into medical-grade silicone supply and direct-to-business platform development bypassing traditional distributors.
Within the professional-equipment tier, Matfer Bourgeat International anchors supply relationships through culinary school procurement frameworks, while Fat Daddio's exemplifies specialization in commercial-tiered cake production sizing. Wilton Brands LLC represents retail-channel dominance through craft store distribution networks. These three occupy distinct positioning vectors without direct segment overlap.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| Fat Daddio's |
| Matfer Bourgeat International |
| Bakery Crafts |
| Kerekes Bakery & Restaurant Equipment Inc. |
| Wilton Brands LLC |
| Pastry Star (LCB Pastry Star Sdn Bhd) |
| AM Manufacturing Company |
| Ateco Cake Decorating |
| Others |
Value Network & Pricing Analysis
Culinary school procurement cooperatives in France and Switzerland concentrate purchasing power around three-year framework agreements, anchoring contract-based pricing that favors certified silicone suppliers over spot-market disposable producers. This buyer concentration compresses margin dispersion across the value chain while elevating batch-traceability documentation to a price-determining threshold.
Pricing Analysis
Polyethylene resin cost pass-through dominates disposable bag economics, with crude oil derivative volatility squeezing margin on high-turnover commercial bakery orders. Pricing stratifies across medical-grade silicone, food-grade polyethylene, and laminated fabric-silicone hybrid tiers, with certification level under REACH and FDA frameworks commanding premium positioning. Pricing pressure stems from Chinese silicone supply concentration, with Zhejiang and Guangdong province dependency amplifying input cost uncertainty. High-turnover commercial bakeries exhibit acute price sensitivity, while culinary schools prioritize traceability credentials over unit economics.
Supply Chain Analysis
Specialized polymer welding technicians in Germany, Belgium, and the Netherlands constrain seam-weld automation throughput, with burst-pressure reliability above 75 psi requiring manual inspection protocols that bottleneck capacity expansion. Medical-grade silicone rubber feeds from Zhejiang and Guangdong provinces in China, food-grade polyethylene resin draws from petrochemical complexes in Germany and the Netherlands, and laminated fabric substrates source from textile manufacturers in Belgium. Single-source vulnerability concentrates in Chinese silicone raw material, with over half of medical-grade formulations originating from two provinces. Distribution runs through restaurant supply distributors in fragmented retail channels, while direct-to-business platforms for culinary schools bypass traditional markups in the UK and Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with REACH polymer migration limits and F-Gas Regulation phase-downs creating durable demand for compliant silicone formulations that outlast commodity substitution cycles.
For Market Incumbents: Lock in backward integration into medical-grade silicone supply to preempt Zhejiang and Guangdong province concentration risk, while embedding batch-traceability documentation into three-year framework agreements with Paris and Lyon école hôtelière cooperatives. Certification investment represents the priority lever against emerging biopolymer substitutes. For New Entrants and Emerging Players: Mid-sized commercial bakeries in Belgium and the Netherlands present the most penetrable buyer archetype, with laminated fabric-silicone hybrid pilots already achieving 15-20% volume substitution rates. Compostable biopolymer convergence with silicone compatibility layers offers white-space positioning against extended producer responsibility mandates in France and Italy. Direct-to-business platform development for UK and Netherlands culinary schools bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Kitchenware conglomerates with retail channel dominance are the most active acquirer in this space, seeking silicone specialists to offset polyethylene commodity exposure. Five-to-ten year viability hinges on regulatory compliance depth rather than unit cost optimization. Acquisition targets should demonstrate REACH, FDA, and BIS qualification simultaneously. The signal to watch is EU extended producer responsibility mandate expansion beyond France and Italy into Germany and Belgium.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Silicone | Captive supply from Zhejiang compounders insulates against REACH qualification timeline compression. |
| Direct-to-Business Platform Launch | Specialized procurement portals for Paris and Lyon culinary schools bypass 25-30% distributor markups. |
| Compostable Biopolymer R&D Partnership | PLA-starch blends with silicone compatibility layers address EU Green Deal circularity targets in Belgium. |
| Three-Year Framework Agreement Consolidation | École hôtelière procurement cooperatives in France and Switzerland displace spot purchasing volume. |
| Automated Seam-Weld Quality Certification | Burst-pressure reliability above 75 psi unlocks industrial bakery integration with German equipment manufacturers. |
Research Methodology
Bottom-up commercial bakery and culinary school modeling reconciled against top-down silicone and polyethylene supply tracking forms the analytical core. Primary interviews with pastry chefs, bakery procurement managers, culinary school purchasing committee chairs, and polymer compounder technical directors combined with secondary validation from ECHA REACH registration databases, FDA food contact substance notifications, BIS certification records, and EU F-Gas Regulation implementation reports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of material substitution patterns and regulatory compliance cost trajectories informed projection framework construction across the analysis window. Segmentation dimensions modeled include material type, product size tier, closure mechanism, and end-user category with geographic regulatory cluster overlay. CAGRs derived from fitted trend extrapolation adjusted for REACH phase-in schedules and F-Gas Regulation enforcement intensity. Industry-specific inputs incorporated thermal stability specifications from German equipment manufacturers and batch-traceability requirements from French école hôtelière cooperatives.
Underlying measurement precision varies by segment; medical-grade silicone and culinary school procurement carry tighter precision than disposable polyethylene and fragmented home baker channels. Forecasts reflect assumptions around REACH enforcement consistency, Chinese silicone export continuity, and EU extended producer responsibility rollout pacing. Material deviation in F-Gas Regulation phase-down acceleration, BIS certification timeline extension, or laminated fabric-silicone hybrid adoption inflection warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Desiccant Bags Market