
 Digital Camera Market | 2026-2036
Digital Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Camera Market Intelligence
Post-sale software subscriptions and cloud service revenue is fragmenting the traditional hardware-centric business model. Sony Group Corp. leverages its deep expertise in sensor manufacturing to drive innovation across its product lines. Canon Inc. sustains its market position through an extensive lens portfolio and established professional support networks. Meanwhile, FUJIFILM Holdings Corp. differentiates with its proprietary film simulations and distinct camera aesthetics.
A digital camera is an optical instrument that captures images electronically using an image sensor, such as a full-frame CMOS sensor, to convert light into digital data. Its primary purpose is the creation of high-fidelity still photographs and video for artistic, commercial, and scientific applications. The mirrorless product type is displacing legacy DSLR systems due to superior autofocus and video performance. While professional photographers remain a key customer type for high-margin sales, the enthusiast segment represents a larger volume base.
Compliance with electronics regulations is a critical market access requirement. This includes CE marking for products sold in the European Union and FCC certifications for wireless functionalities in the United States. Additionally, the RoHS directive influences material sourcing and manufacturing by restricting specific hazardous substances. Future competitive advantage hinges on the ability to integrate advanced software features with high-performance hardware.
Market Dynamics
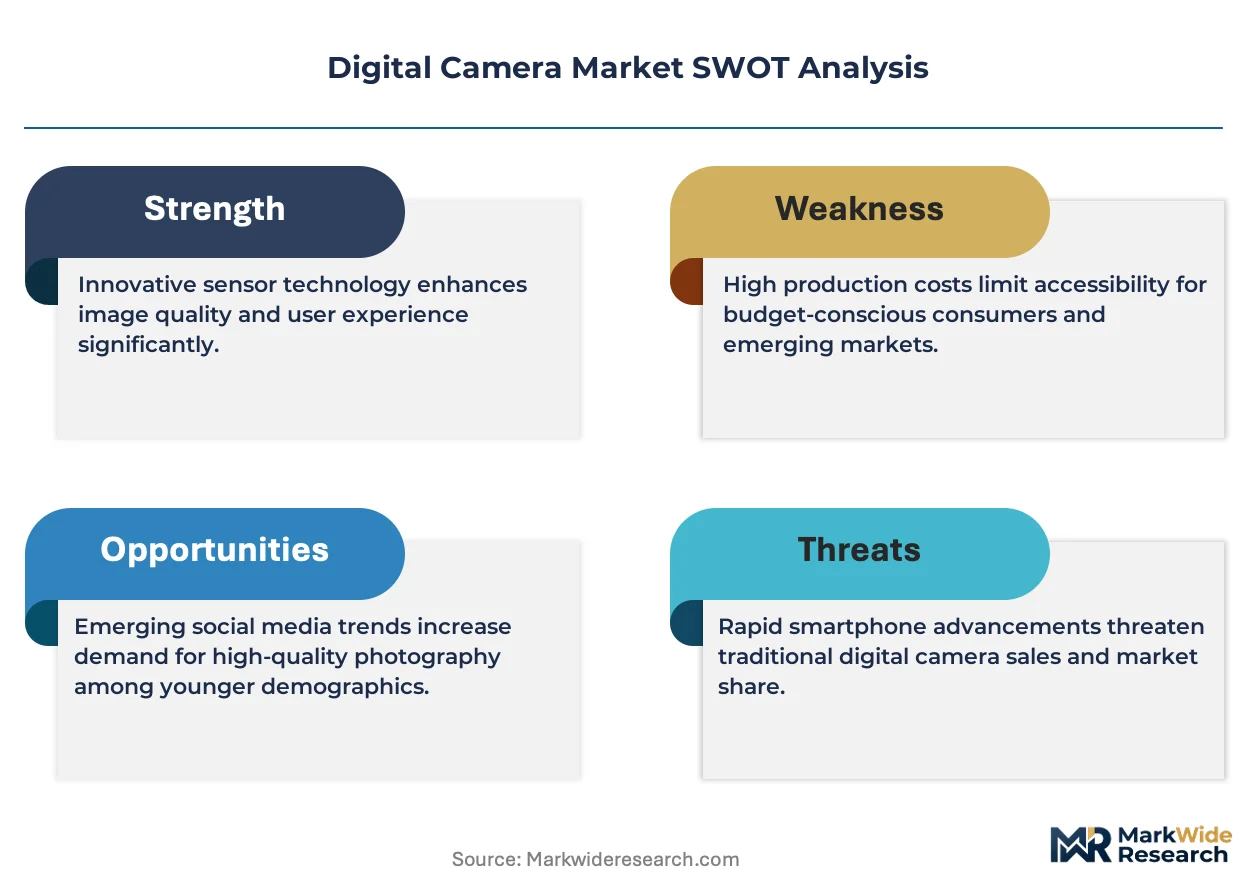
The digital camera market is shaped by a fundamental bifurcation in demand. The proliferation of advanced smartphones erodes the low-end consumer segment, while the simultaneous professionalization of content creation fuels intense innovation and investment at the high end.
Growth Catalysts
- AI-Powered Autofocus:The integration of deep-learning AI for subject recognition and tracking autofocus significantly improves performance for capturing fast-moving subjects, a critical need for sports and wildlife photographers who represent a high-margin customer base.
- Creator Economy Expansion:Demand from independent content creators for high-fidelity 4K and 8K video capabilities is a primary catalyst, driving sales of mirrorless systems that offer superior video features compared to traditional DSLRs.
- Media Production Hubs:Concentrated demand from professional film, television, and commercial production industries in key centers like the United States and Germany sustains a stable market for high-end cinema cameras and related professional services.
Market Restraints
- Smartphone Substitution:The rapid improvement of computational photography in flagship smartphones presents a persistent substitution threat, effectively eliminating the market for dedicated entry-level, point-and-shoot cameras and pressuring the enthusiast segment.
- Sensor Fabrication Dependency:The industry's reliance on a small number of specialized semiconductor foundries, primarily located in East Asia, for the manufacturing of advanced CMOS image sensors creates significant supply chain vulnerability and pricing volatility.
- High Research Costs:Substantial and continuous investment in research and development for next-generation image sensors, processors, and autofocus systems creates a high barrier to entry and compresses margins for manufacturers not operating at scale.
Strategic Opportunities
- Embedded Connectivity:Integrating 5G and advanced Wi-Fi technologies directly into camera bodies presents an opportunity to enable direct-to-cloud workflows, appealing to photojournalists, sports photographers, and live event broadcasters who require immediate content delivery.
- Expansion into Machine Vision:Adapting camera sensor and processing technology for industrial applications, including quality control automation in manufacturing and advanced driver-assistance systems in automotive, opens new B2B revenue streams beyond consumer and media markets.
- Software and Service Monetization:Developing subscription-based cloud storage, advanced post-processing software, and firmware updates with new features allows manufacturers to build recurring revenue and foster ecosystem loyalty beyond the initial hardware purchase.
Industry Challenges
- Regulatory Compliance Overhead:Adherence to a complex matrix of international electronics standards, including CE marking in Europe, FCC certification for wireless functions in the US, and RoHS material restrictions, adds significant cost and time to product development cycles.
- Lens Mount Transitions:Managing the transition from legacy DSLR lens mounts to new mirrorless mounts creates a challenge in maintaining backward compatibility for existing customers while encouraging adoption of new, optically superior native lenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Camera Market |
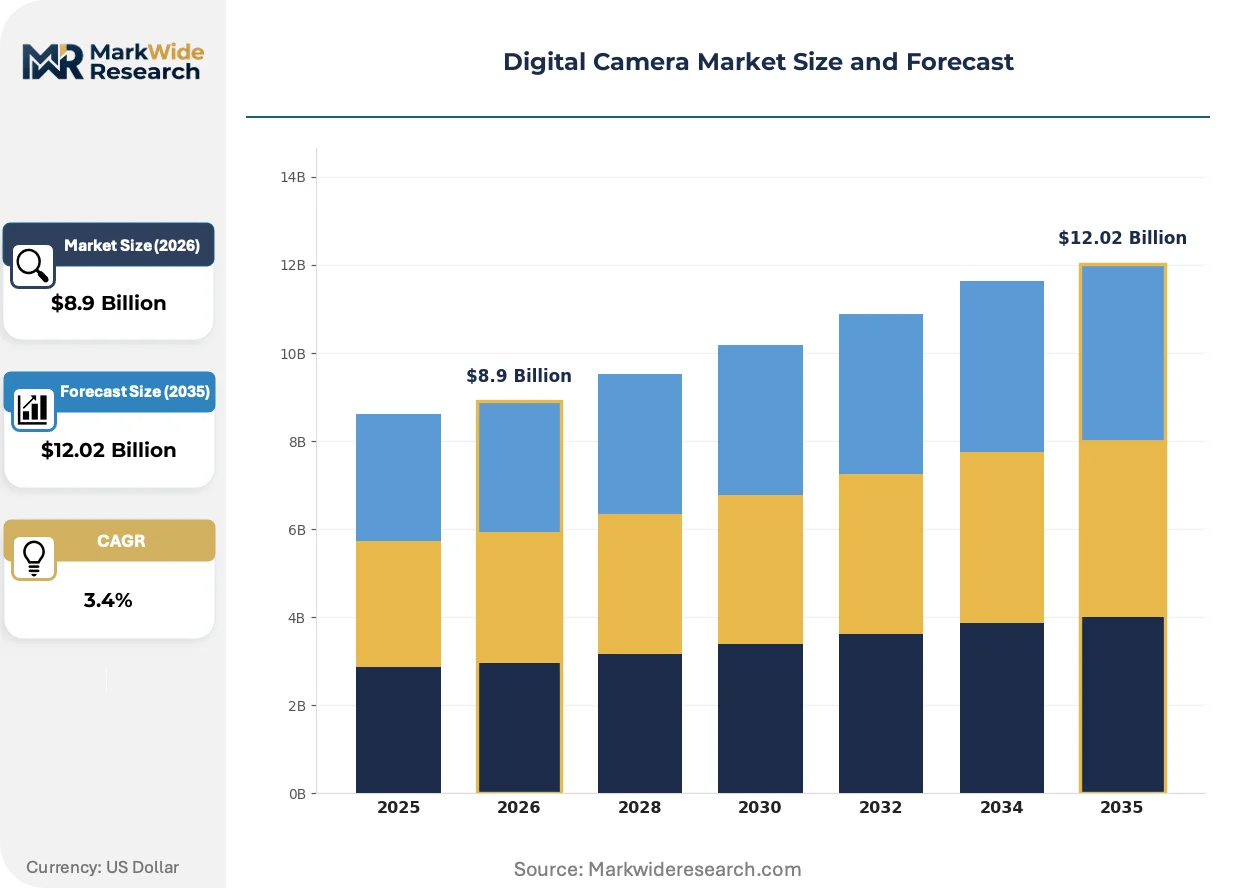
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $12.02 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Point-and-Shoot, Medium Format Sensor Technology: CMOS, CCD, BSI CMOS, Foveon X3 Application: Wildlife Photography, Event Coverage, Scientific Research, Surveillance Customer Type: Professional Photographers, Enthusiasts, Content Creators, Hobbyists |
| Companies Covered | Canon Inc., Sony Group Corp., Nikon Corp., FUJIFILM Holdings Corp., Panasonic Holdings Corp., OM Digital Solutions Inc., Leica Camera AG, GoPro Inc., SZ DJI Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Camera Market Strategic Shifts & Innovations
Software-defined functionality is fundamentally altering the value proposition of digital cameras. Computational power and enhanced connectivity are now as critical as optical excellence, shifting competitive focus from hardware specifications to integrated workflow solutions and post-sale services.
Computational Photography
Computational photography, which leverages dedicated AI processors, uses algorithms to achieve results that are difficult or impossible with optics alone. Enthusiast and professional photographers are adopting these features for tasks like focus stacking and automated dynamic range optimization directly in-camera. This trend is virtualizing elements of the post-production suite, moving complex editing capabilities from the computer into the device to accelerate creative workflows.
Interface Standardization
The European Union's mandate requiring USB-C as a common charging port for electronic devices is compelling hardware convergence. This regulation forces manufacturers to abandon proprietary charging and data ports, which simplifies the user experience but necessitates costly redesigns of camera bodies and power systems. All new camera models intended for sale in the EU are impacted, accelerating a market-wide shift toward this universal standard.
Ecosystem-Centric Purchasing
A notable behavioral shift sees buyers prioritizing a brand's software ecosystem over standalone hardware performance. This change disrupts traditional retail channels, as competition extends to the quality of a manufacturer's cloud storage platforms, remote control applications, and firmware-based feature updates. This pattern is most pronounced among professional content creators in North America and Europe who value workflow efficiency and system integration.
Digital Camera Market Segmentation
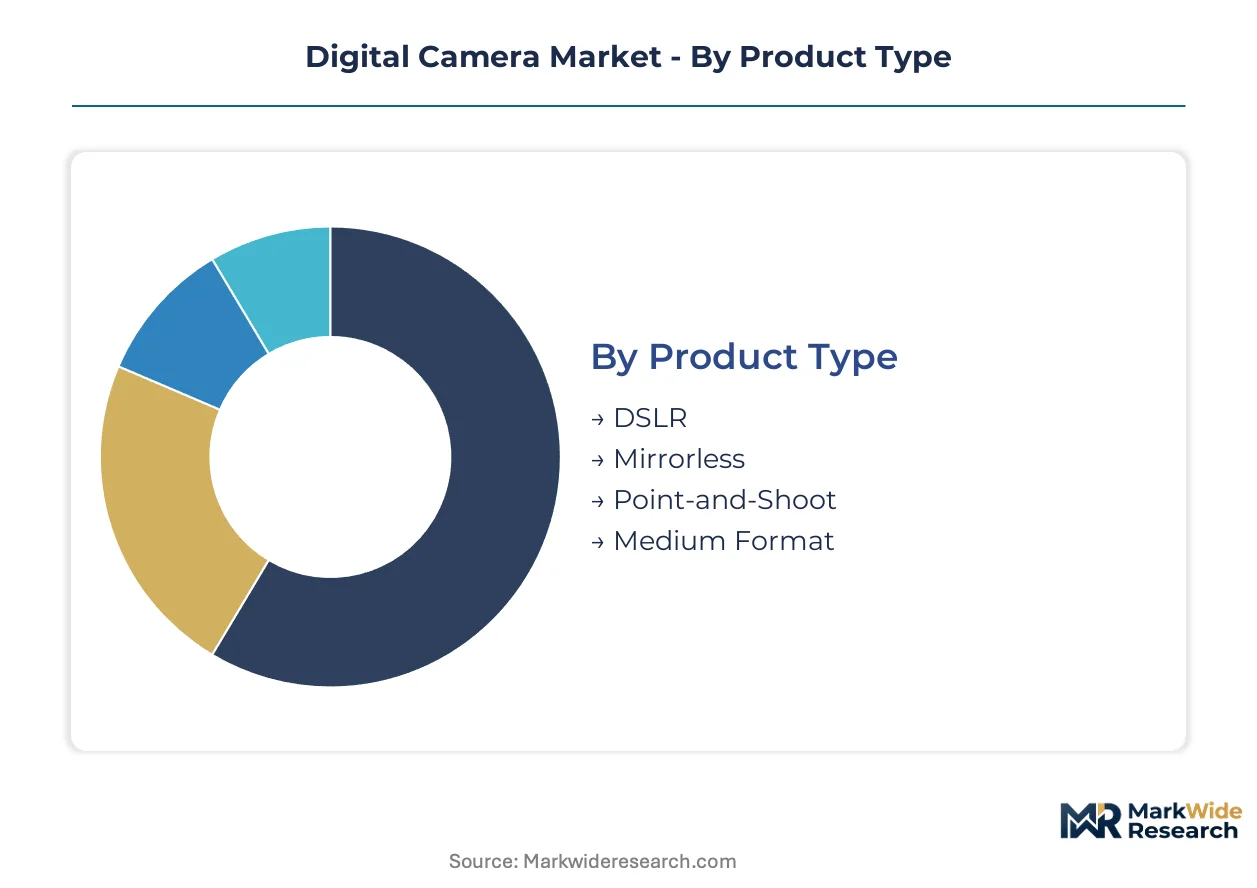
The digital camera market's segmentation reveals distinct demand patterns and technological preferences across various user groups. Understanding these divisions allows manufacturers to tailor product development and marketing strategies effectively. This analysis identifies key segments driving innovation and revenue within the evolving imaging landscape.
Product Type:
The product type segment reflects a maturity spectrum, with legacy systems giving way to advanced digital imaging platforms.
- DSLR:Digital Single-Lens Reflex cameras utilize a mirror mechanism for optical viewing and digital capture. This traditional form factor still serves photographers prioritizing optical viewfinders.
- Mirrorless:Mirrorless cameras employ an electronic viewfinder and directly project light onto the sensor. Demand concentrates among content creators and videographers in the United States, driven by superior video capabilities and advanced autofocus systems.
- Point-and-Shoot:These compact, fixed-lens cameras offer simplicity for casual users. The market for point-and-shoot cameras has significantly eroded due to smartphone substitution.
- Medium Format:Medium format cameras feature larger sensors than full-frame, delivering exceptional image quality and resolution. Professional studios and high-end commercial photographers in Germany increasingly adopt these systems for their unparalleled detail and artistic output.
Mirrorless retains volume leadership; Medium Format holds the steepest expansion curve.
Sensor Technology:
Volume concentration within sensor technology reflects the widespread adoption of specific sensor types across various camera systems.
- CMOS:Complementary Metal-Oxide Semiconductor sensors convert light into digital signals with high efficiency and low power consumption. This technology is foundational across digital cameras, with demand from all segments for its versatility and performance.
- CCD:Charge-Coupled Device sensors historically offered high image quality but have largely been supplanted by CMOS. Niche applications in scientific imaging still utilize CCD sensors.
- BSI CMOS:Back-Side Illuminated CMOS sensors improve light gathering by placing wiring behind the photosensitive layer. Professional videographers and low-light specialists in North America increasingly demand BSI CMOS for its enhanced sensitivity and dynamic range.
- Foveon X3:Foveon X3 sensors capture full color information at each pixel location, offering distinct image characteristics. Enthusiasts appreciate the unique rendering capabilities of these specialized sensors.
CMOS sensor technology maintains dominant market share; BSI CMOS is gaining share fastest due to performance advantages.
Application:
Customer type focus dictates application segment growth, with professionals requiring specialized tools for their distinct workflows.
- Wildlife Photography:This application demands rapid autofocus, high burst rates, and weather sealing for capturing unpredictable subjects. Sports and wildlife photographers in the United States drive demand for high-performance telephoto systems and AI-powered tracking.
- Event Coverage:Event photography and videography require robust low-light performance, reliable autofocus, and efficient data handling. Professional media houses in the United Kingdom prioritize these features for weddings, concerts, and corporate functions.
- Scientific Research:Scientific applications often involve specialized cameras for microscopy, astrophotography, and industrial inspection. Researchers require precise control and specific spectral responses.
- Surveillance:Digital cameras are integrated into security systems for monitoring and recording. Industrial and public sector clients utilize these for continuous operational oversight.
Event Coverage commands significant market volume; Wildlife Photography exhibits a strong growth trajectory.
Customer Type:
Margin profiles vary significantly across customer types, influencing manufacturers' strategic focus and product offerings.
- Professional Photographers:These users require top-tier image quality, robust build, and extensive lens ecosystems for commercial work. Demand from professional photographers in major media hubs like New York and Berlin drives high-margin sales of flagship camera bodies and specialized optics.
- Enthusiasts:Enthusiasts seek advanced features and creative control beyond smartphones, often investing in interchangeable lens systems. This segment represents a larger volume base for mid-range mirrorless cameras and a diverse range of lenses.
- Content Creators:Independent content creators prioritize video capabilities, connectivity, and compact form factors for online platforms. Vloggers and social media influencers drive demand for hybrid still/video cameras.
- Hobbyists:Casual users seek ease of use and improved image quality over smartphones for personal memories. This segment often opts for entry-level mirrorless or advanced compact cameras.
Professional Photographers maintain the highest average transaction value; Content Creators demonstrate the most dynamic purchasing behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor fabrication for digital cameras concentrates in East Asia, while professional demand for high-end systems drives innovation in Western markets. This geographical bifurcation influences product development and market access strategies. Manufacturers navigate diverse regulatory landscapes and customer preferences across key regions.
United States
Demand for high-fidelity 4K and 8K video capabilities drives mirrorless system sales in the United States. FCC certifications are critical for wireless functionalities in digital cameras sold here. Major media production hubs in Los Angeles and New York sustain a stable market for high-end cinema cameras and professional services.
Germany
Professional photographers and videographers in Germany show concentrated demand for high-end digital cameras. CE marking is a mandatory market access requirement for products sold across the European Union. Berlin's creative industries and Munich's industrial sector contribute to sustained demand for specialized imaging equipment.
Japan
Technological innovation and sensor manufacturing expertise position Japan as a critical hub for digital camera production. METI regulations influence the industry's focus on advanced materials and energy efficiency. Tokyo's electronics industry clusters and Osaka's precision manufacturing facilities drive continuous advancements in imaging technology.
China
The large consumer market and burgeoning content creator segment in China fuel demand for hybrid still/video cameras. GB standards ensure product quality and safety for electronics distributed within the country. Shenzhen's electronics manufacturing ecosystem supports both domestic brands and global supply chains for camera components.
United Kingdom
Event photography and videography in the United Kingdom require robust low-light performance and efficient data handling. RoHS directives influence material sourcing for electronic components across Europe, including the UK. London's vibrant media houses and creative agencies prioritize advanced camera systems for commercial and artistic projects.
Digital Camera Market Key Industry Players
Specialized hardware manufacturers and diversified electronics conglomerates split the digital camera market. The industry structure exhibits a tiered approach, with premium brands targeting professionals and volume players serving enthusiasts. Strategic archetypes include sensor technology innovators and ecosystem builders. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Among the diversified electronics conglomerates, Japan-based Sony Group Corp. represents a leader in sensor technology innovation, leveraging its deep expertise across various product lines. This focus on foundational technology allows Sony to drive advancements in image quality and autofocus performance. Canon Inc., another Japan-based corporation, exemplifies an ecosystem builder, sustaining its market position through an extensive lens portfolio and established professional support networks. Canon's long-standing presence in the professional segment underscores its commitment to comprehensive user solutions. FUJIFILM Holdings Corp., also from Japan, occupies a distinct position with its proprietary film simulations and unique camera aesthetics, appealing to a specific enthusiast and professional niche.
| Leading Market Players |
|---|
| Canon Inc. |
| Sony Group Corp. |
| Nikon Corp. |
| FUJIFILM Holdings Corp. |
| Panasonic Holdings Corp. |
| OM Digital Solutions Inc. |
| Leica Camera AG |
| GoPro Inc. |
| SZ DJI Technology Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Sensor fabrication dependency, concentrated in East Asia, dictates both digital camera pricing tier spreads and the overall supply chain shape. This reliance on specialized foundries creates potential for supply volatility, directly impacting manufacturing costs and retail pricing strategies across premium and enthusiast segments.
Pricing Analysis
CE marking dictates the pricing tier structure for digital cameras sold within the European Union, influencing product design and cost. The dominant pricing model is a tiered structure across premium, mid-range, and entry-level offerings. Price differentiation stems from sensor quality grade and brand premium, allowing manufacturers to command higher values for advanced systems. Pricing pressure stems from smartphone substitution in the entry-level segment, eroding margins for basic models. Professional photographers exhibit the least price sensitivity, prioritizing performance and reliability, while hobbyists remain highly price-sensitive.
Supply Chain Analysis
Semiconductor export controls could significantly limit technology flows for advanced image sensors, impacting global supply. The digital camera supply chain draws heavily from East Asia, with key component manufacturing concentrated in Japan, South Korea, and China. Dependencies include advanced CMOS image sensors, specialized optical glass, and high-performance processors. Single-source vulnerability for critical sensor components represents a significant structural risk. Distribution runs through a mix of specialized electronics retailers, online marketplaces, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital camera market operates as a high-growth disruption, driven by the continuous evolution of AI-powered autofocus systems and computational photography.
For Market Incumbents: Insulate core professional market share by deepening vertical integration into proprietary sensor and processor development. Expand professional support networks and cloud service offerings to enhance ecosystem loyalty, countering threats from emerging software-centric solutions. Invest heavily in AI R&D to maintain a performance edge over advanced smartphone capabilities.
For New Entrants and Emerging Players: Pursue white-space opportunities in specialized B2B applications such as machine vision and industrial inspection, leveraging sensor technology expertise. Target the burgeoning content creator segment with hybrid still/video cameras featuring robust connectivity and intuitive software. A direct-to-consumer go-to-market angle with subscription-based post-processing and cloud services can foster early loyalty.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors technology innovators and ecosystem builders. Long-term viability hinges on the ability to generate recurring revenue from software and services, rather than hardware alone. Target acquisition profiles include AI software developers specializing in imaging algorithms or companies with strong cloud infrastructure. The signal to watch is the adoption rate of embedded 5G and direct-to-cloud workflows among professional users.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI-Powered Autofocus R&D | This enhances camera performance for sports and wildlife photographers, a high-margin customer base. |
| Expand Cloud Service Offerings | This builds recurring revenue streams and strengthens ecosystem loyalty for professional users. |
| Invest in Machine Vision Adaptation | This opens new B2B revenue streams beyond traditional consumer and media markets. |
| Standardize USB-C Port Integration | This ensures regulatory compliance in the European Union while simplifying user experience. |
| Develop Advanced Film Simulation Algorithms | This differentiates product lines for FUJIFILM Holdings Corp. and appeals to creative professionals. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market reports anchors the qualitative findings of this study. The research involved discussions with professional photographers, videographers, R&D engineers, and product managers across major camera manufacturers. Secondary data sources included company annual reports, technology journals, electronics trade publications, and government export/import data, supporting both bottom-up and top-down triangulation.
The analytical framework calibrated market volume and value across the analysis window, modeling segmentation dimensions including product type, sensor technology, application, customer type, and regional demand. Compound Annual Growth Rates (CAGRs) were derived through a regression analysis of historical data and projected forward. Industry-specific forecast inputs included sensor manufacturing capacity and content creator growth rates.
Sensitivities concentrate around technological breakthroughs, regulatory shifts, and supply chain disruptions. Forecasts reflect assumptions regarding the continued professionalization of content creation and advancements in computational photography. Material shifts in semiconductor supply volatility or smartphone camera capabilities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Mobile Camera Module Market
Imaging
PET Imaging Systems Market
Imaging
Fiducial Markers Market
Imaging
Hybrid Imaging Systems Market
Imaging
Ent Cameras Market
Imaging
Underwater Camera Market
Imaging
High-Power Objective Lens Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
High-Speed Camera Market
Imaging
Photoacoustic Microscope Market
Imaging
Smart Camera Market
Imaging
In Vivo Imaging Systems Market
Imaging
Compact Camera Module Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Light Field Market