
 Infrared Imaging Software Market | 2026-2036
Infrared Imaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Imaging Software Market Outlook
The EU Green Deal is broadening the addressable market for infrared diagnostics in building energy audits and industrial emissions monitoring. Teledyne FLIR LLC leverages its captive sensor-to-software stack to dominate defense and industrial verticals. BAE Systems anchors its position through deep integration with UK and NATO military procurement channels. Leonardo S.p.A. competes on European sovereignty credentials, sustaining R&D intensity in dual-use thermal systems.
Infrared imaging software processes thermal radiation data captured by uncooled or cooled detector arrays, converting raw sensor output into interpretable visual maps with temperature accuracy typically within two degrees Celsius; its core purpose is to enable non-contact measurement for condition monitoring, security screening, and scientific observation. Software solutions command the deepest margin pools because recurring licensing and analytics subscriptions outpace hardware commoditization cycles. Cloud-based deployment is the fastest-expanding configuration as edge-to-cloud architectures reduce latency for real-time surveillance and predictive maintenance workflows. The industrial end-user segment remains the volume anchor, though military buyers sustain premium pricing through classified-feature requirements.
The US FAA and NHTSA shape commercial and automotive thermal vision standards, while EMA and EU AI Act obligations govern healthcare and algorithmic analytics deployment across Europe. Compliance with CE marking and REACH material restrictions affects sensor import pathways and software localization requirements. Stakeholders must weigh sovereign data residency mandates against the cost of region-specific cloud infrastructure as procurement rules tighten.
Market Dynamics
The migration from on-premise thermal analytics to edge-to-cloud architectures is compressing deployment timelines and forcing software vendors to rebuild licensing models around consumption rather than perpetual seats. NATO defense procurement channels are accelerating this shift by mandating interoperability standards that privilege modular, API-first platforms.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare and security deployers must demonstrate algorithmic transparency for thermal diagnostic systems, creating pull for explainable AI modules in infrared analytics stacks.
- Automotive predictive maintenance:German steel and automotive producers in the Ruhr industrial corridor are integrating thermal monitoring into Industry 4.0 platforms to reduce unplanned downtime.
- Uncooled microbolometer advances:Sensor cost curves below cooled alternatives are expanding addressable volume in building energy audits and agricultural monitoring.
Market Restraints
- Germanium supply concentration:Optical substrate production clusters in China and Russia expose lens assembly costs to geopolitical disruption and export control friction.
- GDPR data residency requirements:Cloud-deployed thermal analytics face mandatory EU sovereign hosting, inflating infrastructure costs versus US or Asian alternatives.
- Silicon photonics substitution:Emerging SWIR sensors threaten traditional thermal imaging in semiconductor inspection and certain machine vision applications.
Strategic Opportunities
- EU Green Deal building retrofits:Mandatory energy performance certificates across member states are creating standardized demand for thermal audit software in residential and commercial property markets.
- Drone-based agricultural monitoring:Brazilian and Australian precision farming operators are adopting thermal crop-stress analytics for irrigation optimization.
- 5G-enabled edge processing:Convergence of cellular low-latency networks with on-device inference is enabling real-time thermal analytics without dedicated ground infrastructure.
Industry Challenges
- Thermal-radiometry software engineering scarcity:The intersection of physics-based modeling and machine learning deployment requires specialized talent pools concentrated in defense-adjacent labor markets.
- CE marking and MDR certification timelines:Medical thermal imaging software faces extended validation periods that delay revenue recognition and compress development runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Imaging Software Market |
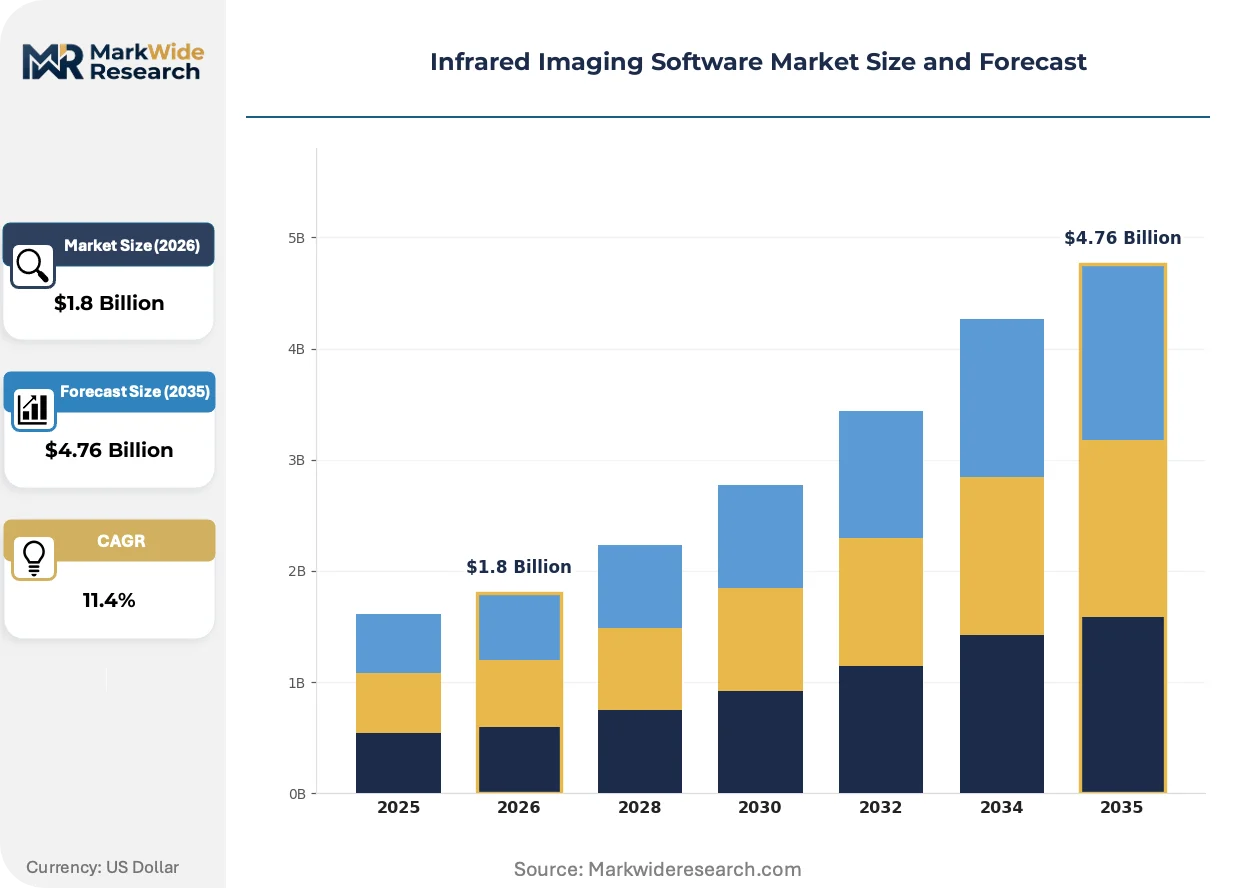
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
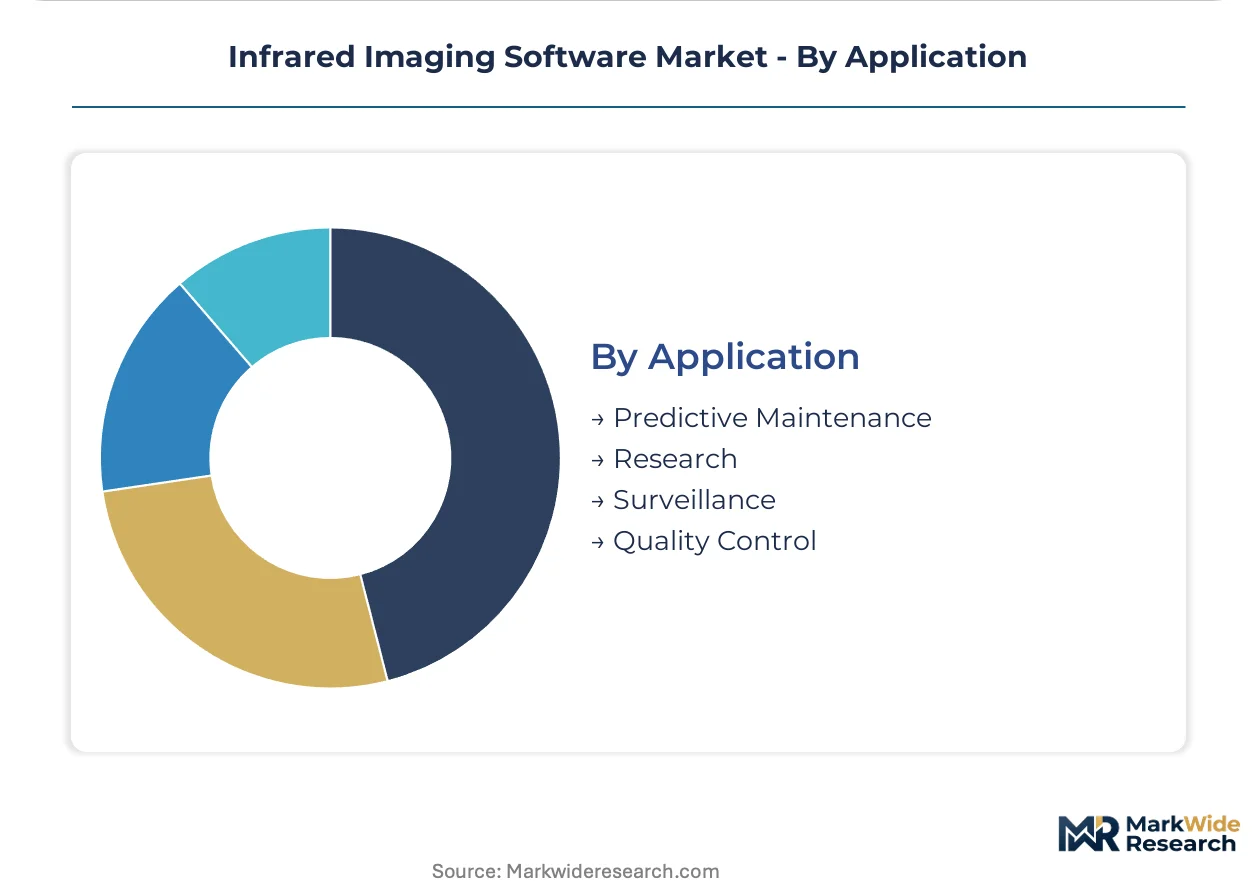
| Segmentation | Product Type: Thermal Cameras, Software Solutions, Accessories, Sensors End User: Industrial, Healthcare, Military, Building Inspection Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Predictive Maintenance, Research, Surveillance, Quality Control |
| Companies Covered | Teledyne FLIR LLC, Fluke Corporation, Axis Communications AB, BAE Systems, L3Harris Technologies, Leonardo S.p.A., Fortive Corp., Honeywell International Inc., Testo SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Imaging Software Market Strategic Shifts
Software-defined thermal sensing is displacing hardware-centric product architectures, with analytics engines now determining competitive differentiation more than detector specifications. Vendors are racing to embed computer vision pipelines directly into edge devices.
Sensor fusion middleware is unifying thermal, visible-light, and LiDAR data streams into single coherent scene interpretations. Automotive OEMs and autonomous vehicle developers are adopting these stacks for 24-hour perception redundancy. The technology is unifying previously siloed procurement budgets for vision hardware and analytics software into consolidated platform contracts.
The EU AI Act's risk-classification framework for biometric and safety-critical applications is forcing thermal analytics vendors to document training data provenance and model drift monitoring. Industrial deployers in Germany and France are prioritizing vendors with pre-certified algorithmic audit trails. Healthcare thermal diagnostics face the steepest compliance burden, with notified body involvement required for clinical decision-support features.
Defense and industrial buyers are consolidating vendor relationships around integrated sensor-to-software stacks, reducing the number of approved suppliers per thermal surveillance program. This concentration favors vendors with captive detector manufacturing or exclusive distribution partnerships. The shift is most pronounced in UK and NATO procurement channels, where interoperability certification costs now exceed the economics of multi-vendor integration.
Infrared Imaging Software Market Segmentation
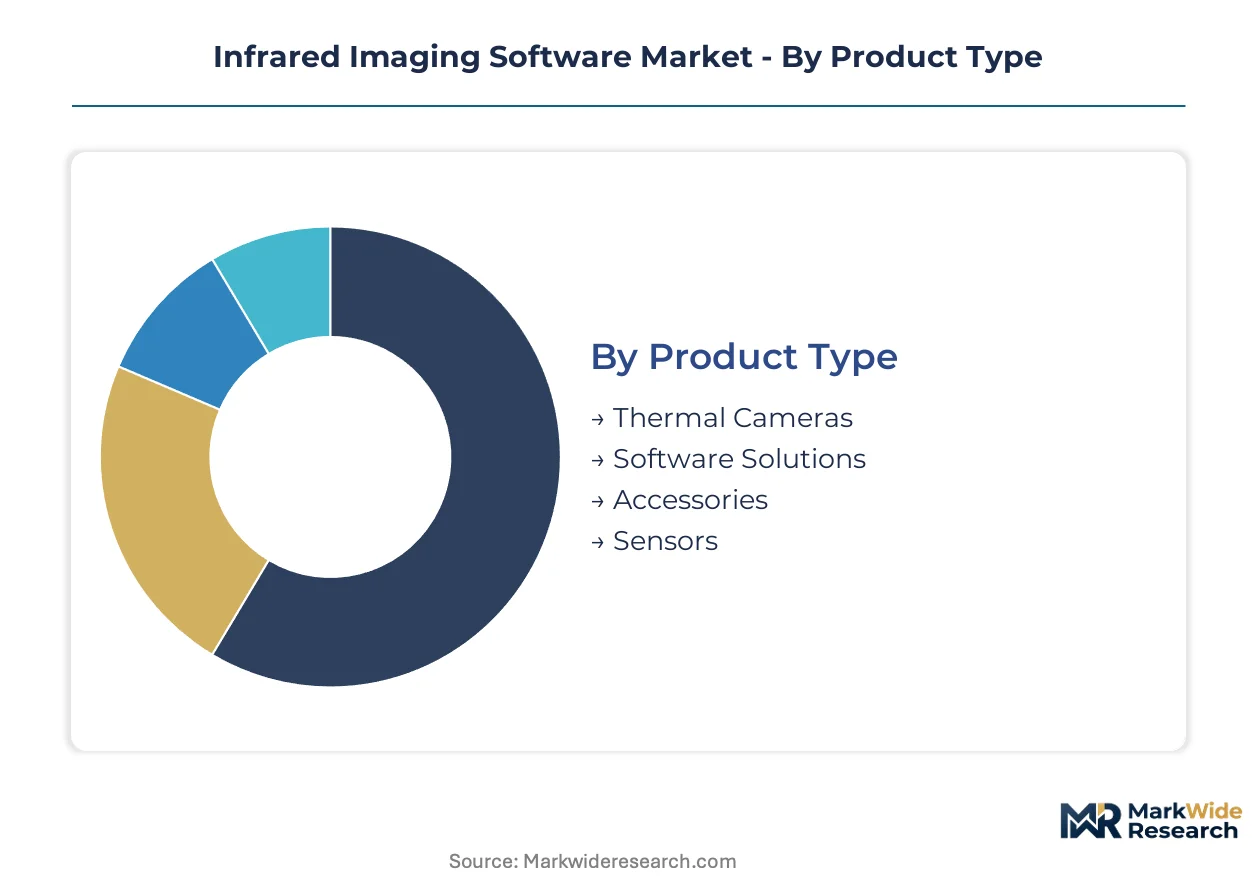
Segmentation in infrared imaging software reveals how procurement priorities diverge across buyer archetypes. Defense agencies prioritize sovereign data handling and classified-feature access, while industrial operators optimize for integration latency and predictive maintenance ROI. Understanding these fault lines clarifies where vendors must build distinct capability bundles versus unified platforms.
Product Type:
Cost tier separates buyers seeking capital expenditure control from those prioritizing recurring operational flexibility.
- Software Solutions:Licensing and analytics subscriptions generate recurring revenue streams with margin profiles superior to hardware commoditization cycles. German automotive producers in the Ruhr corridor favor SaaS thermal analytics for predictive maintenance platforms, drawn by consumption-based scaling and reduced IT overhead.
- Thermal Cameras:Hardware-software bundles dominate defense procurement channels where NATO interoperability standards mandate modular, API-first architectures. UK military programs specify integrated sensor-to-software stacks to reduce multi-vendor certification burdens.
- Sensors:Uncooled microbolometer arrays from captive manufacturing lines anchor volume in building energy audits and agricultural monitoring applications.
- Accessories:Optical substrates and lens assemblies face germanium supply concentration risks from China and Russia production clusters.
Volume sits with Software Solutions; growth tilts toward Sensors as uncooled cost curves expand addressable markets.
End User:
Application maturity determines whether buyers seek turnkey platforms or specialized diagnostic modules.
- Industrial:Steel and automotive producers integrate thermal monitoring into Industry 4.0 workflows to compress unplanned downtime. The EU Green Deal's mandatory energy performance certificates are standardizing demand across member states.
- Military:Classified-feature requirements sustain premium pricing through deep integration with UK and NATO procurement channels. Leonardo S.p.A. competes on European sovereignty credentials in this segment.
- Healthcare:Thermal diagnostic software faces EMA and EU AI Act compliance burdens with extended notified body validation timelines.
- Building Inspection:Residential and commercial property markets are expanding under EU Green Deal retrofit mandates.
Industrial buyers anchor current volume; healthcare applications face the steepest regulatory climb.
Deployment:
Latency tolerance and data sovereignty requirements partition buyers between localized and distributed architectures.
- Cloud-Based:Edge-to-cloud architectures reduce latency for real-time surveillance and predictive maintenance workflows. GDPR data residency mandates inflate infrastructure costs versus US alternatives.
- Edge Computing:5G-enabled cellular networks converge with on-device inference to enable real-time analytics without dedicated ground infrastructure.
- Hybrid:Brazilian and Australian precision farming operators adopt split architectures for drone-based crop-stress monitoring.
- On-Premises:Defense and classified industrial programs retain localized deployment for air-gapped security requirements.
Cloud-Based deployment is expanding most quickly; Edge Computing is gaining share fastest in agricultural and autonomous vehicle applications.
Application:
Return-on-investment measurability separates buyers with operational cost reduction mandates from those funding exploratory research.
- Predictive Maintenance:German steel producers quantify thermal monitoring ROI through downtime reduction metrics. Automotive OEMs integrate these stacks into 24-hour perception redundancy systems.
- Surveillance:NATO defense procurement channels mandate interoperability standards privileging modular platforms. Teledyne FLIR LLC leverages captive sensor-to-software integration here.
- Quality Control:Semiconductor inspection faces substitution pressure from emerging SWIR silicon photonics sensors.
- Research:Scientific observation applications require physics-based modeling expertise concentrated in defense-adjacent labor markets.
Predictive Maintenance commands the deepest margin pools; Surveillance sustains premium pricing through classified procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European demand for predictive maintenance platforms, while defense procurement channels across NATO member states sustain premium pricing for thermal surveillance systems.
Germany
Automotive and steel producers in the Ruhr corridor integrate thermal monitoring into Industry 4.0 workflows to compress unplanned downtime. The EU Green Deal mandates energy performance certificates for buildings, expanding addressable markets for audit software. KBA certification requirements shape automotive thermal vision deployment standards.
United States
FAA and NHTSA regulations govern commercial aviation and automotive thermal vision standards, creating compliance-driven procurement patterns. Defense agencies prioritize sovereign data handling through classified-feature access contracts. The FAA's airworthiness directives for thermal imaging in commercial aircraft sustain specialized vendor relationships.
United Kingdom
BAE Systems anchors defense procurement through deep integration with UK and NATO military channels. The UK Ministry of Defence's interoperability standards mandate modular, API-first platform architectures. London-based security contractors adopt cloud-deployed analytics for critical infrastructure monitoring.
France
ANSM and CNIL obligations govern healthcare thermal diagnostics and biometric data handling respectively. Leonardo S.p.A. competes on European sovereignty credentials in dual-use thermal systems. The Île-de-France aerospace cluster sustains R&D intensity for defense-adjacent applications.
Italy
Industrial automation demand concentrates in the Emilia-Romagna machinery corridor. CE marking and REACH material restrictions affect sensor import pathways and software localization requirements. Milan-based system integrators bundle thermal analytics into smart building retrofits under EU Green Deal mandates.
Infrared Imaging Software Market Competitive Environment
The competitive structure tilts toward integrated sensor-to-software stacks rather than point solutions. Defense and industrial buyers consolidate vendor relationships, reducing approved suppliers per thermal surveillance program. Three archetypes dominate: captive sensor manufacturers with proprietary software layers, defense primes with deep procurement channel integration, and industrial instrumentation specialists with predictive maintenance expertise. M&A activity concentrates on analytics capability acquisition, while geographic expansion targets EU Green Deal retrofit markets.
Among defense primes with European sovereignty positioning, Leonardo S.p.A. and BAE Systems exemplify the procurement-channel-anchored archetype. Teledyne FLIR LLC occupies the integrated sensor-to-software tier, representing captive manufacturing advantages. Within industrial instrumentation, Fluke Corporation and Testo SE & Co. KGaA sit within the predictive maintenance specialist category, leveraging recurring licensing models against hardware commoditization.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Fluke Corporation |
| Axis Communications AB |
| BAE Systems |
| L3Harris Technologies |
| Leonardo S.p.A. |
| Fortive Corp. |
| Honeywell International Inc. |
| Testo SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Captive sensor-to-software integration anchors both supply security and pricing power for defense-grade thermal systems, with vendors controlling detector manufacturing commanding premium positioning against modular competitors facing germanium lens assembly bottlenecks from China and Russia production clusters.
Pricing Analysis
Uptime-linked value-based pricing dominates industrial predictive maintenance contracts, with German automotive producers in the Ruhr corridor paying consumption-scaled SaaS tiers tied to downtime reduction outcomes. Price differentiation rests on algorithmic transparency certification under EU AI Act risk-classification frameworks and sovereign data residency guarantees. Pricing pressure stems from uncooled microbolometer cost curves expanding addressable volume in building energy audits. Industrial operators exhibit highest price sensitivity, while NATO defense procurement channels sustain premium tiers through classified-feature requirements.
Supply Chain Analysis
Specialized thermal-radiometry software engineering pools concentrate in defense-adjacent labor markets across the United States, United Kingdom, and Germany, constraining rapid capacity expansion for explainable AI module development. Optical substrate production draws from germanium refining concentrated in China and Russia, creating single-source vulnerability for lens assembly costs. Distribution runs through NATO interoperability-certified channel partners and industrial system integrators in the Emilia-Romagna machinery corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined thermal sensing is displacing hardware-centric architectures, with edge-embedded computer vision pipelines rendering legacy detector-specification competition obsolete.
For Market Incumbents: Deepen captive manufacturing control over uncooled microbolometer arrays to offset germanium supply concentration risks from China and Russia. Consolidate algorithmic audit trail certification under EU AI Act frameworks before notified body validation timelines compress development runway for healthcare thermal diagnostics. For New Entrants and Emerging Players: Enter via drone-based agricultural monitoring in Brazil and Australia, where precision farming operators seek thermal crop-stress analytics without incumbent defense channel relationships. Pursue 5G-enabled edge processing partnerships to bypass dedicated ground infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in analytics capability acquisition by industrial instrumentation specialists seeking recurring licensing models against hardware commoditization. Long-term viability favors vendors with pre-certified sovereign data handling and modular API-first architectures. Watch silicon photonics SWIR substitution pressure in semiconductor inspection as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Analytics capability targets compress multi-vendor certification burdens under NATO interoperability mandates. |
| Platform Integration | Sensor fusion middleware unifies thermal, visible-light, and LiDAR streams for automotive OEM perception redundancy. |
| Strategic Partnership | 5G cellular network alliances enable real-time edge inference without dedicated ground infrastructure investment. |
| Geographic Expansion | EU Green Deal retrofit markets in Milan and Emilia-Romagna standardize thermal audit software procurement. |
| Product Launch | Explainable AI modules address EU AI Act algorithmic transparency mandates for healthcare and security deployers. |
Study Parameters
Trade databases, regulatory filings, and hyperscaler capex disclosures formed the secondary backbone, supplemented by primary interviews with defense procurement officers, industrial maintenance directors, platform integration specialists, and thermal camera OEM product managers. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Historical trendline analysis across deployment model, end-user vertical, and regional adoption pattern dimensions informed projection mechanics. CAGRs derived from segment-level growth rate reconciliation with input-output modeling of sensor cost curves and regulatory compliance burden trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under germanium export control friction or accelerated silicon photonics substitution in machine vision. Material deviation in NATO interoperability certification timelines or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
AI-Based Fever Detection Camera Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Instant Digital Cameras Market
Imaging
Acoustic Microscopy Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Japan Digital X-Ray Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Document Imaging Market
Imaging
Global 4K Camera Market
Imaging
Europe IP Camera Market
Imaging
Microscopic Camera Market
Imaging
Industrial Computed Tomography Market
Imaging
X-Ray Photoelectron Spectroscopy Market