
 Machine Vision System Market | 2026-2036
Machine Vision System Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Vision System Market Intelligence
Automotive quality assurance is recalibrating machine vision procurement priorities as electric vehicle battery inspection protocols multiply defect-detection points. Cognex Corporation leverages deep learning software libraries to anchor North American automotive contracts. KEYENCE Corporation dominates inline 3D measurement with integrated laser profilometer architectures. Sick AG specializes in ruggedized IP69K camera housings for paint-shop and underbody inspection lanes.
Machine vision systems integrate industrial cameras, illumination modules, image-processing hardware, and algorithmic software to automate visual inspection, measurement, and guidance tasks with sub-pixel accuracy. Smart cameras embed DSP and FPGA processing directly on the sensor board, eliminating external PC tethering for high-speed line applications. 3D imaging captures depth maps through structured light or time-of-flight methods, capturing fastest-growing share as robotic bin-picking and dimensional verification requirements spread. Frame grabbers persist in high-bandwidth applications but occupy a mature margin pool as Camera Link and CoaXPress interfaces face displacement by GigE Vision and USB3 Vision standards.
FDA software-as-medical-device guidance and EU MDR Class IIa requirements shape validation burdens for healthcare vision deployments, particularly in surgical navigation and pathology slide scanning. The EU AI Act risk-classification framework forces conformity assessments on autonomous quality decisions in safety-critical manufacturing. Stakeholders must monitor harmonization gaps between FDA predicate-device pathways and EMA notified-body expectations as dual-territory product strategies complicate development roadmaps.
Market Dynamics
Automotive battery inspection protocols are multiplying defect-detection points across electric vehicle assembly lines, forcing recalibration of procurement priorities toward 3D imaging modules with sub-pixel accuracy.
Growth Catalysts
- EU AI Act risk classification:Conformity assessments on autonomous quality decisions in safety-critical manufacturing are accelerating validation investments for vision-based diagnostic tools.
- Electric vehicle battery inspection:Cell-to-pack architectures require 3D profilometry at every weld seam and busbar junction, expanding machine vision deployment density on automotive lines.
- Germany's precision manufacturing corridor:Stuttgart and Munich clusters concentrate demand for inline 3D measurement systems serving automotive OEMs and Tier-1 suppliers.
Market Restraints
- Sensor supply concentration:Sony and ON Semiconductor dominate CMOS image sensor supply for industrial cameras, creating single-source vulnerability for high-resolution variants.
- Validation cost inflation:FDA software-as-medical-device guidance and EU MDR Class IIa requirements extend certification timelines for surgical navigation and pathology applications.
- Limited substitute flexibility:Structured light systems face displacement pressure from time-of-flight methods in robotic bin-picking, stranding prior capital investments.
Strategic Opportunities
- Healthcare vision underpenetration:Surgical navigation and pathology slide scanning remain below saturation in diagnostic laboratories, offering expansion room for validated systems.
- Smart camera edge processing:DSP and FPGA embedding on sensor boards eliminates external PC tethering, opening high-speed line applications previously blocked by latency constraints.
- Interface standard migration:GigE Vision and USB3 Vision adoption creates service and retrofit opportunities as Camera Link and CoaXPress installations age out.
Industry Challenges
- Deep learning engineering scarcity:Convolutional neural network training for defect classification requires specialized talent rarely available in traditional automation engineering teams.
- Harmonization gaps:Dual-territory product strategies face friction between FDA predicate-device pathways and EMA notified-body expectations, complicating development roadmaps.
- Legacy system integration:Brownfield manufacturing environments require protocol bridging between modern vision systems and established PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Vision System Market |
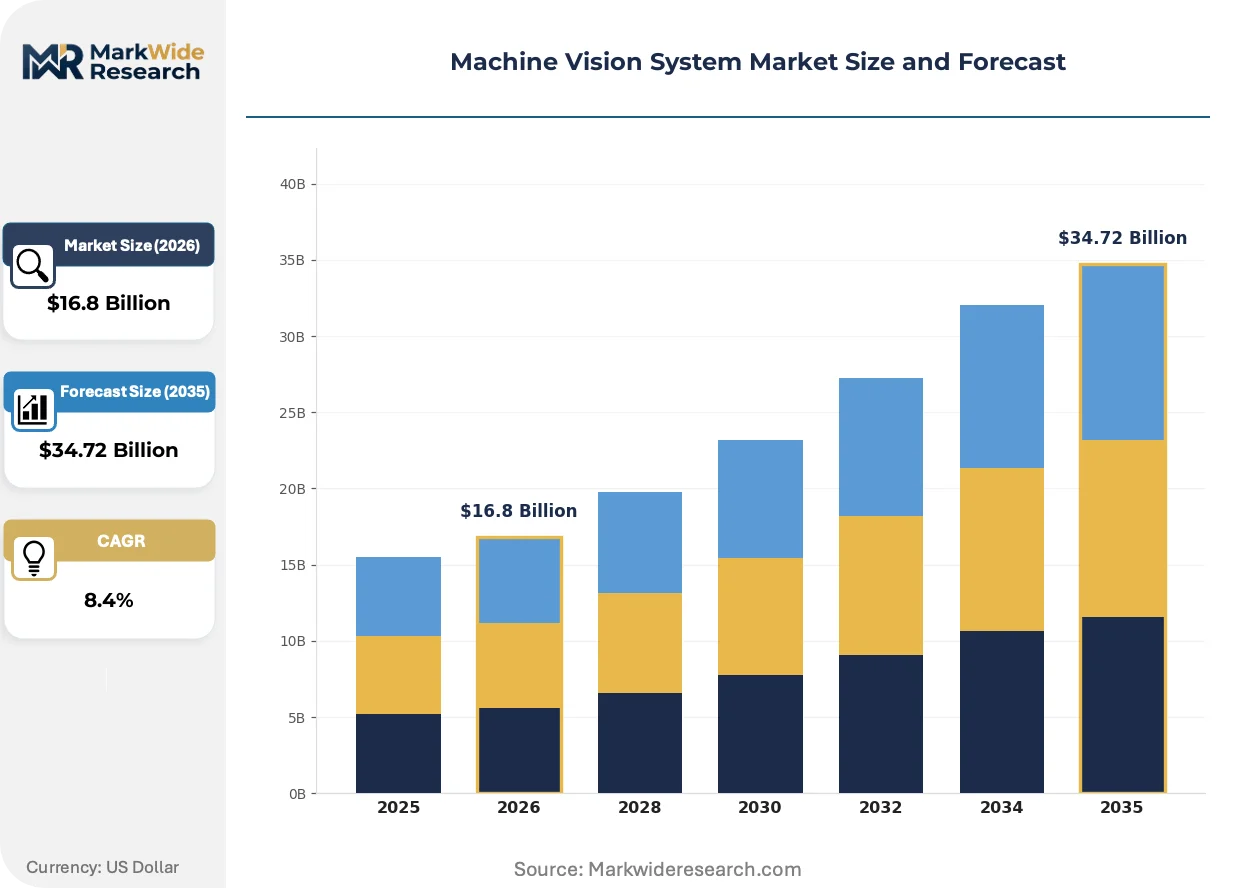
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, Vision Sensors, Frame Grabbers, Processing Units Technology: 2D Imaging, 3D Imaging, Hyperspectral Imaging, Infrared Imaging Application: Quality Assurance, Robotics, Surveillance, Identification End User: Manufacturing, Healthcare, Logistics, Automotive |
| Companies Covered | Basler AG, SensoPart, Cognex Corporation, National Instruments Corporation, Sick AG, KEYENCE Corporation, Omron Corporation, Pleora Technologies, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Vision System Market Strategic Shifts & Innovations
Deep learning software libraries are compressing algorithm development cycles while interface standardization and regulatory risk classification reshape competitive requirements across automotive and healthcare verticals.
Edge inference acceleration is unifying image capture and classification on single sensor boards. Automotive paint-shop and underbody inspection lanes adopt smart cameras with embedded processing to eliminate network latency. This architecture is unifying quality decision-making with mechanical actuation for real-time reject routing.
EU AI Act enforcement is tightening validation documentation for autonomous quality decisions in safety-critical manufacturing. Notified bodies now demand algorithmic transparency logs and bias-testing protocols for high-risk vision deployments. German automotive suppliers are front-loading compliance investments to secure CE marking ahead of 2025 implementation deadlines.
Buyer consolidation among automotive OEMs is compressing supplier qualification cycles and unbundling after-sales service contracts. Tier-1 integrators now demand separate pricing for hardware, software licenses, and maintenance. This procurement restructuring is most visible in Stuttgart and Munich, where battery plant ramp-ups favor vendors offering modular subscription pricing over capital-heavy perpetual licenses.
Machine Vision System Market Segmentation
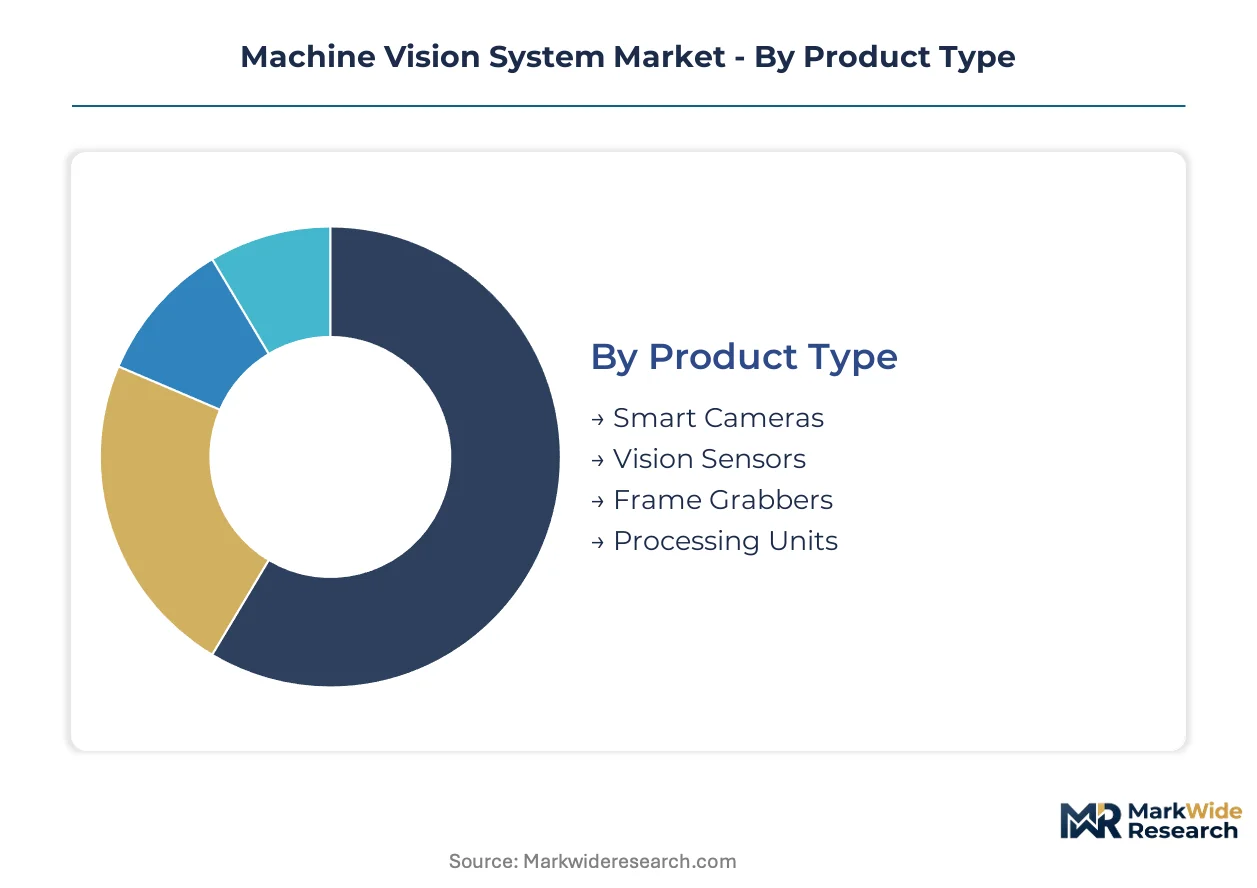
Machine vision procurement splits sharply between capital-intensive inline installations and modular retrofit packages. Buyers weigh embedded processing against external PC architectures based on line speed requirements and legacy infrastructure constraints.
Product Type:
Smart cameras demand the highest upfront engineering investment for DSP and FPGA integration, while frame grabbers require substantial supporting infrastructure.
- Smart Cameras:Embedded DSP and FPGA processing on the sensor board eliminates external PC tethering. Automotive paint-shop lines in Germany's Stuttgart corridor deploy these for real-time reject routing where network latency blocks traditional architectures.
- Vision Sensors:Compact units with pre-configured inspection tools reduce deployment complexity. Logistics hubs across the US Midwest favor these for barcode verification and package dimensioning at high throughput speeds.
- Frame Grabbers:High-bandwidth data acquisition cards persist in semiconductor wafer inspection and flat-panel display manufacturing where Camera Link and CoaXPress interfaces remain entrenched.
- Processing Units:External industrial PCs with GPU acceleration support deep learning model execution for complex defect classification in battery cell manufacturing.
Smart cameras absorb the bulk of installed capacity in new automotive lines; vision sensors are expanding most quickly in logistics retrofit projects.
Technology:
Dimensionality drives equipment cost tiers, with multi-spectral systems commanding premium positioning against monochrome 2D alternatives.
- 2D Imaging:Established grayscale and color camera technology dominates high-volume barcode reading and surface defect detection. Food processing facilities in France rely on these for packaging label verification under ANSM hygiene protocols.
- 3D Imaging:Structured light and time-of-flight methods capture depth maps for robotic bin-picking and dimensional verification. Electric vehicle battery plants in Germany's Munich cluster deploy laser profilometry at every weld seam and busbar junction.
- Hyperspectral Imaging:Spectral signature analysis beyond visible wavelengths enables material composition verification. Agricultural sorting operations use these for foreign object detection in bulk grain processing.
- Infrared Imaging:Thermal capture supports predictive maintenance and heat-seal inspection in pharmaceutical packaging lines regulated by FDA guidance.
2D imaging retains the largest installed base; 3D imaging is climbing the fastest as robotic guidance requirements multiply.
Application:
Quality assurance commands the most comprehensive system integration spend, while surveillance applications leverage commoditized components.
- Quality Assurance:Inline defect detection with sub-pixel accuracy requirements drives the most sophisticated camera and illumination configurations. Tier-1 automotive suppliers in Germany front-load compliance investments for EU AI Act conformity assessments on autonomous quality decisions.
- Robotics:Vision-guided pick-and-place and assembly operations require real-time coordinate transformation. Bin-picking deployments favor time-of-flight 3D methods over structured light for speed advantages.
- Surveillance:Perimeter monitoring and process oversight use lower-resolution cameras with reduced processing demands. Manufacturing facilities integrate these with existing security infrastructure.
- Identification:Optical character recognition and barcode reading support track-and-trace mandates under EU MDR and FDA device regulations.
Quality assurance captures the dominant share of system revenue; robotics applications are gaining share fastest as collaborative robot deployments accelerate.
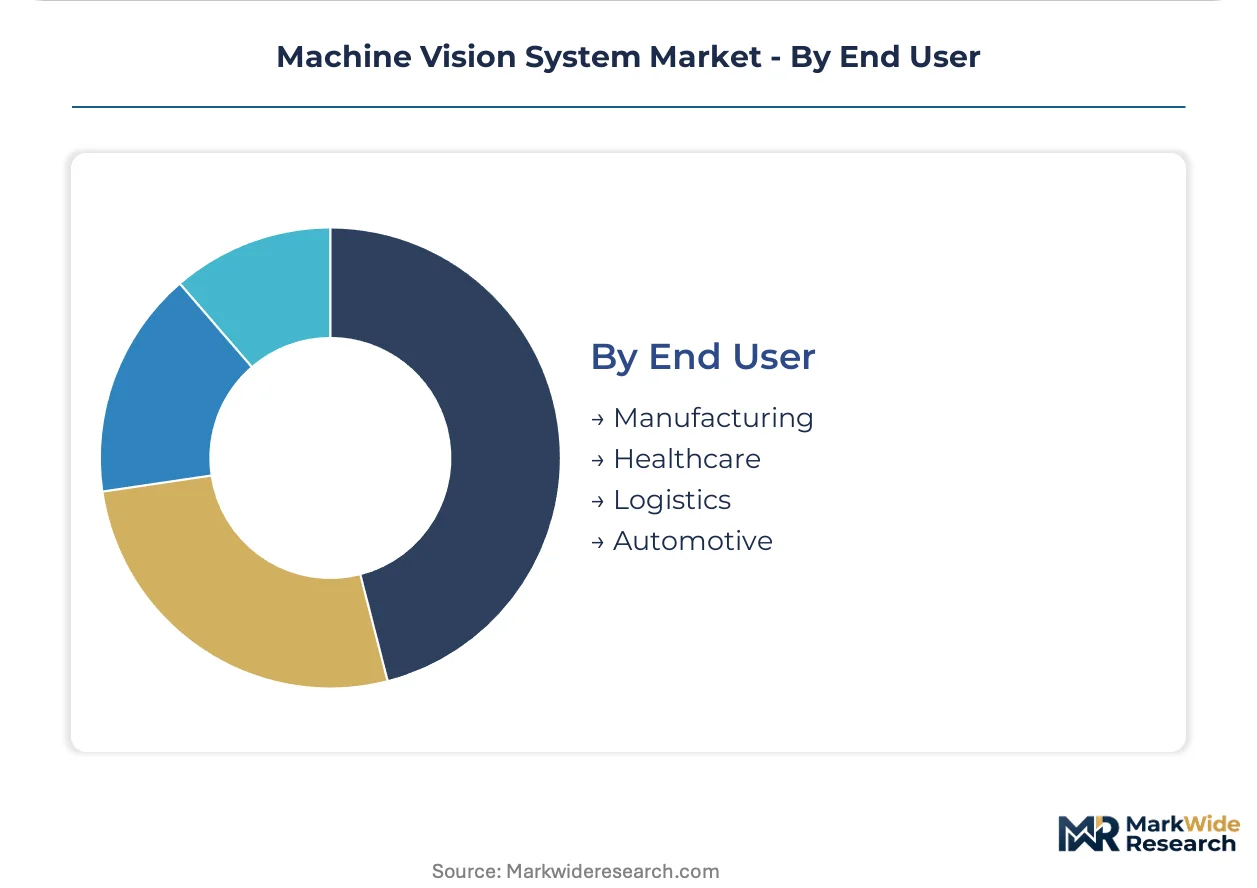
End User:
Automotive manufacturing concentrates the most sophisticated multi-camera installations, while healthcare imposes the steepest validation cost burdens.
- Manufacturing:Discrete and process industries deploy vision across assembly, packaging, and material handling. Precision manufacturing corridors in Germany concentrate demand for inline 3D measurement systems.
- Healthcare:Surgical navigation and pathology slide scanning face FDA software-as-medical-device and EU MDR Class IIa validation requirements. Diagnostic laboratories remain below saturation for validated systems.
- Logistics:E-commerce fulfillment centers drive volume demand for dimensioning and sortation verification. High-speed line applications favor smart cameras with embedded processing to eliminate latency.
- Automotive:Battery inspection protocols for electric vehicles multiply defect-detection points across cell-to-pack architectures. OEM procurement restructuring favors modular subscription pricing over capital-heavy perpetual licenses.
Automotive end users absorb the majority of new capital deployment; healthcare represents the steepest expansion trajectory as diagnostic automation penetrates clinical workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor around Stuttgart and Munich concentrates the densest machine vision deployment in Europe, with tax incentives under the EU Green Deal accelerating battery plant investments that demand inline 3D inspection systems.
United States
FDA software-as-medical-device guidance shapes validation requirements for surgical navigation systems in Boston's medical device cluster. The EPA's industrial emissions monitoring mandates drive vision-based compliance systems across Texas petrochemical corridors. Automotive battery plants in Michigan's Detroit-Toledo corridor are recalibrating procurement priorities toward 3D imaging modules.
Germany
EU AI Act risk-classification frameworks force conformity assessments on autonomous quality decisions in safety-critical manufacturing. KBA automotive safety regulations intersect with MDR Class IIa requirements for vision-guided surgical tools. Stuttgart and Munich clusters concentrate demand for inline 3D measurement systems serving automotive OEMs and Tier-1 suppliers.
China
MIIT smart manufacturing initiatives accelerate machine vision adoption across Yangtze River Delta electronics assembly hubs. GB standards for industrial automation create localization requirements for vision system components. Shenzhen's robotics corridor deploys time-of-flight 3D methods for bin-picking applications at scale.
Japan
METI's Society 5.0 roadmap funds edge-processing vision systems for predictive maintenance in Nagoya's automotive belt. JIS standards for industrial cameras shape procurement specifications across precision manufacturing. Osaka's pharmaceutical packaging lines integrate thermal imaging under PMDA guidance for heat-seal validation.
South Korea
MFDS medical device software regulations extend certification timelines for vision-based diagnostic tools in Seoul's healthcare technology cluster. The government's K-Semiconductor Belt initiative concentrates display panel manufacturing around Gyeonggi Province, driving high-bandwidth frame grabber demand for flat-panel inspection.
Machine Vision System Market Key Industry Players
Top-tier vendors anchor automotive and healthcare verticals with integrated hardware-software stacks, while mid-tier specialists occupy modular retrofit niches. The vendor base stratifies across three tiers: full-stack platform providers, component specialists, and regional system integrators. Two strategic archetypes dominate: deep-learning software licensors and ruggedized hardware fabricators. Competitive moves concentrate on M&A for AI talent acquisition and geographic expansion through distributor partnerships in precision manufacturing corridors.
Within the full-stack platform tier, Cognex Corporation and KEYENCE Corporation exemplify integrated solution architectures that compress deployment complexity for automotive OEMs. Sick AG occupies a position among ruggedized hardware specialists, with IP69K camera housings representing the archetype of paint-shop environmental resilience. Basler AG and Teledyne Technologies sit within the component-specialist vector, anchoring industrial camera supply for system integrators across German and North American manufacturing belts.
| Leading Market Players |
|---|
| Basler AG |
| SensoPart |
| Cognex Corporation |
| National Instruments Corporation |
| Sick AG |
| KEYENCE Corporation |
| Omron Corporation |
| Pleora Technologies |
| Teledyne Technologies |
| Others |
Cost & Logistics Intelligence
Deep learning engineering talent concentration in Germany's Stuttgart precision manufacturing corridor widens labor-cost differentials between premium-tier smart camera systems and economy-tier vision sensor deployments. These labor-cost spreads translate directly into pricing-tier stratification, with embedded processing architectures commanding substantial premiums over external PC-dependent configurations.
Pricing Analysis
Short lead-time premiums dominate machine vision procurement negotiations, with automotive OEMs paying substantial markups for expedited delivery of 3D imaging modules during battery plant ramp-ups. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because logistics hubs favor commoditized vision sensors for high-volume barcode verification. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to EU AI Act compliance deadlines, while mid-sized contract manufacturers remain highly price-sensitive and delay upgrades.
Supply Chain Analysis
CE marking and FDA software-as-medical-device qualification requirements gate supplier entry, extending vendor onboarding timelines for healthcare vision deployments. CMOS image sensor fabrication concentrates in Japan, South Korea, and the United States, with Sony and ON Semiconductor anchoring high-resolution industrial camera supply. Laser profilometer optics and FPGA processing chips represent critical component dependencies. Single-source vulnerability for specialized sensors creates supply chain risk. Distribution runs through authorized system integrators serving Germany's automotive belt and direct OEM relationships in North American medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine vision component supply remains constrained by qualified FPGA engineering capacity, propping pricing power for vendors with captive semiconductor design teams.
For Market Incumbents: Acquire deep learning software libraries and trained convolutional neural network models to defend against pure-play AI entrants. Backward integration into FPGA firmware development secures supply continuity against foundry allocation constraints. Cement channel control through exclusive distributor partnerships in Germany's Stuttgart-Munich corridor. For New Entrants and Emerging Players: The price-point gap between premium smart cameras and economy vision sensors opens white-space opportunity in mid-tier logistics retrofit projects. Target US Midwest e-commerce fulfillment centers with subscription-priced embedded processing units. Pursue modular hardware-software unbundling to bypass incumbent bundled license structures. For Investors and Strategic Acquirers: Re-rating potential sits with ruggedized hardware specialists given EU AI Act enforcement accelerating validation documentation investments. Long-term viability favors vendors with dual automotive-healthcare certification capabilities. Watch algorithmic transparency log requirements as the inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Deep Learning Talent Acquisition | Convolutional neural network expertise anchors differentiation in defect classification algorithms. |
| Modular Subscription Pricing | Unbundled hardware-software-maintenance contracts align with Tier-1 automotive procurement restructuring. |
| EU AI Act Compliance Pre-Investment | Front-loaded validation documentation secures CE marking ahead of notified body bottlenecks. |
| Edge Processing Architecture Migration | DSP-FPGA embedding eliminates network latency for real-time automotive reject routing. |
| Healthcare Validation Pathway Expansion | FDA software-as-medical-device and EU MDR Class IIa certifications unlock diagnostic laboratory penetration. |
Research Approach
Document review covered SEC filings from industrial automation vendors, EU regulatory guidance documents, and automotive OEM procurement disclosures, complemented by interviews with machine vision system engineering directors, Tier-1 supplier procurement managers, biomedical equipment validation specialists, and logistics automation integrators. Secondary validation drew from FDA software-as-medical-device guidance, EU AI Act implementation texts, and German KBA automotive safety regulations. Bottom-up segmentation modeling triangulated against top-down market sizing from component shipment data.
Cross-referencing historical adoption curves with expert panel input shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, imaging technology dimensionality, application function, and end-user industry vertical. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs encompass electric vehicle battery plant construction pipelines and diagnostic laboratory automation penetration rates.
Inputs from regulatory guidance documents and OEM procurement disclosures were available through the study window; gaps in real-time component pricing data introduce uncertainty bands around vendor revenue estimates. Forecasts reflect assumptions regarding EU AI Act enforcement timing and semiconductor foundry capacity allocation. A model refresh is warranted upon material change in battery inspection protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Biophotonics Market
Imaging
Machine Vision System and Services Market
Imaging
China Electron Microscopy Market
Imaging
Chemiluminescence Imaging Market
Imaging
Image Intensifier Market
Imaging
Photography Ring Flash Market
Imaging
Near Infra-Red Imaging Market
Imaging
360-Degree Camera Market
Imaging
Global Microbolometer Market
Imaging
Computational Photography Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
PET Scanners Market
Imaging
Global Document Scanner Market