
 Photo Kiosk Market | 2026-2036
Photo Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Kiosk Market Outlook
Event venues and wedding planners is rotating share away from traditional retail photo services as experiential spending reshapes buyer priorities. DNP Imagingcomm America leverages its manufacturing scale to dominate professional-grade dye-sublimation printing hardware. Simple Booth specializes in streamlined software-hardware bundles that anchor the mobile-integrated rental segment. Photo Booth Supply Co. competes through modular kiosk architectures that reduce freight costs and setup labor for independent operators.
A photo kiosk is a self-contained, automated station that captures, processes, and outputs photographic images through integrated cameras, touchscreens, and thermal or inkjet printers, typically operating at resolutions between 300 and 600 DPI for instant print delivery. These systems serve commercial and social purposes by enabling unattended or attendant-assisted photography at retail, entertainment, and private event locations. Self-service kiosks occupy the largest installed base due to their lower per-unit cost and minimal staffing requirements, while cloud-based solutions represent the fastest-growing technology segment as remote image storage and over-the-air updates reduce on-site maintenance. Interactive kiosks command premium positioning where gesture control, augmented reality filters, and green-screen compositing justify higher rental rates.
FCC certification governs wireless connectivity modules in U.S.-deployed units, while CE marking requirements under EU machinery and electromagnetic compatibility directives shape export-bound product design. GDPR compliance obligations in Europe constrain how customer images are stored, shared, and retained, directly affecting cloud architecture decisions for vendors with transatlantic operations. Stakeholders must weigh regulatory fragmentation against the margin advantages of standardized global platforms.
Market Dynamics
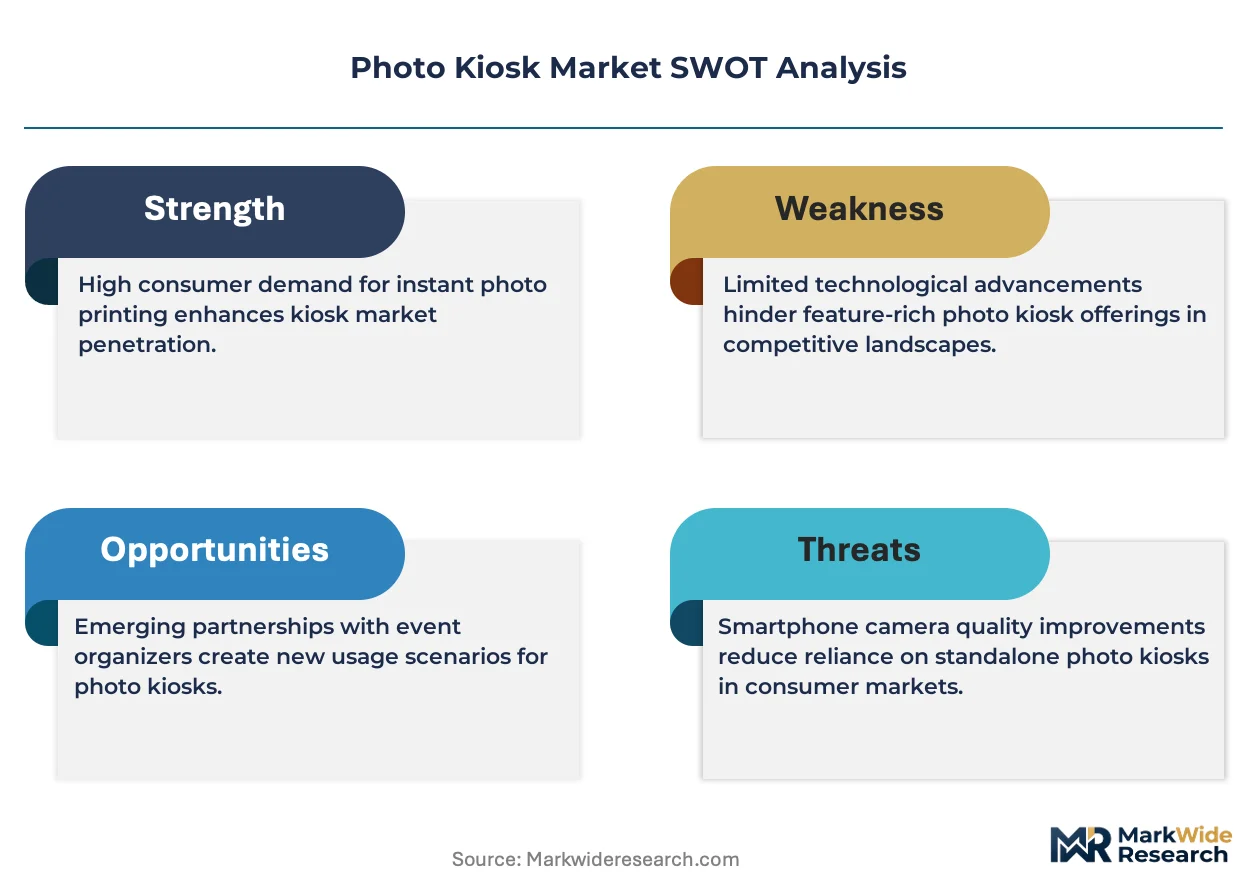
Cloud-based printing technology is decomposing the traditional hardware-centric value chain, forcing vendors to restructure around software subscriptions and remote fleet management rather than unit sales.
Growth Catalysts
- FCC certification mandates for wireless modules:U.S. deployment requirements accelerate standardization of connectivity stacks, reducing engineering overhead for domestic manufacturers.
- Experiential retail spending:Mall operators and brand activations prioritize photo kiosks as dwell-time extenders, driving rental demand in high-footfall locations.
- Dye-sublimation thermal transfer:This printing process delivers archival-grade output durability, sustaining premium pricing in wedding and corporate event segments.
Market Restraints
- Paper and ribbon supply concentration:Specialty consumables production clusters in East Asian manufacturing hubs, exposing operators to freight cost volatility and currency fluctuation.
- Smartphone camera substitution:Native portrait mode and computational photography reduce impulse print demand among casual consumers at retail touchpoints.
- GDPR image retention rules:European cloud storage limitations force architectural fragmentation, raising compliance costs for vendors with transatlantic deployments.
Strategic Opportunities
- India private event expansion:Tier-2 city wedding markets remain undersupplied with attendant-assisted photo kiosk rentals, offering first-mover positioning.
- Augmented reality filter integration:Gesture-controlled overlays and green-screen compositing justify premium rate cards in corporate activation and brand experience budgets.
- PLI scheme electronics manufacturing:Indian production-linked incentives attract component assembly and final integration, reducing import duty exposure for regional fleets.
Industry Challenges
- Legacy POS integration complexity:Event rental operators struggle to reconcile kiosk transaction data with existing accounting and CRM stacks.
- Field technician scarcity:Mechatronics repair skills lag deployment growth, extending mean time to repair and inflating service contract costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Kiosk Market |
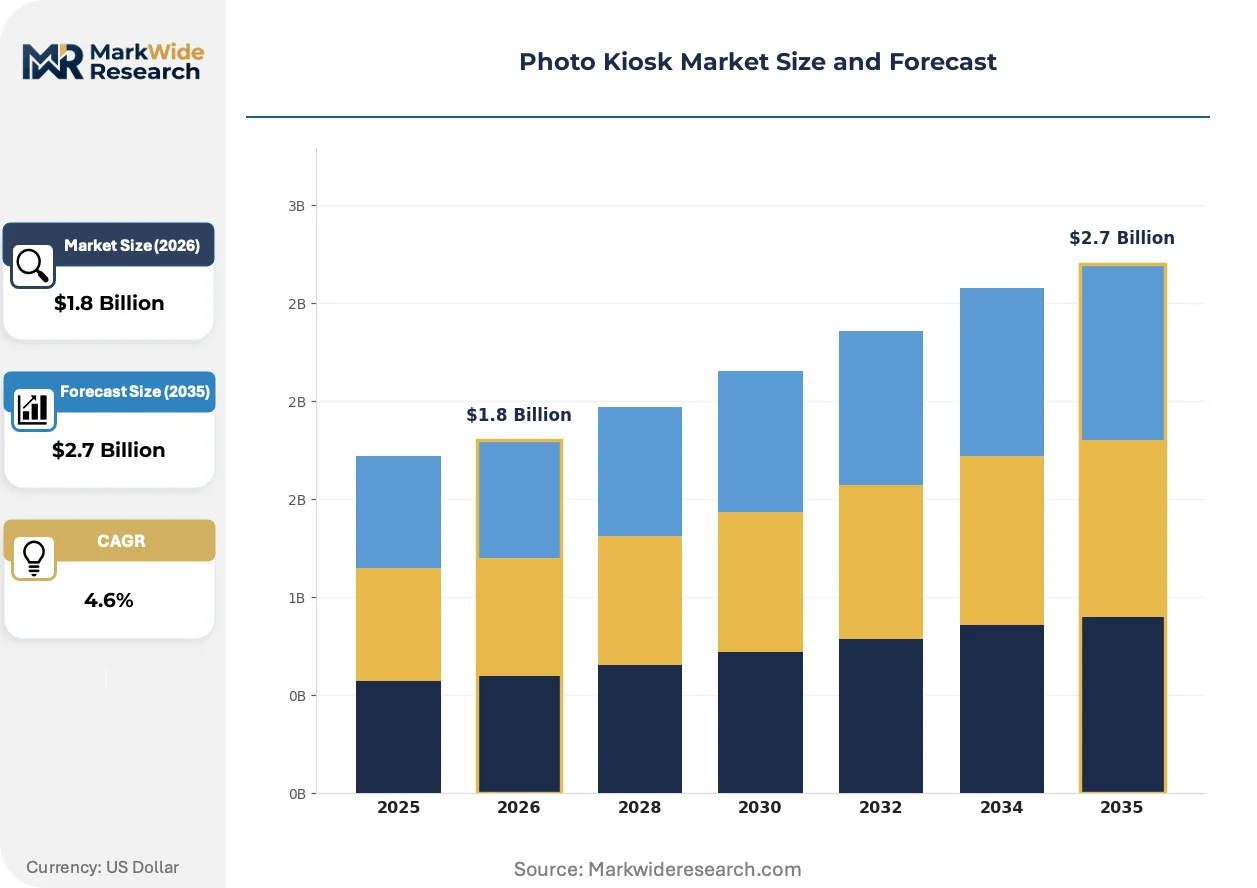
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Digital Kiosks, Mini Kiosks, Interactive Kiosks Technology: Cloud-Based Solutions, Local Storage, Mobile Integration, Touchscreen Interfaces End User: Retail Stores, Event Venues, Shopping Malls, Photo Studios Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Open Air Photo Booth, Photobooth.com, Innovative FOTO, Magic Mirror Photo Booth, Booth By Mail, DNP Imagingcomm America, Simple Booth, Selfie Booth Co., Photo Booth Supply Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Kiosk Market Strategic Shifts
Software-hardware unbundling is redistributing margin capture across the value chain, with recurring revenue models displacing capital-intensive ownership structures in both rental and retail deployments.
Edge computing architectures for real-time image processing are decomposing the traditional dependency on cloud roundtrips, reducing latency for AR filter rendering and enabling offline operation at remote event venues. Wedding planners and rural festival operators adopt these systems fastest where connectivity is unreliable. This shift compresses infrastructure requirements and lowers per-event data costs for independent operators.
EU AI Act transparency obligations for automated image manipulation impose documentation burdens on vendors deploying facial recognition and automated retouching algorithms. Compliance costs concentrate in interactive kiosk segments where gesture tracking and emotion detection trigger classification thresholds. European operators respond by segregating feature sets across regional firmware builds.
Social media sharing unbundling from print fulfillment is fragmenting the traditional transaction bundle, with younger demographics prioritizing instant digital distribution over physical output. Event venues now specify TikTok-optimized aspect ratios and direct-platform upload APIs as standard procurement requirements. This behavioral pivot is most visible in U.S. coastal metropolitan markets where experiential spending concentrates.
Photo Kiosk Market Segmentation
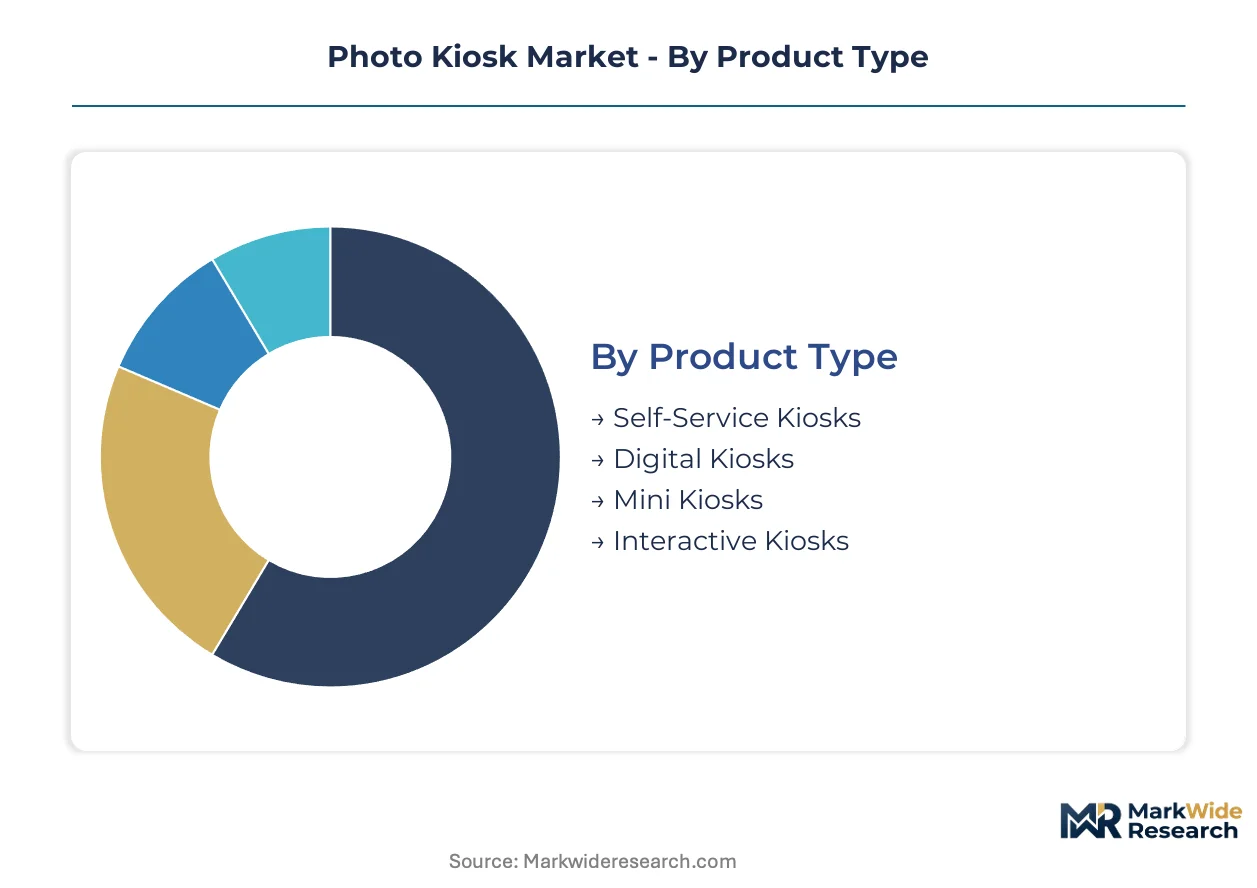
Photo kiosk segmentation reveals divergent margin structures across hardware, software, and service layers. Vendors prioritize segments where recurring revenue or premium positioning offset capital intensity and field service costs.
Product Type:
Margin pools concentrate in attendant-assisted configurations where labor bundling justifies rate premiums over unattended hardware.
- Self-Service Kiosks:Unattended units with integrated payment, capture, and thermal printing modules operate at 300-600 DPI resolution. Demand concentrates in United States retail pharmacies and big-box stores where labor cost reduction drives procurement. Minimal staffing requirements compress total cost of ownership for high-footfall deployments.
- Interactive Kiosks:Gesture-controlled systems with augmented reality filters and green-screen compositing command premium rental rates at corporate activations. Wedding planners in United States coastal metropolitan markets specify these units where experiential budgets absorb higher day-rates for differentiated guest engagement.
- Digital Kiosks:Screen-centric units emphasizing social media upload over physical output serve brand activation budgets.
- Mini Kiosks:Compact footprints reduce freight costs and venue space requirements for independent rental operators.
The dominant share belongs to Self-Service Kiosks, while Interactive Kiosks is closing the gap fastest.
Technology:
Recurring revenue concentration shifts toward subscription-based fleet management and remote software delivery.
- Cloud-Based Solutions:Architectures enabling remote image storage, over-the-air firmware updates, and centralized fleet monitoring reduce on-site maintenance visits. GDPR compliance obligations in Europe constrain data retention architectures, raising compliance costs for vendors with transatlantic deployments.
- Mobile Integration:Direct-platform upload APIs and TikTok-optimized aspect ratios address younger demographics prioritizing instant digital distribution. United States event venues now specify these capabilities as standard procurement requirements where experiential spending concentrates.
- Local Storage:Edge-based architectures enable offline operation at remote venues with unreliable connectivity.
- Touchscreen Interfaces:Capacitive multi-touch panels constitute baseline hardware specification across all product tiers.
Cloud-Based Solutions holds the dominant position, though Mobile Integration is expanding most quickly.
End User:
Application-specific procurement patterns separate volume-driven retail from rate-driven private events.
- Event Venues:Wedding planners and corporate activation coordinators rent attendant-assisted units for single-day or weekend deployments. Tier-2 city markets in India remain undersupplied, offering first-mover positioning for rental operators.
- Retail Stores:Pharmacy chains and convenience stores deploy unattended kiosks as impulse purchase enablers. Smartphone camera substitution reduces print demand among casual consumers at these touchpoints.
- Shopping Malls:Operators prioritize dwell-time extension through experiential installations in high-footfall common areas.
- Photo Studios:Professional photographers integrate kiosks as self-service extensions of traditional portrait services.
Retail Stores maintains dominant share, while Event Venues is climbing the fastest.
Distribution Channel:
Channel economics favor direct relationships where vendor-controlled service contracts capture lifetime value.
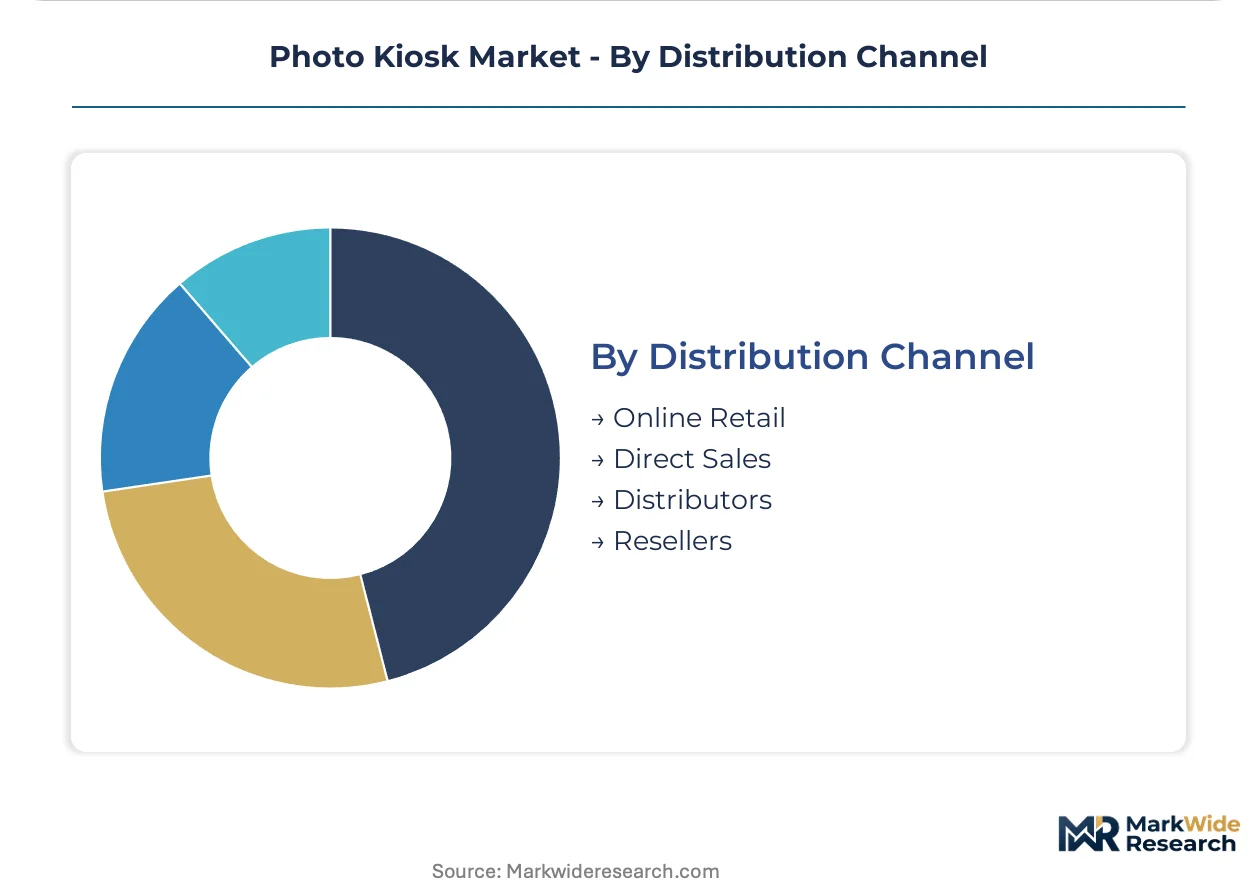
- Direct Sales:Vendor field teams configure hardware-software bundles and attach multi-year service agreements. FCC certification mandates for wireless modules accelerate standardization of connectivity stacks, reducing engineering overhead for domestic manufacturers selling directly.
- Distributors:Regional warehousing and local language support enable fleet deployment across fragmented geographic markets.
- Online Retail:E-commerce platforms serve small independent operators purchasing single units or consumable replenishment.
- Resellers:Value-added resellers bundle kiosk procurement with event production services.
Direct Sales commands dominant share, while Distributors is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific freight corridors that import thermal printing hardware and dye-sublimation consumables into the United States, establishing West Coast logistics as the throughput backbone for North American kiosk deployment.
United States
Mall operators in California and Texas deploy experiential photo installations as dwell-time extenders, while wedding planners in coastal metropolitan markets specify gesture-controlled units for premium events. FCC certification mandates for wireless connectivity modules standardize hardware stacks across domestic manufacturing. The Greater Los Angeles logistics cluster processes inbound consumables from East Asian suppliers for redistribution to rental operators nationwide.
Germany
Retail pharmacy chains in Bavaria and North Rhine-Westphalia maintain unattended kiosk fleets for impulse photo printing, offsetting smartphone substitution through convenience positioning. CE marking requirements under EU machinery and electromagnetic compatibility directives shape product design for export-bound units. The Stuttgart industrial corridor hosts precision manufacturing of thermal transfer components serving both domestic deployment and intra-European supply.
India
Tier-2 city wedding markets in Maharashtra and Gujarat remain undersupplied with attendant-assisted photo kiosk rentals, creating first-mover positioning for independent operators. The PLI scheme for electronics manufacturing attracts component assembly and final integration, reducing import duty exposure for regional fleets. The Mumbai-Pune logistics corridor enables rapid deployment of rental units to emerging private event venues across western India.
United Kingdom
Corporate activation coordinators in London and the Southeast specify interactive kiosks with augmented reality filters for brand experience budgets. GDPR compliance obligations constrain cloud storage architectures and image retention policies, raising compliance costs for vendors with transatlantic operations. The Thames Valley technology cluster develops software platforms for remote fleet management serving European rental operators.
Japan
Retail convenience chains in the Kanto region deploy compact mini kiosks for space-constrained urban locations, prioritizing minimal footprint over feature depth. METI standards for consumer electronics safety govern touchscreen interfaces and thermal printer specifications. The Osaka-Kobe manufacturing base produces high-durability dye-sublimation ribbons for archival-grade output in professional event segments.
Photo Kiosk Market Competitive Environment
Concentration sits with specialized hardware-software bundlers who control rental channel relationships through turnkey service contracts. The vendor base separates into three strategic tiers: manufacturing-scale printing hardware suppliers, streamlined software-centric operators, and modular architecture specialists serving independent rental fleets. Dominant competitive moves include geographic expansion into undersupplied private event markets and technology licensing arrangements that reduce customer acquisition costs.
Within the manufacturing-scale tier, DNP Imagingcomm America exemplifies integrated production of professional-grade thermal transfer systems. Simple Booth and Photo Booth Supply Co. occupy distinct positions in the software-hardware bundle and modular architecture segments respectively, representing alternative paths to rental operator capture. These three anchors illustrate the structural divergence between capital-intensive hardware ownership and asset-light service models.
| Leading Market Players |
|---|
| Open Air Photo Booth |
| Photobooth.com |
| Innovative FOTO |
| Magic Mirror Photo Booth |
| Booth By Mail |
| DNP Imagingcomm America |
| Simple Booth |
| Selfie Booth Co. |
| Photo Booth Supply Co. |
| Others |
Value Chain & Pricing Dynamics
FCC certification mandates for wireless connectivity modules gate both hardware qualification and rate differentiation in United States deployments, compressing margins for uncertified imports while enabling domestic manufacturers to command service-contract premiums. Wedding planners and corporate activation coordinators absorb higher day-rates for attendant-assisted configurations where labor bundling justifies experiential positioning, while retail pharmacy chains drive hard bargains on unattended self-service units.
Pricing Analysis
Volume-discount tiering structures dominate procurement between independent rental operators and fleet-scale event production companies. Three-tier pricing stratifies across premium interactive kiosks with AR filters, standard attendant-assisted bundles, and economy self-service hardware. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because smartphone substitution erodes impulse print demand. Retail pharmacy chains exhibit highest price sensitivity; wedding planners in coastal metropolitan markets demonstrate lowest sensitivity.
Supply Chain Analysis
Inventory lead-times for dye-sublimation ribbons and thermal print heads stretch 8-12 weeks from order placement, constraining rental operator fleet expansion timing. Manufacturing concentrates in Japan, South Korea, and China for consumables, while final integration clusters in United States and Indian PLI-subsidized facilities. Raw material dependencies include specialty coated paper, thermal transfer ribbons, and precision mechatronics components. Single-source vulnerability concentrates in East Asian consumables production. Distribution runs through direct vendor relationships for fleet operators and regional distributors for independent rentals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs tether rental operators to incumbent hardware-software bundles through multi-year service contracts and consumables lock-in.
For Market Incumbents: Consolidate channel control by acquiring regional distributors in undersupplied Tier-2 Indian wedding markets, and deepen backward integration into consumables production to offset East Asian supply concentration. Smartphone camera substitution threatens impulse retail print demand; counter with certification investment in FCC-compliant wireless stacks that gate competitor hardware qualification.
For New Entrants and Emerging Players: Differentiate on edge-computing architectures that enable offline operation at remote rural festivals where connectivity failures disable cloud-dependent competitors. Target attendant-assisted rentals in Maharashtra and Gujarat wedding corridors where incumbent coverage remains thin. Pursue white-label software licensing to established event production houses as capital-light go-to-market path.
For Investors and Strategic Acquirers: EU AI Act transparency obligations for automated image manipulation reshape the acquisition landscape, concentrating compliance costs on interactive kiosk segments and creating distressed opportunities. Five-to-ten year viability favors modular architecture specialists with India manufacturing footprints over hardware-heavy dye-sublimation manufacturers. Monitor PLI scheme electronics manufacturing uptake as inflection signal for regional supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumables | Captive supply of dye-sublimation ribbons insulates margin from East Asian freight volatility. |
| Edge Computing Architecture Deployment | Offline AR rendering capability unlocks remote wedding venue contracts beyond cloud-dependent competitors. |
| PLI Scheme Manufacturing Relocation | Indian production-linked incentives reduce import duty exposure for regional rental fleet expansion. |
| Direct-to-Venue Software Licensing | White-label platform partnerships with wedding planners compress customer acquisition costs. |
| GDPR-Compliant Cloud Segregation | Regional firmware builds satisfy EU image retention rules without fragmenting global codebase. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wedding planners, corporate activation coordinators, retail pharmacy procurement managers, and independent rental fleet operators. Secondary validation drew from FCC equipment authorization databases, EU CE marking registries, Indian PLI scheme beneficiary disclosures, and customs import records for thermal printing hardware. Bottom-up unit deployment estimates triangulated against top-down experiential spending flows across retail and private event verticals.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented projections across product type, technology architecture, end-user application, and distribution channel. CAGRs derived from logistic diffusion curves fitted to hardware replacement cycles and software subscription renewal patterns. Industry-specific inputs included wedding industry expenditure surveys, mall operator experiential budget allocations, and smartphone camera resolution advancement curves.
The analysis sits within stated boundaries; outcomes outside sustained experiential spending growth or stable East Asian consumables supply would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Middle East and Africa Image Sensors Market
Imaging
EUV Mask Inspection System Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Global Ingaas Camera Market
Imaging
Computer Aided Detection Market
Imaging
Contact Image Sensor Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Global Broadcast Cameras Market
Imaging
Low-Light Imaging Market
Imaging
Europe Image Sensors Market
Imaging
Machine Vision Market
Imaging
Digital X-Ray Technology Market
Imaging
Small CCTV Camera Market
Imaging
Global Digital Photography Market
Imaging
Europe Machine Vision Systems Market
Imaging
North America IP Camera Market